
 Global Feminine Protection Market | 2026-2036
Global Feminine Protection Market Size, Share, and Industry Trends Forecast 2026-2036
Global Feminine Protection Market Analysis
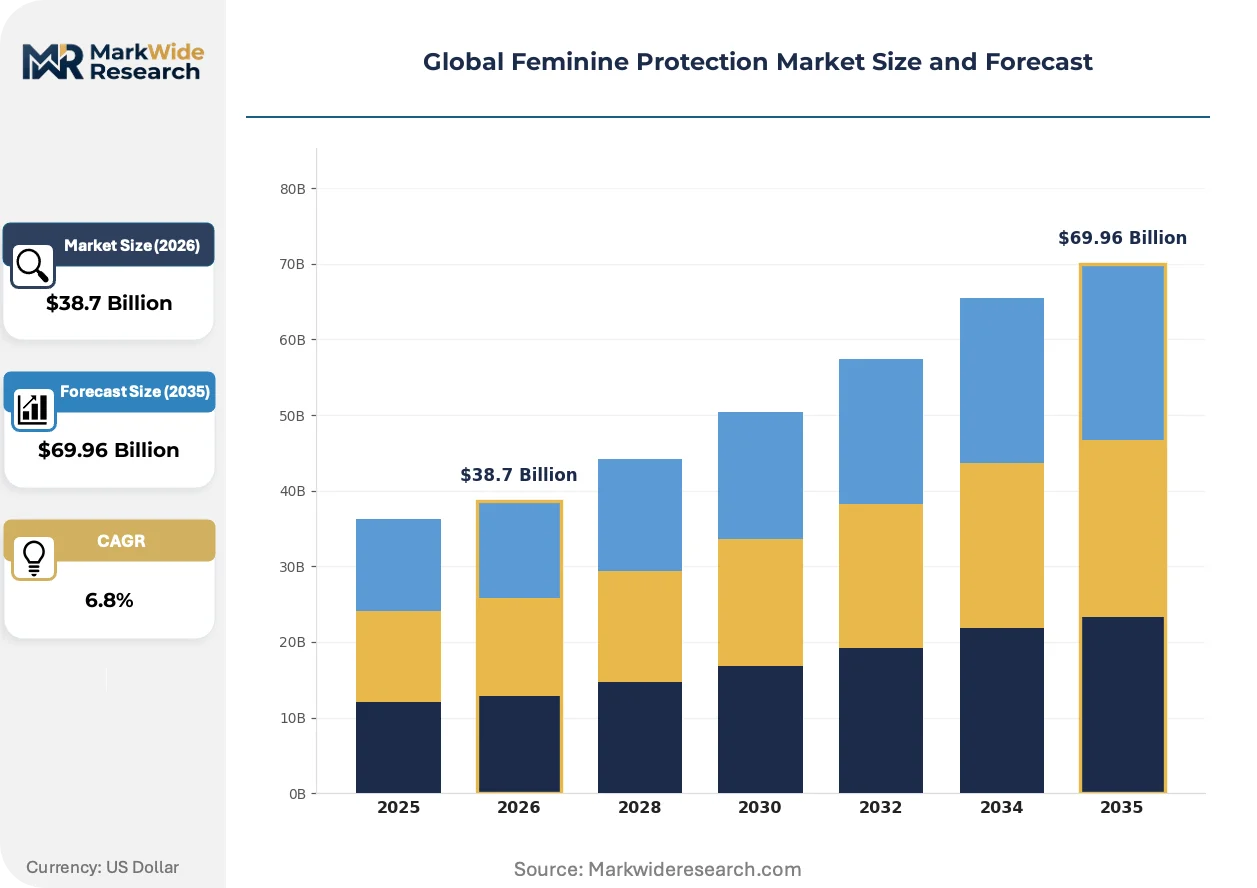
Organic cotton and dermatologically certified tiers is redrawing competitive benchmarks across the Global Feminine Protection Market. Procter & Gamble leverages its North American manufacturing scale to control premium shelf positioning in mass retail. Essity AB anchors its European presence through sustained R&D intensity in sustainable absorbent materials. Hengan International Group dominates Greater China distribution through deep pharmacy and convenience store networks.
Feminine protection encompasses absorbent hygiene products engineered with superabsorbent polymer cores, nonwoven topsheets, and breathable backsheet films designed to manage menstrual flow with leak prevention and skin-health compliance. Sanitary pads retain the largest revenue share due to universal familiarity and lower price barriers across emerging economies, though margin pools are shifting toward menstrual cups where reuse economics attract sustainability-oriented buyers. Online retail channels are expanding fastest among distribution segments, particularly for subscription-based tampon and panty liner deliveries that bypass traditional retail markup structures.
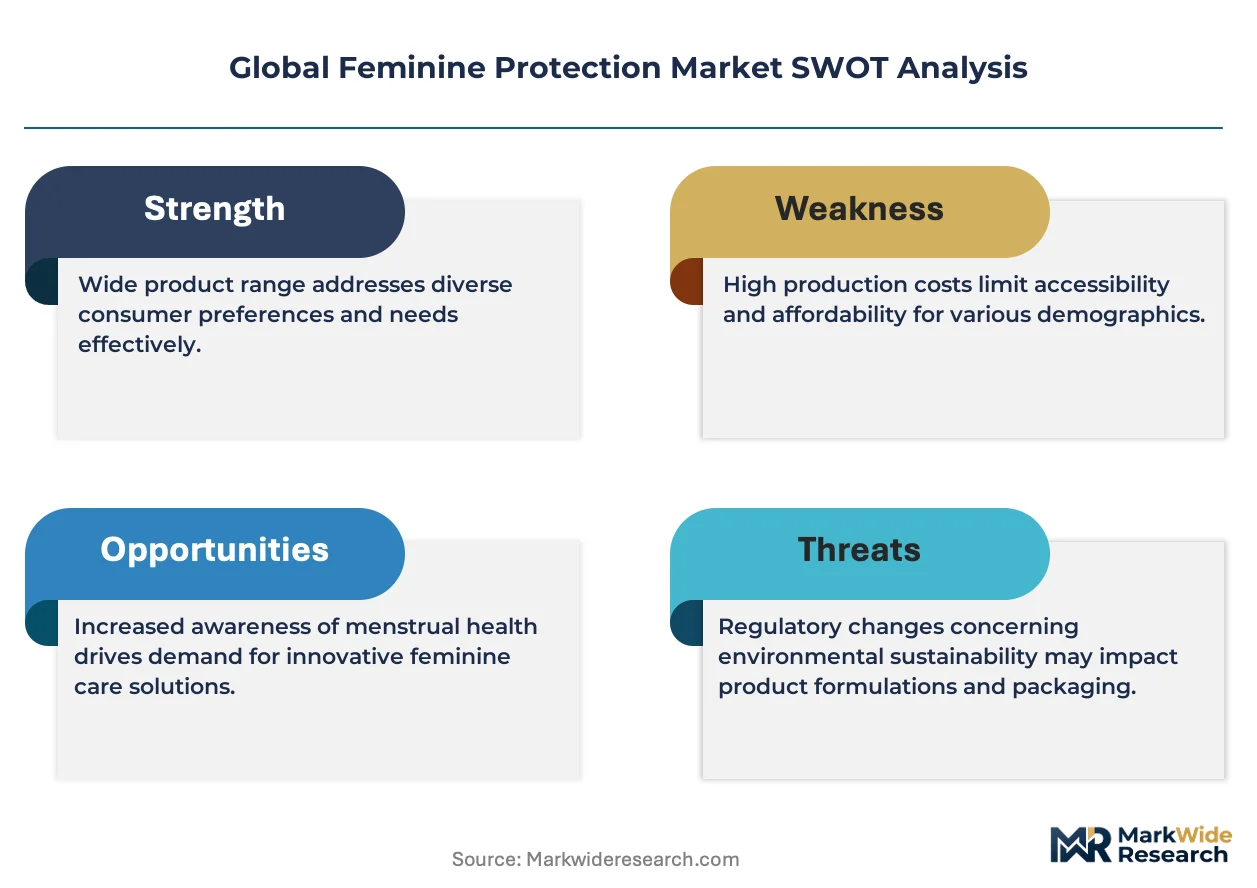
FDA biocompatibility standards and EPA chemical exposure thresholds govern product composition in the United States, while REACH substance restrictions and the EU Green Deal's packaging mandates reshape material specifications across Europe. India's BIS quality certification requirements and PLI scheme incentives for domestic manufacturing are simultaneously elevating product standards and local production capacity. Stakeholders must monitor how diverging biodegradability timelines across FDA, EMA, and BIS frameworks will fragment formulation strategies and complicate unified global product platforms.
Market Dynamics
The EU Green Deal's single-use plastics directive is forcing material transitions across absorbent hygiene supply chains, while adolescent demand expansion through school distribution programs is redrawing end-user targeting strategies. Superabsorbent polymer sourcing concentration and biodegradable substrate certification timelines now determine competitive viability more than manufacturing scale alone.
Growth Catalysts
- EU Green Deal Packaging Mandates:REACH substance restrictions and biodegradability timelines are accelerating certified organic cotton adoption across European formulations. Manufacturers reformulate topsheet compositions to preempt compliance deadlines.
- India PLI Scheme Incentives:Domestic manufacturing capacity expansion under production-linked incentive frameworks is reducing import dependency for superabsorbent polymers. Rural penetration campaigns amplify addressable demand.
- Menstrual Cup Reuse Economics:Sustainability-oriented buyers in urban clusters are pivoting toward medical-grade silicone alternatives. Subscription retention rates exceed disposable product cohorts.
Market Restraints
- Superabsorbent Polymer Supply Concentration:Petrochemical feedstock volatility and concentrated Asian supplier bases expose margin structures to input cost spikes. Inventory hedging consumes working capital.
- FDA-EMA-BIS Divergence:Fragmented biodegradability certification timelines across United States, European, and Indian regulatory frameworks complicate unified global product platforms. Reformulation costs multiply.
- Reusable Product Substitution:Menstrual cups and period underwear with multi-year lifespans are compressing replacement frequency for traditional disposables. Average revenue per user declines.
Strategic Opportunities
- Rural India Penetration:Untapped demand in tier-3 and tier-4 population centers offers volume expansion beyond saturated urban markets. Microfinance-linked distribution partnerships reduce price barriers.
- Subscription Direct-to-Consumer Channels:Bypassing traditional retail markup structures through automated tampon and liner delivery models captures margin pools. Customer lifetime value metrics improve.
- Pharmacy Network Integration:Dermatological certification tiers positioned through pharmacy channels in Greater China and Southeast Asia command premium positioning. Pharmacist recommendation influence exceeds mass retail.
Industry Challenges
- BIS Certification Timeline Compression:India's quality certification requirements for imported absorbent materials extend product launch windows. Testing backlog creates competitive lag.
- Legacy Fluff Pulp Integration:Transitioning manufacturing lines from wood pulp-based cores to biodegradable alternatives requires capital-intensive equipment retooling. Downtime costs accumulate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Feminine Protection Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sanitary Pads, Tampons, Menstrual Cups, Panty Liners Distribution Channel: Supermarkets, Online Retail, Pharmacies, Convenience Stores End User: Women, Adolescents, Healthcare Providers, Institutions Usage Frequency: Daily Use, Occasional Use, Seasonal Use, Emergency Use |
| Companies Covered | Procter & Gamble, Kimberly-Clark Corporation, Unicharm Corporation, Essity AB, Johnson & Johnson, Ontex Group NV, Edgewell Personal Care, Unilever Plc, Hengan International Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Feminine Protection Market Emerging Trajectories
Material science advances and channel disintermediation are restructuring how feminine protection products reach end users. Regulatory pressure on petrochemical inputs intersects with buyer preference shifts toward transparency and sustainability credentials.
Plant-based absorbent cores derived from agricultural waste streams are displacing petroleum-derived superabsorbent polymers in premium tier formulations. European manufacturers under EU Green Deal timelines are accelerating adoption, while FDA biocompatibility review pathways lag EMA equivalence determinations. This displacement is compressing conventional polymer supplier margins and fragmenting raw material sourcing strategies.
REACH substance restrictions and the EU Green Deal's packaging waste directive are mandating compostable backsheet films and reduced plastic content across European distribution. Manufacturers serving Germany, France, and Netherlands markets must reformulate or face market exclusion. Indian exporters targeting European buyers are retrofitting production lines to meet divergent BIS and ECHA compliance requirements simultaneously.
Subscription-based replenishment models are capturing urban professional segments who prioritize convenience and privacy over in-store selection. Direct-to-consumer channels in United States and United Kingdom markets are disintermediating pharmacy and mass retail intermediaries. This behavioral pivot concentrates customer data ownership with manufacturers and reduces price comparison transparency.
Global Feminine Protection Market Segmentation
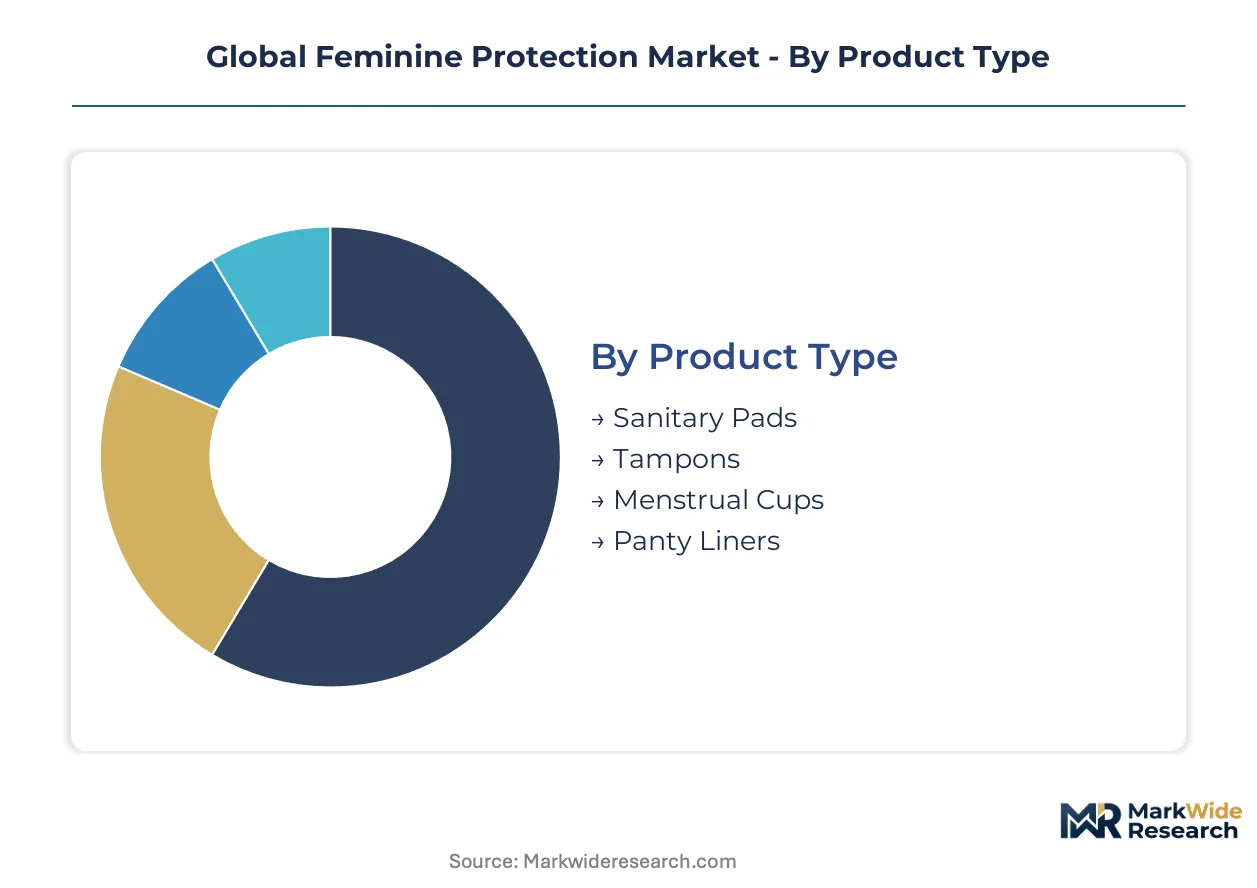
Segmentation in feminine protection reveals how regulatory divergence, channel economics, and user life-cycle stages fragment manufacturing priorities. Formulation choices must simultaneously satisfy FDA biocompatibility standards in the United States, REACH substance restrictions in Europe, and BIS certification timelines in India.
Product Type:
FDA biocompatibility standards in the United States, REACH substance restrictions across Europe, and BIS quality certification in India each impose distinct material specifications that reshape product development roadmaps.
- Sanitary Pads:Multi-layer construction combines nonwoven topsheets, superabsorbent polymer cores, and breathable backsheet films for leak prevention. Demand concentrates in rural India where penetration campaigns and PLI scheme incentives expand domestic manufacturing capacity; price barriers remain lower than alternative formats.
- Menstrual Cups:Medical-grade silicone or thermoplastic elastomer designs offer multi-year reuse cycles. Adoption accelerates fastest among sustainability-oriented urban professionals in Germany, France, and Netherlands where EU Green Deal packaging mandates compress demand for single-use alternatives; subscription retention rates exceed disposable cohorts.
- Tampons:Rayon or organic cotton core designs with plastic or cardboard applicators. FDA biocompatibility review pathways govern United States distribution.
- Panty Liners:Thin absorbent layers for light daily discharge management. REACH substance restrictions reshape European topsheet compositions.
Established volume favors sanitary pads; emerging adoption favors menstrual cups.
Distribution Channel:
Channel economics fragment margin capture between legacy retail intermediaries and direct-to-consumer platforms that bypass traditional markup structures.
- Online Retail:Subscription-based tampon and panty liner deliveries concentrate customer data ownership with manufacturers. Demand expands fastest among United Kingdom and United States urban professionals who prioritize convenience and privacy; automated replenishment models improve customer lifetime value metrics.
- Supermarkets:Mass retail shelf positioning requires trade spend negotiation and promotional calendar coordination. Volume concentrates in North American and European suburban markets.
- Pharmacies:Dermatological certification tiers command premium positioning through pharmacist recommendation influence. Networks in Greater China and Southeast Asia outperform mass retail on conversion rates.
- Convenience Stores:Emergency purchase occasions and impulse replenishment drive placement density in urban Japan and South Korea.
Legacy volume anchors supermarkets; margin expansion concentrates in online retail.
End User:
User life-cycle stages from menarche through menopause impose distinct performance requirements and purchasing authority patterns.
- Adolescents:School-based distribution programs in India, Kenya, and Bangladesh expand first-product trial and brand loyalty formation. Demand climbs the fastest as government procurement scales and stigma reduction campaigns normalize menstrual health education.
- Women:Prime reproductive-age consumers drive premium tier adoption of organic cotton and dermatologically certified formulations. Concentration in European urban clusters.
- Healthcare Providers:Clinical settings and post-surgical recovery applications require sterile, hypoallergenic specifications. FDA and EMA medical device classifications apply.
- Institutions:Corporate wellness programs, military procurement, and prison systems generate bulk contract demand. Price sensitivity exceeds individual consumer markets.
Procurement scale favors institutions; lifetime value potential favors adolescents.
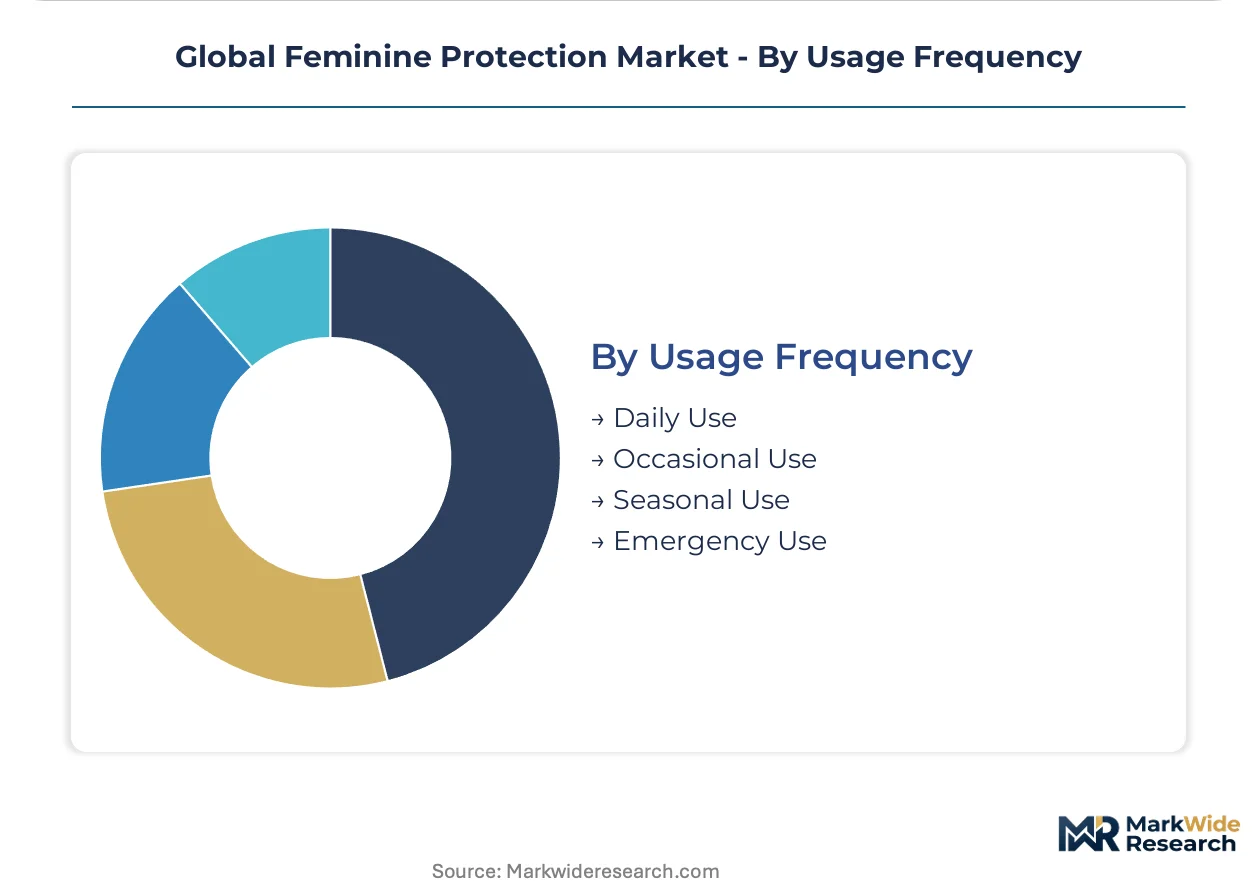
Usage Frequency:
Purchase cadence and inventory planning requirements vary sharply between predictable daily routines and contingency-driven emergency acquisition.
- Daily Use:Panty liner and light-flow pad consumption creates recurring replenishment patterns. Subscription models capture United States and United Kingdom professional segments.
- Occasional Use:Backup protection for menstrual cup or tampon users, or light-flow days. Pharmacy channel preference in France and Germany.
- Seasonal Use:Athletic event preparation, travel, or climate-driven humidity management. Concentration in Southeast Asian tropical urban centers.
- Emergency Use:Vending machine, convenience store, and workplace dispenser procurement. Price inelasticity supports premium unit economics in Japan and South Korea transit hubs.
Predictable revenue streams favor daily use; margin per transaction favors emergency use.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports feminine protection products to European Union markets under REACH-compliant formulations, while Chinese manufacturers supply superabsorbent polymer substrates to Southeast Asian converters.
United States
FDA biocompatibility standards govern tampon and pad compositions, with EPA chemical exposure thresholds limiting volatile organic compound emissions from backsheet films. Manufacturing clusters in Cincinnati and Boston metro areas concentrate absorbent core production for North American distribution.
Germany
EMA equivalence determinations for organic cotton certifications accelerate faster than FDA pathways, driving Berlin and Hamburg-based formulators toward biodegradable substrate adoption. EU Green Deal packaging mandates force compostable backsheet transitions by 2025 deadlines.
India
BIS quality certification requirements and PLI scheme incentives expand domestic manufacturing capacity for superabsorbent polymers. Rural penetration campaigns in Maharashtra and Gujarat amplify addressable demand beyond saturated Mumbai and Delhi urban markets.
China
Dual carbon goals and MIIT industrial standards pressure manufacturers toward plant-based absorbent cores. Manufacturing gravity concentrates in Yangtze River Delta clusters where Hengan International Group maintains pharmacy and convenience store distribution networks.
Japan
METI energy efficiency standards and PMDA medical device classifications apply to menstrual cup formulations. Tokyo and Osaka metro areas drive premium-tier demand for dermatologically certified panty liners through pharmacy channel preference.
Global Feminine Protection Market Vendor Landscape
Listed leaders compete with private specialists across manufacturing scale and channel access dimensions. Consolidation concentrates among North American and European public companies controlling mass retail shelf positioning, while fragmentation persists among Asia-Pacific private manufacturers serving pharmacy and convenience networks. Three archetypes dominate: multinational CPG conglomerates with R&D intensity, regional specialists with deep distribution integration, and private-label converters with cost-driven flexibility. Competitive moves center on sustainable material certification races and direct-to-consumer channel bypass strategies.
Within the multinational CPG tier, Procter & Gamble and Kimberly-Clark Corporation exemplify scale-driven manufacturing archetypes with North American production bases. Essity AB occupies a position representing European sustainable materials specialization, while Hengan International Group anchors Greater China distribution depth. Unicharm Corporation and Ontex Group NV sit within regional specialist archetypes serving pharmacy-dominant channels in Japan and Belgium respectively. Johnson & Johnson and Edgewell Personal Care represent diversified personal care portfolios where feminine protection serves as one vertical among broader hygiene offerings.
| Leading Market Players |
|---|
| Procter & Gamble |
| Kimberly-Clark Corporation |
| Unicharm Corporation |
| Essity AB |
| Johnson & Johnson |
| Ontex Group NV |
| Edgewell Personal Care |
| Unilever Plc |
| Hengan International Group |
| Others |
Supply Flow & Price Mechanics
Plant-based absorbent core substitution for petroleum-derived superabsorbent polymers simultaneously redraws raw material sourcing geography toward agricultural processing clusters and compresses legacy polymer supplier pricing power across European and North American markets. This displacement forces manufacturers to rebuild supplier relationships around cellulose pulp and bio-based hydrogel networks rather than concentrated petrochemical feedstock contracts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates medical-grade silicone menstrual cups from organic cotton disposables and conventional rayon-based pads. Certification grade under EU Green Deal timelines and FDA biocompatibility pathways drives price differentiation between REACH-compliant European formulations and conventional Asian exports. Cost compression in economy-tier disposables is intensifying because Indian PLI scheme incentives expand domestic manufacturing capacity and reduce import dependency. Rural adolescents in tier-3 Indian markets exhibit highest price sensitivity; urban sustainability-oriented professionals in Germany and Netherlands show lowest sensitivity for certified organic tiers.
Supply Chain Analysis
Strait of Malacca transit underwrites superabsorbent polymer feedstock flows from South Korean and Japanese petrochemical complexes toward Southeast Asian converters and Indian manufacturers. Raw material dependencies center on fluff pulp from Scandinavian forestry operations, medical-grade silicone from German and Chinese specialty chemical producers, and organic cotton from Indian and Turkish agricultural cooperatives. Single-source vulnerability concentrates in superabsorbent polymer supply where three Asian suppliers control majority capacity. Distribution runs through pharmacy networks in Greater China and Japan, mass retail in North America, and direct-to-consumer subscription platforms in United Kingdom and United States urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of certified biodegradable substrate manufacturing expertise and REACH-compliant formulation capabilities constrains how quickly manufacturers can reposition toward EU Green Deal compliance deadlines without sacrificing margin structures.
For Market Incumbents: Shield core revenue streams by accelerating backward integration into organic cotton farming cooperatives in India and Turkey to secure certified fiber supply ahead of competitor lock-up. Fortify pharmacy channel control in Greater China through exclusive dermatological certification tiers that emerging players cannot replicate without multi-year BIS and NMPA approval timelines. For New Entrants and Emerging Players: Anchor in rural India tier-3 and tier-4 population centers where government school distribution programs create first-product trial opportunities without competing against entrenched urban shelf presence. Pursue microfinance-linked distribution partnerships that reduce price barriers below multinational economy-tier positioning while building brand loyalty among adolescent cohorts entering reproductive age. For Investors and Strategic Acquirers: The market sits at a material-transition phase that favors manufacturers with captive biodegradable substrate supply and established REACH certification pathways over scale-dependent incumbents tethered to legacy petrochemical inputs. Long-term viability across the next decade hinges on acquisition targets possessing integrated organic cotton processing or medical-grade silicone molding capabilities rather than pure brand equity. Monitor BIS certification backlog resolution as the inflection signal indicating when Indian manufacturing capacity expansion accelerates toward export competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Sustainability Repositioning | REACH-compliant biodegradable substrate adoption preempts EU Green Deal exclusion risks in Germany and France. |
| Direct-to-Consumer Launch | Subscription tampon deliveries bypass mass retail markup structures and concentrate customer data ownership with manufacturers. |
| Backward Integration | In-house organic cotton processing secures certified fiber supply ahead of competitor lock-up in Turkish and Indian cooperatives. |
| Distribution Channel Expansion | Pharmacy network penetration in Greater China leverages pharmacist recommendation influence exceeding mass retail conversion rates. |
| Premium Tier Introduction | Dermatologically certified panty liners through Japanese pharmacy channels command price premiums under PMDA medical device classifications. |
Methodological Framework
Cross-validation between primary interviews with supply chain managers at absorbent hygiene manufacturers and secondary customs trade data anchors the qualitative findings on raw material flow concentration. Conversations with procurement leads at European retailers, regulatory affairs directors navigating REACH substance restrictions, and brand managers at direct-to-consumer platforms informed formulation and channel dynamics. Bottom-up triangulation against top-down trade flow analysis from Indian DGFT export records and ECHA pre-registration databases validated regional supply estimates.
Sensitivity analysis across superabsorbent polymer price volatility scenarios and BIS certification timeline compressions shapes the forecast framework. Segmentation dimensions modeled include product format, distribution channel, end-user life-cycle stage, and usage frequency patterns across the projection horizon. CAGRs derive from elasticity-adjusted demand curves incorporating adolescent population growth, rural penetration campaign scaling, and reusable product substitution rates.
Material uncertainties — regulatory divergence between FDA, EMA, and BIS biodegradability timelines, petrochemical feedstock price spikes, and menstrual cup adoption acceleration — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as EU Green Deal packaging mandate enforcement dates and Indian PLI scheme disbursement schedules evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Safety Products
India Pant Type Adult Diaper Market
Baby Safety Products
BRICS Disposable Hygiene Products Market
Baby Safety Products
Baby Safety Seats Market
Baby Safety Products
Forward Facing Type Child Safety Seats Market
Baby Safety Products
Booster Car Seats Market
Baby Safety Products
Baby Safety Products Market
Baby Safety Products
Japan Adult Diaper Market
Baby Safety Products
Biodegradable Sanitary Napkins Market
Baby Safety Products
Global Baby Cleaning Products Market
Baby Safety Products
United States Away from Home Tissue and Hygiene Market
Baby Safety Products
North America Baby Monitors Market
Baby Safety Products
Reusable/Washable Hygiene Products Market
Baby Safety Products
Reusable Sanitary Pads Market
Baby Safety Products
Panty Liner Market
Baby Safety Products
Organic Sanitary Napkin Market
Baby Safety Products
North America Adult Diaper Market