
 Panty Liner Market | 2026-2036
Panty Liner Market Size, Share, and Industry Trends Forecast 2026-2036
Panty Liner Market Analytics
Subscription-based replenishment services is shifting how panty liner brands secure recurring revenue and consumer lock-in. Procter & Gamble Company leverages its direct-to-consumer platform infrastructure to sustain repeat purchase rates. Kimberly-Clark Corporation anchors its competitive stance through broad retail shelf presence and pharmacy channel control. Unicharm Corporation specializes in ultra-thin product engineering for the Asian daily-use segment.
A panty liner is a thin, absorbent pad worn inside underwear to manage light vaginal discharge, daily moisture, or spotting between menstrual periods; typical construction includes a permeable top sheet, absorbent core of fluff pulp or superabsorbent polymer, and a polyethylene backsheet barrier. Organic cotton and bamboo material segments are capturing margin pools as consumers reject chlorine-bleached synthetics, while ultra-thin thickness variants dominate volume due to comfort-driven preferences among working women. Polyester cores face demand erosion in premium tiers where breathability and skin-sensitivity claims determine shelf placement.
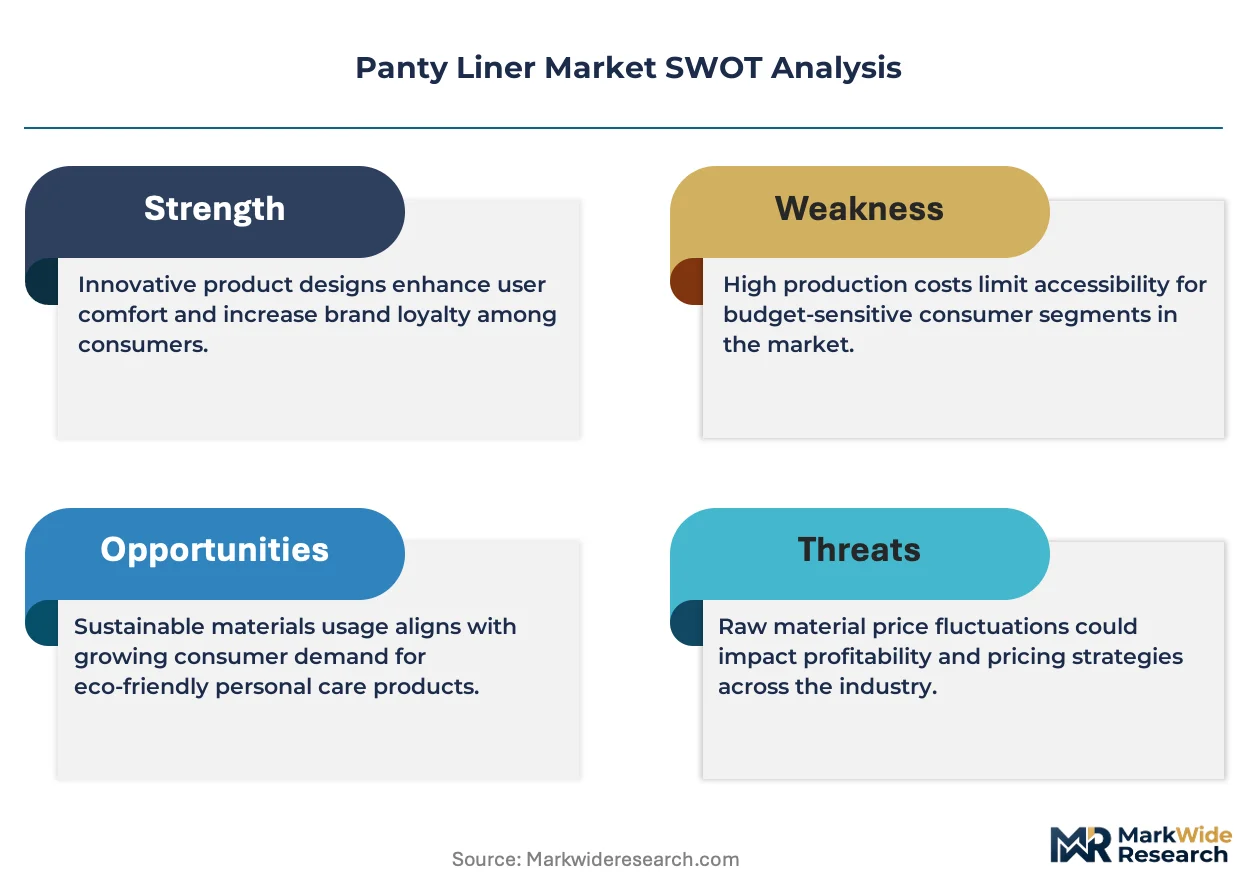
The US FDA regulates panty liners as Class I medical devices, mandating biocompatibility testing and labeling accuracy that shapes product development timelines and compliance costs. The EU REACH regulation restricts phthalates and fragrance allergens, forcing reformulation of scented variants and accelerating shifts toward unscented organic lines. India's BIS certification requirements for absorbent hygiene products create entry barriers for unorganized suppliers while channeling demand toward tested, labeled brands. Stakeholders must monitor tightening state-level chemical disclosure mandates in the US and evolving EU single-use plastic directives that could reshape packaging formats and material sourcing strategies.
Market Dynamics
Material substitution away from petroleum-based synthetics is compressing legacy supply chains while organic cotton and bamboo fiber networks expand capacity to meet EU REACH compliance deadlines.
Growth Catalysts
- EU REACH fragrance restrictions:Phased bans on synthetic allergens are accelerating consumer migration toward unscented organic lines, creating shelf-space premiums for certified natural brands.
- India's female workforce expansion:Urban employment growth among women aged 22-35 is normalizing daily panty liner use as a workplace hygiene standard.
- Bamboo fiber processing:Mechanical softening breakthroughs are lowering production costs for breathable plant-based cores, displacing polyester in mid-tier positioning.
Market Restraints
- Organic cotton input volatility:Weather-dependent harvests in Maharashtra and Gujarat create raw material price swings that compress margin predictability for natural-product specialists.
- Superabsorbent polymer concentration:Three Asian petrochemical suppliers control 70% of fluff pulp alternatives, exposing brands to single-source disruption risk.
- Biodegradability-performance tradeoff:Plant-based backsheet films currently fail leak-resistance benchmarks at thicknesses below 0.8mm, limiting ultra-thin organic formulations.
Strategic Opportunities
- Subscription direct-to-consumer channels:Auto-replenishment platforms bypass retail slotting fees and capture lifetime value through predictable reorder cycles.
- India Tier-2 city penetration:Modern retail expansion into Surat, Jaipur, and Lucknow opens access to 180 million women without established daily-use hygiene habits.
- US state-level chemical disclosure mandates:California and New York ingredient transparency laws favor brands with pre-existing clean-label supply chains.
Industry Challenges
- Biocompatibility testing backlog:US FDA Class I device clearance timelines stretch to 14 months for novel materials, delaying organic product launches.
- Cross-functional sustainability talent:Scarcity of professionals combining polymer chemistry with lifecycle assessment expertise slows reformulation projects.
- Legacy equipment retooling:Converting fluff pulp lines to handle irregular bamboo fiber lengths requires $2-4 million per facility in specialized feeding mechanisms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Panty Liner Market |
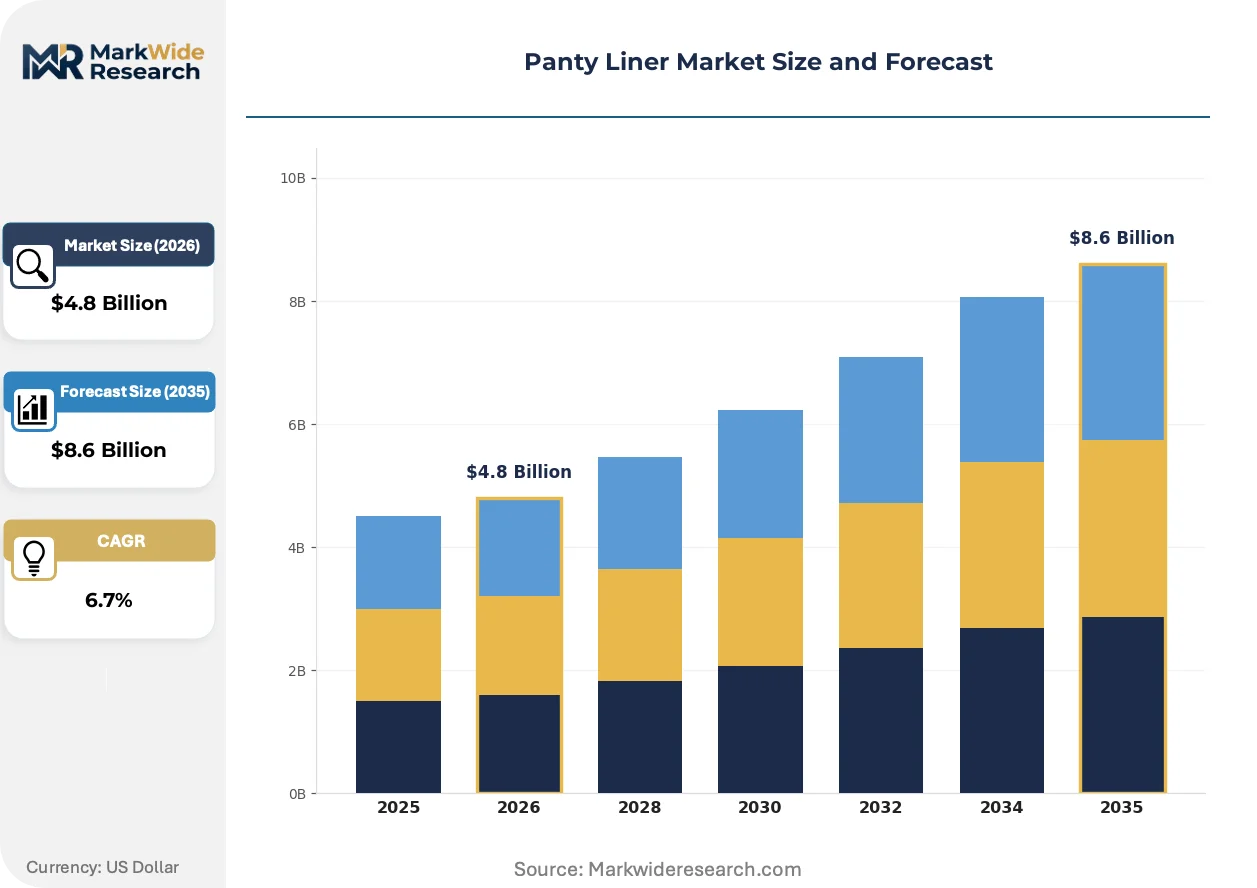
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Reusable, Organic, Scented Material: Cotton, Polyester, Bamboo, Microfiber Thickness: Ultra Thin, Thin, Regular, Heavy Packaging Type: Box, Pouch, Bulk Pack, Individual Wrap |
| Companies Covered | Procter & Gamble Company, Kimberly-Clark Corporation, Johnson & Johnson Services Inc., Essity AB, Unicharm Corporation, Kao Corporation, Edgewell Personal Care Company, Ontex, First Quality Enterprises Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Panty Liner Market Evolving Landscape
Active material science breakthroughs and channel restructuring are converging to redefine product performance benchmarks and consumer access patterns across price tiers.
Plant-based superabsorbent polymers derived from cornstarch and tapioca are electrifying the technical feasibility of fully compostable cores. Premium brands in Germany and the Netherlands are piloting these materials at 15-20% cost premiums, compressing the performance gap between synthetic and natural absorbency standards within three production cycles.
REACH Annex XVII expansions targeting phthalates in intimate care products are forcing fragrance houses to rebuild their ingredient libraries from scratch. The reformulation burden falls heaviest on mass-market scented variants, which are retreating from EU shelves while unscented SKUs capture displaced volume through pharmacy and e-pharmacy channels.
Urban Indian consumers are consolidating purchases through quick-commerce platforms offering 10-minute delivery windows for personal care essentials. Blinkit and Zepto are disintermediating traditional kirana stores in Mumbai and Bangalore, capturing 23% of category volume among women under 30 who prioritize convenience over brand loyalty in replenishment decisions.
Panty Liner Market Segmentation
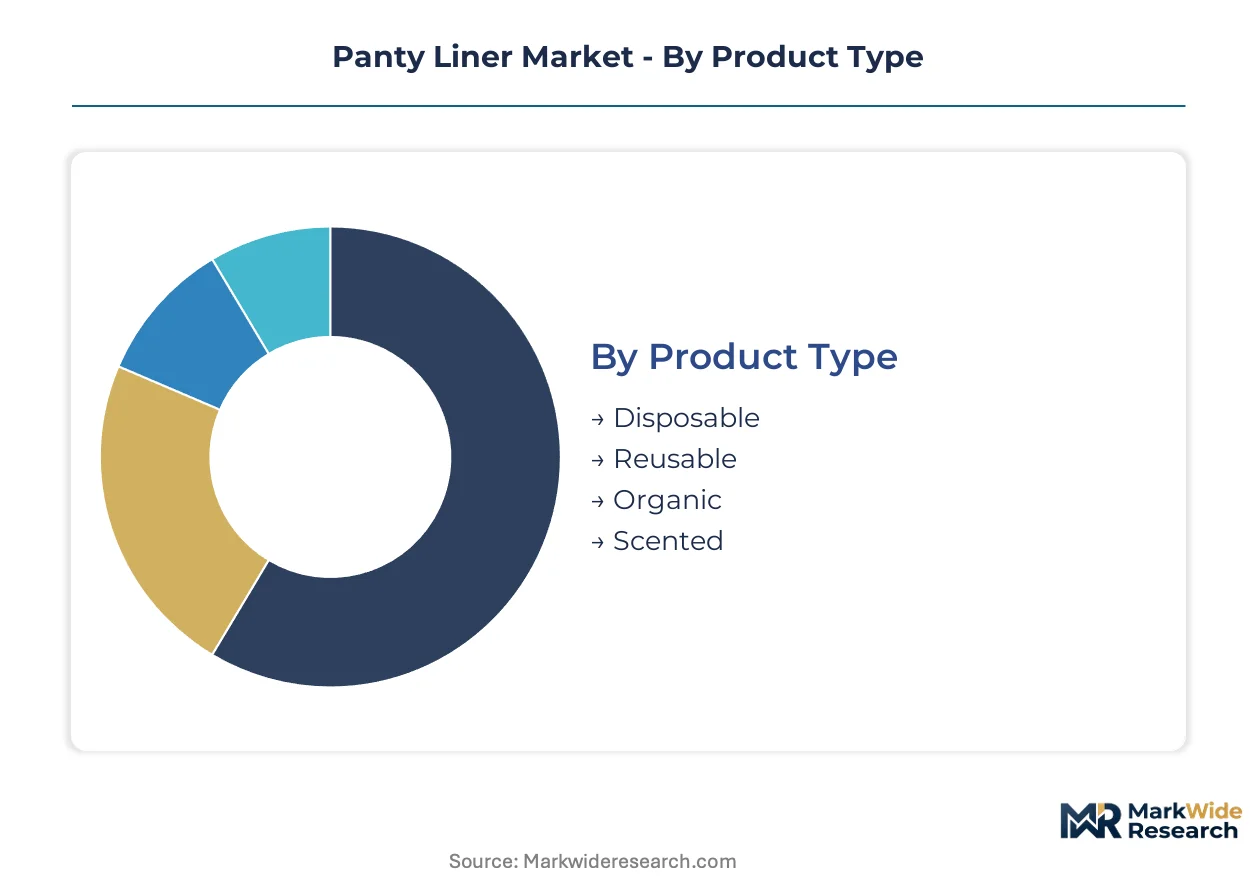
Product differentiation in panty liners tracks closely with material science advances and regulatory pressure on chemical content. Manufacturers now engineer across four distinct axes—product format, substrate composition, thickness calibration, and packaging configuration—to capture diverging consumer priorities around convenience, sustainability, and skin sensitivity.
Product Type:
Technology and specification choices determine usage occasion and disposal pathway for each format variant.
- Disposable:Single-use construction with synthetic absorbent cores dominates pharmacy and modern retail channels. Working women in Indian metropolitan centers treat this as a workplace hygiene staple, driving volume through quick-commerce replenishment.
- Organic:Certified cotton or bamboo substrates without chlorine bleaching command shelf-space premiums under EU REACH fragrance and chemical restrictions. German and Dutch consumers absorb 15-20% cost premiums for compostable core formulations.
- Reusable:Washable designs with snap-in absorbent layers target environmental advocates seeking zero-waste alternatives. Limited penetration outside eco-conscious urban clusters due to laundering friction and upfront cost barriers.
- Scented:Fragrance-embedded variants face phased withdrawal from EU markets as ECHA expands allergen bans. Remaining demand concentrates in Middle Eastern markets where fragrance masking retains cultural priority.
Disposable leads on scale; organic leads on momentum.
Material:
Substrate selection now functions as a compliance and margin strategy rather than pure cost engineering.
- Cotton:Conventional and organic grades split between mass-market fluff pulp blends and premium unbleached certifications. Maharashtra and Gujarat harvest volatility creates margin unpredictability for natural-product specialists.
- Bamboo:Mechanical softening breakthroughs reduce production costs for breathable plant-based cores. Mid-tier brands displace polyester positioning as Asian fiber networks expand capacity.
- Polyester:Petroleum-based synthetic cores face demand erosion in premium tiers where breathability claims determine placement. Legacy supply chains compress as REACH deadlines accelerate substitution.
- Microfiber:Ultra-fine synthetic webs deliver moisture-wicking performance for athletic and active-use positioning. Niche adoption limited by biodegradability concerns and washing microplastic release.
Bamboo climbs the fastest; cotton retains volume dominance.
Thickness:
Calibrated absorbency-to-bulk ratios align with occupational dress codes and mobility requirements.
- Ultra Thin:Sub-0.8mm profiles with superabsorbent polymer cores dominate Asian daily-use segments. Unicharm engineering standards set comfort benchmarks for working women in formal attire.
- Thin:Moderate capacity designs balance discretion with light-flow protection. Standard offering across European pharmacy channels where discretion drives preference.
- Regular:Conventional thickness for moderate discharge management retains rural and price-sensitive urban share. Kirana store availability sustains penetration where modern retail has not displaced traditional distribution.
- Heavy:Enhanced absorbent capacity targets spotting, postpartum, or peri-menopause applications. Limited shelf presence outside specialty health retailers and direct-to-consumer platforms.
Ultra thin commands the steepest expansion trajectory; regular defends the installed base.
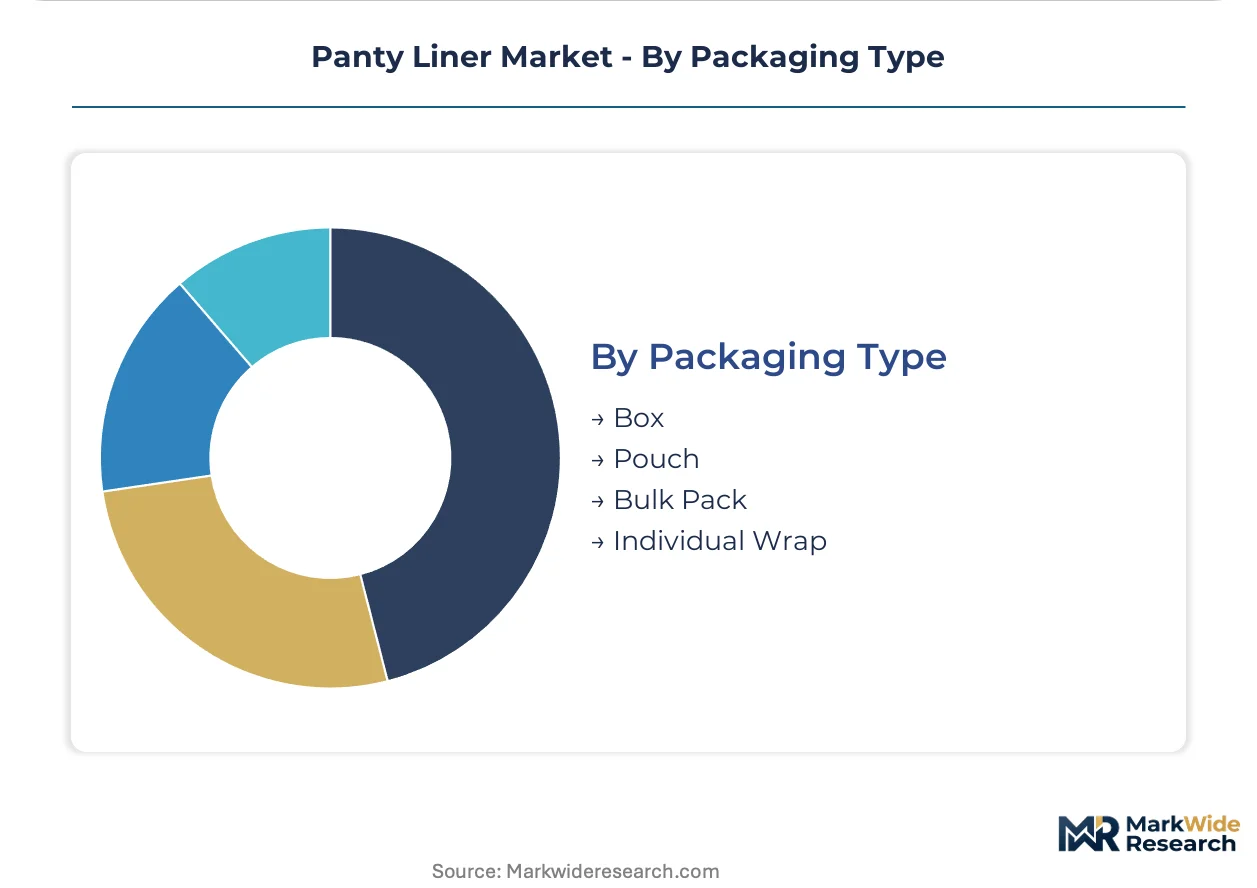
Packaging Type:
Format economics and channel access patterns shape configuration choices across price tiers.
- Individual Wrap:Single-unit sealed pouches enable discreet carriage and workplace storage. Blinkit and Zepto quick-commerce platforms prioritize this format for 10-minute delivery convenience in Mumbai and Bangalore.
- Box:Rigid cardboard retail packaging maximizes shelf visibility and brand billboard effect. Standard for pharmacy and supermarket slotting where retail presence drives trial.
- Pouch:Flexible film bags reduce shipping cube and material cost for e-commerce fulfillment. Subscription services favor this configuration for auto-replenishment logistics.
- Bulk Pack:Multi-count value formats target institutional procurement and price-conscious household stockpiling. Tier-2 Indian city expansion into Surat, Jaipur, and Lucknow channels volume through this configuration.
Individual wrap gains share fastest; box retains channel control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials are redirecting manufacturing investment toward jurisdictions with streamlined compliance pathways, while consumer markets fragment across divergent chemical disclosure standards and retail modernization trajectories.
United States
Quick-commerce adoption among urban millennials drives replenishment velocity through Blinkit-equivalent platforms in New York and Los Angeles. The FDA maintains Class I medical device oversight with biocompatibility testing mandates that extend clearance timelines. Texas and Georgia host contract manufacturing clusters serving private-label pharmacy chains.
Germany
REACH Annex XVII fragrance restrictions have eliminated synthetic-scented variants from pharmacy shelves, concentrating demand in unscented organic certifications. ECHA compliance costs favor established brands with dedicated regulatory affairs teams. The Rhine-Ruhr industrial corridor processes mechanical-softened bamboo fiber for mid-tier European distribution.
India
Female workforce participation in Mumbai, Bangalore, and Delhi-NCR normalizes daily panty liner use as workplace hygiene infrastructure. BIS certification requirements channel demand toward tested brands and create entry barriers for unorganized suppliers. Modern retail expansion into Surat, Jaipur, and Lucknow accesses 180 million women without established daily-use habits.
Japan
Ultra-thin engineering standards set by Unicharm influence comfort benchmarks across Asian daily-use segments. METI guidelines on sustainable materials accelerate pilot programs for plant-based superabsorbent polymers. The Kansai region hosts specialized converting equipment for sub-0.8mm profile production.
Netherlands
Compostable core formulations command 15-20% cost premiums among environmentally conscious consumers in Amsterdam and Rotterdam. EU single-use plastic directives reshape packaging format requirements toward fiber-based alternatives. The Eindhoven region concentrates pilot-scale production of cornstarch-derived absorbent materials.
Panty Liner Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmacy-controlled channels favoring established multinationals while private-label growth erodes margin pools in mass retail. The vendor base organizes into three functional tiers: diversified personal care conglomerates with direct-to-consumer infrastructure, regional hygiene specialists with retail shelf dominance, and OEM converters serving pharmacy and supermarket private-label programs. Capacity expansion and subscription platform development represent the dominant competitive moves, with players prioritizing recurring revenue capture over transactional volume growth.
Among diversified personal care conglomerates, Procter & Gamble Company and Kimberly-Clark Corporation occupy positions defined by channel control architectures—P&G through direct-to-consumer platform infrastructure and Kimberly-Clark through pharmacy and broad retail shelf presence. Unicharm Corporation exemplifies the regional engineering specialist archetype, with positioning derived from ultra-thin product development for Asian daily-use consumption patterns. These three entities represent divergent strategic bets on consumer access: platform-based replenishment, physical retail density, and technical specification leadership.
| Leading Market Players |
|---|
| Procter & Gamble Company |
| Kimberly-Clark Corporation |
| Johnson & Johnson Services Inc. |
| Essity AB |
| Unicharm Corporation |
| Kao Corporation |
| Edgewell Personal Care Company |
| Ontex |
| First Quality Enterprises Inc. |
| Others |
Value Network & Pricing Analysis
Backward integration into organic cotton sourcing anchors supply position for premium-tier brands while compressing margin exposure to Maharashtra and Gujarat harvest volatility. Captive fiber procurement buffers pricing power against commodity swings, though REACH compliance investments offset gains through certification overhead.
Pricing Analysis
Retailer markup layers in EU pharmacy channels absorb REACH-driven reformulation costs through shelf-space premiums for unscented organic SKUs. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale, with subscription direct-to-consumer platforms capturing least price-sensitive buyers through auto-replenishment lock-in. Cost compression in polyester-core segments intensifies as plant-based alternatives displace synthetic positioning, while quick-commerce delivery fees elevate effective prices for convenience-driven urban Indian consumers.
Supply Chain Analysis
BIS certification gating channels Indian demand toward tested brands while creating compliance moats against unorganized suppliers. Raw material networks draw from India for organic cotton, China for bamboo fiber processing, and Germany for mechanical-softening equipment, with fluff pulp alternatives resting on concentrated Asian petrochemical supply. Single-source vulnerability in superabsorbent polymer feedstock exposes brands to disruption, while distribution runs through pharmacy-controlled channels in Europe and quick-commerce platforms in Indian metropolitan centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The panty liner market reads as a late-cycle quality story, with EU REACH fragrance restrictions and Indian workforce expansion normalizing premium daily-use specifications over commodity alternatives.
For Market Incumbents: Hedge margin exposure by securing captive organic cotton contracts in Maharashtra and Gujarat before harvest volatility intensifies. Accelerate FDA biocompatibility testing pipelines to compress 14-month clearance timelines for novel plant-based materials, defending position against emerging bamboo-fiber specialists.
For New Entrants and Emerging Players: Begin with Surat, Jaipur, and Lucknow Tier-2 penetration, where 180 million women lack established daily-use habits and modern retail expansion creates first-mover shelf access. Target quick-commerce platform listings as the primary go-to-market angle, capturing 23% of under-30 replenishment decisions before brand loyalty solidifies.
For Investors and Strategic Acquirers: Roll-up economics work for regional hygiene specialists with BIS certification and established kirana distribution because India's modern retail transition fragments share across too many local players for standalone viability. Monitor FDA clearance timeline compression as the inflection signal for organic material feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Platform Launch | Auto-replenishment bypasses retail slotting fees and captures lifetime value through predictable reorder cycles. |
| Organic Certification Investment | REACH Annex XVII compliance creates shelf-space premiums in EU pharmacy channels. |
| Bamboo Fiber Backward Integration | Mechanical softening breakthroughs lower production costs for breathable plant-based cores. |
| Quick-Commerce Channel Entry | Blinkit and Zepto disintermediation captures 23% of category volume among women under 30. |
| Tier-2 City Distribution Expansion | Surat, Jaipur, and Lucknow access 180 million women without established daily-use hygiene habits. |
Research Methodology
Coverage spans the United States, Germany, India, Japan, and the Netherlands, with primary inputs from each market combining interviews with brand managers, category buyers at retailers, supply planners, and regulatory affairs specialists with secondary validation from FDA filings, ECHA REACH registrations, BIS certification databases, and Nielsen retail audit data. Bottom-up volume modeling and top-down value triangulation cross-verify outputs.
Rate-of-change decomposition isolates volume drivers from price-mix effects across the analysis window, with segmentation modeling across product format, substrate composition, thickness calibration, and packaging configuration. CAGRs derive from regression against female workforce participation rates, modern retail penetration curves, and regulatory compliance cost indices, with REACH deadline phasing and quick-commerce adoption velocity as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including weather-induced cotton harvest shocks, FDA clearance timeline extensions for novel materials, and single-source superabsorbent polymer supply disruptions. Forecasts reflect assumptions about regulatory stability and fiber processing cost trajectories. A model refresh is warranted upon material change in EU single-use plastic directive implementation or Indian Tier-2 modern retail expansion velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Safety Products
BRICS Disposable Hygiene Products Market
Baby Safety Products
Global Feminine Protection Market
Baby Safety Products
United States Away from Home Tissue and Hygiene Market
Baby Safety Products
Baby Safety Products Market
Baby Safety Products
Organic Sanitary Napkin Market
Baby Safety Products
Reusable/Washable Hygiene Products Market
Baby Safety Products
Biodegradable Sanitary Napkins Market
Baby Safety Products
Reusable Sanitary Pads Market
Baby Safety Products
Baby Safety Seats Market
Baby Safety Products
North America Baby Monitors Market
Baby Safety Products
Global Baby Cleaning Products Market
Baby Safety Products
Japan Adult Diaper Market
Baby Safety Products
Booster Car Seats Market
Baby Safety Products
Forward Facing Type Child Safety Seats Market
Baby Safety Products
North America Adult Diaper Market
Baby Safety Products
Baby Gate Market