
 Baby Safety Seats Market | 2026-2036
Baby Safety Seats Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Safety Seats Market Analysis
The EU Green Deal is pivoting baby safety seat manufacturers toward bio-based foams and recycled polymer shells. Dorel Juvenile Inc. anchors North American distribution through deep retail partnerships with mass merchandisers. Britax Child Safety Inc. specializes in advanced side-impact protection systems that command premium positioning. Goodbaby International Holdings Ltd. dominates Asian manufacturing scale with vertically integrated plastic injection operations.
Baby safety seats are child restraint systems engineered to absorb crash energy through engineered foam cores, steel-reinforced frames, and five-point harness assemblies that distribute forces across the strongest body regions. Their primary purpose is reducing fatal and serious injury risk during automotive collisions for occupants from birth through approximately twelve years of age. Convertible seats and all-in-one configurations capture the largest margin pools as parents prioritize extended-use value over single-stage products. ISOFIX installation methods are displacing seat belt routing in premium tiers due to measurable reduction in misuse rates during consumer fitting.
The National Highway Traffic Safety Administration enforces Federal Motor Vehicle Safety Standard 213 in the United States, mandating dynamic sled testing and flammability resistance that shapes product development timelines. The European Union's i-Size regulation under ECE R129 imposes mandatory rear-facing requirements to fifteen months and side-impact testing protocols that exceed prior UN specifications. Stakeholders must monitor pending regulatory harmonization between China's GB standards and international crash-test protocols, as alignment decisions will determine which manufacturing platforms achieve cross-border economies.
Market Dynamics
Extended rear-facing mandates under ECE R129 and state-level enforcement tightening in the United States are compressing product lifecycles and forcing convertible seat redesigns across the value chain.
Growth Catalysts
- i-Size regulation expansion:Mandatory rear-facing requirements to fifteen months and side-impact testing protocols are accelerating replacement demand for non-compliant legacy inventories across European markets.
- Bio-based material mandates:The EU Green Deal is pulling manufacturers toward recycled polymer shells and plant-derived foam cores, creating premium positioning opportunities for compliant suppliers.
- Urban parent density:Concentrated metropolitan household formation in the United States is concentrating demand for ISOFIX-compatible installation systems that reduce fitting errors.
Market Restraints
- Polypropylene feedstock volatility:Crude-linked resin pricing swings compress margin stability for injection-molded shell producers without captive polymer supply.
- Testing facility concentration:Dynamic sled certification capacity clusters in Germany and the United States, creating bottlenecks for new market entrants seeking ECE R129 validation.
- Extended-use value capture:All-in-one seat architectures that span birth-to-booster stages reduce per-child purchase frequency, compressing unit volume expansion.
Strategic Opportunities
- Secondhand channel formalization:Certified pre-owned seat programs with verified crash-history documentation can unlock price-sensitive segments without new production capex.
- GB standard harmonization:Alignment between China's domestic crash-test protocols and UN ECE specifications would enable single-platform manufacturing for cross-border export.
- Subscription-based rotation models:Staged-size exchange services address rear-facing-to-forward-facing transition timing without full purchase commitment.
Industry Challenges
- Child passenger safety technician scarcity:Certified installation training capacity limits retail execution of proper fitting services, elevating misuse liability exposure.
- Multi-jurisdiction labeling complexity:Dual FMVSS 213 and ECE R129 certification requirements fragment packaging and documentation workflows for universal product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Safety Seats Market |
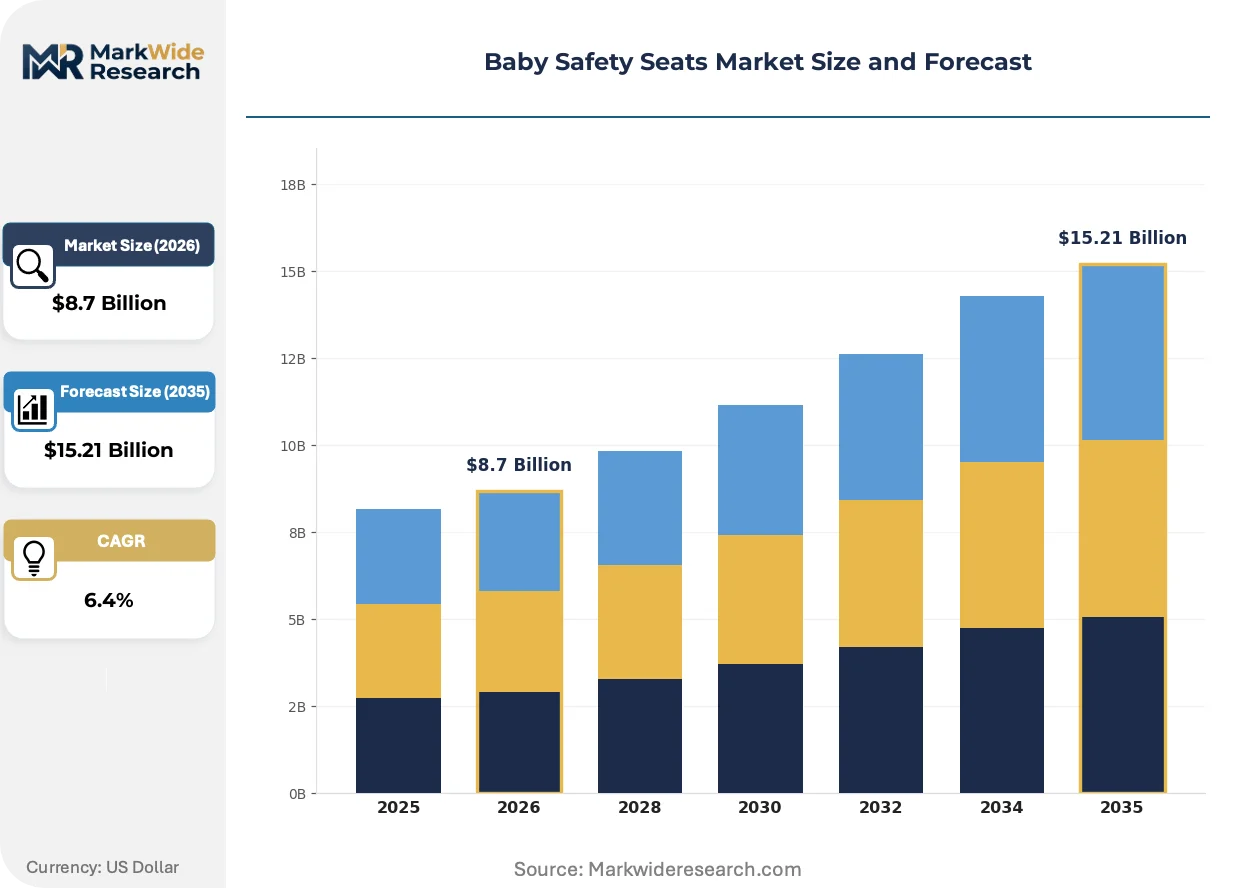
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infant Seats, Convertible Seats, Booster Seats, All-in-One Seats Installation Method: ISOFIX, Latch System, Seat Belt, Hybrid Material: Plastic, Metal, Foam, Fabric Age Group: Newborn, Toddler, Preschooler, School Age |
| Companies Covered | Graco Children's Products Inc., Dorel Juvenile Inc., Britax Child Safety Inc., Artsana S.p.A., Goodbaby International Holdings Ltd., Evenflo Company, Inc., Newell Brands Inc., Nuna International B.V., Combi Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Safety Seats Market Emerging Trajectories
Material science advances and installation system standardization are compressing the gap between premium safety performance and mass-market accessibility across all price tiers.
Smart sensor arrays embedded in harness tensioners and chest clips are integrating real-time installation feedback through Bluetooth-connected mobile applications. First-time parents in metropolitan United States markets are adopting these systems at accelerated rates. The technology is integrating misuse detection directly into the fitting process, reducing improper angle and loose-strap incidents that dominate field failure modes.
The European Union's updated i-Size regulation under ECE R129 mandates side-impact sled testing that exceeds prior UN specifications for frontal crashes alone. Manufacturers serving EU member states must redesign internal frame geometries and energy-absorbing foam densities. Convertible seat architectures face the steepest compliance burden, as dual-orientation designs must satisfy rear-facing structural loads plus new lateral intrusion protocols.
Direct-to-consumer digital channels are displacing traditional baby specialty retail for initial product research and purchase completion. Millennial and Gen-Z parents in the United States and United Kingdom increasingly complete transactions through manufacturer-owned websites with virtual fitting assistance. This rotation compresses wholesale margin extraction and elevates logistics complexity for bulky, regulated products requiring signature delivery.
Baby Safety Seats Market Segmentation
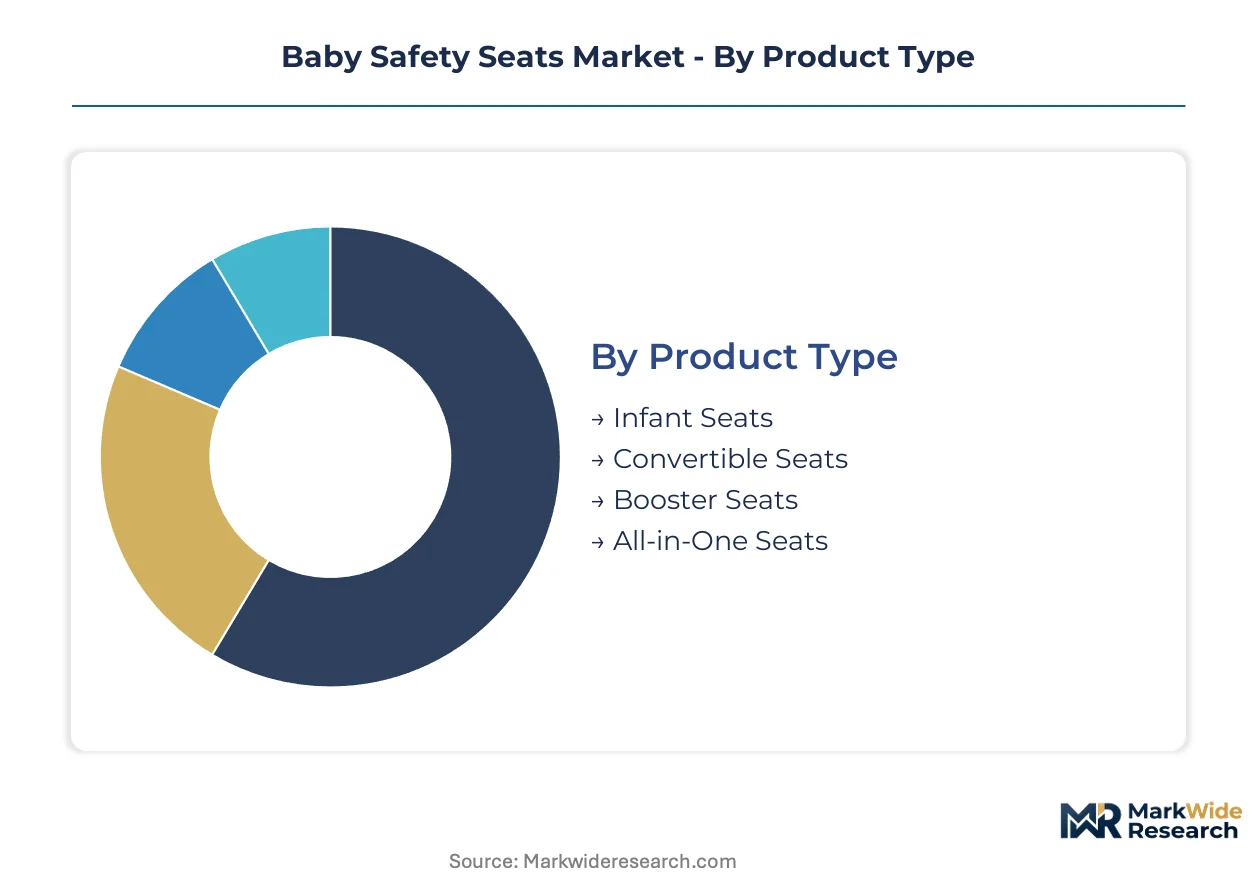
Product architecture in baby safety seats divides sharply between single-purpose designs and extended-use platforms, with installation system choices determining both manufacturing complexity and retail margin structure. Material specifications and age-targeted sizing create distinct supply chain footprints that shape competitive positioning across price tiers.
Product Type:
Supply concentration clusters around convertible architectures that amortize development costs across multiple regulatory testing protocols.
- Convertible Seats:Dual-orientation frames accommodate both rear-facing and forward-facing configurations through adjustable base angles and reinforced steel spine structures. Parents in the United States facing tightened state enforcement standards are prioritizing these designs for extended-use value, compressing demand for single-stage alternatives.
- All-in-One Seats:Birth-to-booster platforms integrate internal harness systems with removable backrests that transition to belt-positioning boosters. Metropolitan households in the United States are adopting these most aggressively as urban density reduces storage capacity for multiple seat replacements.
- Infant Seats:Rear-facing-only carriers with detachable bases dominate hospital discharge bundle programs and rental fleet inventories.
- Booster Seats:Belt-positioning designs without internal harness systems capture the final stage before adult seat belt transition.
Convertible Seats absorb the bulk of installed capacity; All-in-One Seats are expanding most quickly.
Installation Method:
Cost tier stratification separates premium ISOFIX-compatible systems from economy seat belt routing across retail channels.
- ISOFIX:Rigid lower anchor attachments with color-coded indicators reduce misuse rates through standardized connection geometry. First-time parents in the United States are demanding these systems at premium price points as direct-to-consumer channels displace traditional retail fitting assistance.
- Latch System:Flexible webbing-based lower anchors with tether straps accommodate vehicle anchor point variations across manufacturer specifications.
- Seat Belt:Universal routing paths through belt guides maintain compatibility with older vehicle fleets lacking standardized anchor hardware.
- Hybrid:Dual-compatible bases accept either ISOFIX rigid anchors or seat belt lock-off mechanisms for fleet flexibility.
ISOFIX captures the steepest margin expansion; Hybrid configurations are gaining share fastest among value-conscious segments.
Material:
Volume concentration in injection-molded polymer shells creates feedstock exposure that shapes supplier consolidation patterns.
- Plastic:Polypropylene copolymer shells with talc filler reinforcement dominate mass production through high-volume injection molding operations. The EU Green Deal is pulling manufacturers toward recycled polymer grades that command premium positioning in European markets.
- Foam:Expanded polypropylene and polyurethane energy-absorbing cores manage crash deceleration through controlled compression characteristics.
- Metal:Steel reinforcement bars and aluminum adjustment mechanisms provide structural integrity for harness anchor points.
- Fabric:Polyester blend covers with moisture-wicking treatments balance durability against skin contact comfort requirements.
Plastic absorbs the bulk of installed capacity; Foam specifications are expanding most quickly with side-impact testing mandates.
Age Group:
Customer type segmentation separates first-time parents seeking maximum protection from multi-child households prioritizing cost amortization.
- Toddler:Extended rear-facing requirements under ECE R129 and United States state-level mandates are concentrating demand in this bracket as parents delay forward-facing transitions.
- Newborn:Hospital discharge programs and prenatal registry completions drive initial purchase timing for rear-facing-only carriers.
- Preschooler:Forward-facing harness systems with higher weight limits accommodate children before booster stage transition.
- School Age:Belt-positioning boosters address final stage requirements before adult seat belt fit adequacy.
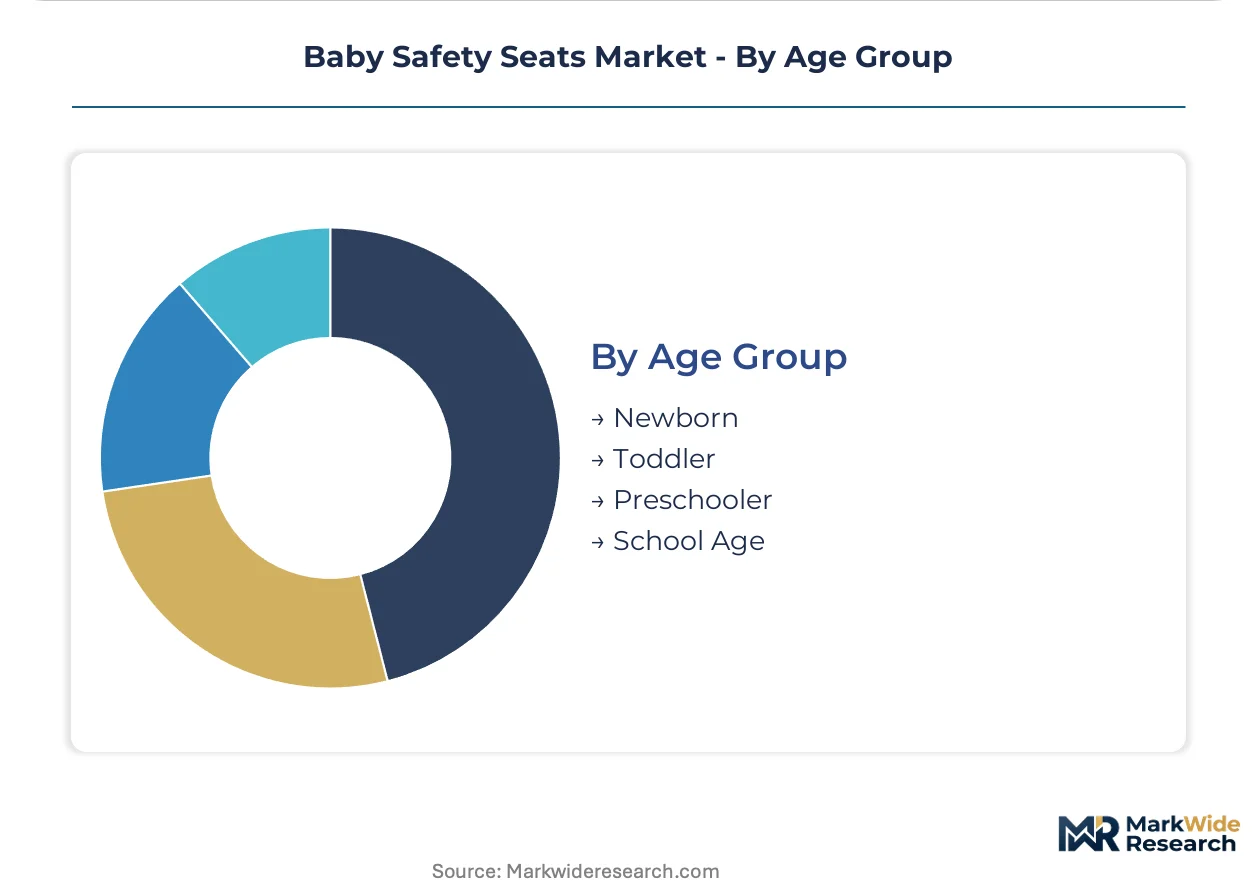
Toddler specifications absorb the bulk of installed capacity; Newborn configurations are expanding most quickly with updated rear-facing duration recommendations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dongguan anchors Asian manufacturing capacity for injection-molded polymer shells, while Detroit and Stuttgart concentrate engineering design for advanced side-impact systems. State-level enforcement tightening and i-Size regulatory expansion are redrawing competitive geography across three continents.
United States
California and Texas drive demand concentration as metropolitan household formation accelerates ISOFIX-compatible purchases. NHTSA enforces FMVSS 213 with dynamic sled testing mandates that shape product development timelines for domestic release. Detroit engineering clusters specialize in steel-reinforced frame architectures for convertible seat platforms.
Germany
Stuttgart and Munich host certification facilities for ECE R129 validation, creating bottlenecks for new market entrants. The KBA administers i-Size compliance verification alongside side-impact testing protocols that exceed prior UN specifications. Bavarian manufacturing corridors concentrate foam core production for energy-absorbing applications.
China
Yangtze River Delta manufacturing zones dominate plastic injection operations for shell production at global scale. GB standard harmonization discussions with UN ECE protocols remain pending, determining cross-border manufacturing platform viability. Shanghai-based engineering centers prototype smart sensor arrays for harness tension monitoring.
United Kingdom
London and Southeast England concentrate direct-to-consumer digital channel adoption among Millennial parents. Trading standards enforcement aligns with EU i-Size requirements during post-Brexit regulatory transition. Midlands manufacturing clusters produce textile covers with moisture-wicking treatments for premium positioning.
Japan
Tokyo and Osaka metropolitan areas drive compact vehicle fleet penetration that favors space-efficient convertible designs. METI oversees alignment between domestic safety standards and international crash-test protocols for export manufacturing. Nagoya engineering corridors specialize in aluminum adjustment mechanism production.
Baby Safety Seats Market Vendor Landscape
Premium-margin players sit above commodity-margin players across installation system sophistication and certification tiering. Market structure consolidates around three to five dominant specialists with vertically integrated manufacturing footprints, while mid-tier assemblers rely on outsourced polymer supply. Two strategic archetypes define competitive positioning: engineering-led specialists commanding patent-protected side-impact technologies, and scale-driven manufacturers optimizing injection-molded shell economics. Dominant competitive moves include backward integration into captive polymer supply and technology licensing partnerships for smart sensor integration.
Among North American specialists, Dorel Juvenile Inc. and Britax Child Safety Inc. exemplify the engineering-led archetype through deep retail partnership structures. Goodbaby International Holdings Ltd. anchors the scale-driven tier with Dongguan-based manufacturing concentration. Graco Children's Products Inc. occupies a hybrid position combining mass-market distribution reach with standardized ISOFIX platform deployment.
| Leading Market Players |
|---|
| Graco Children's Products Inc. |
| Dorel Juvenile Inc. |
| Britax Child Safety Inc. |
| Artsana S.p.A. |
| Goodbaby International Holdings Ltd. |
| Evenflo Company, Inc. |
| Newell Brands Inc. |
| Nuna International B.V. |
| Combi Corporation |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up specialists like Dorel Juvenile and Newell Brands anchor pricing discipline through centralized procurement leverage over polypropylene feedstock contracts, while their captive retail partnerships compress wholesale margin extraction and enforce volume-tiered rebate structures across mass-merchandiser channels.
Pricing Analysis
Value-based pricing anchored to ECE R129 certification tier separates premium ISOFIX-compatible systems from economy seat belt routing. Price differentiation stems from side-impact testing validation and steel-reinforced frame architectures. Cost compression in economy tiers intensifies as recycled polymer mandates under the EU Green Deal elevate compliant material premiums. First-time parents in metropolitan United States markets exhibit lowest price sensitivity; multi-child households in secondary cities show highest elasticity.
Supply Chain Analysis
Polypropylene copolymer supply rests on Yangtze River Delta injection molding clusters, German foam core production corridors, and Japanese aluminum mechanism specialists. Raw material dependencies span crude-linked resin grades, talc filler reinforcements, and steel reinforcement bar specifications. Single-source vulnerability concentrates in ECE R129 sled testing facilities clustered in Germany and the United States. Distribution runs through mass-merchandiser retail partnerships and direct-to-consumer digital channels with signature delivery requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where control over captive polymer supply and in-house foam core production determines margin capture against feedstock volatility.
For Market Incumbents: Cement certification tier separation by accelerating ECE R129 validation for convertible architectures before pending GB standard harmonization unlocks Chinese export competition. Deepen retail partnership exclusivity to defend against direct-to-consumer channel displacement. Prioritize backward integration into recycled polymer compounding to capture EU Green Deal premium positioning.
For New Entrants and Emerging Players: Hospital discharge bundle programs represent the most penetrable entry vector, as maternity ward relationships face minimal incumbent lock-in. Target certified pre-owned seat formalization to unlock price-sensitive segments without production capex. Pursue subscription-based rotation models as the primary go-to-market angle for urban density constraints.
For Investors and Strategic Acquirers: Pending KBA certification queue length is the leading indicator that ECE R129 validation capacity scarcity will persist, favoring asset-light testing partnerships over facility buildout. Five-to-ten year viability hinges on smart sensor integration patents and ISOFIX platform standardization. Target acquisition archetypes: engineering-led specialists with side-impact IP portfolios. Watch GB standard harmonization announcements as the decisive inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Sensor Integration | Bluetooth-enabled harness tension monitoring reduces misuse rates for NHTSA compliance. |
| Recycled Polymer Transition | EU Green Deal mandates pull manufacturers toward bio-based foam cores for premium positioning. |
| Direct-to-Consumer Channel Expansion | Manufacturer-owned websites with virtual fitting displace traditional baby specialty retail. |
| ECE R129 Certification Acceleration | Side-impact testing validation creates bottleneck moats against unvalidated competitors. |
| Subscription Rotation Model Launch | Staged-size exchange services address rear-facing-to-forward-facing transition timing. |
Methodological Framework
Document review covered NHTSA FMVSS 213 enforcement data, ECE R129 technical specifications, EU Green Deal material mandates, and customs trade records, complemented by interviews with product development executives at convertible seat manufacturers, KBA certification engineers, mass-merchandiser category buyers, and child passenger safety technicians. Secondary validation drew from hospital discharge program administrators, polymer procurement leads, and direct-to-consumer logistics operators. Bottom-up unit shipment estimates triangulated against top-down value projections across the analysis window.
Cross-referencing historical certification timelines with expert panel input on regulatory harmonization probabilities shaped the analytical framework. Segmentation dimensions modeled include product architecture, installation method, material specification, and age-targeted sizing. CAGRs derived from slope analysis of replacement cycle compression and extended rear-facing mandate adoption curves. Industry-specific forecast inputs encompassed polypropylene feedstock price elasticity and ISOFIX vehicle fleet penetration rates.
Caveats apply where ECE R129 enforcement delays, GB standard harmonization reversals, or polypropylene supply disruptions could materially shift the outlook. Forecasts reflect assumptions about state-level mandate tightening trajectories and recycled polymer cost curves. A small set of named triggers—KBA certification queue length, Dongguan manufacturing wage inflation, and NHTSA misuse rate field studies—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Safety Products
Reusable/Washable Hygiene Products Market
Baby Safety Products
Booster Car Seats Market
Baby Safety Products
North America Adult Diaper Market
Baby Safety Products
Baby Safety Products Market
Baby Safety Products
United States Away from Home Tissue and Hygiene Market
Baby Safety Products
BRICS Disposable Hygiene Products Market
Baby Safety Products
Japan Adult Diaper Market
Baby Safety Products
Panty Liner Market
Baby Safety Products
North America Baby Monitors Market
Baby Safety Products
Reusable Sanitary Pads Market
Baby Safety Products
Global Feminine Protection Market
Baby Safety Products
Biodegradable Sanitary Napkins Market
Baby Safety Products
Baby Gate Market
Baby Safety Products
Forward Facing Type Child Safety Seats Market
Baby Safety Products
India Pant Type Adult Diaper Market
Baby Safety Products
Organic Sanitary Napkin Market