
 Global Baby Cleaning Products Market | 2026-2036
Global Baby Cleaning Products Market Size, Share, and Industry Trends Forecast 2026-2036
Global Baby Cleaning Products Market Analysis
The premium-commodity split in baby cleaning products is consolidating around ingredient transparency and certification standards. Johnson & Johnson leverages its heritage positioning to sustain trust among first-time parents seeking dermatologist-tested formulations. Procter & Gamble anchors volume through mass retail distribution and private-label defense in North American and European supermarkets. Himalaya Drug Company differentiates via Ayurvedic ingredient narratives that resonate with South Asian and Middle Eastern consumers prioritizing plant-derived baby care.
Baby cleaning products encompass surfactant-based and solvent-based formulations engineered for residue-free removal of milk film, food soils, and environmental contaminants from infant-contact surfaces, with pH specifications typically ranging from 4.5 to 6.5 to match infant skin barrier chemistry. Wipes command the largest revenue pool due to convenience-driven diaper-bag portability and on-the-go usage patterns, though organic formulation lines are capturing margin premiums as ingredient-conscious parents trade up from standard offerings. Refill packs are gaining structural share as sustainability mandates and retailer plastic-reduction commitments reshape packaging economics across European and Asian markets.
FDA oversees cosmetic and drug-claim distinctions for baby wipes and washes in the United States, while ECHA enforces REACH substance restrictions that limit preservative options for European formulators. The EU Green Deal's packaging waste directives are accelerating fiber-based and compostable material transitions. China's SAMR and GB standards for infant products are tightening labeling requirements for imported brands. Stakeholders must monitor evolving chemical hazard classifications across these jurisdictions to anticipate reformulation costs and market access barriers.
Market Dynamics
Ingredient disclosure mandates across multiple jurisdictions are compressing formulation flexibility while simultaneously creating tiered market segmentation based on certification depth and testing rigor.
Growth Catalysts
- EU Green Deal packaging directives:European retailers are accelerating fiber-based and compostable material transitions, creating structural demand for refill-compatible formats and concentrated formulations that reduce plastic intensity.
- Millennial and Gen Z parent cohorts:These buyers prioritize dermatologist-tested and organic-certified products, trading up from standard wipes and washes to premium-positioned lines with transparent supply chains.
- Birth rate concentration:Rising disposable incomes in China, India, and Brazil are expanding addressable demand for imported and domestic infant care brands simultaneously.
Market Restraints
- Preservative restriction tightening:ECHA REACH substance limitations are reducing viable antimicrobial options for European formulators, forcing reformulation cycles that extend product development timelines.
- Surfactant feedstock volatility:Palm-derived and petrochemical-based surfactant input costs fluctuate with agricultural commodity and energy markets, compressing margin predictability for mass-market producers.
- Private-label substitution:Supermarket chains in North America and Western Europe are expanding house-brand baby wipes with comparable performance claims at 30-40% price discounts to national brands.
Strategic Opportunities
- Ayurvedic ingredient narratives:Plant-derived positioning rooted in traditional medicine systems resonates with South Asian and Middle Eastern consumers seeking culturally familiar safety assurances.
- Subscription and auto-replenishment channels:Direct-to-consumer platforms are capturing recurring revenue from time-constrained parents who prioritize convenience over in-store brand browsing.
- China SAMR labeling convergence:Tightened GB standards for imported infant products create competitive moats for early-compliant brands willing to invest in localized testing and documentation.
Industry Challenges
- Cross-jurisdiction formulation complexity:Maintaining separate SKUs for FDA cosmetic-claim, ECHA REACH-compliant, and China SAMR-registered markets fragments production economics and inventory management.
- Biodegradability certification timelines:Third-party compostability validations for fiber-based wipes require 6-18 month testing periods that lag behind retailer sustainability commitment deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Baby Cleaning Products Market |
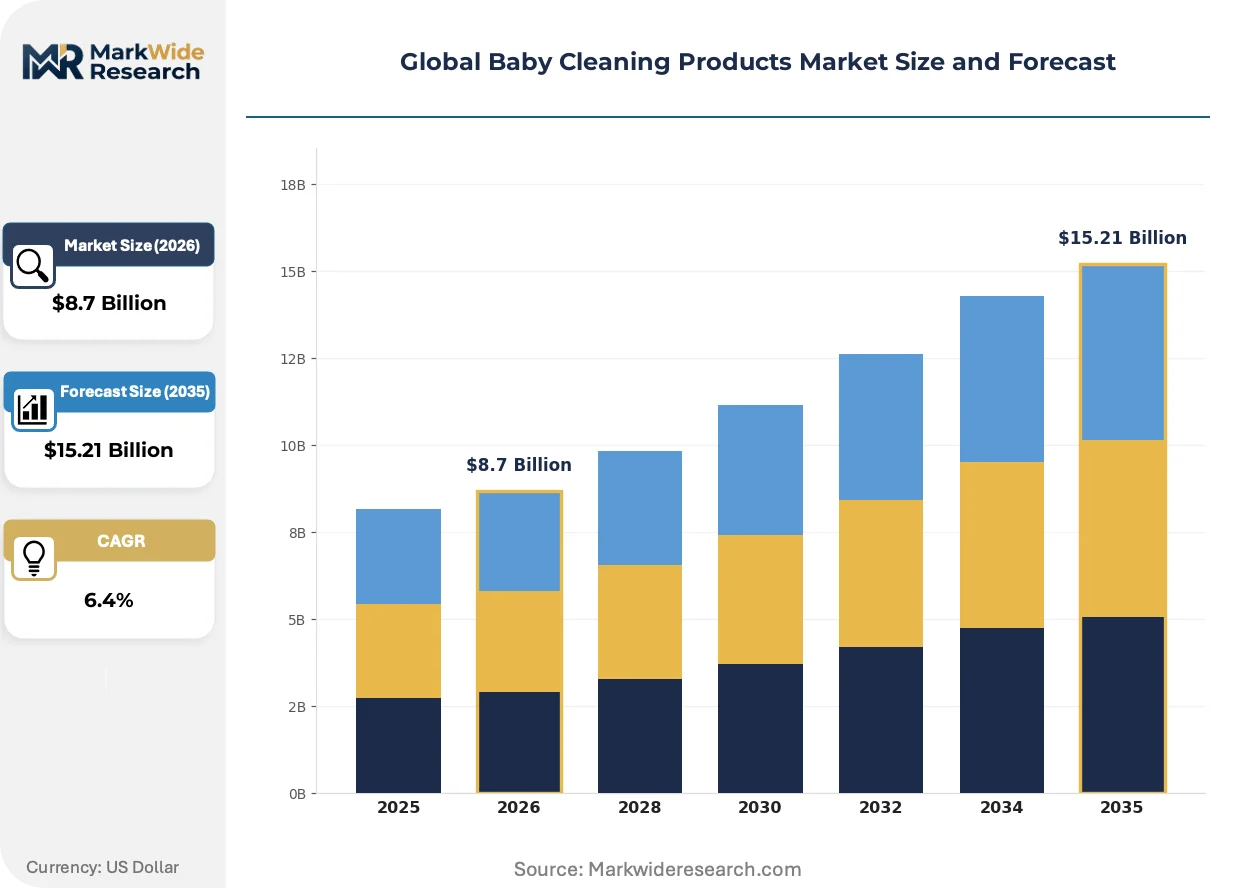
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wipes, Sprays, Detergents, Soaps Formulation: Organic, Hypoallergenic, Biodegradable, Scented Usage: Dishes, Laundry, Toys, Surfaces Packaging Type: Refill Packs, Bottles, Sachets, Bulk Containers |
| Companies Covered | Johnson & Johnson, Procter & Gamble, Kimberly-Clark, Pigeon Corporation, Mayborn Group Limited, Nuby, Unilever, Kenvue, Himalaya Drug Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Baby Cleaning Products Market Emerging Trajectories
Formulation chemistry and material science are converging to redefine performance benchmarks while regulatory disclosure requirements reshape competitive differentiation mechanisms.
Plant-derived surfactant systems are absorbing market share from traditional petrochemical bases as European and North American parents prioritize renewable ingredient sourcing. Premium-positioned brands are adopting alkyl polyglucoside and amino acid-derived surfactants at accelerated rates. This absorption is compressing the performance gap between natural-positioned and conventional formulations while raising raw material cost structures across mid-tier product lines.
REACH substance restriction expansions are systematically eliminating isothiazolinone preservatives from European baby wipe formulations. ECHA hazard reclassifications have triggered wholesale preservative system overhauls among contract manufacturers serving EU markets. Wet wipes and liquid washes containing legacy biocide packages face delisting pressure from major German and French retail banners.
Refill economics are restructuring purchase patterns as sustainability-motivated buyers trade single-use packaging for concentrated replenishment formats. European supermarket chains are dedicating expanded shelf space to refill stations and bulk pouches, displacing traditional canister wipes in premium urban locations. This shift is most visible in Scandinavian markets and German-speaking cities where municipal waste reduction targets intersect with affluent parent demographics.
Global Baby Cleaning Products Market Segmentation
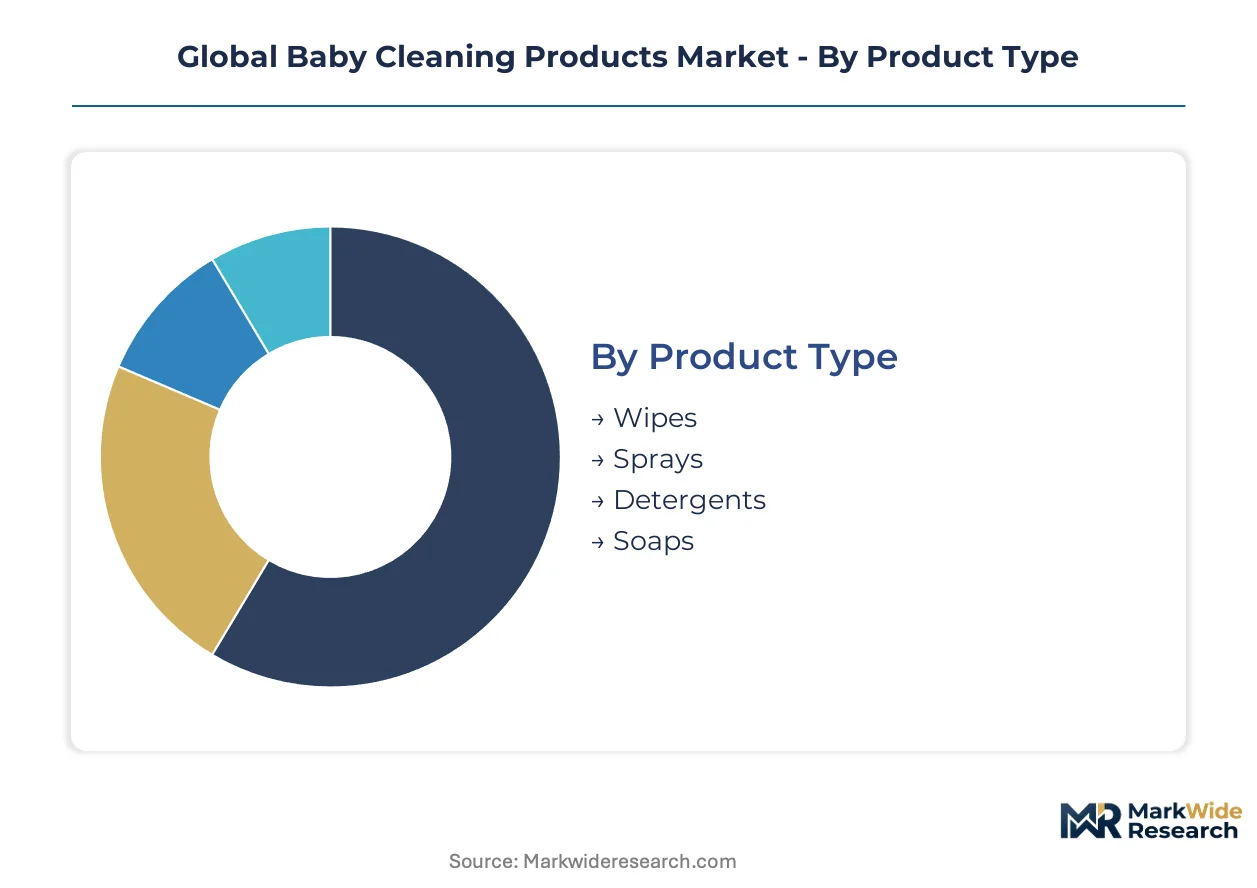
Segmentation in baby cleaning products reveals how capital deployment, regulatory compliance costs, and raw material sourcing intensity vary dramatically across product architectures. Manufacturers must align production investments with the specific formulation chemistry and packaging formats that dominate each addressable niche.
Product Type:
Capital intensity peaks in wipe manufacturing due to nonwoven substrate production lines and wet-laid processing equipment, while spray and liquid formats require lower fixed asset thresholds but higher working capital for surfactant inventory.
- Wipes:Nonwoven substrate integration with liquid impregnation systems dominates manufacturing economics. Demand concentrates in diaper-bag portability use cases across urban China and India, where on-the-go parenting patterns drive repeat purchase frequency.
- Sprays:Trigger-mechanism assembly and aerosol or pump dispersion systems require precision filling lines. Surface disinfection applications in Brazilian and Saudi Arabian households are expanding fastest as dual-income parents prioritize time-efficient cleaning protocols.
- Detergents:Concentrated liquid and powder formulations for infant laundry carry moderate capital requirements in blending and packaging equipment.
- Soaps:Solid bar and liquid hand wash production leverages existing personal care manufacturing infrastructure with minimal incremental investment.
Wipes absorb the bulk of installed capacity; sprays are expanding most quickly.
Formulation:
Margin structure stratifies sharply across certification depth, with organic and hypoallergenic lines commanding ingredient transparency premiums while scented and standard formulations compete on unit economics.
- Organic:Plant-derived surfactant systems and preservative-free chemistry require dedicated batch processing equipment and segregated supply chains. Millennial parents in Germany, France, and California are trading up from conventional alternatives as ECHA REACH restrictions and FDA cosmetic-claim scrutiny intensify.
- Hypoallergenic:Dermatologist-tested and pediatrician-endorsed positioning demands clinical validation investments and specialized quality assurance protocols. First-time parents across Canada, Australia, and the United Kingdom prioritize these assurances for newborn skin barrier protection.
- Biodegradable:Formulation chemistry optimized for wastewater treatment compatibility and aquatic toxicity reduction carries moderate R&D overhead.
- Scented:Fragrance incorporation adds minimal marginal cost but faces declining preference among ingredient-conscious buyer cohorts.
Hypoallergenic formulations capture the deepest margin pools; organic lines are gaining share fastest.
Usage:
Application-specific performance requirements dictate surfactant selection and pH calibration, with toy and surface cleaning demanding broader antimicrobial spectra than laundry or dish applications.
- Toys:Residue-free removal of saliva, food soils, and environmental contaminants from mouthing surfaces requires pH-balanced formulations typically ranging 4.5 to 6.5. Parents in Japan, South Korea, and Singapore prioritize these specifications for early childhood developmental objects.
- Surfaces:High-touch area disinfection for changing tables and feeding stations demands broader antimicrobial efficacy. Urban Indian and Chinese households with multigenerational cohabitation patterns are expanding purchase frequency for these applications.
- Dishes:Milk film and formula residue removal from bottles and utensils requires surfactant systems effective against protein soils.
- Laundry:Fabric-safe cleaning for infant clothing and bedding represents the highest volume application with established supply chain infrastructure.
Laundry absorbs the bulk of installed capacity; toy-focused formulations are climbing the fastest.
Packaging Type:
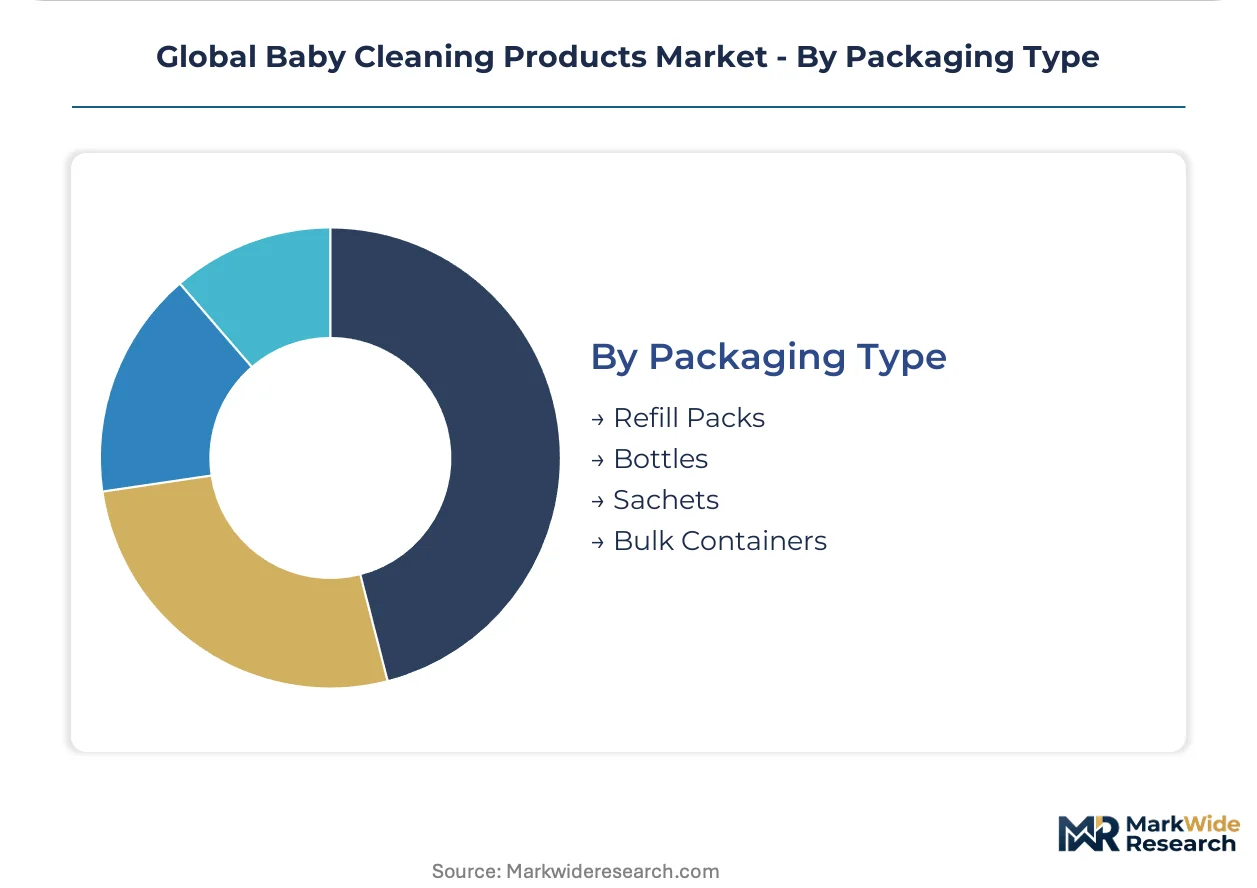
Plastic intensity and circular economy compliance costs are restructuring packaging investment priorities, with refill-compatible formats requiring specialized filling equipment and bulk logistics infrastructure.
- Refill Packs:Concentrated replenishment formats and flexible pouch systems demand precision dosing technology and bulk distribution networks. EU Green Deal packaging directives and Scandinavian municipal waste reduction targets are accelerating retailer shelf space allocation in Stockholm, Copenhagen, and Berlin.
- Bottles:Rigid PET and HDPE containers with trigger or flip-cap closures remain the default for spray and liquid detergent categories. Mass retail distribution in US and Canadian supermarkets sustains volume concentration despite sustainability headwinds.
- Sachets:Single-use flexible packaging for travel and trial formats carries low capital barriers but high unit cost structures.
- Bulk Containers:Institutional and daycare channel supply requires specialized drum and intermediate bulk container logistics.
Bottles retain the bulk of installed capacity; refill packs are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors the Asia-Pacific demand concentration for baby cleaning products, where premium-formulation imports and domestic organic lines compete for shelf space in tier-one retail channels. Birth rate stabilization and disposable income expansion in urban clusters are reshaping purchase patterns across the region.
United States
Millennial parents in California and Texas metro areas prioritize dermatologist-tested wipes and concentrated refill formats. FDA cosmetic-claim oversight and EPA disinfectant registration requirements shape formulation pathways for surface sprays. Chicago and Atlanta retail corridors are expanding private-label baby wipe allocations at 30-40% price discounts to national brands.
Germany
Organic certification penetration reaches deepest in Bavaria and Baden-Württemberg, where ECHA REACH preservative restrictions have eliminated isothiazolinone biocides from mainstream formulations. EU Green Deal packaging directives accelerate fiber-based wipe transitions in Berlin and Hamburg. Refill station infrastructure in Munich and Cologne is displacing traditional canister formats.
China
SAMR labeling convergence and tightened GB standards for imported infant products create compliance moats for early-adopter brands. Yangtze River Delta manufacturing clusters around Shanghai and Suzhou supply both domestic consumption and Southeast Asian export demand. Tier-two city expansion in Chengdu and Xi'an is outpacing coastal saturation.
India
Ayurvedic ingredient narratives resonate in Maharashtra and Gujarat, where Himalaya Drug Company anchors plant-derived positioning. BIS quality certification requirements are tightening for imported wipes and liquid formulations. Bangalore and Hyderabad urban parent cohorts are trading up from commodity baby soaps to hypoallergenic certified lines.
Brazil
ANVISA pharmaceutical-grade registration requirements for disinfectant claims limit surface spray market entry to established multinationals. São Paulo and Rio de Janeiro dual-income households drive demand for time-efficient cleaning protocols. Northeast regional distributors are expanding reach into Recife and Salvador birth-rate concentration zones.
Global Baby Cleaning Products Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification depth and dermatological validation investment, creating a tiered structure where heritage trust and organic transparency command price premiums. The vendor base clusters around three strategic archetypes: legacy healthcare heritage brands, mass-market retail anchors with private-label defense capabilities, and plant-derived specialists leveraging traditional medicine narratives. Consolidation pressure concentrates among mid-tier regional players lacking certification infrastructure. Dominant competitive moves include portfolio diversification into refill-compatible formats and geographic licensing partnerships to bypass cross-jurisdiction registration complexity.
Within the heritage-trust tier, Johnson & Johnson and Procter & Gamble occupy positions sustained by first-time parent loyalty and mass retail distribution density. Himalaya Drug Company exemplifies the plant-derived specialist archetype, anchoring Ayurvedic ingredient credibility across South Asian and Middle Eastern consumer segments. These three entities represent the structural poles around which formulation chemistry, certification investment, and channel access strategies are organizing.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Procter & Gamble |
| Kimberly-Clark |
| Pigeon Corporation |
| Mayborn Group Limited |
| Nuby |
| Unilever |
| Kenvue |
| Himalaya Drug Company |
| Others |
Supply Flow & Price Mechanics
Palm-derived surfactant feedstock costs cascade through formulation tiers, compressing margins for mass-market producers while organic-certified lines absorb premiums through segregated supply chains and dermatologist validation investments.
Pricing Analysis
Certification-grade anchoring stratifies pricing across organic, hypoallergenic, and standard formulation tiers, with ECHA REACH-compliant preservative systems and FDA cosmetic-claim documentation commanding 25-40% uplifts over commodity alternatives. Price differentiation rests on dermatologist endorsement depth and supply chain transparency rather than raw performance metrics. Cost compression in standard wipes is intensifying because private-label substitution at 30-40% discounts erodes national brand positioning. First-time parents in Germany and California exhibit lowest price sensitivity, while mass-market buyers in Brazilian supermarkets and Indian tier-two cities prioritize unit economics.
Supply Chain Analysis
Skilled chemical formulation labor availability in Shanghai, Suzhou, and Yangtze River Delta manufacturing clusters anchors wet-wipe substrate production and liquid impregnation system capacity. Raw material dependencies draw from Malaysian and Indonesian palm oil derivatives, German specialty chemical preservatives, and Chinese nonwoven substrate engineering. Single-source vulnerability concentrates in isothiazolinone-free preservative alternatives following ECHA hazard reclassifications. Distribution runs through European supermarket refill station networks, North American mass retail chains, and direct-to-consumer subscription platforms capturing recurring revenue from time-constrained parents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into surfactant feedstock and preservative chemistry represents the decisive competitive lever as formulation flexibility becomes the primary constraint under tightening cross-jurisdiction disclosure mandates.
For Market Incumbents: Extend certification infrastructure into China SAMR pre-registration and EU Green Deal packaging compliance ahead of competitor lag, while consolidating wet-laid substrate capacity in Yangtze River Delta clusters to defend against private-label volume erosion. Anchor dermatologist endorsement networks in California and Texas metro corridors to sustain premium positioning against plant-derived specialist encroachment.
For New Entrants and Emerging Players: Launch via direct-to-consumer subscription channels targeting refill-compatible format adoption in Scandinavian and German urban markets, where sustainability-motivated parent cohorts trade single-use packaging for concentrated replenishment. Target Ayurvedic ingredient positioning in Maharashtra and Gujarat, where cultural familiarity with plant-derived safety narratives creates penetrable white space against heritage brand dominance.
For Investors and Strategic Acquirers: ECHA preservative restriction expansion announcements are the leading indicator that formulation chemistry capabilities will consolidate toward vertically integrated specialists with in-house toxicology validation. Long-term viability across the analysis window favors acquisition targets possessing dual FDA-ECHA regulatory dossiers and fiber-based wipe compostability certifications already in third-party validation pipelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Refill-Compatible Format Launch | EU Green Deal packaging directives in Berlin and Stockholm accelerate retailer shelf space reallocation toward concentrated replenishment systems. |
| Preservative System Overhaul | ECHA REACH isothiazolinone eliminations force wholesale biocide package replacements across contract manufacturers serving German and French retail banners. |
| Ayurvedic Ingredient Line Extension | Plant-derived positioning rooted in traditional medicine systems captures South Asian and Middle Eastern consumer trust premiums. |
| Direct-to-Consumer Channel Buildout | Subscription auto-replenishment platforms secure recurring revenue from Millennial and Gen Z parents prioritizing convenience. |
| China SAMR Pre-Registration Investment | Early compliance with tightened GB standards creates competitive moats for imported brands in Yangtze River Delta tier-one retail channels. |
Methodological Framework
Multi-period observation of birth rate trajectories in China, India, and Brazil, ECHA substance restriction expansion timelines, and retailer plastic-reduction commitment announcements anchored the trend analysis, supplemented by interviews with brand managers at heritage healthcare companies, category buyers at European supermarket chains, contract manufacturing executives in Shanghai and Suzhou, and regulatory affairs specialists navigating FDA cosmetic-claim distinctions. Secondary validation drew from SAMR labeling guidance documents, EU Green Deal packaging directive drafts, REACH substance restriction updates, and customs records tracking surfactant feedstock trade flows. Bottom-up segment sizing triangulated against top-down macroeconomic consumption models.
Segment-weighting across product type, formulation chemistry, application usage, and packaging format dimensions structured the analytical framework, with growth rate derivation reflecting category-specific volume elasticities to disposable income and regulatory compliance cost pass-through assumptions. Infant skin barrier pH specification adherence, compostability certification penetration curves, and multigenerational household cohabitation patterns in urban India and China informed projection dynamics throughout the forecast period.
Preservative reclassification acceleration, birth rate volatility in key emerging markets, and retailer sustainability commitment deadline compression are the dominant revision risks warranting forecast reassessment. Material deviation in ECHA hazard classification timelines, SAMR enforcement intensity, or EU Green Deal implementation pacing warrants pause and re-evaluation of capacity deployment and certification investment priorities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Safety Products
North America Baby Monitors Market
Baby Safety Products
Reusable Sanitary Pads Market
Baby Safety Products
Panty Liner Market
Baby Safety Products
Forward Facing Type Child Safety Seats Market
Baby Safety Products
Reusable/Washable Hygiene Products Market
Baby Safety Products
Booster Car Seats Market
Baby Safety Products
Baby Safety Products Market
Baby Safety Products
Global Feminine Protection Market
Baby Safety Products
Organic Sanitary Napkin Market
Baby Safety Products
Baby Safety Seats Market
Baby Safety Products
Baby Gate Market
Baby Safety Products
Biodegradable Sanitary Napkins Market
Baby Safety Products
BRICS Disposable Hygiene Products Market
Baby Safety Products
Japan Adult Diaper Market
Baby Safety Products
India Pant Type Adult Diaper Market
Baby Safety Products
North America Adult Diaper Market