
 United States Away from Home Tissue and Hygiene Market | 2026-2036
United States Away from Home Tissue and Hygiene Market Size, Share, and Industry Trends Forecast 2026-2036
United States Away from Home Tissue and Hygiene Market Analytics
The US Southeast is rewriting capacity dynamics for away-from-home tissue production as mills expand near pulp sources and major logistics corridors. Georgia-Pacific LLC leverages its integrated pulp-to-tissue infrastructure across the Carolinas and Georgia. Kimberly-Clark Corporation sustains R&D intensity in high-capacity dispensing systems for commercial restrooms. Essity AB anchors its North American position through specialized hygiene solutions for healthcare and hospitality channels.
Away from home tissue and hygiene products comprise absorbent paper goods manufactured from virgin wood pulp, recycled fiber, or alternative cellulose sources, typically featuring basis weights of 15–40 gsm and designed for single-use dispensing in commercial environments. These products serve sanitation, hand drying, and surface cleaning functions across high-traffic institutional settings. Paper towels command the largest volume share within product type segmentation, driven by foodservice hand-drying mandates and healthcare infection control protocols. Hotels and healthcare facilities represent the most margin-attractive end user segments due to contract bundling requirements and premium product specifications. Recycled paper and virgin fiber grades compete directly on total cost of ownership, with procurement committees weighing EPA purchasing guidelines against performance benchmarks.
EPA Safer Choice certification, FDA food contact material standards, and OSHA workplace sanitation requirements collectively shape product formulation, labeling, and facility compliance obligations for manufacturers and distributors. State-level extended producer responsibility frameworks in California and New York are beginning to influence fiber sourcing disclosures and post-consumer content minimums. Stakeholders must monitor evolving procurement standards from the General Services Administration and large healthcare systems, as these specifications cascade through distributor networks and determine competitive access.
Market Dynamics
Healthcare system consolidation across the US Southeast is compressing procurement cycles and forcing distributors to reconfigure contract structures around bundled hygiene solutions rather than discrete product categories.
Growth Catalysts
- EPA Safer Choice mandates:Federal purchasing guidelines now require certified products in GSA contracts, pulling institutional buyers toward compliant formulations and expanding addressable market for qualifying suppliers.
- Foodservice hand-drying protocols:State health departments in Florida and Georgia have adopted stricter post-wash sanitation standards, mandating single-use paper towels in commercial kitchens and driving volume requirements.
- Pulp-to-tissue corridor expansion:Integrated mill capacity additions near Savannah and Charleston are shortening supply chains for Southeast distributors and reducing landed costs for regional healthcare networks.
Market Restraints
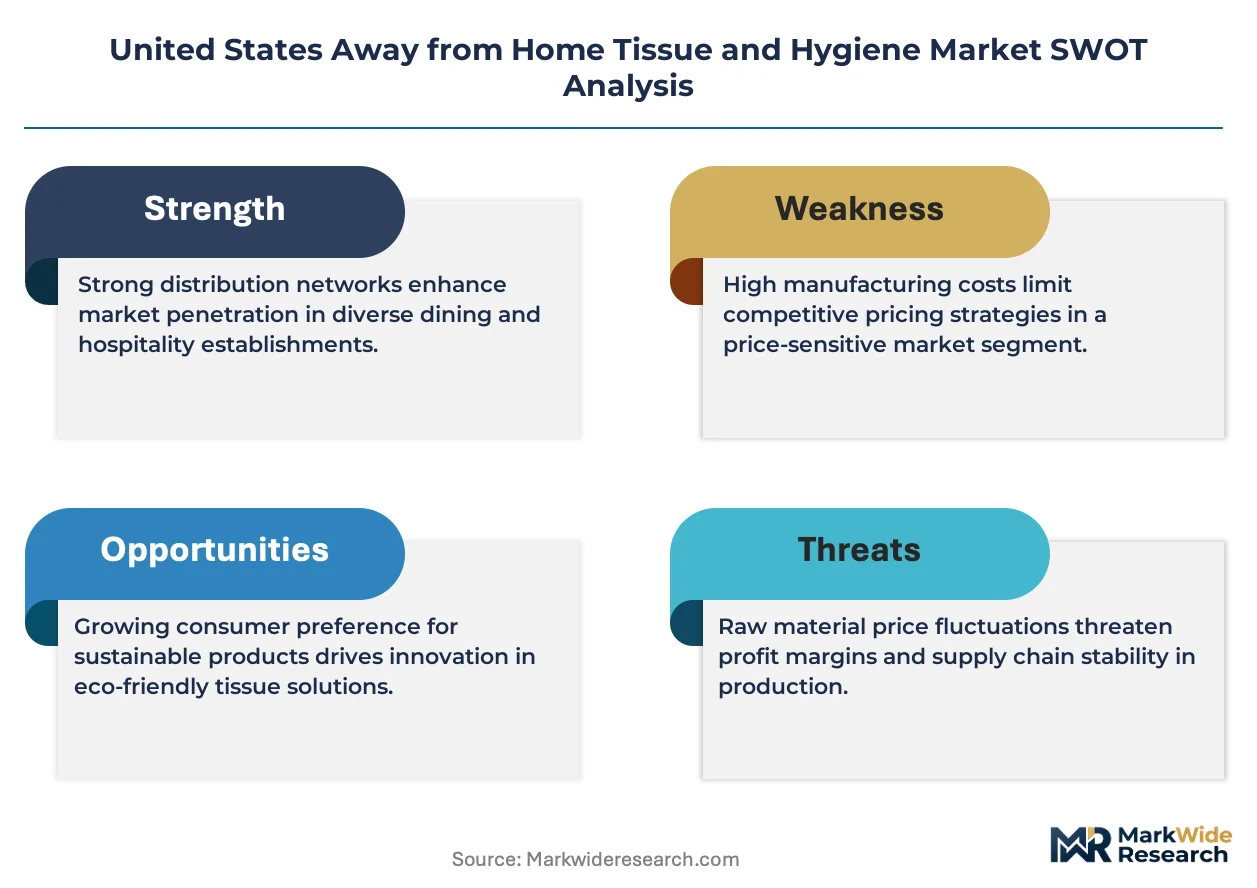
- Recycled fiber cost volatility:Post-consumer recovered paper pricing swings with municipal collection program funding, compressing margins for mid-tier products dependent on secondary fiber inputs.
- Southeast pulp concentration:Georgia-Pacific and International Paper control virgin softwood pulp supply across the Carolinas, creating bottleneck risk for independent tissue converters without long-term fiber agreements.
- Plastic dispenser compatibility:Legacy mounting hardware in older commercial restrooms limits adoption of sensor-activated systems without costly facility retrofitting.
Strategic Opportunities
- Extended producer responsibility frameworks:California and New York post-consumer content mandates are creating premium positioning for manufacturers with verified recycling streams and transparent fiber sourcing.
- Smart restroom integration:IoT-enabled dispensers that track consumption and predict refill cycles are penetrating upscale hospitality chains in Miami and Atlanta, opening recurring service revenue models.
- Rural healthcare satellite expansion:Federally qualified health centers in Alabama and Mississippi are adding outpatient facilities faster than national averages, generating distributed demand for specialized clinical hygiene products.
Industry Challenges
- OSHA bloodborne pathogen compliance:Healthcare facility audits are intensifying documentation requirements for infection control product efficacy, extending sales cycles and demanding dedicated clinical affairs staffing.
- Legacy distributor ERP integration:National procurement platforms used by major hospital systems require API connectivity that smaller regional distributors struggle to implement without third-party middleware investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Away from Home Tissue and Hygiene Market |
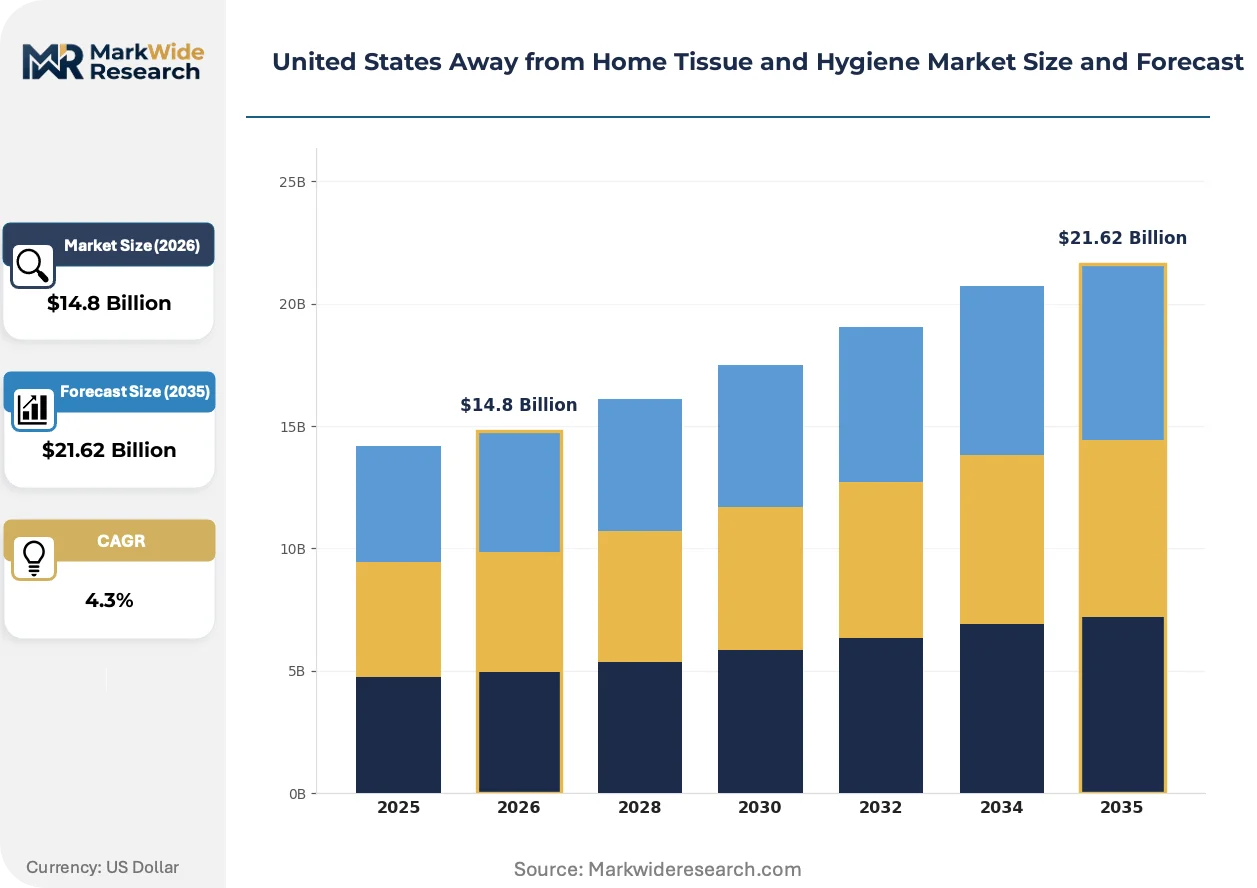
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $21.62 Billion |
| CAGR (2026 – 2036) | 4.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toilet Paper, Paper Towels, Facial Tissue, Napkins End User: Hotels, Restaurants, Schools, Healthcare Facilities Material: Recycled Paper, Virgin Fiber, Bamboo, Compressed Cellulose Distribution Channel: Wholesale, Direct Sales, E-commerce, Retail |
| Companies Covered | Essity AB, Cascades Inc., Kimberly-Clark Corporation, First Quality Enterprises Inc, Clearwater Paper Corporation, Georgia-Pacific LLC, Sofidel Group, Kruger Products, Procter & Gamble, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Away from Home Tissue and Hygiene Market Evolving Landscape
Material science advances and connected facility infrastructure are converging to redefine performance benchmarks and service delivery models across institutional hygiene procurement.
Dispensing systems are migrating from mechanical levers to touchless sensor activation. Healthcare facilities in Texas and Florida are retrofitting at accelerated pace following updated CDC environmental infection control guidance. The shift is compressing replacement cycles for installed base hardware and favoring suppliers with integrated electronics manufacturing capabilities over pure-play tissue converters.
State-level plastic reduction statutes are forcing formulation changes in packaging and dispenser housings. California's SB 54 implementation timeline requires 30% post-consumer recycled content in covered products by 2028, compelling manufacturers to requalify resin suppliers and redesign dispenser architectures. Hospitality chains with California properties are adopting these specifications chain-wide to simplify inventory management, spreading compliance costs across national footprints.
Contract structures are consolidating around total cost of ownership metrics rather than unit pricing. Large healthcare systems in North Carolina and Tennessee now evaluate dispenser reliability, installation labor, and maintenance burden alongside per-roll cost. Distributors are responding with field service teams dedicated to restroom infrastructure rather than pure product logistics, blurring traditional boundaries between hygiene supply and facilities management.
United States Away from Home Tissue and Hygiene Market Segmentation
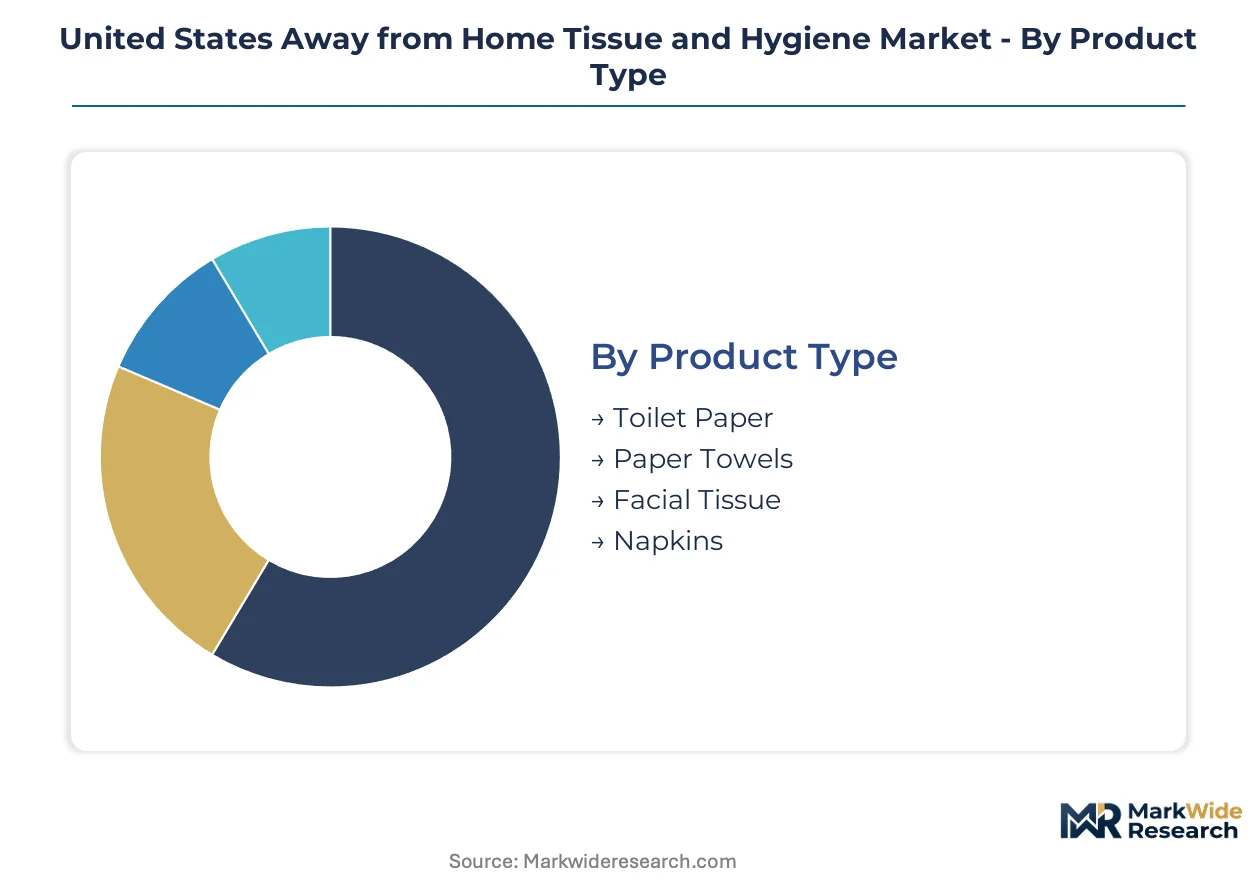
Segmentation in the United States Away from Home Tissue and Hygiene Market reveals divergent replacement cycles and margin structures across product categories. Procurement committees evaluate segments through total cost of ownership lenses rather than unit pricing alone. Understanding these distinctions enables suppliers to align capacity investments with the highest-velocity demand pools.
Product Type:
Paper towels rotate through institutional supply closets fastest due to foodservice hand-drying mandates and healthcare infection protocols, while facial tissue sits at the slowest turnover extreme in back-office settings.
- Paper Towels:Absorbent sheets manufactured from 18–35 gsm wood pulp or recycled fiber, engineered for single-pull dispensing in lever or sensor-activated systems. Demand concentrates in Florida and Georgia commercial kitchens where state health departments enforce post-wash sanitation standards, compressing replacement cycles to weekly intervals in high-traffic locations.
- Toilet Paper:Wound rolls of 15–25 gsm tissue designed for high-capacity commercial dispensers, with jumbo formats reducing janitorial labor. Healthcare facilities across the Carolinas specify clinical-grade variants with enhanced dispersibility for plumbing system compatibility, driving premium positioning in hospital contract bundles.
- Facial Tissue:Soft-ply sheets for guest amenities and administrative spaces, typically 20–24 gsm with lotion additives. Flat demand in corporate settings with quarterly replenishment cycles.
- Napkins:Dinner and beverage formats for foodservice table settings, ranging from 1-ply dispenser to 2–3 ply premium. Seasonal volume spikes align with tourism patterns in Southeast hospitality corridors.
Paper towels anchor the volume base while facial tissue gains share at the steepest rate through upscale hotel amenity upgrades.
End User:
Margin structures diverge sharply across end user categories, with contract bundling requirements and compliance documentation intensity determining supplier profitability.
- Healthcare Facilities:Hospitals, outpatient clinics, and long-term care operations subject to OSHA bloodborne pathogen protocols and CDC environmental infection control guidance. EPA Safer Choice certification now gates GSA contract eligibility, forcing formulation standardization across Southeast health system procurement platforms.
- Hotels:Full-service and limited-service properties with brand-mandated amenity specifications and guest-visible dispenser aesthetics. Miami and Atlanta upscale chains are retrofitting sensor-activated systems fastest, opening recurring service revenue models.
- Restaurants:Quick-service and full-service operations with high-velocity hand-drying demand and health department inspection exposure. Florida and Georgia state mandates on single-use towels drive volume concentration.
- Schools:K–12 and higher education facilities with seasonal demand patterns and constrained maintenance budgets. Procurement runs through cooperative purchasing agreements with extended payment terms.
Healthcare anchors the volume base while hotels gain share at the steepest rate through smart restroom integration investments.
Material:
Raw material selection determines compliance positioning and supply chain resilience against pulp price volatility and state-level content mandates.
- Virgin Fiber:Softwood pulp from Southeastern timberlands delivering superior tensile strength and absorbency for clinical and premium hospitality applications. Georgia-Pacific and International Paper control Carolinas pulp supply, creating sourcing concentration risk for independent converters without long-term fiber agreements.
- Recycled Paper:Post-consumer recovered fiber processed to EPA Comprehensive Procurement Guidelines standards. California and New York extended producer responsibility frameworks mandate minimum post-consumer content, spreading compliance specifications to national hospitality chains.
- Bamboo:Alternative cellulose source with rapid regrowth cycles and reduced water intensity. Niche positioning in sustainability-focused boutique hotel segments with limited scale.
- Compressed Cellulose:High-density formats for compact dispensing systems in space-constrained restrooms. Emerging application in urban healthcare satellite facilities.
Virgin fiber anchors the volume base while recycled paper gains share at the steepest rate under state-level plastic reduction and content disclosure mandates.
Distribution Channel:
Channel selection reflects customer scale, technical service requirements, and integration burden with procurement platform connectivity.
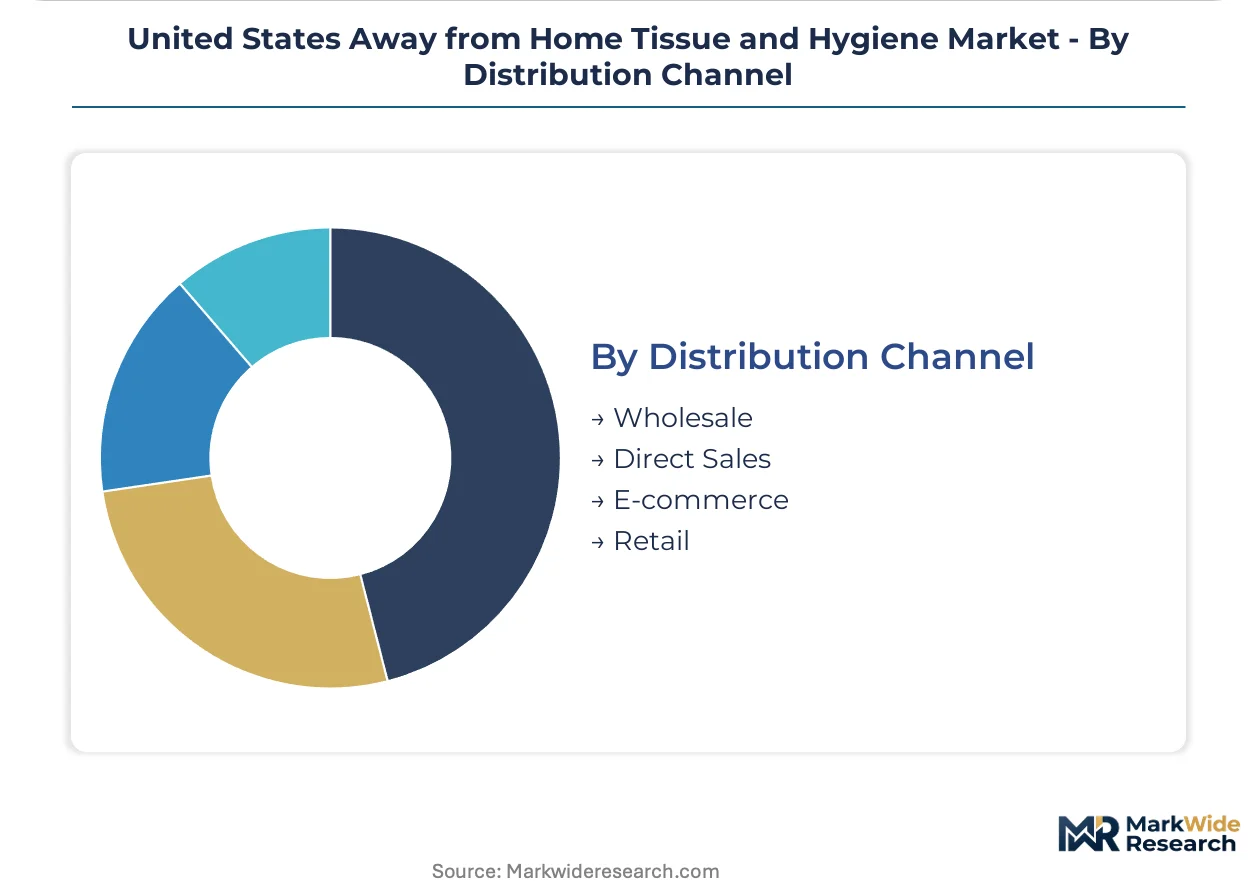
- Wholesale:Broadline distributors serving mid-market restaurants and schools with consolidated delivery schedules and inventory financing. Southeast regional players face ERP integration pressure from healthcare system consolidation.
- Direct Sales:Manufacturer-led account teams for large healthcare systems and national hospitality chains with customized contract structures and field service commitments. North Carolina and Tennessee health networks now evaluate dispenser reliability alongside per-roll cost.
- E-commerce:Digital procurement platforms penetrating small independent restaurants and rural healthcare satellites in Alabama and Mississippi. Growth constrained by bulk shipping economics.
- Retail:Big-box and specialty trade channels for small commercial operators without distributor relationships. Limited to emergency replenishment and startup provisioning.
Wholesale anchors the volume base while direct sales gains share at the steepest rate as healthcare consolidation compresses procurement cycles around bundled hygiene solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Safer Choice mandates and state-level plastic reduction statutes are redrawing procurement boundaries across US sub-regions. Southeast pulp-to-tissue corridors shorten supply chains while California and New York extended producer responsibility frameworks cascade compliance costs nationwide.
Southeast
Healthcare system consolidation in North Carolina and Tennessee compresses procurement cycles around bundled hygiene solutions. Florida and Georgia health departments enforce stricter post-wash sanitation standards mandating single-use paper towels in commercial kitchens. Integrated mill capacity near Savannah and Charleston reduces landed costs for regional healthcare networks.
California
SB 54 implementation requires 30% post-consumer recycled content in covered products by 2028, compelling manufacturers to requalify resin suppliers. Los Angeles and San Francisco hospitality chains adopt these specifications chain-wide to simplify inventory management. The state's extended producer responsibility framework spreads compliance specifications to national hospitality footprints.
New York
Post-consumer content mandates and fiber sourcing disclosure requirements are reshaping procurement standards for healthcare systems in New York City and Albany. The state's plastic reduction statutes force formulation changes in packaging and dispenser housings. Buffalo and Rochester distributors face ERP integration pressure from hospital system consolidation.
Texas
Houston and Dallas healthcare facilities retrofit touchless sensor-activated dispensing systems at accelerated pace following updated CDC environmental infection control guidance. The state's oilfield services corridor generates demand for industrial hygiene products in remote workforce housing. San Antonio federally qualified health centers add outpatient facilities faster than national averages.
Midwest
Chicago and Detroit school districts run procurement through cooperative purchasing agreements with extended payment terms constraining distributor cash cycles. Ohio and Michigan manufacturing belt facilities maintain flat demand for back-office facial tissue with quarterly replenishment cycles. Cleveland clinic networks evaluate dispenser reliability alongside per-roll cost in total cost of ownership frameworks.
United States Away from Home Tissue and Hygiene Market Competitive Landscape
Capability concentration sits with integrated pulp-to-tissue operators; scale advantage sits with diversified hygiene conglomerates. The market structures around three tiers: virgin fiber controllers with captive timberland, recycled fiber specialists with municipal collection partnerships, and dispenser-integrated solution providers with electronics manufacturing capabilities. Strategic moves cluster on backward integration into pulp supply and forward integration into smart restroom service contracts.
Within the integrated infrastructure tier, Georgia-Pacific LLC and Kimberly-Clark Corporation exemplify scale-driven positioning through southeastern pulp corridor dominance. Essity AB occupies a position as the specialized hygiene solutions anchor for healthcare and hospitality channels. Among North American converters, Cascades Inc. and Clearwater Paper Corporation represent recycled fiber specialization archetypes with exposure to post-consumer recovered paper volatility.
| Leading Market Players |
|---|
| Essity AB |
| Cascades Inc. |
| Kimberly-Clark Corporation |
| First Quality Enterprises Inc |
| Clearwater Paper Corporation |
| Georgia-Pacific LLC |
| Sofidel Group |
| Kruger Products |
| Procter & Gamble |
| Others |
Value Network & Pricing Analysis
I-95 corridor freight dynamics compress landed costs for Southeast distributors while amplifying price spreads between virgin fiber and recycled grades across regional healthcare networks.
Pricing Analysis
Price spreads between Carolinas-sourced virgin fiber and post-consumer recycled grades widen during municipal collection funding cycles. Pricing stratifies across premium clinical specifications, standard commercial bundles, and economy foodservice tiers. Cost compression in recycled mid-tier products intensifies because post-consumer recovered paper swings with collection program budgets. Quick-service restaurants in Florida and Georgia exhibit highest price sensitivity; integrated health systems in North Carolina and Tennessee prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Single-source vulnerability around Georgia-Pacific and International Paper softwood pulp control across the Carolinas dominates supply risk for independent converters. Raw material sourcing draws from Southeastern timberlands, post-consumer municipal collection streams, and imported northern bleached softwood kraft. Pulp-to-tissue integration near Savannah and Charleston shortens lead times for regional distributors. Distribution runs through broadline wholesalers serving mid-market accounts and direct sales teams for consolidated health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart restroom integration in upscale hospitality chains signals early-cycle expansion, with IoT-enabled dispensing systems penetrating faster than historical hardware replacement cycles.
For Market Incumbents: Entrench position through captive pulp supply agreements across the Carolinas and accelerated sensor-activated dispenser manufacturing. Emerging recycled fiber specialists threaten margin structures in mid-tier segments. Certification investment in EPA Safer Choice compliance gates GSA contract eligibility and protects premium positioning.
For New Entrants and Emerging Players: Rural healthcare satellites in Alabama and Mississippi represent the most penetrable entry point, with federally qualified health centers adding outpatient capacity faster than national benchmarks. Smart restroom service contracts for Miami and Atlanta upscale hotels offer recurring revenue models distinct from transactional tissue supply. Target e-commerce procurement platforms serving small independent restaurants with bulk-shipping optimization.
For Investors and Strategic Acquirers: Recycled fiber specialists with verified municipal collection partnerships and transparent sourcing disclosure capabilities present acquisition targets with regulatory tailwinds. Long-term viability centers on compliance positioning under extended producer responsibility frameworks spreading from California and New York. Watch for inflection when health systems mandate API-enabled procurement platform connectivity as a contract prerequisite.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Captive softwood fiber from Southeastern timberlands secures cost position against Georgia-Pacific concentration. |
| Smart Restroom Service Contract Expansion | IoT-enabled dispenser networks in Miami and Atlanta hotels generate recurring revenue beyond product sales. |
| EPA Safer Choice Certification Investment | Federal purchasing guidelines now require compliant formulations for GSA contract eligibility. |
| API Procurement Platform Integration | North Carolina and Tennessee health systems demand connectivity for distributor contract participation. |
| Post-Consumer Content Verification Systems | California SB 54 mandates force requalification of resin suppliers and fiber sourcing transparency. |
Research Methodology
Cross-validation between distributor procurement data and health system contract disclosures anchors the qualitative findings. Primary interviews with tissue mill operations directors, GPO contracts managers, hospitality procurement leads, and EPA compliance officers combined with secondary validation from customs records, SEC 10-K filings, and state environmental agency rulemaking dockets. Bottom-up capacity modeling and top-down demand estimation triangulate volume figures across product categories.
Calibration against historical pulp price cycles and health system consolidation timelines shapes the analytical framework. Segmentation dimensions modeled include product type, end-user vertical, material grade, and distribution channel complexity. CAGRs derive from trend extrapolation of replacement cycle compression and smart restroom penetration curves. Forecast inputs incorporate EPA Safer Choice adoption rates and extended producer responsibility implementation timelines.
Macroeconomic conditions sit as an overlay; deviation in construction spending for hospitality and healthcare facilities would shift the trajectory. Forecasts reflect assumptions about pulp price stability and regulatory enforcement intensity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Safety Products
Baby Safety Products Market
Baby Safety Products
India Pant Type Adult Diaper Market
Baby Safety Products
Forward Facing Type Child Safety Seats Market
Baby Safety Products
Panty Liner Market
Baby Safety Products
Biodegradable Sanitary Napkins Market
Baby Safety Products
Reusable/Washable Hygiene Products Market
Baby Safety Products
Organic Sanitary Napkin Market
Baby Safety Products
North America Baby Monitors Market
Baby Safety Products
Booster Car Seats Market
Baby Safety Products
Baby Gate Market
Baby Safety Products
BRICS Disposable Hygiene Products Market
Baby Safety Products
Reusable Sanitary Pads Market
Baby Safety Products
Global Feminine Protection Market
Baby Safety Products
Global Baby Cleaning Products Market
Baby Safety Products
Japan Adult Diaper Market
Baby Safety Products
Baby Safety Seats Market