
 North America Baby Monitors Market | 2026-2036
North America Baby Monitors Market Size, Share, and Industry Trends Forecast 2026-2036
North America Baby Monitors Market Analytics
Multi-source component procurement is consolidating as manufacturers reduce supplier fragmentation for camera sensors and RF modules. VTech Holdings Limited leverages vertically integrated electronics manufacturing to sustain cost advantages across mid-tier audio and video units. Samsung Electronics Co. Ltd anchors its position through in-house semiconductor supply for high-resolution night vision chipsets. Koninklijke Philips NV differentiates via clinical-grade sensor calibration originally developed for its hospital equipment division.
Baby monitors are electronic surveillance devices combining audio receivers, video cameras, and wireless transceivers operating on DECT, Wi-Fi, or Bluetooth protocols to transmit infant status data to parent units or smartphones. These systems employ CMOS image sensors, MEMS microphones, and cloud-connected analytics to enable real-time respiratory pattern tracking and environmental condition alerts. Smart monitors with movement detection and temperature monitoring command premium positioning as parents prioritize biometric feedback over basic audio functionality. Wi-Fi connectivity segments face margin compression from subscription-dependent cloud storage models, while DECT-based systems retain stable profitability through hardware-only sales to privacy-conscious buyers.
FCC Part 15 emissions standards govern wireless transmission protocols, and CPSC safety regulations mandate cord-length limitations and battery compartment integrity for nursery deployment. Health Canada adds IC certification requirements that delay cross-border product launches by three to six months for unapproved RF configurations. Stakeholders must weigh cloud dependency against emerging state-level data privacy statutes affecting video stream storage and third-party access permissions.
Market Dynamics
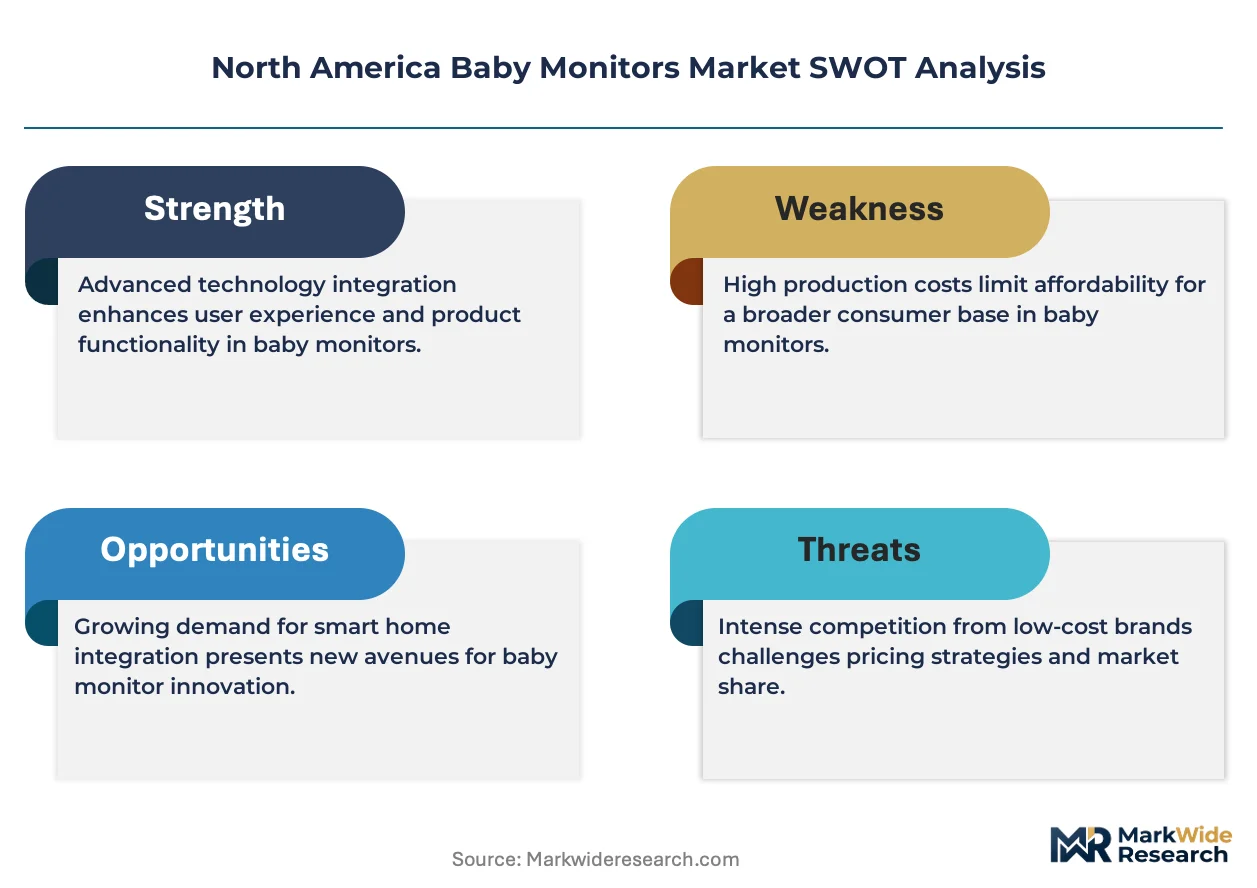
Smart sensor convergence with respiratory pattern tracking is compressing the traditional audio-only segment as parents demand biometric feedback loops. FCC Part 15 certification requirements for radio frequency emissions now gate market entry, favoring manufacturers with established RF engineering capabilities over hardware-only assemblers.
Growth Catalysts
- Dual-income household density:Suburban Texas and Ontario corridors generate concentrated demand for movement-detection monitors. Parents in these clusters prioritize real-time infant status visibility during work hours.
- FCC Part 15 framework:Standardized RF emissions testing reduces certification uncertainty for Wi-Fi and DECT protocols. Device manufacturers benefit from predictable compliance pathways.
- MEMS microphone miniaturization:Advanced acoustic sensors enable room-temperature monitoring through sound wave analysis. This secondary data stream eliminates dedicated hardware costs.
Market Restraints
- CMOS image sensor supply concentration:Camera module procurement depends on East Asian fab capacity. Regional logistics disruptions propagate directly to North American assembly lines.
- Cloud storage subscription fatigue:Recurring fees for video archive access encounter resistance from privacy-conscious buyers. DECT-based hardware-only alternatives capture this defecting demand.
- Health Canada IC certification lag:Cross-border product launches face three-to-six-month delays for unapproved RF configurations. Revenue recognition timing suffers versus US-first strategies.
Strategic Opportunities
- Pediatric sleep clinic partnerships:Clinical-grade calibration protocols from hospital equipment divisions transfer to consumer monitors. Medical credibility differentiation commands shelf placement premiums.
- State-level data privacy statutes:Emerging video stream storage regulations create compliance service revenue. Third-party access permission management becomes a monetizable feature layer.
- Bluetooth Low Energy mesh networks:Multi-room coverage without Wi-Fi dependency addresses cybersecurity concerns. Apartment-dwelling parents in dense urban corridors adopt this architecture.
Industry Challenges
- Firmware security patching cadence:Connected device vulnerability disclosure timelines compress. Engineering teams must maintain OTA update infrastructure across decade-long product lifecycles.
- Legacy DECT inventory rationalization:Wi-Fi-enabled unit proliferation strand mid-tier audio-only channel stock. Retailer markdown pressure transmits upstream to contract manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Baby Monitors Market |
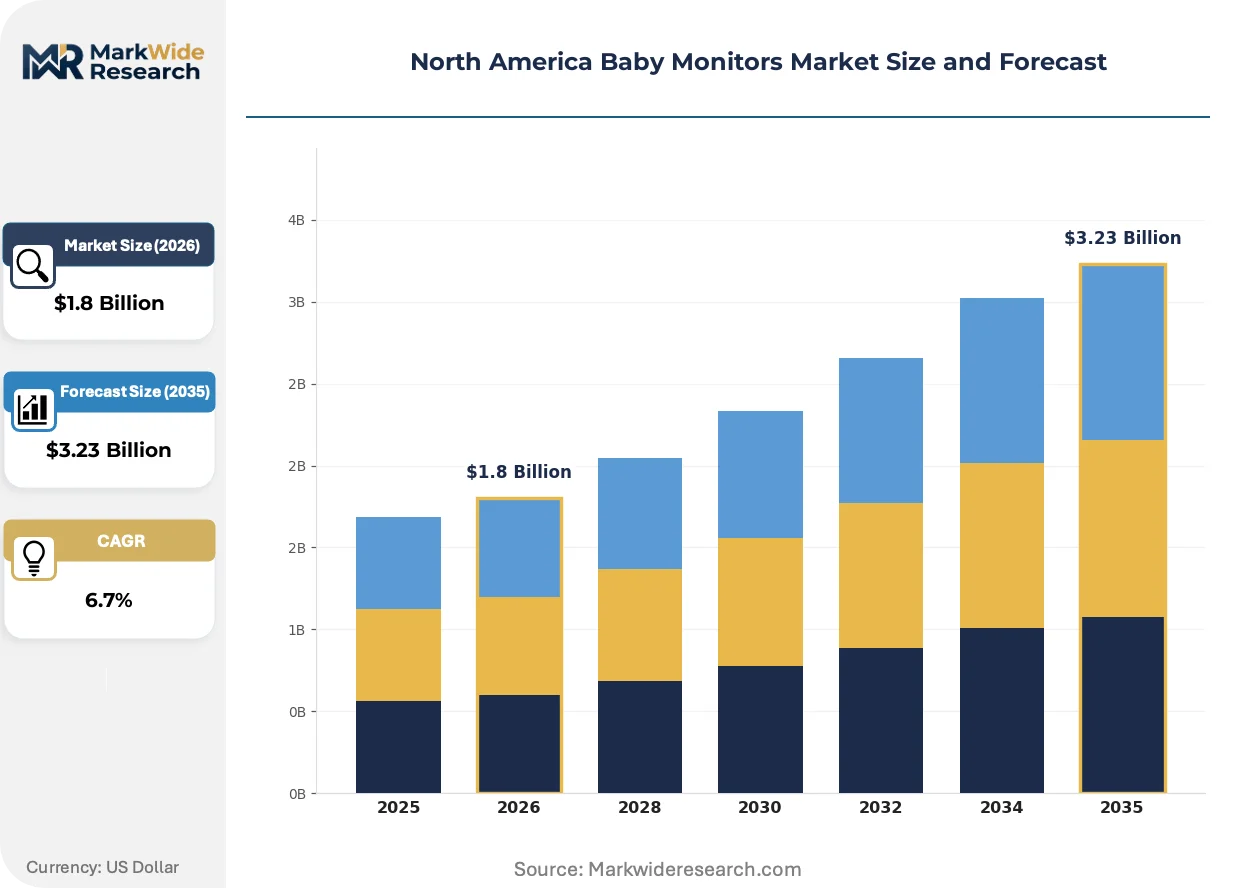
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Audio Monitors, Video Monitors, Smart Monitors, Wearable Monitors Connectivity: Wi-Fi, Bluetooth, Wired, DECT End User: Parents, Caregivers, Hospitals, Childcare Centers Feature: Temperature Monitoring, Night Vision, Two-Way Communication, Movement Detection |
| Companies Covered | Summer Infant, VTech Holdings Limited, Samsung Electronics Co. Ltd, Koninklijke Philips NV, Dorel Industries, Inc., Angelcare Monitors Inc., Motorola Solutions Inc, Lorex Technology Inc., Arlo Technologies Inc, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Baby Monitors Market Evolving Landscape
Respiratory pattern tracking algorithms are migrating from cloud-dependent processing to edge-computing architectures. This shift reduces latency and addresses parental data sovereignty concerns.
Sensor fusion is unifying accelerometer, temperature, and acoustic inputs into single-chip biometric inference engines. Premium nursery technology buyers in California and New York metro corridors adopt these consolidated units fastest. The technology is unifying previously separate hardware categories into integrated monitoring platforms, compressing component count and assembly complexity.
FCC Part 15 emissions standards now explicitly cover 6 GHz Wi-Fi 6E protocols for baby monitor applications. Manufacturers must retest existing certifications or restrict product configurations to 2.4 GHz and 5 GHz bands. High-resolution night vision chipset suppliers face the steepest compliance recertification burdens.
Direct-to-consumer channel expansion is displacing big-box nursery aisle dependence. Specialty parenting boutiques and telehealth-integrated subscription services capture first-time parents seeking personalized onboarding. This channel rotation concentrates in Ontario and British Columbia where digital-native parenting communities cluster.
North America Baby Monitors Market Segmentation
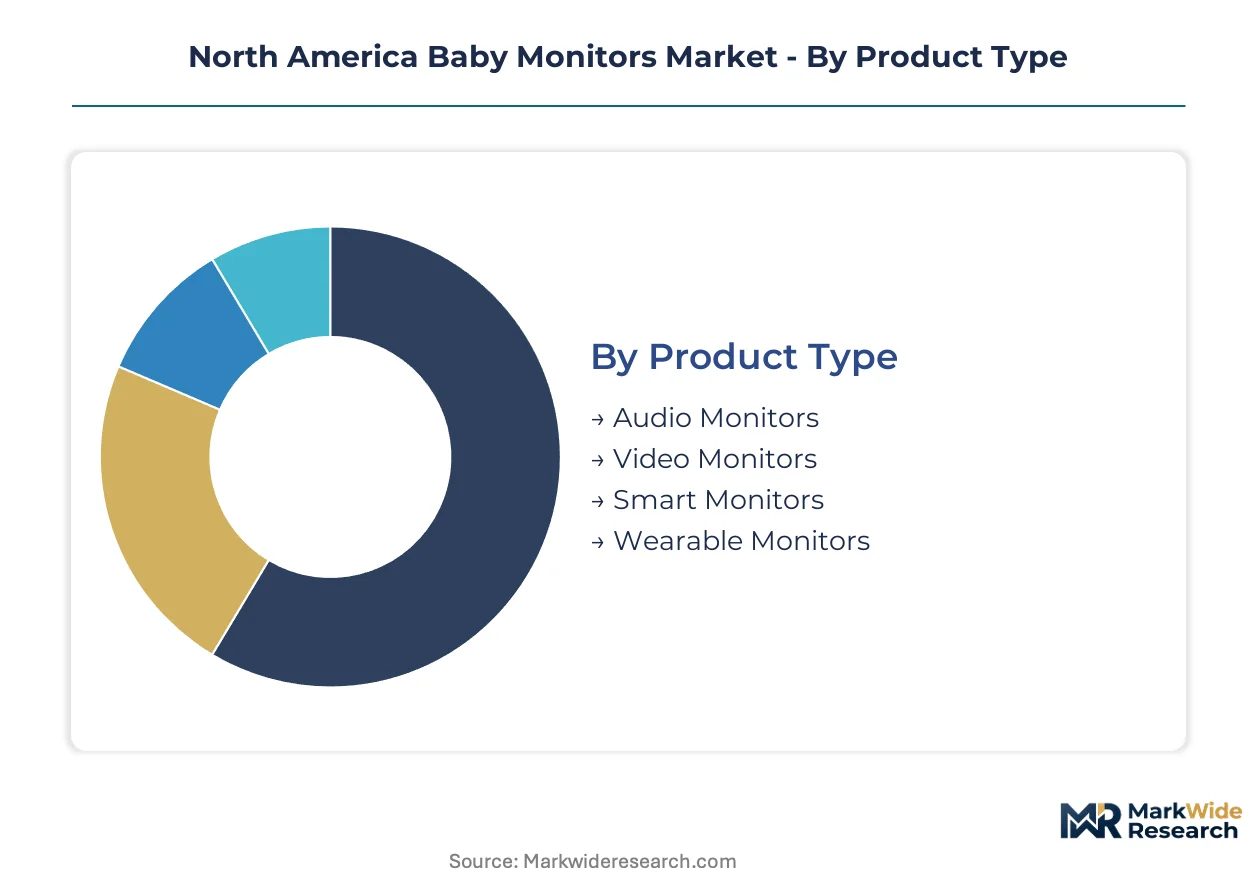
Product architecture in the North America Baby Monitors Market stratifies sharply between legacy hardware and biometric-integrated platforms. FCC Part 15 certification requirements and parental privacy preferences fragment purchasing decisions across connectivity protocols and sensor capabilities.
Product Type:
Technology sophistication defines tier boundaries, with CMOS sensor density and edge-processing capability separating price bands.
- Smart Monitors:Edge-computing architectures process respiratory patterns locally without cloud dependency. California and New York metro corridors concentrate demand as dual-income households prioritize biometric feedback loops during work hours.
- Video Monitors:CMOS image sensors with MEMS microphones transmit real-time audiovisual streams to parent units or smartphones. Suburban Texas adoption clusters favor these units for nursery visibility without subscription fees.
- Audio Monitors:DECT-based transmission delivers hardware-only sales to privacy-conscious buyers seeking simplicity.
- Wearable Monitors:Accelerometer-integrated garments track infant movement through skin-contact sensors.
Mature deployment sits with Audio Monitors. Newer deployment is concentrated in Smart Monitors.
Connectivity:
Transmission protocol selection directly determines certification pathway complexity and recurring revenue potential.
- DECT:Dedicated 1.9 GHz spectrum avoids Wi-Fi congestion and eliminates internet dependency. Privacy-focused parents in Ontario corridors defect from cloud-tethered alternatives to capture hardware-only ownership models.
- Wi-Fi:2.4 GHz and 5 GHz bands enable smartphone integration and remote access from workplace locations. FCC Part 15 emissions testing now extends to 6 GHz Wi-Fi 6E protocols, forcing recertification for chipset suppliers.
- Bluetooth:Low Energy mesh architectures support multi-room coverage without router dependency.
- Wired:Physical coaxial or Ethernet connections eliminate RF emissions concerns entirely.
Volume leadership belongs to DECT. Steepest expansion trajectory is concentrated in Wi-Fi.
End User:
Purchasing authority and reimbursement pathways segment demand across consumer and institutional channels.
- Parents:First-time buyers in dual-income households drive premium feature adoption. California and New York metro corridors concentrate spending on night vision and two-way communication capabilities.
- Hospitals:Clinical-grade sensor calibration requirements from neonatal intensive care units transfer to post-discharge monitoring protocols.
- Caregivers:Grandparent and extended-family purchasers prioritize simplified interface design over advanced biometric tracking.
- Childcare Centers:Multi-infant scalability requirements favor wired or DECT systems with centralized monitoring stations.
Revenue concentration sits with Parents. Emerging deployment is concentrated in Hospitals.
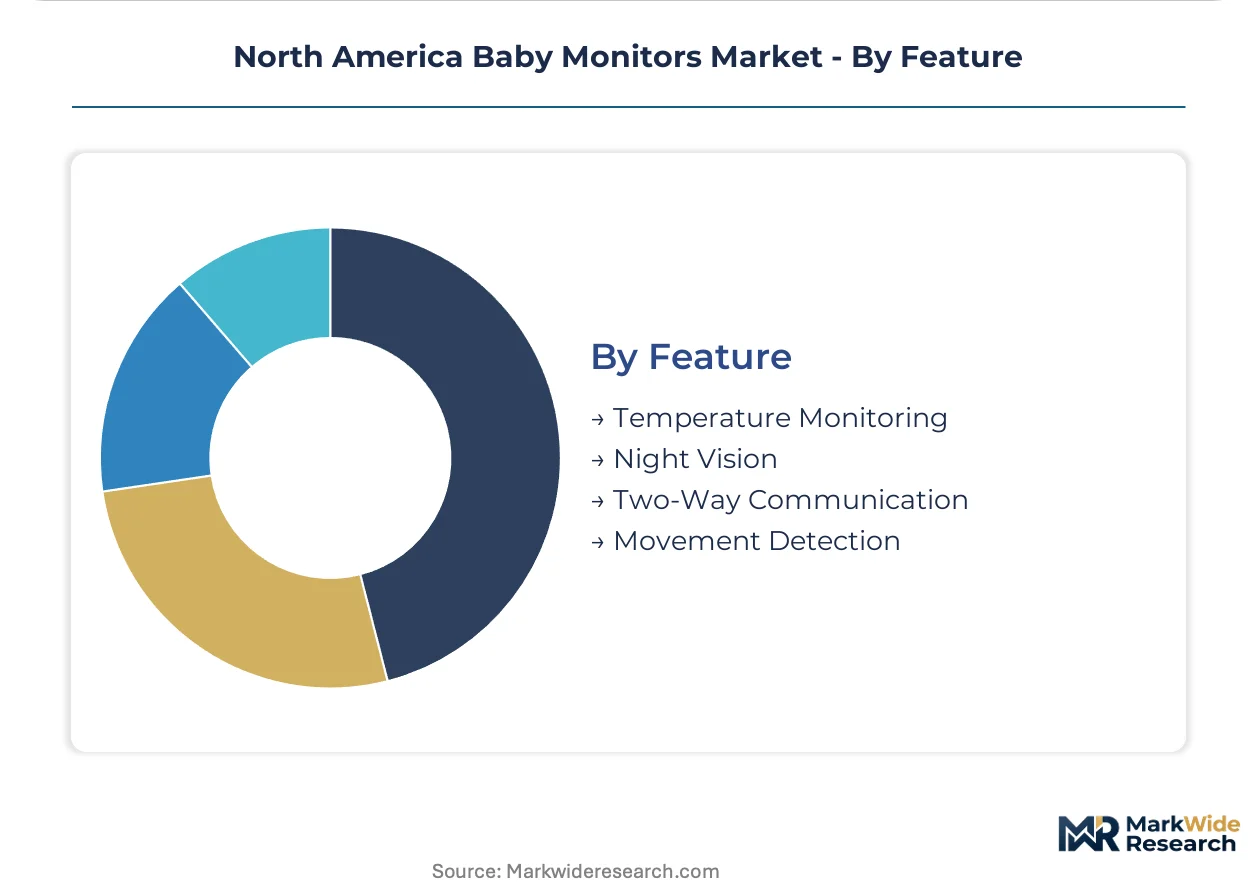
Feature:
Sensor fusion capabilities compress standalone hardware categories into integrated monitoring platforms.
- Movement Detection:Accelerometer-based algorithms trigger alerts for breathing irregularities or rollover events. Suburban Texas and Ontario corridors generate concentrated demand as working parents seek real-time infant status visibility.
- Night Vision:Infrared LED arrays with high-resolution CMOS sensors enable low-light nursery monitoring. FCC Part 15 recertification burdens fall heaviest on chipset suppliers supporting 6 GHz Wi-Fi 6E integration.
- Temperature Monitoring:MEMS microphone miniaturization enables acoustic room-temperature inference without dedicated sensors.
- Two-Way Communication:Full-duplex audio channels allow parental voice transmission to soothe infants remotely.
Feature bundling sits with Movement Detection. Discrete adoption is concentrated in Night Vision.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dual-income household density in suburban Texas and Ontario corridors concentrates demand for movement-detection monitors. FCC Part 15 certification requirements shape product entry pathways across the continent. Health Canada IC regulations create cross-border timing differentials for RF configurations.
United States
California and New York metro corridors drive premium video and Wi-Fi-enabled unit adoption. FCC Part 15 emissions standards govern 2.4 GHz, 5 GHz, and newly extended 6 GHz Wi-Fi 6E protocols for nursery applications. Greater Boston clusters concentrate pediatric sleep clinic partnerships that transfer clinical-grade calibration protocols to consumer monitors.
Canada
Ontario suburban corridors generate concentrated demand for smart monitors with biometric feedback loops. Health Canada mandates IC certification requirements that delay product launches by three to six months for unapproved RF configurations. British Columbia digital-native parenting communities cluster around direct-to-consumer specialty boutiques and telehealth-integrated subscription services.
Mexico
Mexico City Metro anchors demand for mid-tier audio and video units among dual-income professional households. The country's national telecommunications regulator oversees spectrum allocation for DECT and Wi-Fi nursery devices. Nuevo León industrial corridors host contract manufacturing facilities serving North American assembly requirements.
North America Baby Monitors Market Competitive Landscape
Vertical integration dominates the current landscape as manufacturers reduce supplier fragmentation for camera sensors and RF modules. The vendor base stratifies between consolidated electronics conglomerates and specialized nursery technology firms. Three archetypes occupy distinct positions: semiconductor-integrated conglomerates, clinical-calibration specialists, and vertically integrated mid-tier producers. M&A activity and in-house component production represent the dominant competitive moves reshaping procurement patterns.
Within the semiconductor-integrated tier, Samsung Electronics Co. Ltd exemplifies captive supply chain advantages for high-resolution imaging chipsets. VTech Holdings Limited and Koninklijke Philips NV occupy positions reflecting divergent strategic foundations—VTech through electronics manufacturing scale, Philips through hospital equipment calibration heritage. These three anchors illustrate how RF engineering capabilities and clinical credibility serve as alternative pathways to shelf placement premiums.
| Leading Market Players |
|---|
| Summer Infant |
| VTech Holdings Limited |
| Samsung Electronics Co. Ltd |
| Koninklijke Philips NV |
| Dorel Industries, Inc. |
| Angelcare Monitors Inc. |
| Motorola Solutions Inc |
| Lorex Technology Inc. |
| Arlo Technologies Inc |
| Others |
Value Network & Pricing Analysis
RF engineering talent pools in Greater Shenzhen and Hsinchu anchor labor-cost differentials that widen pricing-tier spreads between premium Wi-Fi 6E units and economy DECT alternatives. CMOS sensor procurement concentration in East Asian fabs transmits directly to landed cost structures across California and Ontario distribution channels.
Pricing Analysis
Warranty and cloud-storage bundling separates premium smart monitors from hardware-only DECT alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects FCC Part 15 certification grade and CMOS sensor resolution. Pricing pressure stems from subscription-fatigue defection toward hardware-only ownership models. Privacy-conscious buyers in suburban Texas exhibit highest price sensitivity; dual-income households in New York metro corridors show lowest.
Supply Chain Analysis
Assembly workforce availability in Nuevo León and Guangdong provinces shapes contract manufacturer allocation decisions. Camera module production draws from Taiwan, South Korea, and Japan; MEMS microphone supply rests on Chinese and Malaysian facilities. Single-source vulnerability concentrates in high-resolution night vision chipset suppliers. Distribution runs through big-box nursery aisles, direct-to-consumer specialty boutiques, and telehealth-integrated subscription services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CMOS image sensor fab capacity constraints prop pricing power for integrated manufacturers with captive semiconductor supply. Foundry slot scarcity limits volume scaling for hardware-only assemblers.
For Market Incumbents: Hedge against cloud-subscription fatigue by accelerating DECT product line refreshes with biometric sensor fusion. Defensive moves center on backward integration into RF module production and securing Health Canada IC certification ahead of US-first launches. Threat vectors include Bluetooth Low Energy mesh entrants targeting cybersecurity-conscious apartment dwellers. For New Entrants and Emerging Players: Grandparent purchasers represent an underserved buyer archetype with simplified-interface preferences and low price sensitivity. White-space targets cluster in childcare center multi-infant scalability and pediatric sleep clinic partnership channels. Go-to-market angle emphasizes clinical-grade calibration heritage transferred from hospital equipment divisions. For Investors and Strategic Acquirers: Re-rating potential sits with clinical-calibration specialists given FDA-cleared respiratory pattern tracking catalysts. Long-term viability favors targets with edge-computing architectures reducing cloud dependency. Acquisition target archetype: vertically integrated mid-tier producers with Health Canada pre-certification. Signal to watch: state-level data privacy statute passage triggering compliance-service monetization.| Strategic Initiative | Industry Significance |
|---|---|
| FCC Part 15 Recertification Investment | 6 GHz Wi-Fi 6E protocol approval gates premium product launches in California corridors. |
| Edge-Computing Architecture Migration | Local respiratory pattern processing addresses parental data sovereignty concerns in Ontario. |
| Pediatric Sleep Clinic Partnership | Clinical credibility differentiation commands shelf placement premiums in Greater Boston clusters. |
| Bluetooth Low Energy Mesh Development | Multi-room coverage without router dependency targets cybersecurity-conscious urban parents. |
| Direct-to-Consumer Channel Expansion | Specialty parenting boutiques capture first-time buyers in British Columbia digital-native communities. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs. Primary interviews with product managers at RF module suppliers, FCC certification consultants, nursery technology retailers, and biomedical engineers at pediatric sleep clinics combined with secondary validation. FCC equipment authorization databases, Health Canada IC certification records, CPSC safety recall notices, and import manifests provided demand-side triangulation. Bottom-up unit shipment estimates and top-down consumer spending analysis were reconciled.
Granularity-level modeling captured product type, connectivity protocol, end-user channel, and feature bundle dimensions at the metropolitan statistical area level. CAGRs were derived from regression analysis against dual-income household density and birth rate projections. Forecast inputs included CMOS sensor fab capacity expansion schedules and FCC Part 15 ruleset evolution timelines across the analysis window.
Revisions become necessary when Health Canada IC certification delays extend beyond six months or when state-level data privacy statutes mandate video stream storage localization. Forecasts reflect assumptions about continued DECT spectrum allocation stability and MEMS microphone cost curves. Material deviation in foundry capacity utilization or FCC 6 GHz testing backlogs warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Safety Products
Organic Sanitary Napkin Market
Baby Safety Products
Forward Facing Type Child Safety Seats Market
Baby Safety Products
Global Baby Cleaning Products Market
Baby Safety Products
BRICS Disposable Hygiene Products Market
Baby Safety Products
Baby Gate Market
Baby Safety Products
Japan Adult Diaper Market
Baby Safety Products
Booster Car Seats Market
Baby Safety Products
Baby Safety Products Market
Baby Safety Products
India Pant Type Adult Diaper Market
Baby Safety Products
Baby Safety Seats Market
Baby Safety Products
Reusable Sanitary Pads Market
Baby Safety Products
Biodegradable Sanitary Napkins Market
Baby Safety Products
North America Adult Diaper Market
Baby Safety Products
Panty Liner Market
Baby Safety Products
United States Away from Home Tissue and Hygiene Market
Baby Safety Products
Global Feminine Protection Market