
 Booster Car Seats Market | 2026-2036
Booster Car Seats Market Size, Share, and Industry Trends Forecast 2026-2036
Booster Car Seats Market Outlook
Modular convertible-to-backless configurations is repositioning buyer choice by extending product usable life across multiple age stages. Graco Children's Products Inc. leverages its broad retail distribution to sustain volume leadership in North American mass-market channels. Britax anchors its premium positioning through advanced side-impact protection engineering and rigorous crash-test protocols. Maxi-Cosi competes in European markets with ISOFIX-integrated designs that emphasize installation simplicity and reduced misuse rates.
A booster car seat is a child restraint system designed to elevate a seated child so that the vehicle's three-point seat belt fits correctly across the shoulder and lap, typically constructed from injection-molded polypropylene shells, energy-absorbing EPS or EPP foam liners, and polyester or nylon upholstery covers. High-back variants incorporate headrests and side wings for upper-body protection, while backless models prioritize portability and compact storage. The type segment shows high-back and convertible configurations commanding margin pools due to their longer usage windows and higher perceived safety value. ISOFIX and LATCH integration within safety features represents the fastest-growing specification category as regulators and insurers alike emphasize correct installation rates.
FMVSS 213 in the United States, ECE R44/04 across Europe, and China's GB 27887 standard collectively define crash-performance thresholds, labeling requirements, and age/weight boundaries that determine product legality and parental trust. ECE R129 (i-Size) provisions in Europe are forcing design shifts toward rear-facing-for-longer transitions and height-based rather than weight-based classifications. Stakeholders must monitor regulatory divergence between height-centric European standards and weight-retentive frameworks elsewhere, as this split determines which product architectures merit R&D investment and which regional certifications unlock market access.
Market Dynamics
Modular convertible-to-backless configurations are compressing replacement cycles and extending product usable life, forcing manufacturers to recapture margin through premium feature tiers rather than volume turnover.
Growth Catalysts
- ISOFIX-integrated installation systems:LATCH-compatible designs reduce misuse rates and satisfy insurer-driven safety incentives in United States and German markets.
- ECE R129 height-based classifications:European regulators are mandating rear-facing-for-longer transitions that expand addressable age ranges for convertible seat architectures.
- Injection-molded polypropylene shell advances:Energy-absorbing EPS and EPP foam liner technologies enable lighter weight without compromising FMVSS 213 crash thresholds.
Market Restraints
- Petrochemical feedstock volatility:Polypropylene and polyester upholstery input costs fluctuate with crude oil derivatives, compressing margin stability for mid-tier producers.
- Regional certification fragmentation:Divergence between FMVSS 213 weight-based frameworks and ECE R129 height-centric standards forces redundant R&D and testing expenditures.
- Extended product lifecycles:Convertible configurations that span 4-12 year age ranges reduce replacement frequency and absolute unit demand in saturated vehicle ownership markets.
Strategic Opportunities
- China's GB 27887 enforcement gaps:Provincial implementation variance creates first-mover advantage for certified foreign suppliers in tier-two and tier-three cities.
- Ride-share and taxi fleet mandates:Commercial child passenger requirements in urban United States and German jurisdictions open B2B procurement channels distinct from retail.
- Smart restraint integration:Convergence of ISOFIX physical anchoring with occupancy-sensor connectivity enables subscription-based safety monitoring services.
Industry Challenges
- Homologation timeline compression:ECE R44/04 to R129 transition deadlines in European markets strain engineering capacity and certification queue availability.
- Polymer formulation expertise scarcity:Specialized knowledge in impact-optimized polypropylene copolymer blends concentrates among legacy automotive Tier-1 suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Booster Car Seats Market |
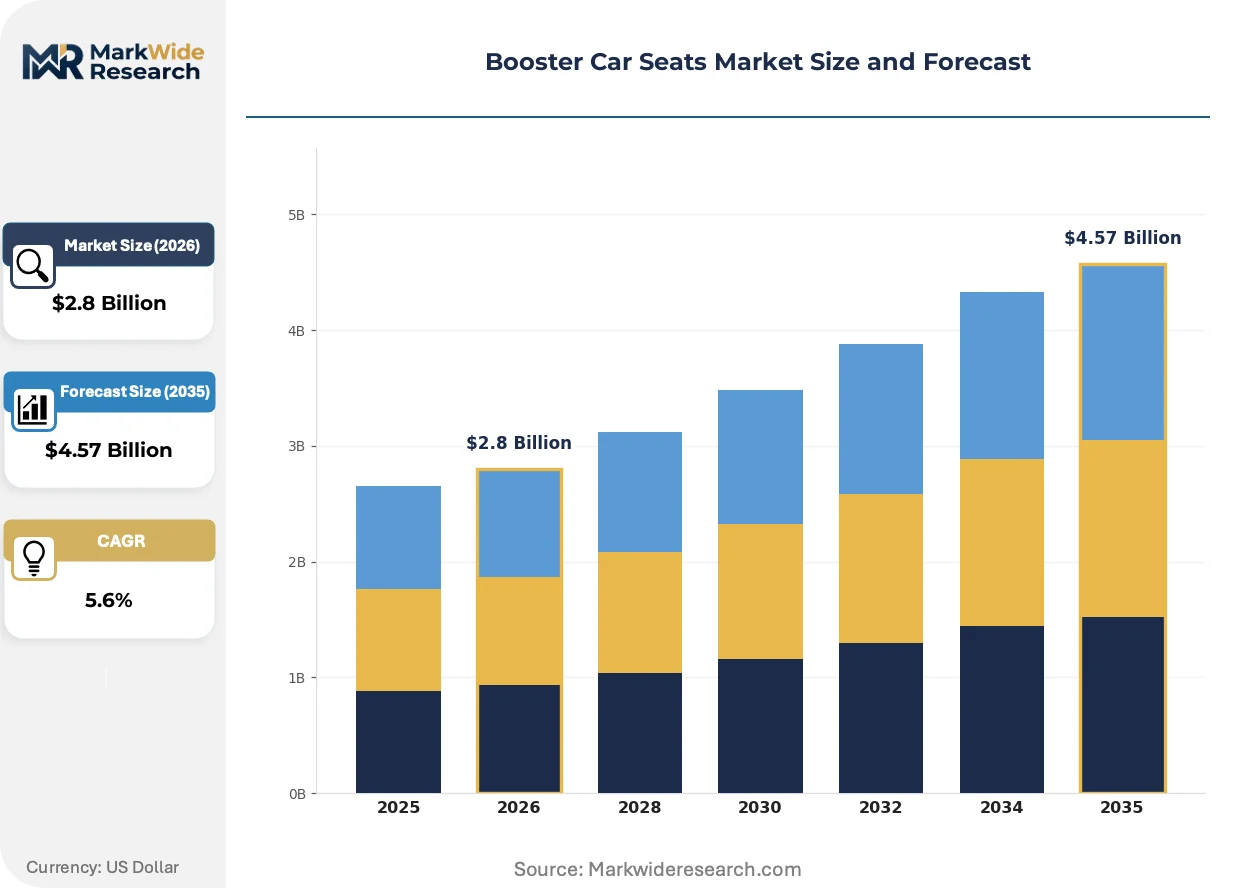
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.57 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: High-back, Backless, Convertible, All-in-one Material: Plastic, Metal, Fabric, Foam Age Group: Toddlers, Preschoolers, School-age, Tweens Safety Features: ISOFIX, LATCH, Side Impact Protection, Harness System |
| Companies Covered | Graco Children's Products Inc., Britax, Maxi-Cosi, Dorel Juvenile, Evenflo Company, Inc., Chicco, BubbleBum, Diono, LLC, Recaro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Booster Car Seats Market Strategic Shifts
Product architecture is pivoting toward adaptive systems that accommodate longer usage windows, while regulatory fragmentation forces parallel development tracks for distinct certification regimes.
Machine-learning-optimized foam density mapping is overtaking uniform liner construction in premium high-back variants. German and United States safety institutes are validating predictive crash-simulation outputs against physical test data. This computational approach is compressing prototype iterations from months to weeks while maintaining FMVSS 213 and ECE R44/04 compliance margins.
REACH substance restrictions on flame-retardant chemistries are forcing polyester and nylon upholstery reformulations across European supply chains. Manufacturers serving ECE R129 markets must certify alternative intumescent coatings and fiber blends without degrading abrasion resistance. High-back configurations with integrated side wings face the steepest requalification burdens given larger surface area exposure.
Fleet procurement through employer-sponsored child safety programs is displacing individual retail purchases in United States urban corridors. Large employers in technology and professional services sectors are subsidizing ISOFIX-compatible seats as retention benefits. This channel concentrates volume with manufacturers capable of direct B2B contracting and customized corporate branding.
Booster Car Seats Market Segmentation
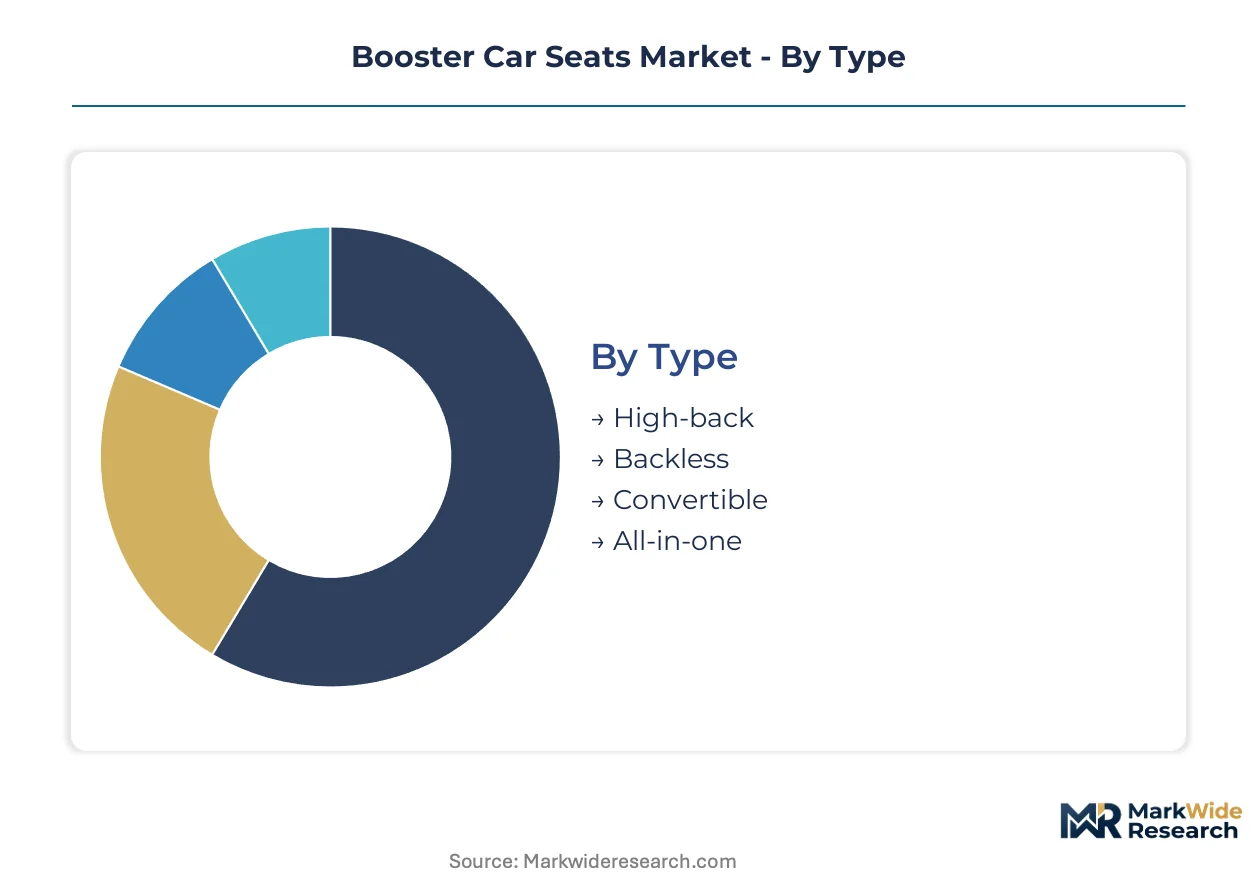
Booster car seat purchasing decisions hinge on installation compatibility, age-appropriate fit, and perceived safety value. Manufacturers engineer distinct product architectures to capture margin pools across regulatory regimes and household lifecycle stages.
Type:
Supply concentration favors manufacturers with integrated molding capabilities for complex shell geometries.
- High-back:Incorporates headrests and side wings from injection-molded polypropylene with EPS foam liners. Demand clusters in Germany and United States where FMVSS 213 and ECE R44/04 emphasize upper-body protection standards.
- Backless:Prioritizes portability through compact polypropylene bases without structural wings. School-age children in multi-vehicle households drive replacement purchases for taxi and ride-share compatibility.
- Convertible:Modular designs transition from high-back to backless configurations.
- All-in-one:Single-purchase solutions spanning forward-facing harness through booster modes.
High-back absorbs the bulk of installed capacity; convertible is expanding most quickly.
Material:
Cost tier stratification separates premium energy-absorbing formulations from commodity inputs.
- Plastic:Polypropylene copolymer shells dominate volume production. REACH substance restrictions in Europe are forcing reformulation of flame-retardant additives without degrading FMVSS 213 impact thresholds.
- Foam:EPP and EPS liners enable progressive energy absorption during crash events. Machine-learning-optimized density mapping is compressing prototype cycles for premium high-back variants in German certification pipelines.
- Fabric:Polyester and nylon upholstery covers require abrasion-resistant weaving.
- Metal:Steel reinforcement inserts anchor ISOFIX and LATCH connector systems.
Plastic commands the greatest production volume; foam is climbing the fastest on safety specification premiums.
Age Group:
Application-driven segmentation aligns product dimensions with anthropometric data and regulatory weight thresholds.
- School-age:Children approximately 6-12 years represent the core addressable population. United States state-level mandate enforcement and high vehicle ownership rates sustain replacement demand in this bracket.
- Preschoolers:Transitional users requiring harness-to-booster progression. ECE R129 height-based classifications in Europe are extending rear-facing requirements, compressing entry timing for forward-facing boosters.
- Toddlers:Early forward-facing transition candidates in weight-based regulatory frameworks.
- Tweens:Older children approaching adult seat belt fit without elevation assistance.
School-age captures dominant revenue share; preschoolers face regulatory headwinds in European markets.
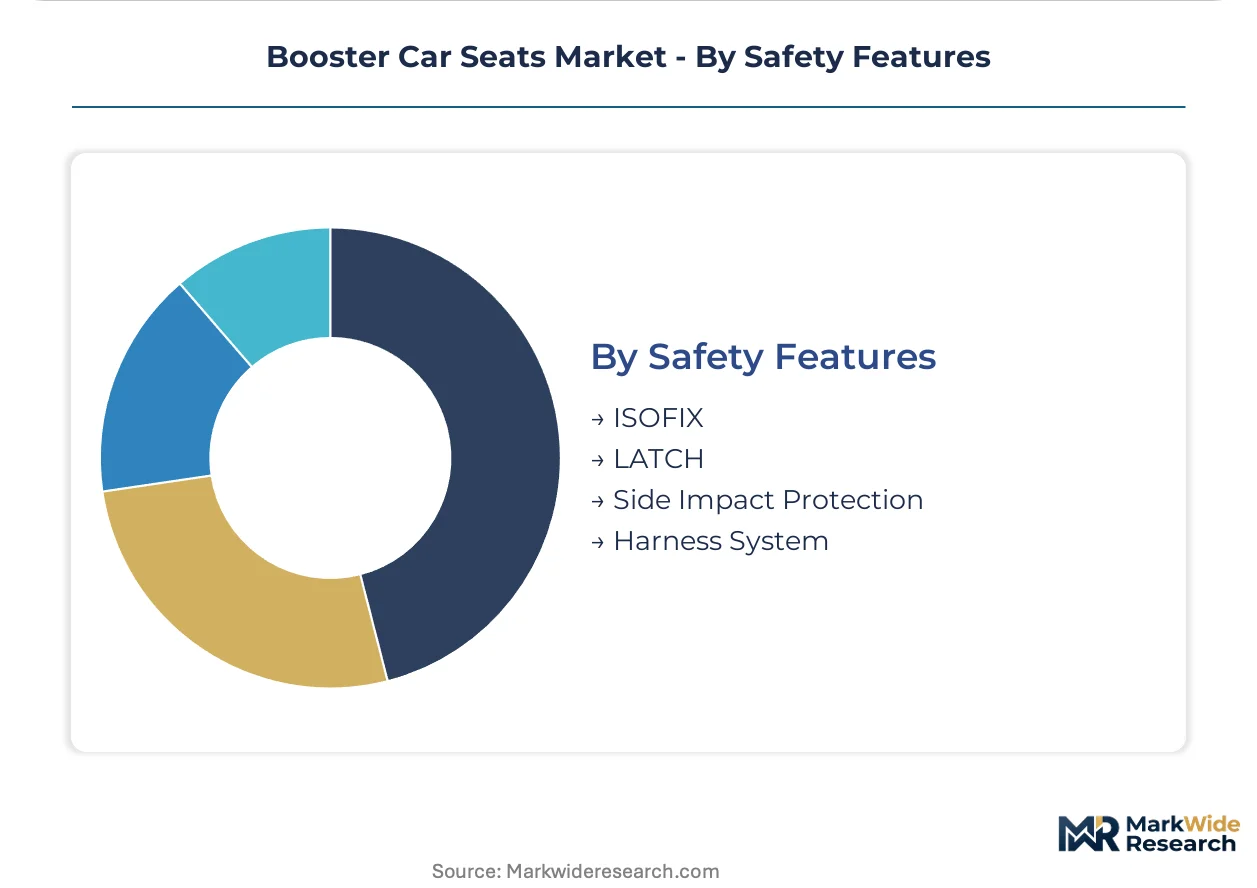
Safety Features:
Margin expansion concentrates on installation systems that reduce misuse liability.
- ISOFIX:Rigid anchoring interface eliminates belt-routing errors. European markets mandate this specification, while United States insurers incentivize correct installation through premium discounts.
- Side Impact Protection:Reinforced wings and energy-absorbing materials shield against lateral collision forces. German KBA validation protocols and FMVSS 213 proposed amendments are tightening performance requirements.
- LATCH:Lower anchor and tether system for United States market compatibility.
- Harness System:Five-point restraint for forward-facing convertible modes.
ISOFIX anchors the greatest certification investment; side impact protection is gaining share fastest on regulatory tightening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free-trade zones in Guangdong and Zhejiang provinces concentrate injection-molding capacity for polypropylene shell production. These special economic zones offer 15% corporate tax rates and streamlined customs clearance for automotive component exports. Manufacturers cluster here to serve both domestic Chinese demand and European OEM supply chains.
United States
State-level mandate enforcement varies widely, with California and New York maintaining the strictest penalties for non-compliance. NHTSA administers FMVSS 213 certification through contracted testing laboratories in Detroit and Los Angeles. Michigan's automotive supplier corridor hosts crash-test validation facilities serving domestic and export-bound manufacturers.
Germany
KBA validation protocols represent the most rigorous European homologation pathway, creating certification backlogs for new market entrants. ECE R129 height-based classifications are compressing traditional weight-based product lines. Stuttgart and Munich anchor development centers where Tier-1 automotive suppliers transfer polymer expertise to child restraint specialists.
China
Provincial enforcement of GB 27887 remains inconsistent, with Shanghai and Beijing exceeding national minimums while interior provinces lag. SAMR conducts market surveillance testing that disqualifies uncertified imports from e-commerce platforms. Yangtze River Delta manufacturing clusters supply ISOFIX anchor hardware to European and North American assembly plants.
United Kingdom
Post-Brexit divergence from ECE R44/04 creates parallel certification requirements for products sold in EU and UK markets. Trading standards officers in London and Birmingham conduct retail compliance inspections with penalty authority. Midlands-based textile suppliers reformulate upholstery fabrics to satisfy both REACH restrictions and domestic flammability standards.
Booster Car Seats Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered price positioning. The vendor base stratifies into three layers: mass-market volume leaders, premium engineering specialists, and niche portability innovators. Two dominant competitive moves define current rivalry: geographic certification expansion to capture regulatory divergence rents, and polymer formulation partnerships with automotive Tier-1 suppliers.
Within the premium engineering tier, Britax and Recaro exemplify positioning through advanced side-impact architectures. Graco Children's Products Inc. occupies the mass-market volume position, leveraging retail distribution density across North American big-box channels. Maxi-Cosi anchors European market presence through ISOFIX-integrated design specialization.
| Leading Market Players |
|---|
| Graco Children's Products Inc. |
| Britax |
| Maxi-Cosi |
| Dorel Juvenile |
| Evenflo Company, Inc. |
| Chicco |
| BubbleBum |
| Diono, LLC |
| Recaro |
| Others |
Value Chain & Pricing Dynamics
Polymer formulation specialists in the Yangtze River Delta command wage premiums that compress margin spreads between economy and premium booster seat tiers. Labor-cost differentials between Guangdong molding hubs and European assembly plants translate directly into pricing stratification across certification-grade segments.
Pricing Analysis
Short lead-time premiums attach to ISOFIX-integrated high-back configurations sourced from KBA-validated German facilities, while spot inventory of backless models from Yangtze Delta warehouses trades at discounted clearance levels. Three-tier pricing structure across premium, standard, and economy levels separates ECE R129-certified units with machine-learning-optimized foam from FMVSS 213 baseline models and uncertified gray-market imports. Pricing pressure stems from petrochemical feedstock volatility in polypropylene copolymer inputs. Fleet procurement managers exhibit lowest price sensitivity due to employer-subsidized volume commitments, whereas individual retail buyers in tier-two Chinese cities drive aggressive economy-tier negotiation.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Los Angeles, and Shanghai anchor hub-and-spoke patterns that consolidate finished-goods inventory before last-mile deployment to retailer DCs and direct-to-consumer fulfillment nodes. Manufacturing concentration centers on China, Germany, and the United States for injection-molded polypropylene shells, with Yangtze Delta and Guangdong provinces hosting the majority of EPS and EPP foam liner production. Raw material dependencies include Saudi-sourced polypropylene resin, Belgian-engineered ISOFIX anchor hardware, and Taiwanese-sourced polyester upholstery fibers. Single-source vulnerability concentrates in specialized polymer formulation expertise held by legacy automotive Tier-1 suppliers. Distribution runs through big-box retail procurement offices, direct B2B fleet contracting channels, and e-commerce platform fulfillment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The booster car seat market sits in a technology-transition phase as machine-learning-optimized foam density mapping displaces uniform liner construction in premium segments. Computational crash simulation is compressing prototype cycles and redefining R&D investment thresholds.
For Market Incumbents: Anticipate margin compression from convertible configurations extending product lifecycles by capturing share through ISOFIX-integrated premium tiers and securing exclusive polymer formulation partnerships with automotive Tier-1 suppliers in Stuttgart and Munich. ECE R129 height-based regulatory divergence threatens legacy weight-based product architectures, necessitating parallel certification investments to defend European market access.
For New Entrants and Emerging Players: Ride-share and taxi fleet operators in urban United States jurisdictions represent an underserved buyer archetype with concentrated procurement volume and limited incumbent penetration. White-space targets include employer-sponsored child safety programs in technology sector corridors and tier-two Chinese cities where GB 27887 enforcement gaps create first-mover certification advantages. Go-to-market execution should prioritize direct B2B contracting capabilities over retail channel buildout.
For Investors and Strategic Acquirers: The window for entry favors polymer formulation specialists with transferable automotive safety expertise and existing KBA validation relationships. Long-term viability hinges on five-to-ten year regulatory convergence scenarios between FMVSS 213 and ECE R129 frameworks. The inflection signal to monitor is provincial GB 27887 enforcement acceleration in China's interior provinces, which would compress gray-market tolerance and validate certified foreign supplier positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| ISOFIX-Integrated Platform Standardization | ECE R129 mandates in Germany and insurer incentives in the United States accelerate specification convergence. |
| Machine-Learning Foam Optimization Partnership | German KBA validation protocols reward computational crash-simulation capabilities with faster certification timelines. |
| Provincial Certification Pre-Positioning | Early GB 27887 compliance in Shanghai and Beijing creates transferable qualification assets for tier-two expansion. |
| Fleet Procurement Channel Development | Employer-sponsored programs in United States technology corridors concentrate volume outside saturated retail. |
| Polymer Formulation Backward Integration | Captive supply of impact-optimized polypropylene copolymer blends insulates margin from petrochemical volatility. |
Study Parameters
Independent corroboration across NHTSA FMVSS 213 certification databases, KBA type-approval registries, and SAMR market surveillance disclosures underwrites the qualitative findings on regulatory divergence and enforcement gaps. Primary interviews with child restraint engineering directors, automotive Tier-1 polymer specialists, fleet procurement managers at large employers, and big-box retail category buyers combined with secondary validation from customs trade records, SEC filings of diversified juvenile product manufacturers, and IHS Markit vehicle registration data. Bottom-up segment sizing and top-down macroeconomic anchoring provided cross-checks on volume and value outputs.
Historical reference periods spanning pre-pandemic baseline through post-regulatory-transition implementation anchored the forecast window across the analysis window. Segmentation dimensions modeled include product type architecture, material composition tier, age-group application, safety feature specification, and regional regulatory cluster. CAGRs were derived from regression analysis of certified unit volumes against vehicle ownership rates and mandate enforcement intensity. Industry-specific forecast inputs incorporated ECE R44/04 to R129 transition timeline assumptions and provincial GB 27887 enforcement acceleration scenarios.
Revisions become necessary when petrochemical feedstock volatility exceeds historical bands, when ECE R129 transition deadlines compress homologation capacity, or when China's provincial enforcement harmonization accelerates unexpectedly. Forecasts reflect documented assumptions on regulatory timeline adherence and substitution elasticity between high-back and convertible configurations. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Safety Products
Forward Facing Type Child Safety Seats Market
Baby Safety Products
Global Baby Cleaning Products Market
Baby Safety Products
Baby Gate Market
Baby Safety Products
BRICS Disposable Hygiene Products Market
Baby Safety Products
North America Adult Diaper Market
Baby Safety Products
Reusable Sanitary Pads Market
Baby Safety Products
Baby Safety Seats Market
Baby Safety Products
North America Baby Monitors Market
Baby Safety Products
India Pant Type Adult Diaper Market
Baby Safety Products
Japan Adult Diaper Market
Baby Safety Products
Biodegradable Sanitary Napkins Market
Baby Safety Products
Global Feminine Protection Market
Baby Safety Products
Organic Sanitary Napkin Market
Baby Safety Products
Baby Safety Products Market
Baby Safety Products
Reusable/Washable Hygiene Products Market
Baby Safety Products
Panty Liner Market