
 Mesitylene Market | 2026-2036
Mesitylene Market Size, Share, and Industry Trends Forecast 2026-2036
Mesitylene Market Foresight
Capital-intensity divergence between integrated refinery operators and specialty chemical pure-plays is rotating competitive dynamics across the mesitylene value chain. Mitsubishi Gas Chemical Company leverages captive feedstock from its xylene isomerization complexes to sustain cost-advantaged positions in ultra-high-purity grades. The DOW Chemical Company anchors North American supply through integrated aromatics infrastructure, while Jurong Anbei Chemical competes on regional logistics proximity to Yangtze River Delta coating manufacturers.
Mesitylene, or 1,3,5-trimethylbenzene, is an aromatic hydrocarbon with a molecular formula of C9H12 and a boiling point of approximately 165 degrees Celsius, produced primarily through fractional distillation of C9 aromatic streams or catalytic reformate extraction. Its primary industrial purpose centers on serving as a chemical intermediate for 2,4,6-trimethylaniline synthesis and as a high-boiling solvent in coatings, adhesives, and electronics-grade cleaning formulations. The solvent segment dominates volume flows into industrial coatings and adhesive systems, while chemical intermediate applications represent the fastest-growing category as pharmaceutical and agrochemical manufacturers expand 2,4,6-trimethylaniline derivative production. Electronics end users command premium positioning due to stringent metal-ion purity requirements below ten parts per billion, creating concentrated margin pools distinct from commodity solvent grades.
EPA regulations under the Toxic Substances Control Act and REACH registration requirements in Europe impose escalating purity documentation and supply chain traceability obligations on mesitylene importers and formulators. South Korea's MFDS and Japan's METI enforce comparable contaminant thresholds for electronics-grade material entering semiconductor and display manufacturing channels. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions in coatings applications, as regulatory scope expansion could redirect formulation demand toward mesitylene-based alternatives or trigger reformulation costs across adhesive and industrial solvent segments.
Market Dynamics
Ultra-high-purity electronics-grade specifications are compressing margins for commodity solvent producers while concentrating procurement among qualified suppliers serving semiconductor fabrication clusters.
Growth Catalysts
- Semiconductor node advancement:Sub-7nm lithography processes require metal-ion purity below ten parts per billion, expanding qualified supplier rosters for South Korean and Taiwanese fabs.
- REACH registration tier escalation:ECHA's 2023 tonnage band updates mandate enhanced substance characterization for C9 aromatic importers, accelerating documentation investments among European formulators.
- Advanced packaging diffusion:Chiplet architectures and 3D stacking techniques multiply cleaning cycles per wafer, increasing solvent throughput at outsourced assembly and test facilities.
Market Restraints
- Feedstock volatility:Catalytic reformate yields fluctuate with gasoline demand cycles, exposing fractional distillation operators to naphtha cracking economics.
- East Asian supply concentration:Over seventy percent of electronics-grade capacity sits within a three-hundred-kilometer radius of Seoul and Kaohsiung, amplifying disruption risks from regional logistics constraints.
- Perfluorinated solvent substitution:Hydrofluoroether blends for precision cleaning threaten mesitylene volumes in display panel manufacturing where metal-ion tolerances are less stringent.
Strategic Opportunities
- Indian pharmaceutical agglomeration:Hyderabad and Ahmedabad API clusters lack domestic ultra-high-purity solvent supply, creating import substitution openings for qualified exporters.
- Green chemistry procurement mandates:EU Green Deal circular economy requirements favor bio-based aromatic alternatives, positioning catalytic pyrolysis-derived mesitylene for premium certification tiers.
- Direct-to-fab distribution:Bulk chemical logistics platforms are disintermediating traditional distributor networks for Taiwanese and South Korean semiconductor manufacturers.
Industry Challenges
- Analytical chemistry talent scarcity:ICP-MS and GC-MS operators capable of validating parts-per-billion contamination profiles command premium compensation in East Asian manufacturing hubs.
- Qualification timeline compression:Semiconductor fabs now demand twelve-month supply chain validation cycles, halving traditional eighteen-month windows for new grade approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mesitylene Market |
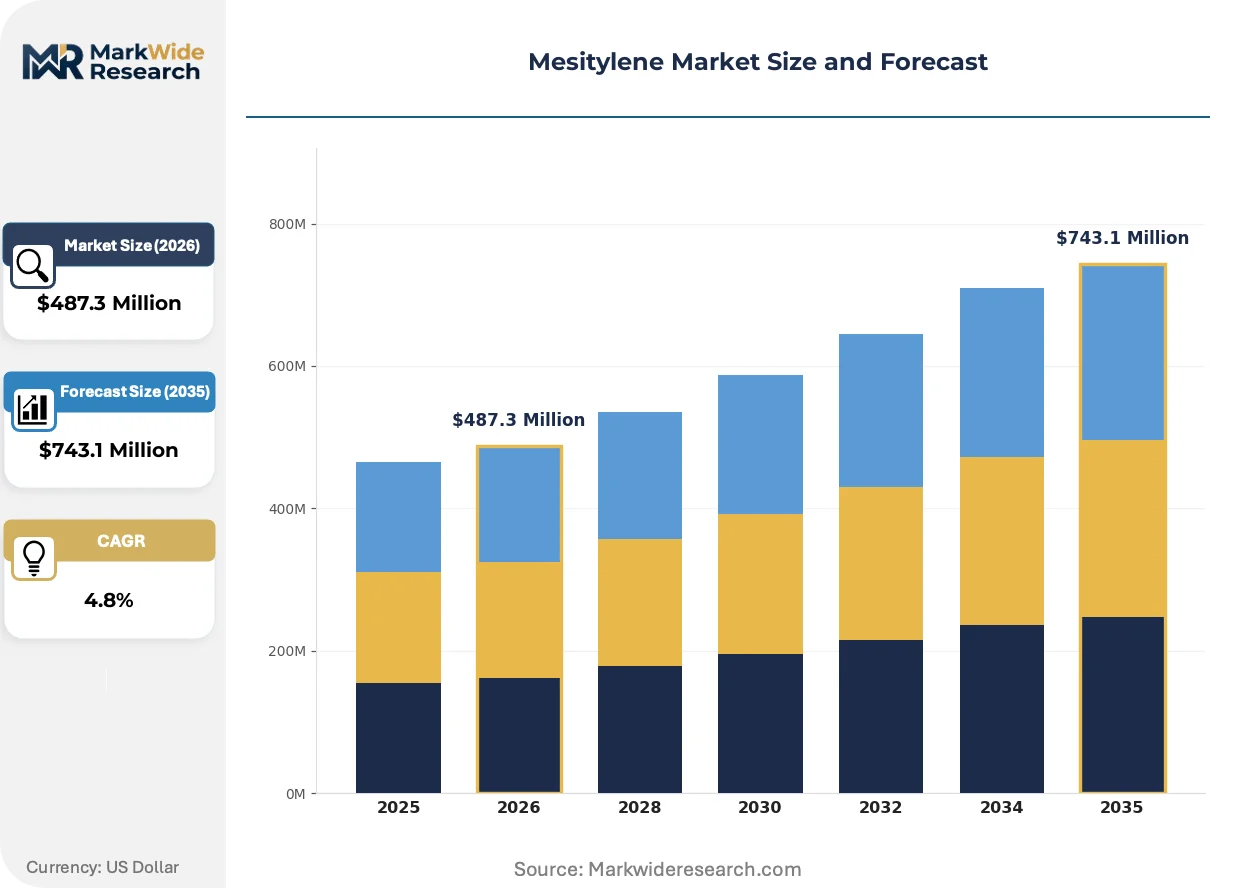
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $743.1 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent, Chemical Intermediate, Additive, Laboratory Reagent Application: Coating, Adhesives, Pharmaceuticals, Industrial Solvents End User: Chemical Industry, Automotive, Electronics, Agriculture Distribution Channel: Direct Sales, Online Sales, Distributors, Wholesale |
| Companies Covered | Mitsubishi Gas Chemical Company Inc., The DOW Chemical Company, Versalis, Refinery of Sinopec Jinling, EMD Performance Materials, Toyo Gosei Co., Ltd., Jurong Anbei Chemical Co., Ltd., Nantong Dingji Chemical Technology Co., Ltd., Jiangsu Jiuri Chemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mesitylene Market Shifts & Advancements
Process intensification and regulatory digitization are restructuring how purity is validated, traced, and contracted across the mesitylene value chain.
Membrane-based aromatic separation is bifurcating the purification technology landscape. Pervaporation systems using polyimide hollow-fiber modules achieve electronics-grade purity without energy-intensive fractional distillation. Samsung Display and AUO have qualified membrane-derived material for photoresist thinning operations. This technology is bifurcating capital deployment between incumbent distillation assets and modular membrane skids that can be co-located at fab perimeters.
EPA's TSCA Section 8(a)(7) reporting requirements for per- and polyfluoroalkyl substances are expanding documentation burdens for coating formulators using mesitylene as a carrier solvent. Metal finishing and adhesive manufacturers must now trace fluorinated additive content through multi-tier supply chains. Industrial coatings segments in the United States are responding by reformulating toward fluorine-free systems, redirecting specification discussions toward mesitylene's inherent solvency advantages.
Long-term offtake contracting is displacing spot market purchasing for electronics-grade volumes. South Korean semiconductor manufacturers now commit to thirty-six-month supply agreements with fixed purity escalation clauses, replacing quarterly tenders. This pattern concentrates procurement leverage among three qualified suppliers while compressing working capital flexibility for smaller formulators serving coating and adhesive segments.
Mesitylene Market Segmentation
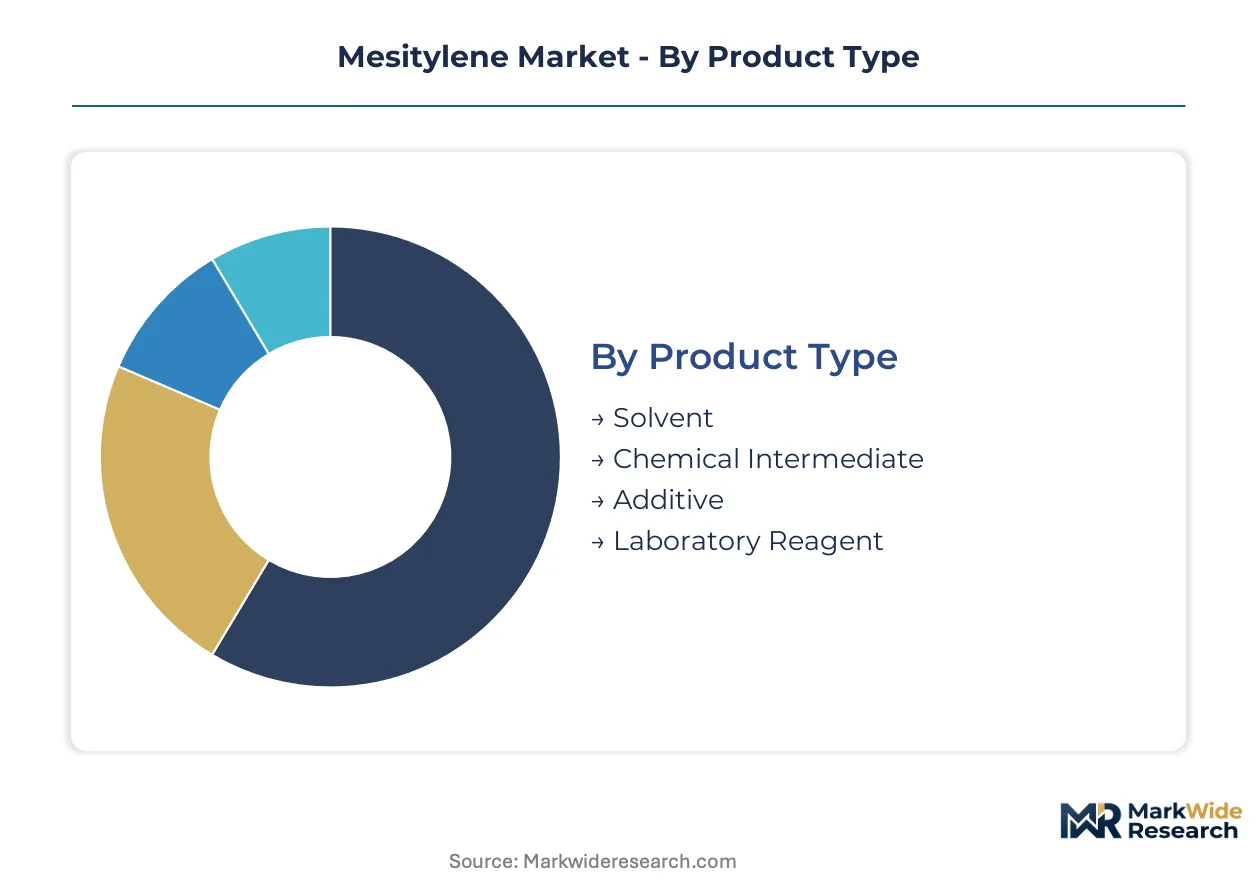
Mesitylene segmentation reveals divergent purity regimes across electronics and industrial applications. Semiconductor fabs enforce metal-ion thresholds below ten parts per billion, while coating formulators operate under less stringent specifications. Understanding these tiered requirements clarifies where margin pools concentrate versus where volume flows commoditize.
Product Type:
REACH registration tier escalation and EPA TSCA documentation obligations separate qualified grades from commodity offerings.
- Solvent:High-boiling aromatic hydrocarbon serving industrial coatings, adhesives, and precision cleaning operations. Demand concentrates in East Asian manufacturing clusters, particularly South Korean flat-panel display facilities, where qualified suppliers command premium positioning over commodity distillers.
- Chemical Intermediate:Feedstock for 2,4,6-trimethylaniline synthesis in pharmaceutical and agrochemical manufacturing. Indian API clusters in Hyderabad and Ahmedabad drive import substitution demand as domestic ultra-high-purity supply remains underdeveloped.
- Additive:Modifying agent enhancing solvent blend performance in specialty formulations. METI and MFDS contaminant thresholds restrict qualified supplier pools for electronics-grade additive applications.
- Laboratory Reagent:Analytical-grade material for research and quality control protocols. Academic and contract research organizations source through distributor networks with ISO-certified documentation trails.
Established volume favors Solvent; emerging adoption favors Chemical Intermediate.
Application:
End-use cost tiers stratify procurement leverage and contract duration.
- Coating:Industrial finishes and protective layers relying on mesitylene's solvency and controlled evaporation profile. EU Green Deal circular economy requirements favor bio-based aromatic alternatives, redirecting specification discussions toward catalytic pyrolysis-derived material.
- Adhesives:Formulation component enabling precise viscosity control in structural bonding systems. EPA Section 8(a)(7) PFAS reporting obligations are forcing reformulation toward fluorine-free carrier solvents.
- Pharmaceuticals:Intermediate production for active pharmaceutical ingredient synthesis. CDSCO and EMA impurity guidelines mandate enhanced substance characterization for C9 aromatic derivatives entering drug manufacturing channels.
- Industrial Solvents:Broad-spectrum cleaning and degreasing applications across metal finishing and maintenance operations. Hydrofluoroether blends threaten displacement in display panel manufacturing where metal-ion tolerances permit substitution.
Procurement concentration runs through Coating; qualification timelines compress fastest in Pharmaceuticals.
End User:
Customer type determines purity documentation intensity and supply chain traceability depth.
- Electronics:Semiconductor fabrication and advanced packaging facilities requiring ultra-high-purity grades. Sub-7nm lithography processes at Taiwanese and South Korean fabs demand twelve-month validation cycles, halving traditional supplier approval windows.
- Chemical Industry:Diversified manufacturers integrating mesitylene into downstream derivative production. Long-term offtake contracting with fixed purity escalation clauses is displacing quarterly spot purchasing among qualified suppliers.
- Automotive:Coatings and adhesives formulators serving vehicle assembly and component manufacturing. NHTSA and EPA compliance documentation adds traceability layers without reaching electronics-grade analytical burdens.
- Agriculture:Agrochemical manufacturers synthesizing crop protection intermediates. Pesticide registration requirements under FIFRA and equivalent national frameworks impose substance characterization obligations distinct from pharmaceutical protocols.
Margin capture concentrates in Electronics; volume scale accumulates in Chemical Industry.
Distribution Channel:
Supply chain configuration determines working capital flexibility and customer proximity.
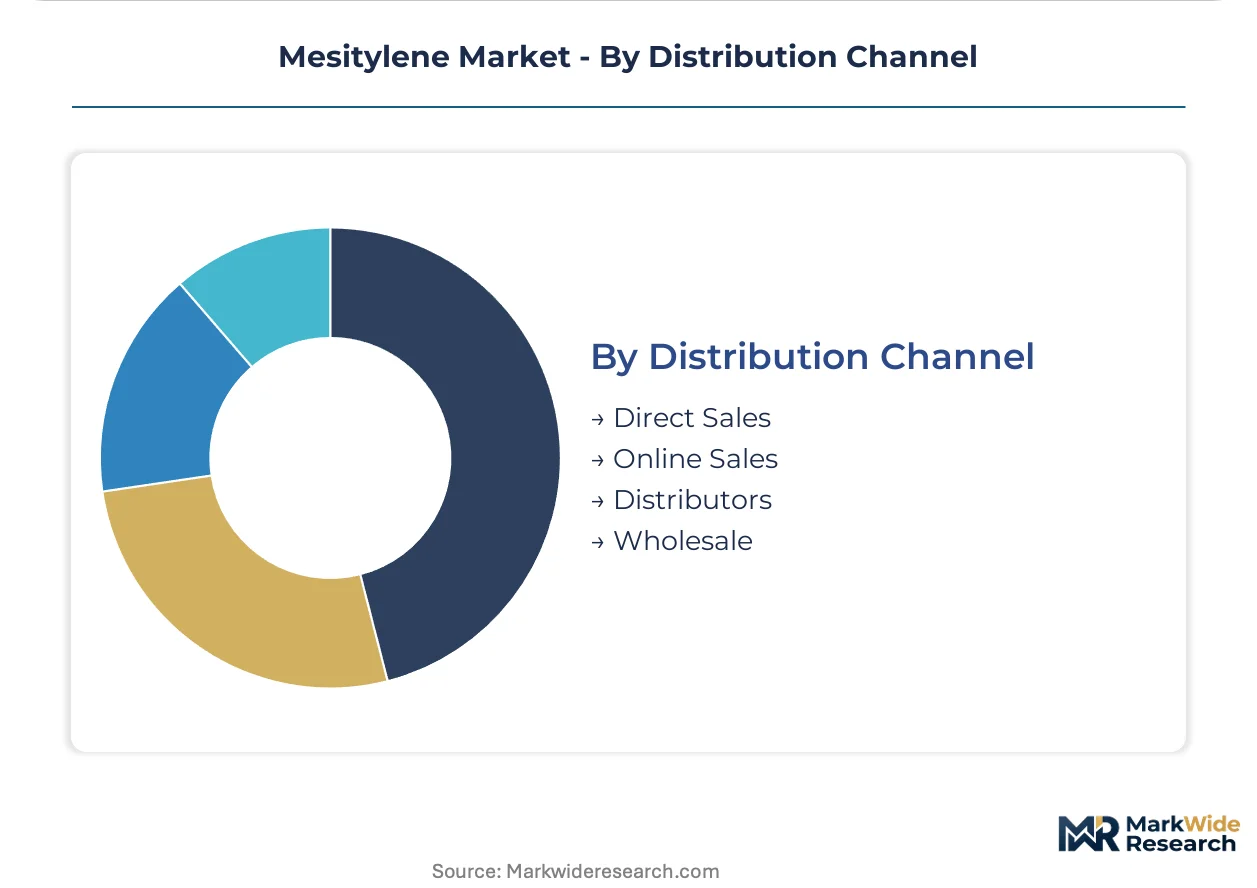
- Direct Sales:Bulk chemical logistics platforms disintermediating traditional networks for Taiwanese and South Korean semiconductor manufacturers. Thirty-six-month supply agreements with fixed purity clauses lock in procurement leverage among three qualified suppliers.
- Distributors:Regional inventory positioning serving coating and adhesive formulators with shorter lead time requirements. Working capital compression from long-term contracting concentrates distributor exposure toward smaller volume accounts.
- Online Sales:Digital procurement channels for laboratory reagent and small-volume industrial orders. ISO-certified documentation trails enable remote qualification for research and quality control applications.
- Wholesale:Volume aggregation for commodity solvent grades entering industrial maintenance and metal finishing segments. Price transparency pressures margin retention where purity specifications permit multi-source qualification.
Channel investment flows toward Direct Sales; distributor relevance persists in Wholesale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea and Taiwan consume mesitylene predominantly for electronics-grade solvent applications, while India and Germany channel larger shares into pharmaceutical intermediate production, creating divergent purity requirements and procurement patterns across major demand centers.
United States
Semiconductor fabrication facilities in Arizona and Texas drive electronics-grade consumption as Intel and TSMC expand domestic advanced packaging capacity. EPA TSCA Section 8(a)(7) reporting obligations for PFAS content are forcing coatings formulators toward fluorine-free carrier solvents. Houston-Galveston petrochemical complexes anchor fractional distillation supply for industrial solvent grades serving Gulf Coast refineries.
South Korea
Samsung and SK Hynix fabs in Pyeongtaek and Yongin command ultra-high-purity volumes for sub-7nm lithography and 3D NAND stacking processes. MFDS contaminant thresholds for electronics-grade solvents match Taiwan's METI-equivalent specifications, creating harmonized qualification standards. The Seoul Capital Area concentrates over sixty percent of national semiconductor solvent procurement through direct-to-fab distribution platforms.
Germany
BASF and Evonik pharmaceutical operations in Ludwigshafen and Marl absorb chemical intermediate volumes for 2,4,6-trimethylaniline derivative synthesis. ECHA REACH registration tier escalation mandates enhanced substance characterization for C9 aromatic importers above one thousand metric tons annually. The Rhine-Neckar chemical triangle maintains Europe's densest agglomeration of mesitylene-consuming API manufacturers.
India
Hyderabad and Ahmedabad API clusters lack domestic ultra-high-purity solvent supply, creating import dependency for pharmaceutical intermediate production. CDSCO impurity guidelines for drug manufacturing inputs are tightening documentation requirements for C9 aromatic feedstocks. Gujarat's Dahej and Mundra port infrastructure enables bulk chemical logistics for qualified exporters serving western Indian pharmaceutical corridors.
Japan
Tokyo Electron and Shin-Etsu Chemical operations in Kumamoto and Niigata source electronics-grade material for photoresist formulations and precision cleaning. METI contaminant thresholds for semiconductor manufacturing chemicals enforce metal-ion purity below ten parts per billion. The Kyushu silicon island hosts concentrated advanced packaging facilities multiplying solvent throughput per wafer.
Mesitylene Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive feedstock access separating cost-advantaged positions from logistics-dependent competitors. Three archetypes populate the landscape: refinery-integrated aromatics producers leveraging reformate extraction, pure-play specialty chemical operators focusing on ultra-high-purity purification, and regional distributors serving coating and adhesive formulators with shorter lead time requirements. Capacity expansion and strategic partnerships dominate competitive moves, with membrane-based separation technology licensing emerging as a differentiation vector.
Among Japanese chemical conglomerates, Mitsubishi Gas Chemical Company Inc. and Toyo Gosei Co., Ltd. occupy positions within the integrated leader tier, representing captive feedstock advantages from xylene isomerization complexes. The DOW Chemical Company anchors North American supply archetypes through aromatics infrastructure scale. Chinese specialists including Jurong Anbei Chemical Co., Ltd., Nantong Dingji Chemical Technology Co., Ltd., and Jiangsu Jiuri Chemical Co., Ltd. exemplify regional logistics proximity strategies serving Yangtze River Delta manufacturing clusters.
| Leading Market Players |
|---|
| Mitsubishi Gas Chemical Company Inc. |
| The DOW Chemical Company |
| Versalis |
| Refinery of Sinopec Jinling |
| EMD Performance Materials |
| Toyo Gosei Co., Ltd. |
| Jurong Anbei Chemical Co., Ltd. |
| Nantong Dingji Chemical Technology Co., Ltd. |
| Jiangsu Jiuri Chemical Co., Ltd. |
| Others |
Supply & Pricing Matrix
Hydrofluoroether blends displacing mesitylene in display panel cleaning simultaneously redraw supply geography toward fluorinated solvent hubs and compress pricing power for commodity aromatic grades serving less stringent metal-ion tolerances. This substitution dynamic bifurcates procurement leverage between qualified ultra-high-purity suppliers and volume-driven commodity distillers.
Pricing Analysis
Long-term offtake contracting dominates electronics-grade procurement, with South Korean and Taiwanese fabs committing to thirty-six-month supply agreements featuring fixed purity escalation clauses. Price differentiation hinges on metal-ion certification grade and volume scale, with semiconductor manufacturers showing minimal price sensitivity compared to coating formulators. Cost compression in industrial solvent tiers intensifies as hydrofluoroether alternatives capture display manufacturing share, while premium electronics-grade margins remain insulated by qualification barriers.
Supply Chain Analysis
South Korea and Taiwan anchor ultra-high-purity electronics-grade production, drawing from catalytic reformate feedstocks sourced through integrated refinery complexes in Japan and the United States. Raw material dependencies center on naphtha cracking economics, xylene isomerization outputs, and membrane separation technology licensing. Single-source vulnerability concentrates within a three-hundred-kilometer radius of Seoul and Kaohsiung, where logistics chokepoints amplify disruption exposure. Distribution runs through direct-to-fab bulk chemical platforms disintermediating traditional distributor networks for semiconductor manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment creates durable competitive positions. Qualification timelines and purity documentation requirements generate switching costs that protect incumbent supplier relationships.
For Market Incumbents: Fortify captive feedstock positions through backward integration into xylene isomerization complexes, securing cost-advantaged supply for ultra-high-purity grades. Expand membrane-based purification capacity at fab-proximate locations to reduce logistics exposure and deepen customer embedment against emerging catalytic pyrolysis competitors. For New Entrants and Emerging Players: Lead with bio-based aromatic alternatives targeting EU Green Deal procurement mandates, where sustainability certification creates qualification pathways distinct from incumbent petroleum-derived supply. Focus initial penetration on Indian pharmaceutical clusters in Hyderabad and Ahmedabad, where domestic ultra-high-purity solvent scarcity forces import dependency and opens distributor partnership opportunities. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated refinery-chemical operators with captive reformate access and established semiconductor customer relationships. Acquisition targets should display membrane separation technology capabilities or qualified positions in underserved pharmaceutical geographies. Monitor ECHA tonnage band escalations and EPA PFAS restriction expansions as regulatory inflection signals that could redirect formulation demand and reshape supplier valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Separation Technology Licensing | Samsung Display qualification of polyimide hollow-fiber systems validates pervaporation as distillation alternative. |
| Backward Integration into Xylene Isomerization | Mitsubishi Gas Chemical's captive feedstock access sustains cost positioning in ultra-high-purity grades. |
| Long-term Supply Agreement with Purity Escalation Clauses | |
| Bio-based Aromatic Certification Investment | Catalytic pyrolysis-derived mesitylene positions for EU Green Deal circular economy procurement tiers. |
| Direct-to-Fab Distribution Platform Development | Bulk chemical logistics disintermediation reduces working capital cycles for Taiwanese semiconductor manufacturers. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with semiconductor procurement managers, coating formulator technical directors, pharmaceutical API manufacturing heads, and refinery aromatics planning officers. Secondary validation drew from customs trade databases, ECHA REACH registration filings, SEC 10-K disclosures, and ACC industry reports. Bottom-up volume modeling triangulated against top-down value estimates derived from production capacity assessments and end-use consumption surveys.
Across the analysis window, forecasts applied segmentation dimensions spanning purity grade tier, end-use industry electronics versus pharmaceutical versus coatings, and regional production hub concentration. CAGRs were derived from regression analysis of historical consumption patterns against semiconductor node advancement timelines and pharmaceutical intermediate production growth. Industry-specific inputs incorporated fab capacity expansion announcements, REACH registration tier escalation schedules, and display panel manufacturing technology substitution curves.
Forecasts assume regulatory continuity in EPA TSCA enforcement and ECHA REACH tier structures; material policy shifts toward expanded PFAS restrictions or accelerated bio-based procurement mandates would require re-modeling. Recalibration cycles align with material shifts in semiconductor lithography node transitions, pharmaceutical agglomeration patterns in India, and membrane separation technology adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
C2 Chlorinated Solvents Market
Solvents
Methyl Acetate Market
Solvents
Diethanolamine (DEA) Market
Solvents
Butyl Glycol Market
Solvents
Vapor Degreasing Solvents Market
Solvents
Green Solvents Market
Solvents
Dimethyl Ether (DME) Market
Solvents
Citrus Solvents Market
Solvents
Asia-Pacific Ethane Market
Solvents
India High Purity Solvents Market
Solvents
Sugar Dissolvers Market
Solvents
Europe Acetonitrile Market
Solvents
Propylene Glycol Methyl Ether Market
Solvents
Trichloroacetyl Chloride Market
Solvents
Decanol Market
Solvents
Green Solvents and Bio-Solvents Market