
 Ionic Liquids Market | 2026-2036
Ionic Liquids Market Size, Share, and Industry Trends Forecast 2026-2036
Ionic Liquids Market Analysis
Aftermarket electrolyte formulation revenue is reconfiguring margin pools away from commodity solvent supply toward tailored ionic liquid blends for battery manufacturers. BASF SE leverages its integrated chemical platform to dominate imidazolium salt production at scale. Solvay anchors European supply through specialized manufacturing in Belgium. Tatva Chintan Pharma Chem Pvt. Ltd. competes on cost-efficient synthesis routes serving Asian pharmaceutical customers.
Ionic liquids are molten salts comprising bulky organic cations paired with inorganic or organic anions, exhibiting negligible vapor pressure below decomposition temperatures near 300-400°C and electrical conductivities spanning 0.1-20 mS/cm depending on composition. Their primary industrial purpose centers on replacing volatile organic solvents in catalysis, extraction, and electrochemical systems where thermal stability and non-flammability prove critical. The 1-Butyl-3-Methylimidazolium product family leads commercial volumes due to established synthesis pathways and broad compatibility profiles. Electrochemistry applications represent the fastest-expanding segment as solid-state battery developers adopt ionic liquid electrolytes for enhanced ionic transport.
The EPA governs volatile organic compound emissions under the Clean Air Act, directly incentivizing ionic liquid substitution in U.S. manufacturing processes. ECHA administers REACH registration requirements that mandate toxicological data for novel ionic liquid chemistries entering European commerce. China's MEE enforces dual carbon goals that favor non-volatile solvents in industrial processes. Stakeholders must monitor evolving battery safety standards and regional chemical registration timelines to secure first-mover positions in electrolyte-grade ionic liquid supply.
Market Dynamics
The substitution of volatile organic solvents with thermally stable ionic alternatives is restructuring procurement patterns across battery manufacturing and pharmaceutical synthesis, driven by tightening emissions controls and solid-state electrolyte development.
Growth Catalysts
- REACH registration pathways:ECHA's streamlined data requirements for ionic liquid categories are accelerating commercial entry of novel chemistries into European industrial solvent markets.
- Solid-state battery electrolyte demand:Lithium-metal cell developers are specifying ionic liquid blends for enhanced thermal stability and dendrite suppression in next-generation energy storage systems.
- Green chemistry procurement mandates:Specialty chemical buyers in Germany and the United States are embedding non-volatile solvent requirements into supplier qualification protocols.
Market Restraints
- Halide salt feedstock volatility:Price swings in imidazolium precursor supply chains compress formulation margins for specialty electrolyte producers.
- Toxicological data gaps:Incomplete ecotoxicity profiles for emerging pyridinium and phosphonium chemistries delay regulatory approvals under REACH and EPA New Chemicals programs.
- Protic solvent substitution:Deep eutectic solvents offer comparable non-volatility at lower synthesis cost for extraction and catalysis applications.
Strategic Opportunities
- Pharmaceutical continuous manufacturing:Flow chemistry adopters in Japan and South Korea are specifying task-specific ionic liquids for integrated reaction-separation sequences.
- Carbon capture absorption media:Post-combustion capture developers are screening amine-functionalized ionic liquids for enhanced CO2 binding capacity and reduced regeneration energy.
- Electrochemical capacitor electrolytes:Supercapacitor manufacturers are validating ionic liquid formulations for extended voltage windows and elevated temperature operation.
Industry Challenges
- Electrolyte-grade purification scale-up:Achieving parts-per-billion impurity levels for battery applications requires capital-intensive distillation and crystallization infrastructure.
- Cross-functional formulation expertise:Synthesis chemists, electrochemists, and regulatory specialists rarely co-locate within single organizations, constraining product development velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ionic Liquids Market |
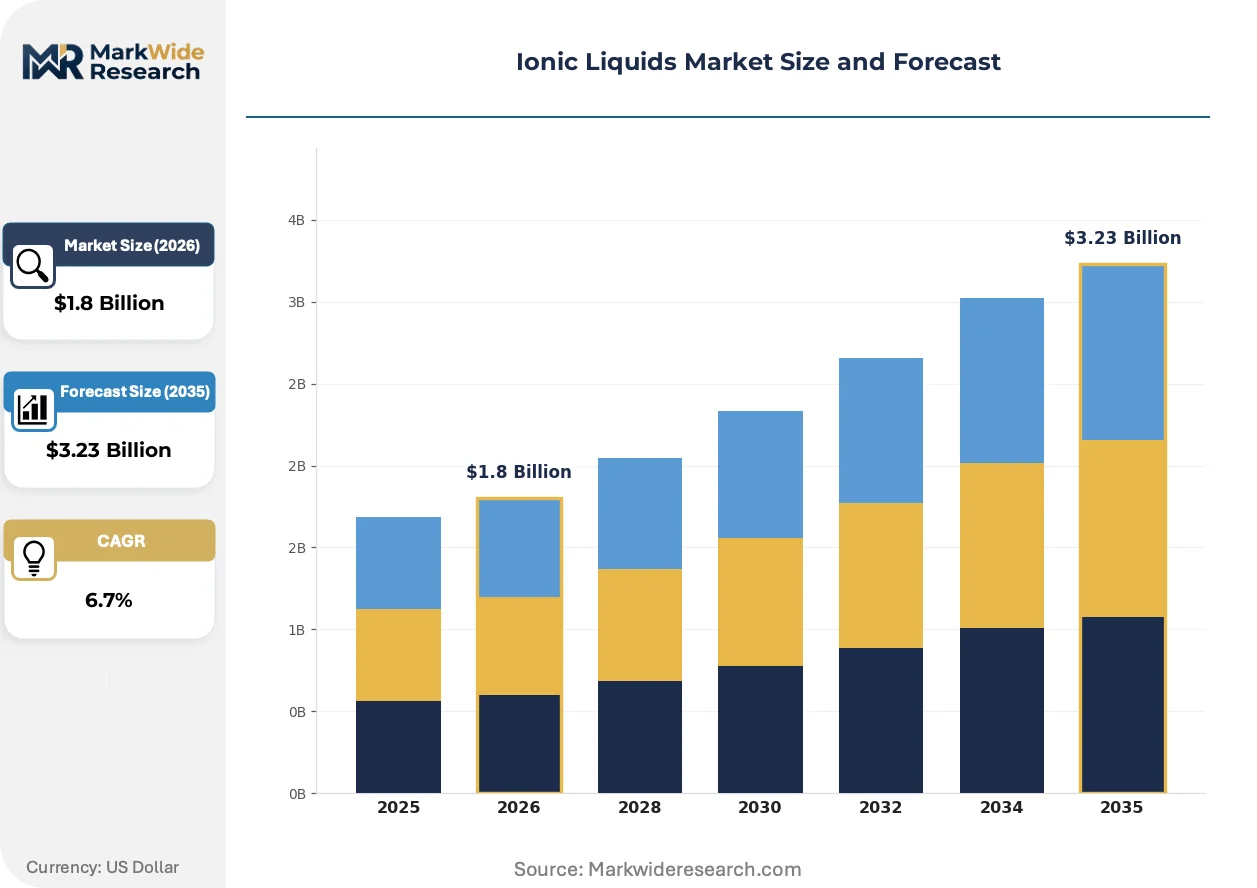
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 1-Butyl-3-Methylimidazolium, 1-Ethyl-3-Methylimidazolium, 1-Hexyl-3-Methylimidazolium, 1-Octyl-3-Methylimidazolium Application: Synthesis, Solvent Extraction, Electrochemistry, Separation Processes End User: Chemical Industry, Pharmaceutical Sector, Petrochemical Industry, Energy Sector Functionality: Solvent, Catalyst, Electrolyte, Phase-Transfer Agent |
| Companies Covered | Ionic Liquids Technologies GmbH, proionic, BASF SE, The Chemours Company, Solvionic SA, Merck KGaA, Solvay, Tatva Chintan Pharma Chem Pvt. Ltd., Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ionic Liquids Market Emerging Trajectories
Synthesis methodologies and application specifications are diverging as battery-grade purity requirements separate from industrial solvent commodity streams, creating distinct technical and commercial tracks within the category.
Task-specific ionic liquid design is migrating from empirical composition screening toward computational prediction of physicochemical properties. Materials informatics platforms are accelerating cation-anion pairing decisions for target conductivity and viscosity profiles. Solid-state battery developers are adopting these predictive workflows to compress electrolyte qualification timelines from years to months.
EPA's implementation of stricter volatile organic compound thresholds under the Clean Air Act is compelling U.S. coating and adhesive formulators to eliminate traditional hydrocarbon solvents. Ionic liquid alternatives are capturing specification share in high-value segments where thermal stability justifies unit cost premiums. State-level green chemistry procurement incentives in California and Massachusetts are amplifying this regulatory pull.
Electrolyte procurement by lithium-ion cell manufacturers is consolidating around qualified supplier lists with locked formulation specifications. Long-term offtake agreements are displacing spot market purchasing for ionic liquid components, mirroring cathode active material contracting patterns. Chinese battery producers are driving this structural shift, leveraging volume commitments to secure dedicated production capacity from specialty chemical suppliers.
Ionic Liquids Market Segmentation
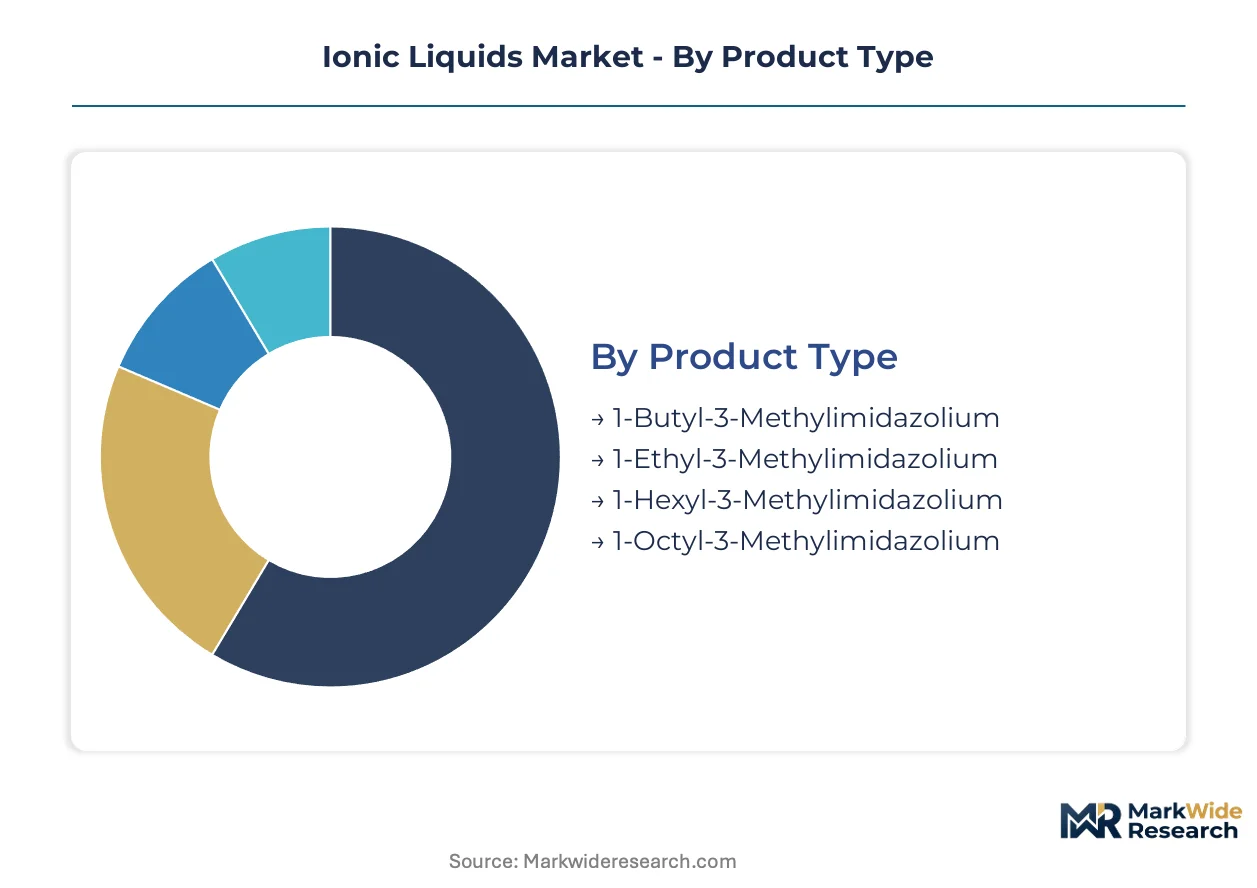
Segmentation in ionic liquids reveals how synthesis complexity and application purity requirements fragment commercial opportunities across distinct technical and commercial tracks. Each category exposes different margin structures, from commodity imidazolium salts to electrolyte-grade formulations commanding qualification premiums.
Product Type:
After-sales service intensity escalates with carbon chain length as longer-alkyl imidazolium variants require specialized handling protocols and application engineering support.
- 1-Butyl-3-Methylimidazolium:The four-carbon alkyl chain delivers optimal viscosity-conductivity balance for battery electrolyte formulations. Demand concentrates in solid-state battery development programs across Germany, Japan, and South Korea where thermal stability specifications exceed 300°C decomposition thresholds.
- 1-Ethyl-3-Methylimidazolium:Shorter ethyl substitution yields lower viscosity profiles suited to high-throughput pharmaceutical catalysis. Chinese and Indian pharmaceutical manufacturers specify this variant for continuous flow chemistry implementations requiring rapid mass transfer.
- 1-Hexyl-3-Methylimidazolium:Six-carbon hydrophobicity enables liquid-liquid extraction applications in rare earth separation circuits.
- 1-Octyl-3-Methylimidazolium:Maximum alkyl chain length in this family targets specialized lubricant and antistatic additive formulations.
By volume, 1-Butyl-3-Methylimidazolium leads. By growth pace, 1-Ethyl-3-Methylimidazolium is ahead.
Application:
Cost tier differentiation separates commodity solvent replacement from qualified electrolyte supply where purification infrastructure investments dominate economics.
- Synthesis:Catalytic applications leverage ionic liquids as reaction media for Friedel-Crafts alkylation and hydrogenation chemistry. BASF and Solvay operate dedicated production trains for pharmaceutical and fine chemical contract manufacturers in Belgium and Germany.
- Solvent Extraction:Non-volatile extraction media replace toluene and dichloromethane in metal recovery and natural product isolation. REACH compliance deadlines in Europe and EPA Clean Air Act enforcement in the United States accelerate substitution timelines for volatile organic compound elimination.
- Electrochemistry:Fastest-expanding application category as lithium-metal cell developers validate ionic liquid electrolytes for dendrite suppression and elevated temperature cycling stability.
- Separation Processes:Gas absorption and membrane separation applications exploit tunable solubility parameters for selective CO2 and hydrocarbon capture.
Electrochemistry commands the steepest price premiums. Synthesis maintains the largest installed consumption base.
End User:
Customer type determines specification stringency, with battery producers imposing parts-per-billion purity requirements that pharmaceutical formulators rarely match.
- Chemical Industry:Broadest adoption base spanning commodity solvent replacement and specialized catalysis. German specialty chemical manufacturers embed green chemistry procurement mandates requiring non-volatile alternatives in supplier qualification protocols.
- Pharmaceutical Sector:Flow chemistry adopters in Japan and South Korea specify task-specific ionic liquids for integrated reaction-separation sequences. Regulatory filing requirements for residual solvent limits under ICH Q3C drive ionic liquid specification in final drug substance manufacturing.
- Petrochemical Industry:Alkylation and oligomerization catalysis applications exploit thermal stability above 200°C for refinery integration.
- Energy Sector:Electrochemical energy storage applications span supercapacitor electrolytes and solid-state battery development programs. Chinese cell manufacturers consolidate procurement around qualified supplier lists with locked formulation specifications.
The chemical industry consumes the most volume. The energy sector is climbing the fastest.
Functionality:
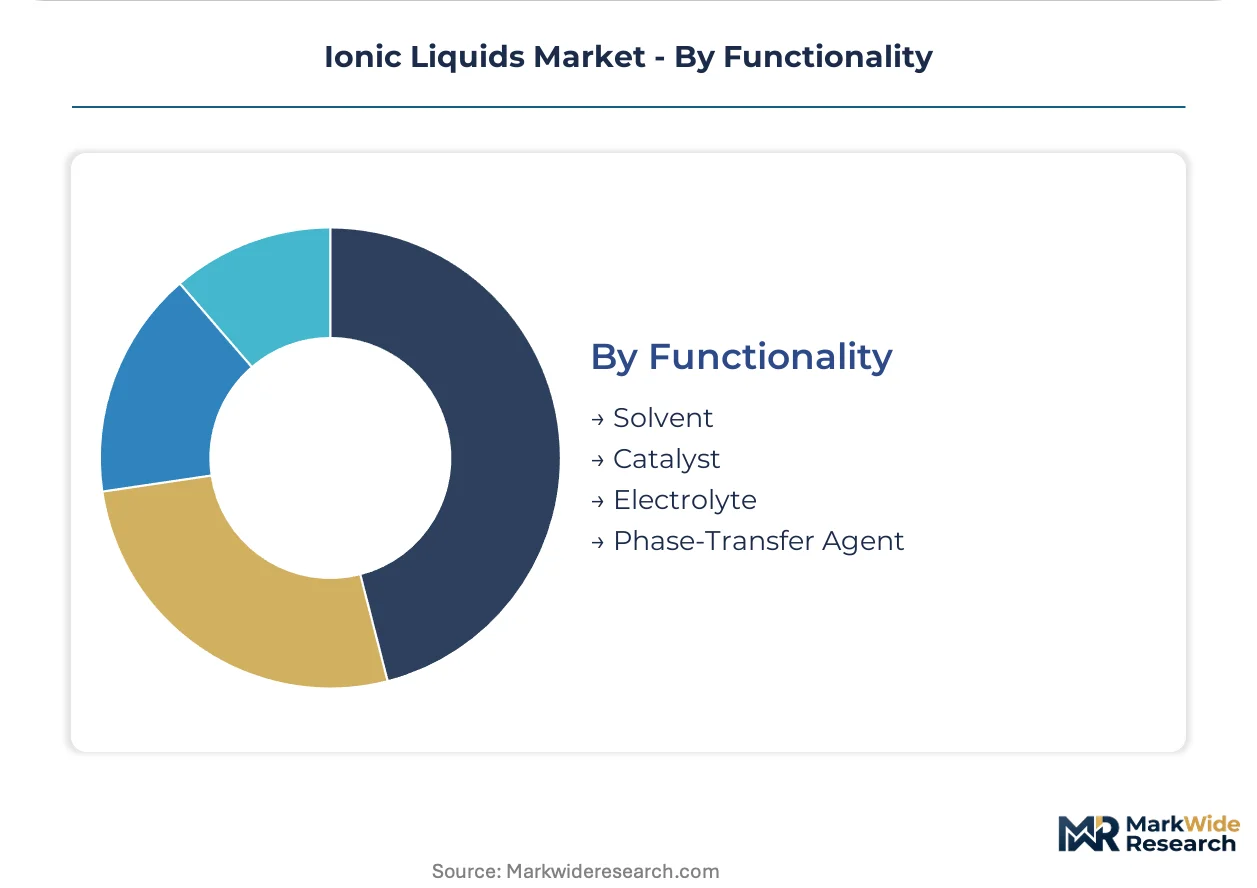
Margin structure varies sharply by functionality, with electrolyte qualification timelines stretching 18-36 months versus solvent spot market availability.
- Solvent:Primary commercial function replacing volatile organic compounds in extraction, cleaning, and reaction media. EPA volatile organic compound thresholds and ECHA REACH registration requirements accelerate specification in U.S. and European manufacturing.
- Catalyst:Acidic and basic ionic liquids enable homogeneous catalysis with simplified product recovery versus traditional Lewis acid systems. Japanese pharmaceutical continuous manufacturing adopters specify task-designed catalytic ionic liquids for selective transformations.
- Electrolyte:Battery-grade functionality demands sub-ppm halide and water content achieved through multi-stage purification. Solid-state battery developers in South Korea and Germany specify ionic liquid blends for enhanced ionic transport and thermal stability.
- Phase-Transfer Agent:Quaternary ammonium and phosphonium variants facilitate biphasic reactions with controlled interfacial activity.
Solvent functionality dominates current volume. Electrolyte functionality is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese battery manufacturers exhibit the lowest price elasticity as they lock in multi-year offtake agreements for electrolyte-grade formulations, while European industrial solvent buyers remain highly sensitive to unit cost premiums despite regulatory pressure.
United States
Solid-state battery developers in California and Massachusetts drive specialty electrolyte procurement. EPA Clean Air Act enforcement tightens volatile organic compound thresholds for coating and adhesive formulators. Boston-area research clusters advance predictive materials informatics for ionic liquid property screening.
Germany
Specialty chemical manufacturers embed green chemistry mandates into supplier qualification protocols. ECHA REACH registration pathways streamline toxicological data requirements for novel ionic liquid categories. The Rhine-Ruhr industrial corridor hosts BASF SE's scaled imidazolium salt production for pharmaceutical and battery customers.
China
Lithium-ion cell producers consolidate procurement around qualified supplier lists with locked formulation specifications. MEE dual carbon goals favor non-volatile solvents in industrial process redesign. Yangtze River Delta battery clusters leverage volume commitments to secure dedicated ionic liquid production capacity.
Japan
Pharmaceutical continuous manufacturing adopters specify task-specific ionic liquids for integrated reaction-separation sequences. METI supports flow chemistry infrastructure investments through national technology roadmaps. Osaka-Kansai chemical engineering hubs validate ionic liquid catalysis for selective transformations.
South Korea
Lithium-metal cell developers validate ionic liquid electrolytes for dendrite suppression and elevated temperature cycling. National battery safety standards mandate enhanced thermal stability specifications. Seoul Capital Area research institutes collaborate with cell manufacturers on solid-state electrolyte qualification timelines.
Ionic Liquids Market Vendor Landscape
Integrated chemical conglomerates and specialized ionic liquid producers split the market between scale-driven commodity supply and qualification-intensive electrolyte formulations. The structure concentrates around three strategic archetypes: diversified chemical majors with captive raw material access, focused ionic liquid specialists with purification expertise, and regional pharmaceutical chemical suppliers with cost-optimized synthesis routes. Competitive moves center on backward integration into halide salt feedstocks and long-term offtake contracting with battery cell manufacturers.
Among European integrated players, BASF SE and Solvay occupy positions anchored in industrial-scale imidazolium production and REACH-compliant supply chains. Solvionic SA exemplifies the specialist archetype with concentrated expertise in electrochemistry-grade formulation. Tatva Chintan Pharma Chem Pvt. Ltd. represents the Asia-Pacific cost-optimization segment serving pharmaceutical catalysis demand through efficient synthesis routes.
| Leading Market Players |
|---|
| Ionic Liquids Technologies GmbH |
| proionic |
| BASF SE |
| The Chemours Company |
| Solvionic SA |
| Merck KGaA |
| Solvay |
| Tatva Chintan Pharma Chem Pvt. Ltd. |
| Evonik Industries AG |
| Others |
Supply Flow & Price Mechanics
The Rhine-Ruhr corridor's scaled imidazolium production capacity anchors European pricing power for battery-grade formulations, while Chinese Yangtze River Delta clusters leverage volume commitments to compress unit costs for pharmaceutical solvent buyers. This geographic bifurcation creates divergent margin structures between qualification-intensive electrolyte supply and commodity catalysis applications.
Pricing Analysis
After-sales formulation support and long-term technical service contracts drive lifetime value for specialty electrolyte producers. Three-tier pricing structure across electrolyte-grade, technical-grade, and industrial-grade levels reflects purification investment and qualification timeline differentials. Cost compression in commodity imidazolium salts intensifies as Indian and Chinese manufacturers scale cost-optimized synthesis routes. Pharmaceutical formulators in Japan and South Korea exhibit lowest price sensitivity due to regulatory filing requirements, while European industrial solvent buyers remain highly elastic despite REACH compliance deadlines.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for halide salt feedstock procurement. Manufacturing concentrates in Germany, Belgium, and China for imidazolium salt production, with India emerging as a cost-competitive alternative for pharmaceutical-grade supply. Production draws from N-methylimidazole and alkyl halide precursors whose price volatility feeds directly into formulation economics. Single-source vulnerability exists for ultra-high-purity electrolyte grades requiring proprietary distillation infrastructure. Distribution runs through qualified supplier lists with locked specifications for battery manufacturers, contrasting with spot-market availability for industrial solvent applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state battery electrolyte adoption represents a high-growth disruption as lithium-metal cell developers validate ionic liquid formulations for dendrite suppression and thermal stability beyond 300°C. EPA Clean Air Act enforcement and ECHA REACH registration pathways provide concurrent regulatory tailwinds accelerating volatile organic compound substitution.
For Market Incumbents: Entrench qualification advantages by securing long-term offtake agreements with South Korean and German battery cell manufacturers before secondary suppliers achieve electrolyte-grade purification scale. Expand captive production of N-methylimidazole feedstocks to insulate margins from halide salt price volatility. Deepen application engineering capabilities for solid-state battery developers to extend service revenue streams. For New Entrants and Emerging Players: North American pharmaceutical continuous manufacturing presents underpenetrated white space where flow chemistry adopters seek task-specific ionic liquid suppliers outside established European networks. Carbon capture absorption media development programs offer second entry vector with reduced qualification barriers versus battery-grade supply. Partner with research institutes in Massachusetts or California to leverage predictive materials informatics for accelerated cation-anion pairing optimization. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical majors with underutilized imidazolium production assets lacking electrolyte-grade purification infrastructure. Position for 5-10 year holding periods as solid-state battery commercialization scales from pilot to production volumes. Monitor South Korean national battery safety standard revisions as inflection indicator for thermal stability specification tightening.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Halide Feedstocks | BASF and Solvay secure N-methylimidazole supply to compress formulation margins against Asian competitors. |
| Long-term Supply Agreement with Battery OEMs | Chinese cell manufacturers lock dedicated production capacity through multi-year offtake commitments. |
| Green Manufacturing Transition | REACH-compliant producers capture specification share as EPA Clean Air Act enforcement tightens VOC thresholds. |
| Joint Venture for Purification Scale-Up | Solvionic SA partnerships address capital-intensive infrastructure for parts-per-billion impurity achievement. |
| Capacity Expansion in Qualified Hubs | Rhine-Ruhr and Yangtze River Delta clusters add electrolyte-grade trains to serve locked supplier lists. |
Methodological Framework
Desk research of customs trade data, ECHA REACH registration databases, and SEC chemical company filings preceded structured interviews with battery cell procurement directors, pharmaceutical process development chemists, ionic liquid plant managers, and specialty chemical distribution partners. Primary fieldwork validated synthesis capacity estimates and qualification timeline assumptions across German, Chinese, and South Korean manufacturing hubs. Secondary sources included Cefic solvent market reports, EPA enforcement action records, and METI technology roadmap disclosures. Bottom-up segment sizing triangulated against top-down chemical industry value chain analysis.
Assumptions held fixed include sustained EPA Clean Air Act enforcement trajectory, ECHA REACH registration pathway continuity, and solid-state battery developer electrolyte specification adoption rates. Variables tested across the analysis window encompassed halide salt feedstock price scenarios, regional battery production capacity buildout pacing, and pharmaceutical continuous manufacturing penetration rates. Segmentation modeling incorporated product type carbon chain length, application purity tier, end-user industry, and regional regulatory cluster dimensions. CAGRs derived from volume-weighted average of segment growth rates adjusted for substitution elasticity and qualification lag effects.
Macroeconomic conditions sit as an overlay; deviation in battery electric vehicle adoption curves or European industrial production indices would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and technology qualification timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Diethylene Glycol Monobutyl Ether Market
Solvents
Solvent Recovery Systems Market
Solvents
Mono Propylene Glycol Market
Solvents
Acetone Derivatives Market
Solvents
Dimethyl Sulfoxide Market
Solvents
Ethoxydiglycol Market
Solvents
Coating Solvents Market
Solvents
Global Ink Solvents Market
Solvents
1,2-Ethanedithiol Market
Solvents
Global Solvent Evaporation Market
Solvents
Ethane Market
Solvents
Hydrocarbon Solvents Market
Solvents
Global Droppers Market
Solvents
Ketone-Based Solvents Market
Solvents
Global Furfural Solvent Market
Solvents
Diethyl Ether Market