
 C2 Chlorinated Solvents Market | 2026-2036
C2 Chlorinated Solvents Market Size, Share, and Industry Trends Forecast 2026-2036
C2 Chlorinated Solvents Market Outlook
Pharmaceutical manufacturing is restructuring its solvent procurement patterns, shifting toward specialized chlorinated grades that meet stricter purity protocols. Dow Chemical Company leverages its integrated chlor-alkali chain to sustain cost leadership in methylene chloride supply. Solvay anchors European supply through its fluorinated chemistry co-product streams, while INEOS competes on bulk perchloroethylene scale across industrial degreasing channels.
C2 chlorinated solvents comprise a family of halogenated hydrocarbons—methylene chloride, trichloroethylene, perchloroethylene, and chloroform—manufactured primarily through methane chlorination or ethylene oxychlorination routes, valued for high solvency power and low flammability in precision cleaning applications. The product type dimension shows perchloroethylene occupying mature, high-volume positions in dry cleaning and vapor degreasing, while methylene chloride leads growth in pharmaceutical extraction and paint stripping formulations. Application segmentation reveals degreasing as the dominant value pool, though chemical processing margins are widening as specialty pharmaceutical intermediates demand higher-specification grades.
The US EPA's Toxic Substances Control Act risk evaluations and OSHA's methylene chloride exposure standards are forcing reformulation investments across metal finishing and adhesive manufacturing sectors. Europe's REACH restrictions and ECHA classification updates on carcinogenicity are reshaping import requirements and substitution economics. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate which product grades will retain market access versus face phasedown pressures.
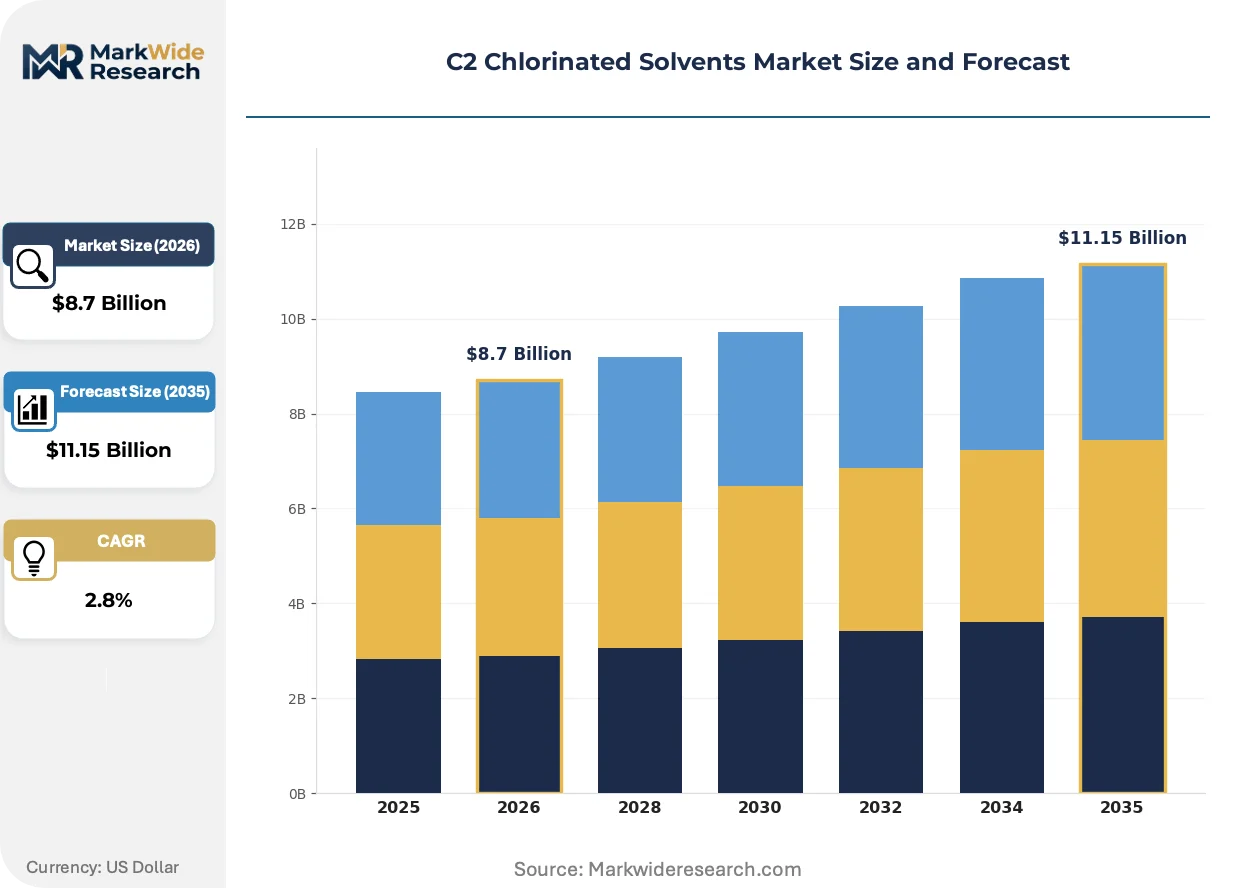
Market Dynamics
Pharmaceutical extractors and precision metal finishers are consolidating procurement around higher-purity chlorinated grades as EPA workplace exposure limits tighten and downstream liability frameworks harden. This regulatory compression is redrawing competitive boundaries between commodity chlor-alkali producers and specialty purification houses.
Growth Catalysts
- Pharmaceutical extraction protocols:Active pharmaceutical ingredient manufacturers are specifying ultra-low-residue methylene chloride for natural product isolation, creating demand for certified pharmaceutical-grade supply tiers.
- REACH authorization timelines:ECHA's staggered sunset date extensions for specific solvent applications are preserving market access for compliant European producers while accelerating substitution investments elsewhere.
- China's eastern manufacturing corridor:Jiangsu and Zhejiang provinces are concentrating vapor degreasing demand as automotive component and electronics contract manufacturers expand captive cleaning capacity.
Market Restraints
- Chlorine feedstock volatility:Electrolytic caustic soda demand swings and energy price spikes transmit directly into methylene chloride and perchloroethylene production economics.
- Substitution by aqueous precision cleaning:Semiconductor and medical device manufacturers are validating surfactant-based and CO2-based systems for sub-micron particle removal applications.
- OSHA methylene chloride exposure mandates:The agency's reduced permissible exposure limits are forcing capital expenditure on engineered ventilation and closed-loop systems across metal finishing shops.
Strategic Opportunities
- India's specialty chemical expansion:CDSCO's streamlined bulk drug approval pathways are attracting contract manufacturing organizations seeking chlorinated solvent-based extraction capacity.
- Refrigerant feedstock conversion:Trichloroethylene's role as a hydrofluorocarbon precursor is creating dedicated offtake agreements as F-Gas Regulation phase-downs accelerate in Europe.
- Closed-loop solvent recovery services:On-site distillation and reclamation contracts are displacing virgin solvent purchases among mid-sized metalworking clusters in Germany's industrial Mittelstand.
Industry Challenges
- Process safety engineering talent:Chlorinated solvent handling expertise—thermal stability management, corrosion metallurgy, and emissions containment—is retiring faster than vocational programs replenish supply.
- Cross-jurisdictional compliance mapping:Divergent carcinogenicity classifications between EPA, IARC, and national EU competent authorities are fragmenting product stewardship documentation requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | C2 Chlorinated Solvents Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $11.15 Billion |
| CAGR (2026 – 2036) | 2.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Methylene Chloride, Trichloroethylene, Perchloroethylene, Chloroform Application: Degreasing, Paint Thinning, Adhesive Manufacturing, Chemical Processing End User: Aerospace, Automotive, Manufacturing, Pharmaceuticals Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors |
| Companies Covered | Dow Chemical Company, Solvay, Westlake Chemical Corporation, 3M, INEOS, Occidental Chemical Corporation, PPG Industries, Kem One, Shin-Etsu Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
C2 Chlorinated Solvents Market Strategic Shifts
Process intensification and regulatory foresight are becoming the primary axes of differentiation as solvent suppliers compete on lifecycle compliance rather than unit cost alone. The sector is witnessing accelerated bifurcation between commodity bulk supply and certified application-specific grades.
Membrane-based solvent dehydration and molecular sieve purification are absorbing the quality assurance burden previously managed through multi-stage distillation. Pharmaceutical contract manufacturers in Switzerland and Singapore are adopting these systems to guarantee sub-ppm moisture specifications for hygroscopic API synthesis. The technology is compressing capital recovery timelines for purification investments while raising barriers for producers lacking integrated quality infrastructure.
EPA's revised risk evaluation under TSCA is triggering reformulation mandates across adhesive and coating sectors that historically relied on methylene chloride paint stripping formulations. Industrial users are retrofitting equipment for alternative chemistries or relocating processes to jurisdictions with less stringent exposure thresholds. Metal refinishing operations in Mexico's border states are capturing displaced North American demand as compliance costs rise.
Buyer consolidation among multinational pharmaceutical and agrochemical formulators is compressing supplier qualification cycles and unbundling technical service from material supply contracts. Procurement teams at top-ten drug manufacturers are mandating solvent-as-a-service arrangements with guaranteed purity certificates and reclamation guarantees. This restructuring is most visible in the Rhine-Main chemical cluster, where integrated logistics providers are assuming inventory and compliance liability from traditional distributors.
C2 Chlorinated Solvents Market Segmentation
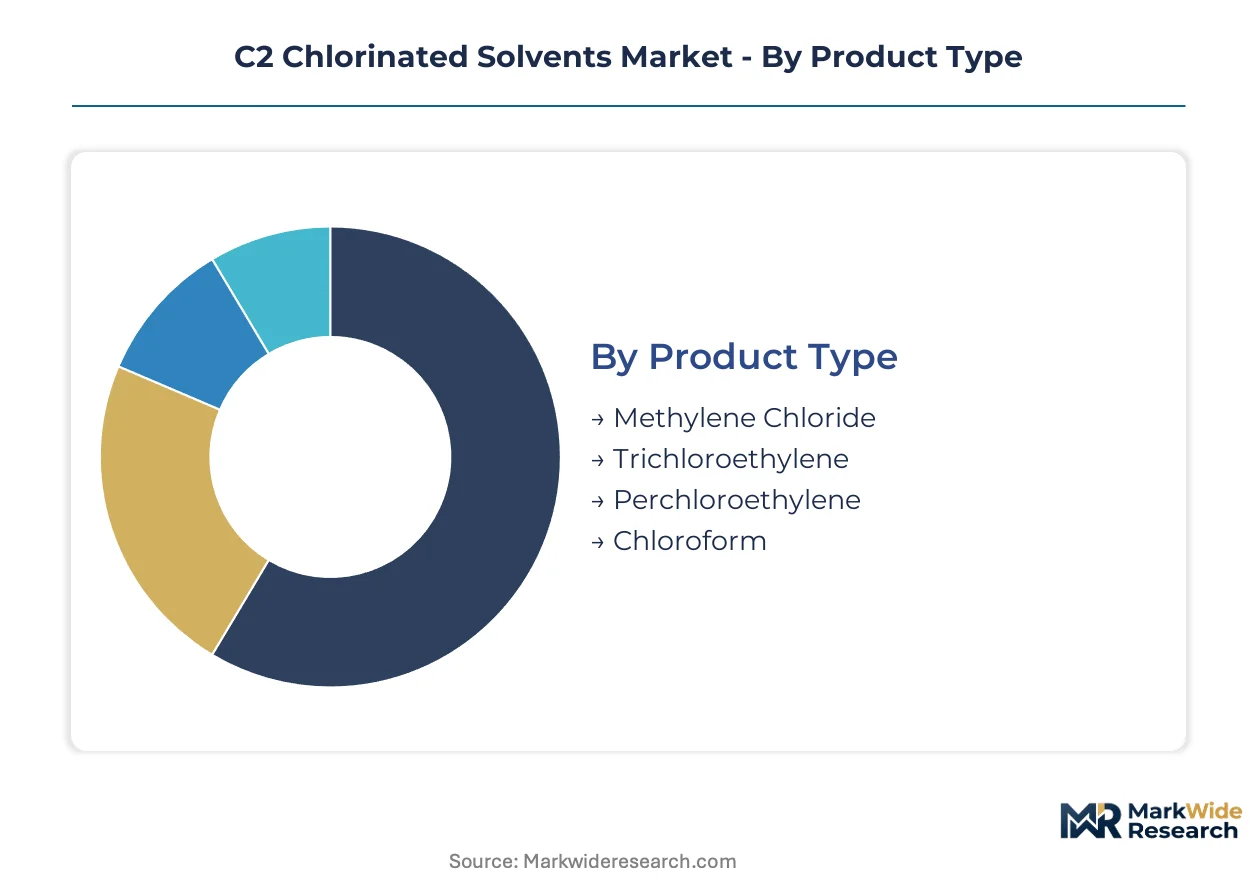
Segmentation in the C2 chlorinated solvents market reveals how regulatory pressure and application-specific purity requirements are fragmenting what was historically a commodity chemical trade into tiered supply relationships. Buyers now select grades based on certification protocols rather than solvency metrics alone.
Product Type:
Buyers differentiate primarily by vapor pressure specifications and residue limits, with pharmaceutical extractors demanding sub-ppm contaminant thresholds that commodity metal finishers ignore.
- Methylene Chloride:A dichloromethane compound with the lowest boiling point among C2 chlorinated solvents, prized for rapid evaporation in precision cleaning. Pharmaceutical API manufacturers in Switzerland and Singapore are consolidating procurement around pharmaceutical-grade supply tiers as FDA extraction protocol validations tighten. Chlor-alkali producers with integrated purification infrastructure capture margin premiums unavailable to bulk commodity suppliers.
- Perchloroethylene:A fully chlorinated ethylene derivative with exceptional thermal stability and non-flammability, dominating vapor degreasing and dry cleaning applications. Jiangsu province metalworking clusters are expanding captive cleaning capacity using this solvent, though REACH authorization timelines are compressing long-term demand visibility in Europe. Volume concentration remains in mature industrial channels while substitution pressure accelerates in textile care.
- Trichloroethylene:A chlorinated solvent with intermediate boiling range, serving precision degreasing and hydrofluorocarbon precursor markets. F-Gas Regulation phase-downs in Europe are redirecting offtake toward refrigerant feedstock conversion agreements.
- Chloroform:A trihalomethane historically used in pharmaceutical synthesis and laboratory applications. ECHA carcinogenicity classifications have restricted industrial use to closed-system chemical processing with stringent emissions containment.
Volume sits with perchloroethylene in mature degreasing channels; growth tilts toward methylene chloride in pharmaceutical extraction applications.
Application:
Margin structures diverge sharply between commodity industrial cleaning and certified chemical processing, with the latter commanding price multiples for documentation and liability transfer.
- Degreasing:The dominant value pool encompassing metal finishing, electronics assembly, and automotive component cleaning. China's eastern manufacturing corridor is concentrating vapor degreasing demand as contract manufacturers expand captive capacity, though OSHA's reduced methylene chloride exposure limits are forcing ventilation capital expenditure across US metalworking shops.
- Chemical Processing:Specialty pharmaceutical intermediate synthesis and agrochemical formulation requiring ultra-low moisture and residue specifications. Membrane-based dehydration systems are absorbing quality assurance burdens previously managed through multi-stage distillation, compressing capital recovery timelines for integrated producers.
- Paint Thinning:Methylene chloride-based stripping formulations facing EPA TSCA reformulation mandates. Industrial users are retrofitting equipment for alternative chemistries or relocating processes to jurisdictions with less stringent exposure thresholds.
- Adhesive Manufacturing:Solvent-based bonding systems in industrial tape and sealant production. Regulatory compression is redrawing procurement patterns toward specialized chlorinated grades with documented purity certificates.
Revenue concentrates in degreasing at volume scale; chemical processing expands most quickly on margin expansion from pharmaceutical-grade certification requirements.
End User:
Procurement sophistication varies by liability exposure, with aerospace and pharmaceutical buyers mandating solvent-as-a-service arrangements that unbundle technical compliance from material supply.
- Pharmaceuticals:Active pharmaceutical ingredient manufacturers specifying ultra-low-residue grades for natural product isolation and synthesis. CDSCO's streamlined bulk drug approval pathways in India are attracting contract manufacturing organizations seeking chlorinated solvent-based extraction capacity.
- Aerospace:Precision component cleaning for turbine blades and avionics assemblies requiring sub-micron particle removal. Surfactant-based and CO2-based systems are validating substitution pathways for semiconductor and medical device adjacent applications.
- Automotive:Powertrain component degreasing and surface preparation for coating adhesion. China's automotive component suppliers are expanding vapor degreasing capacity in Jiangsu and Zhejiang provinces.
- Manufacturing:General industrial metal finishing and maintenance cleaning across mid-sized metalworking clusters. Germany's industrial Mittelstand is displacing virgin solvent purchases through on-site distillation and reclamation contracts.
Procurement volume aggregates in manufacturing; contract value climbs fastest in pharmaceuticals through integrated service arrangements.
Distribution Channel:
Channel selection reflects buyer scale and compliance burden, with large formulators bypassing intermediaries while mid-tier users rely on distributors for inventory and documentation management.
- Direct Sales:Large-volume pharmaceutical and agrochemical formulators negotiating solvent-as-a-service contracts with guaranteed purity certificates and reclamation guarantees. The Rhine-Main chemical cluster shows integrated logistics providers assuming inventory and compliance liability from traditional distributors.
- Distributors:Regional chemical distributors managing qualification documentation and smaller lot fulfillment for mid-sized metal finishers and adhesive manufacturers. REACH authorization timelines are fragmenting product stewardship requirements across European national competent authorities.
- Wholesalers:Bulk volume handlers serving commodity industrial degreasing channels with limited value-added services. Price transparency compresses margins in this channel.
- Online Retail:Small-lot specialty grades for laboratory and research applications with expedited documentation delivery. Limited penetration in regulated industrial channels due to certification complexity.
Transaction volume flows through distributors; contract value and margin expansion concentrate in direct sales relationships with large formulators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's eastern chemical manufacturing corridor operates under special economic zone incentives that concentrate chlorinated solvent demand in Jiangsu and Zhejiang provinces. These zones attract automotive component and electronics contract manufacturers expanding captive vapor degreasing capacity. The clustering effect intensifies procurement consolidation around integrated chlor-alkali suppliers.
United States
Pharmaceutical API manufacturers in New Jersey and Pennsylvania are restructuring procurement toward pharmaceutical-grade methylene chloride as FDA extraction protocol validations tighten. EPA's revised TSCA risk evaluation is forcing reformulation investments across adhesive manufacturing in Ohio and Michigan. Metal finishing shops in these states face capital expenditure pressure from OSHA's reduced permissible exposure limits for methylene chloride.
Germany
Mid-sized metalworking clusters in Baden-Württemberg and Bavaria are displacing virgin solvent purchases through on-site distillation and reclamation contracts. ECHA's REACH authorization timelines are fragmenting product stewardship requirements across national competent authorities. The industrial Mittelstand in these regions is driving closed-loop solvent recovery service adoption to manage compliance liability.
China
Automotive component suppliers in Jiangsu province are expanding vapor degreasing capacity using perchloroethylene. MIIT's dual carbon goals are tightening emissions containment standards for chlorinated solvent handling facilities. The Yangtze River Delta chemical manufacturing corridor is concentrating demand as contract manufacturers scale captive cleaning operations for electronics exports.
India
Contract manufacturing organizations in Gujarat and Maharashtra are seeking chlorinated solvent-based extraction capacity following CDSCO's streamlined bulk drug approval pathways. The country's national pharmaceutical regulator is aligning inspection protocols with FDA standards to attract multinational API sourcing. Chemical processing clusters in these states are upgrading purification infrastructure to meet pharmaceutical-grade specifications.
Switzerland
Pharmaceutical contract manufacturers in Basel and the Rhine-Main corridor are adopting membrane-based solvent dehydration systems to guarantee sub-ppm moisture specifications. Swissmedic's quality certification requirements are compressing supplier qualification cycles toward solvent-as-a-service arrangements. Integrated logistics providers in this region are assuming inventory and compliance liability from traditional distributors.
C2 Chlorinated Solvents Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated chlor-alkali producers capturing margin premiums in pharmaceutical-grade tiers while commodity suppliers compete on bulk industrial degreasing volume. The market structure favors producers with captive chlorine feedstock and purification infrastructure. Three archetypes dominate: integrated chemical conglomerates with chlor-alkali chains, European fluorinated chemistry specialists leveraging co-product streams, and regional bulk distributors serving metalworking clusters. Competitive moves concentrate on backward integration into chlorine supply and geographic expansion through logistics partnerships.
Among North American integrated producers, Dow Chemical Company and Occidental Chemical Corporation exemplify the chlor-alkali conglomerate archetype with cost leadership positions in methylene chloride supply. Solvay anchors European supply capabilities through its fluorinated chemistry operations, while INEOS occupies a position in bulk perchloroethylene scale across industrial channels. These three companies represent the tiered competitive structure where feedstock integration and purification infrastructure determine margin capture.
| Leading Market Players |
|---|
| Dow Chemical Company |
| Solvay |
| Westlake Chemical Corporation |
| 3M |
| INEOS |
| Occidental Chemical Corporation |
| PPG Industries |
| Kem One |
| Shin-Etsu Chemical |
| Others |
Value Chain & Pricing Dynamics
Chlor-alkali feedstock indices cascade through C2 chlorinated solvent supply chains into three distinct pricing tiers: pharmaceutical-grade methylene chloride commands certification premiums, industrial perchloroethylene trades on volume contracts, and spot bulk grades fluctuate with caustic soda and energy input costs. Buyers in Switzerland and Singapore absorb lead-time premiums for sub-ppm moisture specifications, while metal finishers in China's eastern corridor negotiate captive supply arrangements that compress delivered pricing through integrated chlor-alkali ownership.
Pricing Analysis
Short lead-time premiums separate urgent pharmaceutical-grade orders from scheduled industrial offtake, with Swiss and Singaporean API manufacturers paying substantial markups for expedited certification documentation. Three-tier pricing structure across pharmaceutical-grade, technical-grade, and bulk industrial levels reflects purity certification and liability transfer bundling. Cost compression in commodity perchloroethylene is intensifying because REACH authorization uncertainty is extending buyer commitment horizons and pressuring spot market liquidity. Mid-sized metalworking clusters in Germany exhibit highest price sensitivity, while pharmaceutical formulators prioritize specification compliance over unit cost.
Supply Chain Analysis
Process safety engineering talent shortages in Jiangsu province and the US Gulf Coast are constraining capacity expansion timelines and elevating construction cost premiums for chlorinated solvent handling facilities. Manufacturing concentrates in China, the United States, and Germany, with each hub serving distinct regulatory jurisdictions and purity requirements. Feedstock draws from electrolytic chlorine, ethylene derivatives, and methane chlorination intermediates. Single-source vulnerability runs through European fluorinated chemistry co-product streams where Solvay's supply anchors regional availability. Distribution runs through integrated logistics providers in the Rhine-Main corridor and regional chemical distributors serving mid-tier metal finishers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
C2 chlorinated solvent supply is becoming a vertical-integration race where chlorine feedstock control and purification infrastructure determine margin capture. Players are pursuing captive chlor-alkali capacity as the decisive upstream lever to secure cost position and pharmaceutical-grade certification capability.
For Market Incumbents: Anchor market position through backward integration into chlorine supply and membrane-based purification infrastructure investments that pharmaceutical formulators now mandate for supplier qualification. Defend against aqueous precision cleaning substitution by embedding closed-loop solvent recovery services into long-term supply contracts. Capacity addition in India's Gujarat and Maharashtra chemical clusters captures CDSCO-aligned pharmaceutical extraction demand before contract manufacturing organizations consolidate supplier relationships. For New Entrants and Emerging Players: India's contract manufacturing organizations seeking chlorinated solvent-based extraction capacity represent the most penetrable buyer archetype, underserved by integrated global suppliers focused on established pharmaceutical corridors. Specialty purification houses serving mid-sized API manufacturers in Switzerland and Singapore offer white-space entry where certification burden exceeds commodity chlor-alkali producer capabilities. Go-to-market positioning as solvent-as-a-service providers with guaranteed purity certificates and reclamation guarantees unbundles technical compliance from material supply. For Investors and Strategic Acquirers: Distressed-cycle entries favor European fluorinated chemistry specialists with co-product stream advantages in Germany and Belgium, where REACH authorization timelines are compressing valuation multiples for non-integrated assets. Long-term viability over a multi-year horizon rests on regulatory foresight capabilities and pharmaceutical-grade infrastructure ownership rather than commodity scale. Monitor ECHA carcinogenicity classification divergence from EPA and IARC frameworks as the critical inflection signal for which product grades retain market access versus face accelerated substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlor-Alkali Feedstock | Captive chlorine supply secures cost leadership against volatile electrolytic caustic soda pricing swings. |
| Pharmaceutical-Grade Purification Infrastructure | Membrane-based dehydration systems capture FDA and Swissmedic-aligned certification premiums from API manufacturers. |
| Closed-Loop Solvent Recovery Services | On-site distillation contracts displace virgin solvent purchases among Germany's industrial Mittelstand clusters. |
| Geographic Expansion into India's Chemical Corridor | CDSCO streamlined approvals attract contract manufacturing organizations seeking extraction capacity. |
| Long-Term Refrigerant Feedstock Agreements | F-Gas Regulation phase-downs redirect trichloroethylene offtake toward hydrofluorocarbon precursor conversion. |
Study Parameters
Document review covered EPA TSCA risk evaluation filings, ECHA REACH authorization registers, SEC 10-K disclosures from chlor-alkali producers, and customs trade data, complemented by interviews with plant managers at integrated chemical facilities, procurement leads at pharmaceutical API manufacturers, distribution channel partners in the Rhine-Main corridor, and technical R&D directors overseeing purification process development. Bottom-up demand modeling across pharmaceutical extraction, metal finishing, and adhesive manufacturing applications was triangulated against top-down chlor-alkali capacity and utilization data.
Cross-referencing historical price formation patterns with expert panel input on regulatory timeline probabilities shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product grade tier, end-use industry application, regional production hub classification, and certification protocol compliance level. CAGRs were derived through regression analysis of volume trajectories against regulatory event probabilities and substitution elasticity estimates. Industry-specific forecast inputs incorporated OSHA methylene chloride exposure limit compliance cost curves and F-Gas Regulation phase-down schedules.
Revisions become necessary when EPA finalizes revised TSCA workplace exposure standards, ECHA accelerates carcinogenicity classification timelines, or chlorine feedstock volatility exceeds historical bands. Material deviation in these triggers warrants pause and re-evaluation of pharmaceutical-grade premium sustainability and substitution pathway acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Dimethyl Formamide Market
Solvents
Pharmaceutical Solvent Market
Solvents
GCC Acetonitrile Market
Solvents
Retardant Solvent Market
Solvents
Diethylene Glycol (DEG) Market
Solvents
Diethanolamide Market
Solvents
High Purity Solvents Market
Solvents
Electronic Cleaning Solvents Market
Solvents
Japan Acetonitrile Market
Solvents
Diethanolamine (DEA) Market
Solvents
Ketene Market
Solvents
Ethyl Pyruvate Market
Solvents
North America Toluene Market
Solvents
Methyl Diethanolamine Market
Solvents
Toluene Derivatives Market
Solvents
Meta-Xylene Market