
 Global Aliphatic Hydrocarbon Solvents Market | 2026-2036
Global Aliphatic Hydrocarbon Solvents Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aliphatic Hydrocarbon Solvents Market Foresight
Specialized chemical engineering talent is reorganizing around solvent purification and isomer separation capabilities across the aliphatic hydrocarbon value chain. ExxonMobil Corporation leverages its integrated refining footprint to secure feedstock cost advantages for hexane and heptane production. Shell plc anchors its position through proprietary isoparaffin technology developed at its major European research centers. BASF SE differentiates via analytical-grade solvent portfolios that serve pharmaceutical and laboratory end users with exacting purity requirements.
Aliphatic hydrocarbon solvents are saturated acyclic or cyclic hydrocarbons typically refined from petroleum naphtha streams through hydrotreating and fractional distillation, with carbon chain lengths spanning C5 through C12 and boiling point ranges from 30°C to 215°C depending on grade. These solvents dissolve oils, resins, and waxes while exhibiting low aromatic content, making them essential for coatings formulation and edible oil extraction where minimal residue matters. Isoparaffins command premium positioning due to narrow boiling ranges and ultra-low odor profiles that serve personal care and precision cleaning applications. Technical-grade solvents in paints and coatings represent the volume anchor, though pharmaceutical-grade specifications are capturing expanding margin pools as CDSCO and FDA purity requirements tighten across generic drug manufacturing corridors.
EPA volatility standards under the Clean Air Act constrain permissible vapor pressure in architectural coatings, pushing formulators toward higher-flash isoparaffin alternatives. ECHA REACH registration requirements for C6-C7 alkanes impose comprehensive toxicological dossiers that elevate compliance costs for European suppliers while creating entry barriers for non-registered importers. China's MEE enforcement of dual carbon goals is tightening refinery emission permits that underpin naphtha cracking capacity. Stakeholders must monitor regulatory divergence between jurisdictions where solvent substitution timelines and permissible exposure limits are decoupling, forcing regional product portfolio restructuring rather than unified global formulations.
Market Dynamics
REACH registration deadlines for C6-C7 alkanes are compressing supplier margins while EPA volatility standards under the Clean Air Act force architectural coatings formulators toward higher-flash isoparaffin alternatives.
Growth Catalysts
- Pharmaceutical-grade purity mandates:CDSCO and FDA tightening of residual solvent limits in generic drug manufacturing corridors pulls analytical-grade hexane consumption upward.
- China:NMPA-aligned pharmaceutical solvent specifications are expanding domestic procurement volumes faster than any other geography.
- Edible oil extraction:Food-grade heptane demand concentrates in Southeast Asian palm oil processing clusters where minimal residue requirements dominate supplier selection.
Market Restraints
- Naphtha feedstock volatility:Crude oil price swings transmit directly into C5-C12 aliphatic solvent cost structures with limited hedging mechanisms for mid-scale formulators.
- European supply concentration:ECHA REACH compliance costs for toxicological dossiers elevate barriers against non-registered importers, tightening origination points.
- Aqueous cleaning substitution:Precision electronics manufacturers in Japan and South Korea are displacing hydrocarbon solvents with water-based systems for substrate preparation.
Strategic Opportunities
- India:PLI scheme incentives for domestic agrochemical manufacturing are opening solvent procurement corridors previously served by European imports.
- Personal care isoparaffins:Ultra-low odor specifications for cosmetic formulations represent an underpenetrated margin tier distinct from technical grades.
- Carbon border adjustments:EU Green Deal implementation creates first-mover advantages for suppliers with verified low-carbon naphtha cracking pathways.
Industry Challenges
- Isomer separation expertise:Fractional distillation and molecular sieve capabilities require specialized chemical engineering talent that concentrates at legacy European and US refining complexes.
- Dual-use certification timelines:Pharmaceutical-grade solvent qualification protocols at FDA and NMPA impose 18-24 month validation cycles that freeze supplier switching.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aliphatic Hydrocarbon Solvents Market |
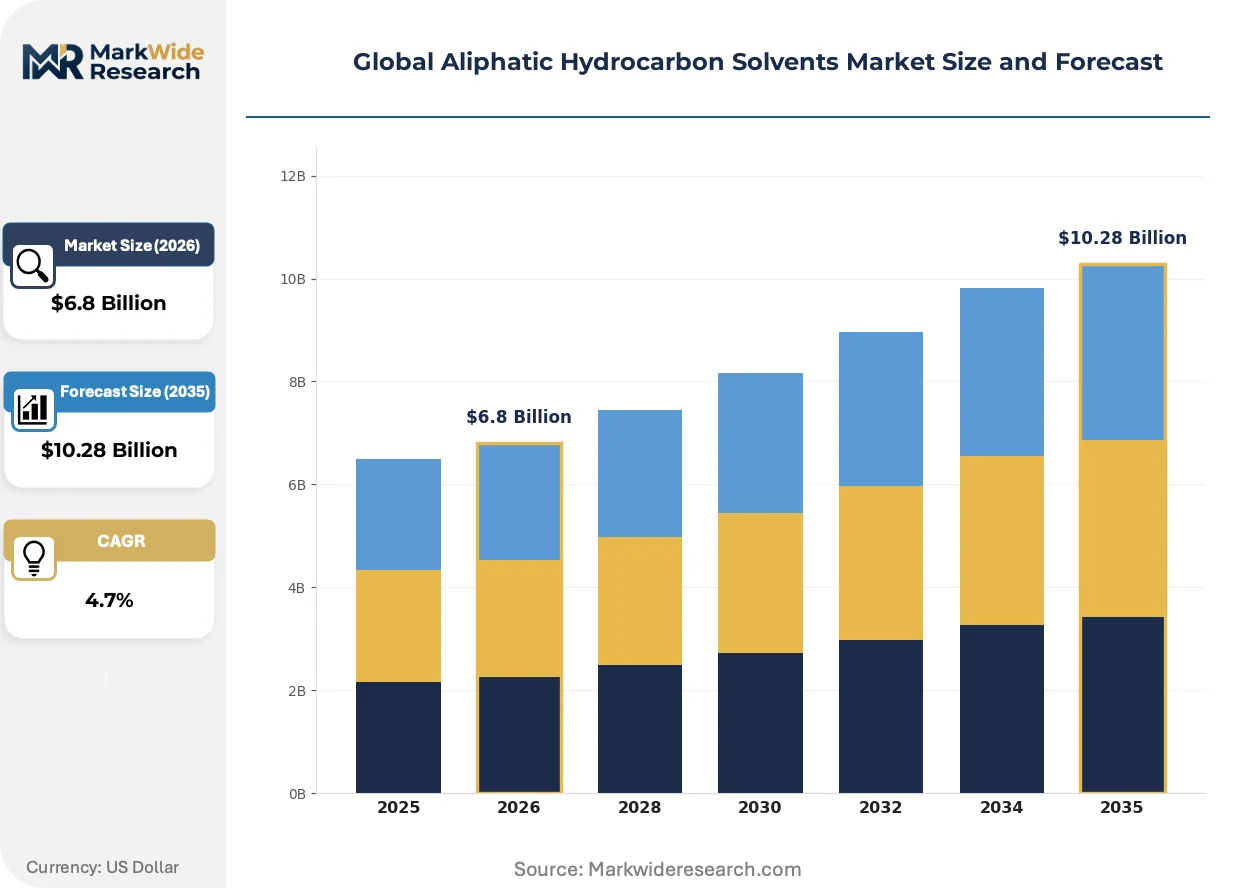
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hexane, Heptane, Pentane, Isoparaffins, Cycloalkanes Grade: Technical Grade, Industrial Grade, Analytical Grade, Food Grade, Pharmaceutical Grade Application: Paints & Coatings, Adhesives, Printing Inks, Cleaning Agents, Extraction Processes End Use Industry: Agrochemical Manufacturers, Personal Care Products, Chemical Processing, Oil Extraction |
| Companies Covered | ExxonMobil Corporation, Shell plc, Phillips 66, Calumet, Inc., TotalEnergies, BASF SE, Chevron Phillips Chemical Company LLC, SK GeoCentric Co., Ltd., LyondellBasell Industries N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aliphatic Hydrocarbon Solvents Market Shifts & Advancements
Refining technology and regulatory divergence are fragmenting product specifications across geographies, forcing solvent portfolios to regionalize rather than globalize.
Membrane-based solvent recovery systems are bifurcating the coatings industry. Automotive OEM paint shops in Germany and Japan are installing closed-loop hexane recovery at accelerating pace. This technology is compressing virgin solvent procurement volumes in high-volume assembly plants while creating aftermarket service revenue pools for equipment suppliers.
REACH authorization requirements for C9-C12 aliphatic hydrocarbons are tightening toxicological dossier standards across European formulators. The industrial consequence is accelerated substitution toward isoparaffin grades with established safety profiles. Pharmaceutical and laboratory end-use segments are absorbing the compliance cost pass-through while architectural coatings face margin compression.
Specification-driven procurement consolidation is concentrating buyer power among CDSCO-registered generic drug manufacturers in India and NMPA-certified API producers in China. Distributors with analytical certification capabilities are displacing commodity traders in these corridors. This pattern is most visible in the pharmaceutical-grade solvent tier where purity documentation requirements exceed standard technical specifications.
Global Aliphatic Hydrocarbon Solvents Market Segmentation
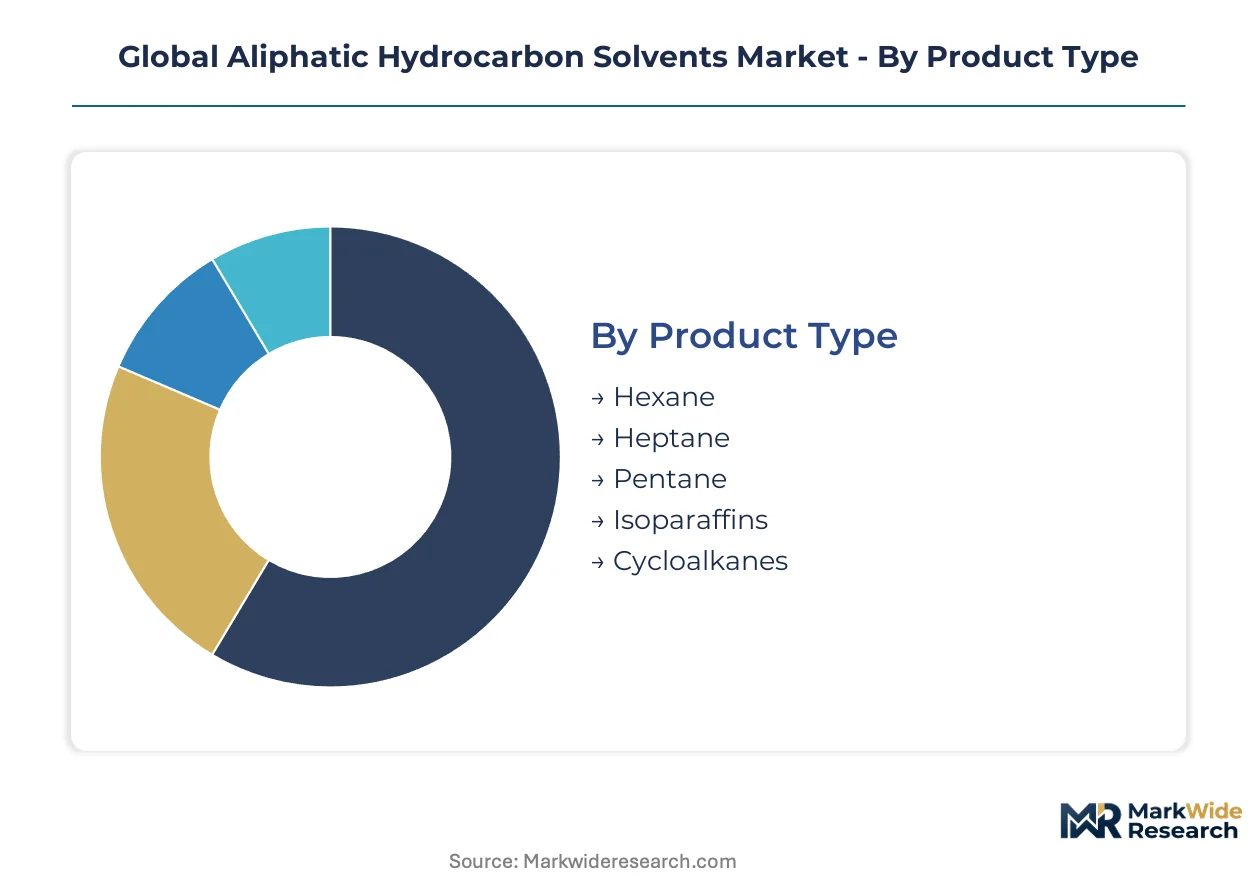
Segmentation in aliphatic hydrocarbon solvents reveals how margin pools concentrate at the intersection of purity certification and end-use specificity. Technical-grade volumes anchor revenue in coatings and adhesives, while pharmaceutical-grade specifications command premium positioning through regulatory qualification barriers.
Product Type:
Margin pools concentrate in isoparaffins and pharmaceutical-grade hexane where narrow boiling ranges and ultra-low aromatics justify 40-60% price premiums over technical solvents.
- Hexane:Saturated C6 aliphatic refined through hydrotreating and fractional distillation, serving as the primary extraction solvent for edible oils and pharmaceutical APIs. Demand concentrates in Southeast Asian palm oil processing corridors where minimal residue specifications dominate supplier selection, with CDSCO and FDA residual solvent limits tightening qualification requirements for generic drug manufacturers in India and China.
- Isoparaffins:Highly branched C10-C12 alkanes produced through proprietary catalytic isomerization, delivering narrow boiling ranges below 10°C and virtually odorless profiles. Personal care formulators in Germany and Japan absorb expanding volumes for cosmetic applications where consumer sensory thresholds reject conventional hydrocarbon odors.
- Heptane:C7 straight-chain solvent critical for laboratory and analytical applications requiring predictable evaporation rates.
- Pentane:Low-boiling C5 aliphatic serving polystyrene foam expansion and specialty extraction processes.
- Cycloalkanes:Saturated ring-structured hydrocarbons including cyclohexane and methylcyclohexane for high-solvency industrial applications.
The dominant share belongs to hexane, while isoparaffins are closing the gap fastest.
Grade:
Cost tiers stratify sharply around certification depth, with pharmaceutical and food grades requiring 18-24 month validation cycles that freeze supplier relationships.
- Pharmaceutical Grade:Solvents meeting USP, EP, and JP monograph specifications with comprehensive impurity profiling and batch-level COA documentation. NMPA-aligned procurement in China and CDSCO-registered generic manufacturers in India are absorbing volumes at the steepest expansion trajectory as residual solvent limits tighten across ICH Q3C guidelines.
- Technical Grade:Standard-refined aliphatics for industrial coatings and adhesives where aromatic content below 1% satisfies most formulation requirements. Architectural coatings formulators in the United States face EPA volatility constraints under Clean Air Act amendments, pushing displacement toward higher-flash alternatives.
- Analytical Grade:Ultra-high purity solvents for chromatography and spectroscopy with specified UV transmittance windows.
- Industrial Grade:Bulk-processed aliphatics for non-critical cleaning and degreasing applications.
- Food Grade:Hexane and heptane meeting FDA 21 CFR 173.270 extraction solvent specifications for edible oil processing.
Technical grade still commands volume leadership, though pharmaceutical grade is climbing the fastest as regulatory qualification barriers deepen.
Application:
Application-driven procurement patterns reflect diverging regulatory pressure intensity across end-use corridors.
- Paints & Coatings:The volume anchor consuming C6-C12 aliphatics for viscosity reduction and flow control in architectural and industrial formulations. German automotive OEM paint shops are installing membrane-based hexane recovery systems at accelerating pace, compressing virgin solvent demand while creating equipment service revenue pools.
- Cleaning Agents:Precision electronics manufacturers in Japan and South Korea are displacing hydrocarbon solvents with aqueous systems for substrate preparation, constraining growth in this segment.
- Adhesives:Solvent-borne systems for pressure-sensitive and structural bonding applications.
- Printing Inks:Fast-evaporating aliphatics for rotogravure and flexographic formulations.
- Extraction Processes:Food-grade and pharmaceutical-grade solvents for botanical, edible oil, and API isolation.
Paints and coatings retain the largest application share, while extraction processes are gaining share fastest on pharmaceutical and food-grade qualification requirements.
End Use Industry:
Customer-type concentration is reshaping distribution economics as specification depth separates qualified suppliers from commodity traders.
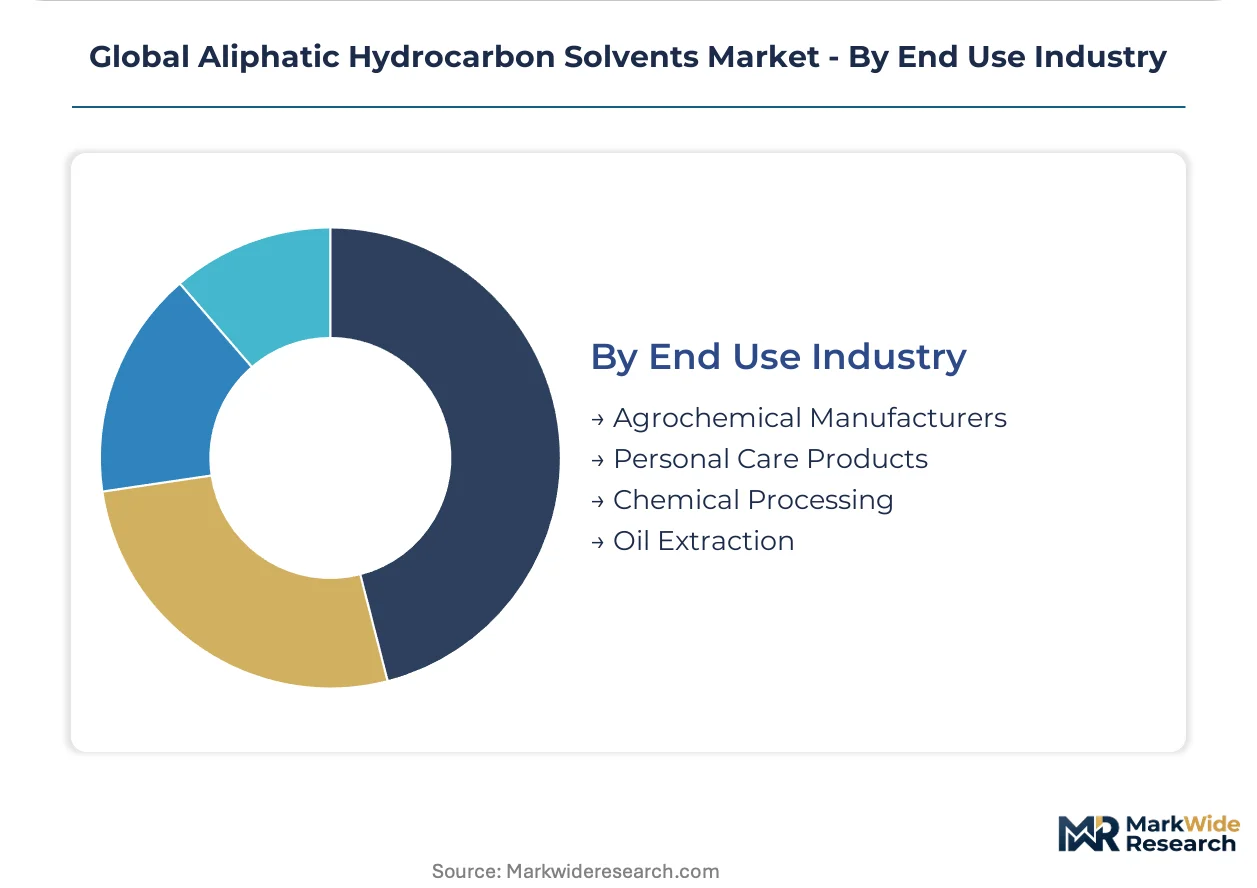
- Agrochemical Manufacturers:Formulators of crop protection products consuming technical-grade solvents for active ingredient synthesis and formulation. India's PLI scheme incentives for domestic agrochemical manufacturing are opening procurement corridors previously served by European imports.
- Personal Care Products:Cosmetic and fragrance houses demanding isoparaffins with ultra-low odor profiles and narrow boiling specifications. This segment captures underpenetrated margin tiers distinct from technical grades as formulators in France and Switzerland prioritize sensory performance.
- Chemical Processing:Intermediate producers using aliphatic solvents as reaction media and purification aids.
- Oil Extraction:Edible oil processors in Indonesia and Malaysia utilizing food-grade hexane for vegetable oil recovery.
Agrochemical manufacturers hold the dominant end-use position, while personal care products are expanding most quickly on isoparaffin premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European suppliers extract 25-35% price premiums over Southeast Asian producers due to REACH registration dossiers and pharmaceutical-grade certification depth. This asymmetry widens as CDSCO and NMPA validation timelines freeze supplier switching in India and China.
United States
EPA volatility standards under Clean Air Act amendments constrain architectural coatings formulators toward higher-flash isoparaffin alternatives. The agency's National Ambient Air Quality Standards enforcement tightens refinery emission permits in the Gulf Coast petrochemical corridor. Houston-area solvent terminals are expanding pharmaceutical-grade storage capacity to serve CDSCO-registered generic manufacturers establishing US distribution.
China
NMPA-aligned pharmaceutical solvent specifications are expanding domestic procurement volumes faster than any other geography. MEE enforcement of dual carbon goals tightens naphtha cracking emission permits across Shandong and Jiangsu provinces. Yangtze River Delta API producers are absorbing analytical-grade hexane at accelerating rates as residual solvent limits tighten under ICH Q3C guidelines.
Germany
ECHA REACH registration requirements for C6-C7 alkanes impose comprehensive toxicological dossiers that elevate compliance costs for domestic suppliers. The EU Green Deal's carbon border adjustment mechanism creates first-mover advantages for verified low-carbon naphtha cracking pathways. Bavarian automotive OEM paint shops are installing membrane-based hexane recovery systems at accelerating pace.
India
PLI scheme incentives for domestic agrochemical manufacturing are opening solvent procurement corridors previously served by European imports. CDSCO tightening of residual solvent limits in generic drug manufacturing pulls analytical-grade hexane consumption upward. Gujarat and Maharashtra chemical clusters are absorbing expanding technical-grade volumes for crop protection formulation.
Japan
Precision electronics manufacturers are displacing hydrocarbon solvents with aqueous systems for substrate preparation, constraining cleaning agent segment growth. METI industrial standards enforce ultra-low aromatic specifications for personal care isoparaffins. Kansai region cosmetic formulators prioritize sensory performance, absorbing odorless C10-C12 grades at premium positioning.
Global Aliphatic Hydrocarbon Solvents Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the aliphatic hydrocarbon value chain. Integrated petroleum majors leverage captive naphtha feedstock and refining scale to dominate technical-grade volumes. Specialty chemical houses anchor pharmaceutical and analytical grades through purification expertise and regulatory dossier capabilities. The competitive arena is compressing around two dominant moves: backward integration into refinery assets and portfolio diversification toward isoparaffin premium tiers.
Among integrated petroleum majors, ExxonMobil Corporation and Shell plc occupy positions that exemplify the feedstock-cost archetype, while BASF SE represents the specialty-grade certification tier. These three anchors illustrate how supplier positioning fragments between volume-driven refining scale and margin-protected purity depth.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Shell plc |
| Phillips 66 |
| Calumet, Inc. |
| TotalEnergies |
| BASF SE |
| Chevron Phillips Chemical Company LLC |
| SK GeoCentric Co., Ltd. |
| LyondellBasell Industries N.V. |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day pharmaceutical-grade qualification timelines compress supplier switching and cement price premiums for REACH-registered European producers serving CDSCO-registered generic manufacturers in India. This lead-time rigidity concentrates buyer power among analytical-certified distributors while naphtha feedstock volatility transmits directly into C5-C12 solvent cost structures with limited hedging mechanisms for mid-scale formulators.
Pricing Analysis
Configured-to-order pharmaceutical-grade specifications command 40-60% premiums over standard technical-grade spot pricing due to 18-24 month FDA and NMPA validation cycles. Three-tier pricing structure across pharmaceutical, technical, and industrial grades stratifies sharply around certification depth and impurity profiling requirements. Cost compression in technical-grade architectural coatings intensifies because EPA volatility standards under the Clean Air Act push formulators toward higher-flash isoparaffin alternatives. Agrochemical manufacturers exhibit highest price sensitivity due to naphtha feedstock exposure, while personal care formulators absorb premium positioning for ultra-low odor isoparaffins with minimal negotiation leverage.
Supply Chain Analysis
Germany and the Netherlands anchor pharmaceutical-grade solvent purification through ECHA-registered hydrotreating and fractional distillation complexes serving global laboratory and API manufacturing corridors. China and the United States concentrate technical-grade volume production through integrated refinery-solvent operations drawing from Gulf Coast and Shandong naphtha cracking capacity. Feedstock supply rests on crude oil price volatility, specialized isomer separation expertise concentrated at legacy European refining complexes, and MEE emission permit constraints across Chinese provinces. Single-source vulnerability emerges from REACH registration concentration among European suppliers for C6-C7 alkanes. Distribution runs through qualified distributors with analytical certification capabilities displacing commodity traders in pharmaceutical-grade corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane-based solvent recovery aftermarket services expand faster than virgin solvent volumes as German and Japanese automotive OEM paint shops install closed-loop hexane systems. This service-attach layer outpaces hardware growth by capturing recurring maintenance revenue and equipment upgrade cycles.
For Market Incumbents: Secure captive naphtha feedstock through backward integration into refinery assets or long-term offtake agreements with Gulf Coast and Shandong crackers. Deepen pharmaceutical-grade certification dossiers at FDA, EMA, and NMPA to defend against aqueous cleaning substitution threatening precision electronics cleaning segments. Capacity addition in India leverages PLI scheme incentives for domestic agrochemical manufacturing while CDSCO residual solvent limits tighten qualification barriers. For New Entrants and Emerging Players: Anchor in personal care isoparaffins where ultra-low odor specifications represent underpenetrated margin tiers distinct from commoditized technical grades. Target Kansai region cosmetic formulators and German fragrance houses prioritizing sensory performance over price. Pursue distributor partnerships with analytical certification capabilities rather than direct technical-grade competition against integrated petroleum majors. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates seeking portfolio rationalization away from solvent-dependent segments facing regulatory substitution pressure. Mid-cap European refiners with ECHA REACH dossiers and established pharmaceutical-grade customer relationships present viable acquisition profiles over the medium-term horizon. Monitor NMPA enforcement timelines in China as inflection indicator for analytical-grade hexane demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Naphtha Cracking | Captive feedstock supply secures cost position against crude oil volatility for C5-C12 aliphatic production. |
| Pharmaceutical-Grade Certification Investment | FDA and NMPA dossier completion locks in 18-24 month supplier switching barriers for generic drug manufacturers. |
| Membrane-Based Recovery System Deployment | Closed-loop hexane recovery at automotive OEM paint shops captures recurring aftermarket service revenue pools. |
| Isoparaffin Capacity Expansion | Ultra-low odor C10-C12 production serves personal care formulators in Germany and Japan at premium positioning. |
| India PLI Corridor Establishment | Domestic technical-grade supply to Gujarat and Maharashtra agrochemical clusters displaces European import dependency. |
Research Methodology
Cross-validation between primary interviews with solvent procurement leads at agrochemical formulators, pharmaceutical API manufacturers, and coatings OEMs and secondary trade data from customs records and chemical industry association filings anchors the qualitative findings. Technical discussions with plant managers at hydrotreating facilities, distribution channel partners with analytical certification capabilities, and regulatory affairs specialists at ECHA and EPA frame supply-side constraints. Bottom-up volume modeling triangulates against top-down naphtha cracking capacity assessments across the analysis window.
Sensitivity analysis across pharmaceutical-grade purity tiers, technical-grade industrial applications, and regional regulatory clusters shapes the analytical framework over the projection horizon. Segmentation dimensions include carbon chain length, certification grade depth, end-use industry concentration, and geographic production hub qualification status. CAGRs derive from regression against naphtha price indices, REACH registration timelines, and CDSCO enforcement intensity. Forecast inputs incorporate ICH Q3C residual solvent limit adoption curves and MEE dual carbon permit issuance patterns.
Decision-makers should treat outputs as directional under sustained naphtha feedstock availability and stable pharmaceutical-grade qualification timelines; material deviation in crude oil volatility or accelerated aqueous substitution would warrant model refresh. Recalibration cycles align with material shifts in EPA volatility standard amendments, ECHA authorization expansions, and NMPA pharmaceutical solvent specification updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Global Chloroform Market
Solvents
North America Acetonitrile Market
Solvents
Global Ethyl Lactate Market
Solvents
Decanol Market
Solvents
Aliphatic Hydrocarbon Solvents and Thinners Market
Solvents
Trifluoroethanol Market
Solvents
Aprotic Solvents Market
Solvents
Acetone Market
Solvents
Pharmaceutical Solvent Market
Solvents
Green Solvents and Bio-Solvents Market
Solvents
Sugar Dissolvers Market
Solvents
3-Butylene Glycol Market
Solvents
Global Ink Solvents Market
Solvents
4-Dichlorobenzyl Alcohol (DCBA) Market
Solvents
Electronic Cleaning Solvents Market
Solvents
Global Furfural Solvent Market