
 Benzene-Toluene-Xylene (BTX) Market | 2026-2036
Benzene-Toluene-Xylene (BTX) Market Size, Share, and Industry Trends Forecast 2026-2036
Benzene-Toluene-Xylene (BTX) Market Outlook
Steam cracker optimization and catalytic reforming advances are rewriting BTX yield economics across integrated refineries. SABIC leverages its Yanbu complex to anchor high-purity benzene supply for Middle Eastern derivative markets. ExxonMobil sustains technology leadership through proprietary aromatics extraction processes at its Singapore and Baytown facilities. Shell dominates European BTX trade flows via its Pernis and Moerdijk aromatics platforms.
Benzene-Toluene-Xylene denotes a family of aromatic hydrocarbons produced primarily through catalytic reforming of naphtha and steam cracking of ethane or naphtha feedstocks, with benzene containing six carbon atoms in a conjugated ring structure, toluene bearing a methyl substituent, and xylene existing as ortho-meta-para isomers distinguished by methyl group positioning. These aromatics serve as essential chemical intermediates for synthetic rubber, plastics, polyester fibers, and solvent formulations across industrial manufacturing. Among product type segments, mixed aromatics feedstock streams command volume leadership while para-xylene specialization captures premium margins tied to purified terephthalic acid demand. Chemical intermediates application segments occupy the deepest value pools, whereas solvents face structural pressure from bio-based alternatives in coatings formulations.
EPA benzene emissions standards under the National Emission Standards for Hazardous Air Pollutants constrain US refinery aromatics recovery operations. REACH registration requirements and the EU Green Deal carbon border adjustments elevate compliance costs for European BTX importers and domestic producers alike. China's MEE enforces stricter volatile organic compound controls on aromatics storage and handling facilities near the Yangtze River Delta chemical clusters. Stakeholders must monitor feedstock flexibility investments that bridge naphtha and ethane cracking economics while tracking regional carbon intensity regulations that threaten cost structures for conventional aromatics production.
Market Dynamics
Steam cracker feedstock flexibility investments are compressing regional BTX cost spreads as producers arbitrage between naphtha and ethane economics across integrated refining-petrochemical complexes.
Growth Catalysts
- Polyester chain expansion:India's downstream chemical parks are attracting integrated refinery-petrochemical investments that anchor para-xylene demand for purified terephthalic acid production.
- REACH compliance upgrades:European aromatics producers are modernizing extraction processes to meet ECHA registration requirements and EU Green Deal carbon border adjustments.
- Catalytic reforming advances:Higher-severity reforming operations are boosting BTX yields from naphtha feedstocks at Middle Eastern and Asian integrated complexes.
Market Restraints
- Naphtha price volatility:Crude-linked naphtha costs expose aromatics margins to upstream oil market swings that compress producer economics during feedstock spikes.
- Asia-Pacific supply concentration:Chinese and South Korean integrated complexes control disproportionate shares of exportable para-xylene volumes, creating geographic dependency risk.
- Bio-based solvent substitution:Coatings formulators are displacing xylene solvents with renewable alternatives under tightening VOC regulations in European and North American markets.
Strategic Opportunities
- India demand concentration:Gujarat and Maharashtra chemical corridors offer greenfield BTX derivative capacity locations with proximity to textile manufacturing clusters.
- Dual carbon policy tailwinds:China's MEE enforcement of stricter VOC controls is accelerating capital deployment toward closed-loop aromatics handling systems.
- Digital supply chain convergence:Blockchain-enabled cargo tracking is virtualizing aromatics trade documentation between Singapore storage terminals and European offtakers.
Industry Challenges
- Process control engineering scarcity:Integrated refineries face shortages of specialists capable of optimizing aromatics extraction unit yields alongside FCC and hydrocracker operations.
- REACH registration timelines:European importers encounter extended ECHA substance evaluation periods that delay new BTX derivative market entry.
- Legacy DCS integration:Aromatics producers struggle to retrofit advanced process control systems onto 1990s-vintage distributed control architectures without production disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Benzene-Toluene-Xylene (BTX) Market |
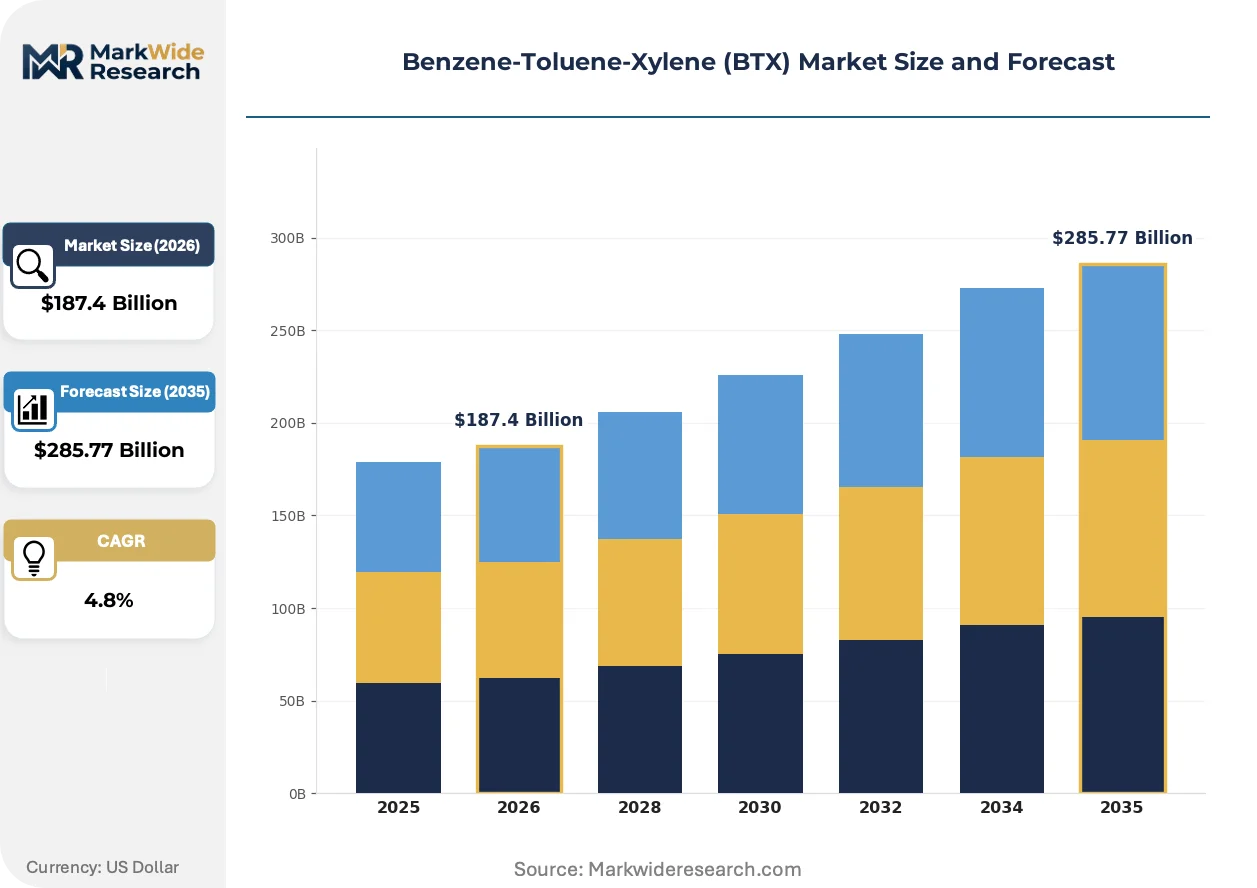
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $285.77 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Benzene, Toluene, Xylene, Mixed Aromatics Application: Solvents, Chemical Intermediates, Fuels, Coatings End User: Manufacturing, Pharmaceuticals, Automotive, Paints Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | SABIC, ExxonMobil, Sinopec, TotalEnergies, Shell, PetroChina, Reliance Industries, Formosa Petrochemical, Saudi Aramco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Benzene-Toluene-Xylene (BTX) Market Strategic Shifts
Digital twin deployment and predictive maintenance algorithms are compressing unplanned aromatics unit downtime while enabling real-time yield optimization across geographically dispersed production assets.
Advanced process control software is virtualizing BTX separation train operations by embedding machine learning models that predict extractive distillation column performance. Refinery operators in Singapore and Rotterdam are deploying these systems to sustain 99.5% plus benzene purity specifications with reduced solvent circulation rates. The technology is virtualizing traditional manual laboratory sampling workflows into continuous spectroscopic monitoring.
EPA benzene emissions standards under NESHAP are forcing US Gulf Coast refineries to install enhanced leak detection and repair programs for aromatics recovery equipment. The regulation is elevating capital intensity for marginal producers while accelerating consolidation toward larger integrated complexes with dedicated environmental compliance teams. Aromatics extraction units at older refineries face disproportionate retrofit burdens relative to greenfield Middle Eastern installations.
Petrochemical buyers are consolidating procurement volumes through long-term offtake contracts with integrated refinery operators rather than spot market purchases. This pattern concentrates supply risk with fewer counterparties but secures feedstock cost predictability for polyester and styrene chain producers. The shift is most pronounced among South Korean and Taiwanese purified terephthalic acid manufacturers securing para-xylene supply from Thai and Singaporean aromatics platforms.
Benzene-Toluene-Xylene (BTX) Market Segmentation
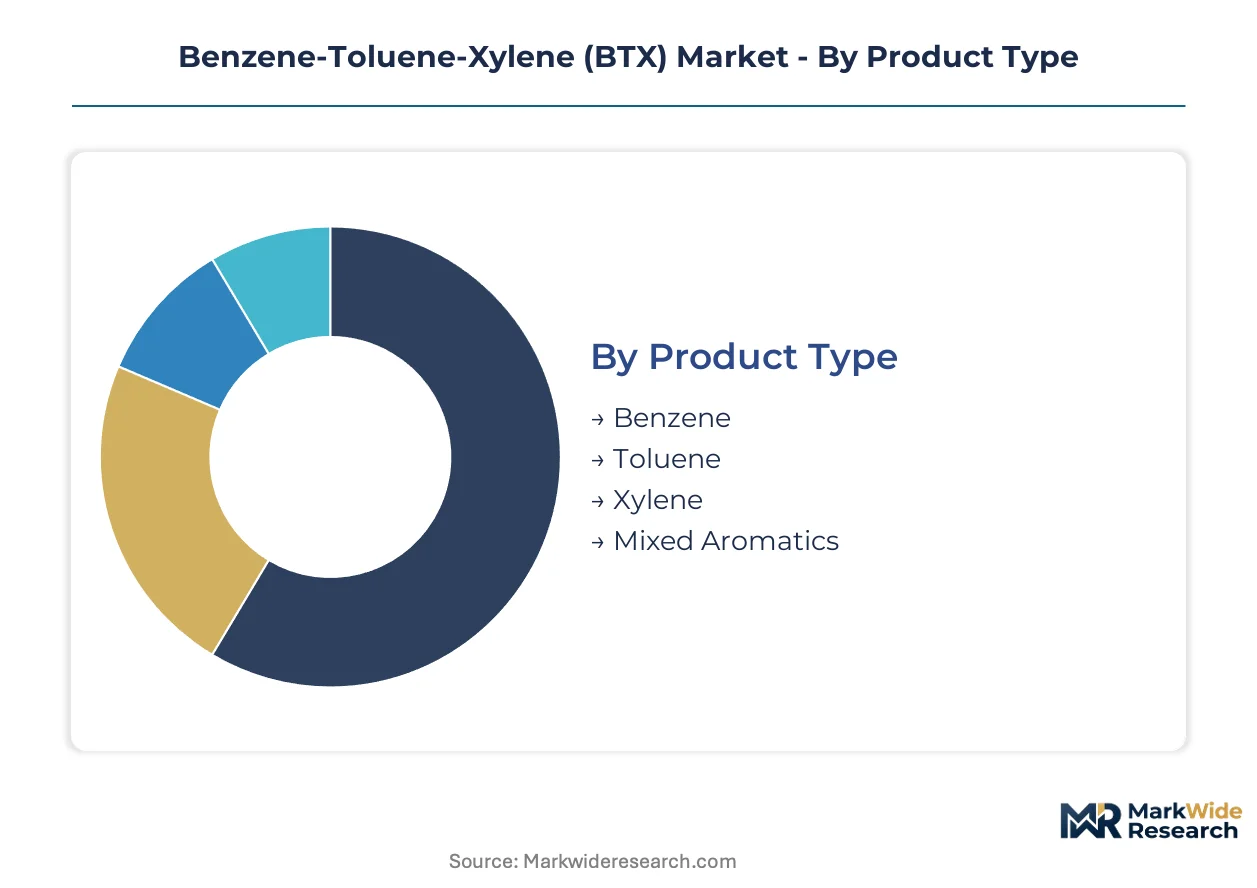
BTX segmentation reveals how aromatic hydrocarbons flow through distinct value chains, with product type determining margin structure and application governing regulatory exposure. Understanding these divisions exposes where integrated producers capture premium returns versus commodity-grade volumes.
Product Type:
After-sales service intensity varies sharply across aromatic grades, with high-purity benzene requiring technical support for derivative synthesis while mixed aromatics trade as standardized feedstock commodities.
- Benzene:Six-carbon aromatic ring with maximum unsaturation serves as the foundational building block for styrene, cumene, and cyclohexane production. Demand concentrates in South Korean and Taiwanese purified terephthalic acid manufacturing clusters, where buyers negotiate long-term offtake contracts to secure feedstock cost predictability against naphtha volatility.
- Xylene:Ortho-meta-para isomers differentiated by methyl group positioning, with para-xylene commanding structural premiums tied to polyester chain expansion. Indian textile manufacturing corridors in Gujarat and Maharashtra are attracting dedicated para-xylene derivative investments from integrated refinery-petrochemical complexes.
- Toluene:Methyl-substituted aromatic primarily consumed in solvent applications and benzene disproportionation units, with toluene diisocyanate representing the highest-value derivative pathway.
- Mixed Aromatics:Unseparated reformate streams traded as refinery blending components and petrochemical feedstock precursors, with volume leadership in Asian spot markets.
Mixed aromatics holds the largest share; momentum sits with para-xylene specialization.
Application:
Margin structure across applications correlates with chemical transformation depth, with intermediates commanding value-added premiums and solvents facing substitution pressure.
- Chemical Intermediates:BTX molecules as precursors for synthetic rubber, plastics, and polyester fibers occupy the deepest value pools in the aromatic value chain. Indian downstream chemical parks anchor expanding demand for benzene-derived styrene and cumene, while Chinese dual carbon goals tighten emissions standards for conventional production routes.
- Solvents:Xylene and toluene formulations for industrial degreasing and coatings face structural displacement from bio-based alternatives under EPA NESHAP benzene emissions standards and EU REACH volatile organic compound controls.
- Fuels:Aromatic blending components for gasoline octane enhancement trade as refinery optimization outputs, with reformate yields adjusting to regional clean fuel specifications.
- Coatings:High-purity aromatic solvents for paint and varnish formulations face tightening storage and handling regulations near Yangtze River Delta chemical clusters under China's MEE enforcement protocols.
Chemical intermediates holds the largest share; coatings faces the steepest regulatory compression.
End User:
Customer concentration patterns diverge by sector, with automotive and pharmaceutical buyers demanding certified purity grades while manufacturing absorbs commodity volumes.
- Manufacturing:Broad industrial consumption spanning synthetic rubber, plastics, and fiber production, with procurement consolidating toward integrated refinery operators through long-term contracts rather than spot purchases.
- Pharmaceuticals:High-purity benzene and toluene for active pharmaceutical ingredient synthesis require REACH registration compliance and ECHA substance evaluation documentation for European market access.
- Automotive:Styrene-butadiene rubber for tire manufacturing and engineering plastics for vehicle lightweighting drive benzene and xylene demand, with specifications tightening for volatile organic compound emissions in cabin air quality standards.
- Paints:Architectural and industrial coatings formulators are displacing xylene solvents with renewable alternatives, compressing traditional aromatic demand in European and North American markets.
Manufacturing holds the largest share; pharmaceuticals claims the steepest purity premium expansion.
Distribution Channel:
Channel economics reflect cargo scale and documentation intensity, with direct sales capturing integrated offtake and distributors serving fragmented specialty buyers.
- Direct Sales:Long-term offtake contracts between integrated refinery-petrochemical complexes and downstream derivative producers, concentrating supply risk with fewer counterparties but securing feedstock cost predictability.
- Distributors:Regional chemical distributors aggregate smaller volume purchases from coatings and solvent formulators, with blockchain-enabled cargo tracking virtualizing trade documentation between Singapore storage terminals and European offtakers.
- Online Sales:Digital platforms emerging for standardized aromatic grades and spot market transactions, with limited penetration in high-purity specification segments.
- Retail:Packaged solvent sales for maintenance and small-scale industrial applications, facing regulatory constraints on consumer benzene exposure limits.
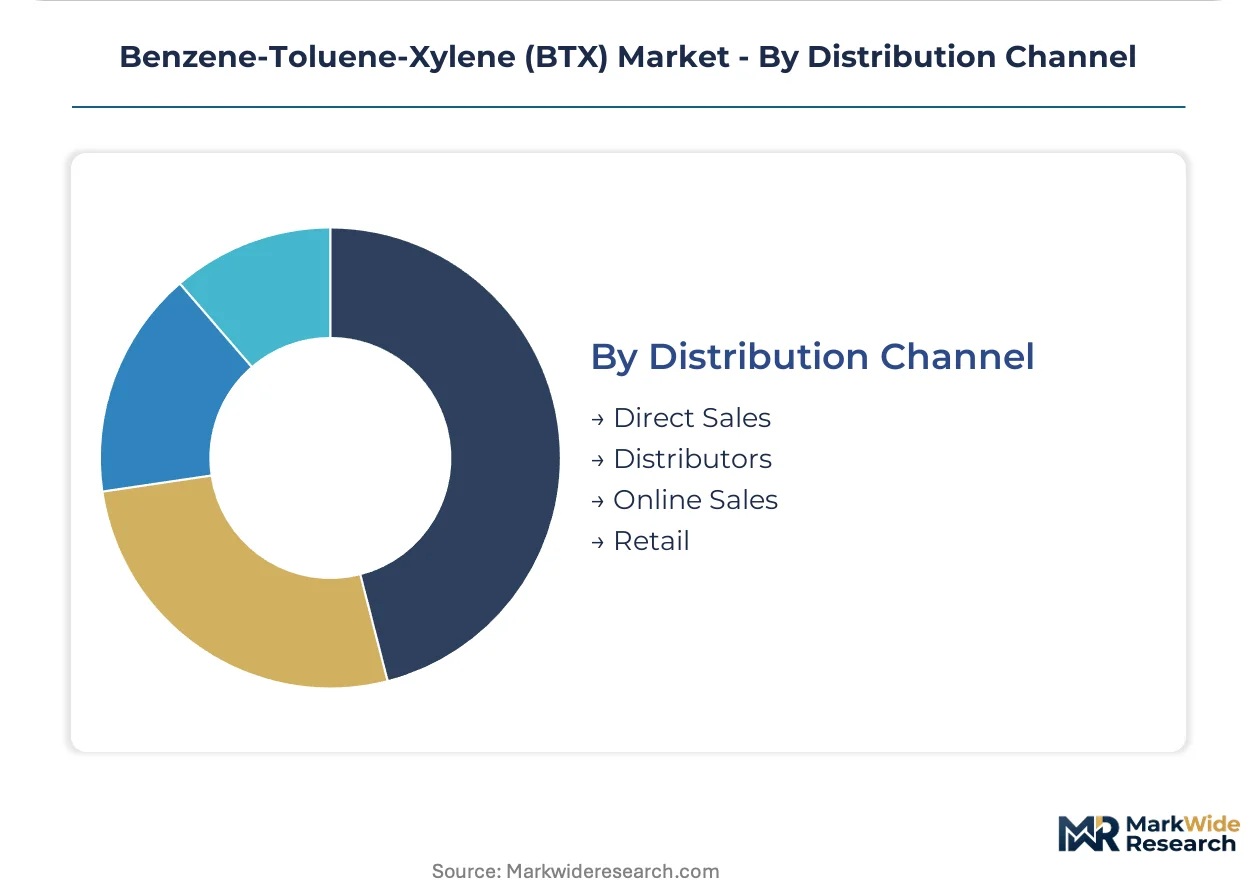
Direct sales holds the largest share; distributors are gaining share fastest through digital documentation integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korean para-xylene exports flow predominantly to Chinese purified terephthalic acid manufacturers, establishing the dominant trade corridor in Asian aromatics commerce. This bilateral dependency shapes inventory positioning and contract negotiation dynamics across the region.
China
Yangtze River Delta chemical clusters drive domestic para-xylene consumption for polyester fiber manufacturing. MEE enforcement of stricter VOC controls near Shanghai and Ningbo is accelerating capital deployment toward closed-loop aromatics handling infrastructure. Zhejiang Province hosts multiple integrated refining-petrochemical complexes expanding extraction capacity.
United States
Gulf Coast styrene and cumene derivative producers anchor benzene demand from Texas and Louisiana aromatics platforms. EPA NESHAP benzene emissions standards constrain refinery recovery operations, elevating compliance costs for older extraction units. Houston Ship Channel terminals serve as the primary export hub for US benzene volumes.
Germany
Ruhr Valley chemical parks consume high-purity benzene for styrene and cyclohexane production serving automotive supply chains. REACH registration requirements and EU Green Deal carbon border adjustments elevate compliance costs for domestic producers and importers. Ludwigshafen and Cologne anchor the densest concentration of aromatics derivative manufacturing.
Saudi Arabia
Yanbu and Jubail industrial cities host integrated complexes exporting high-purity benzene to Asian and European derivative markets. The country's national industrial development program prioritizes downstream chemical manufacturing over raw aromatics exports. SABIC operates extraction capacity serving Middle Eastern and international offtakers.
India
Gujarat and Maharashtra chemical corridors attract greenfield refinery-petrochemical investments targeting domestic para-xylene demand. PLI scheme incentives for textile manufacturing amplify consumption of polyester chain intermediates. Dahej and Mundra port zones concentrate new aromatics derivative capacity.
Benzene-Toluene-Xylene (BTX) Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered market positions defined by feedstock access and extraction technology. Integrated oil majors dominate volume leadership through captive naphtha supply and proprietary aromatics recovery processes. Three archetypes populate the competitive map: integrated refinery operators with backward feedstock control, standalone petrochemical processors, and regional trading houses aggregating spot volumes. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with producers securing long-term offtake contracts to lock in derivative demand.
Within the integrated operator tier, SABIC and ExxonMobil exemplify scale-driven positions anchored by proprietary extraction technology and integrated refining-petrochemical complexes. Shell occupies a channel-controlling position across European trade flows. These companies represent the archetype of feedstock-integrated producers leveraging captive supply chains and dedicated environmental compliance infrastructure to sustain specification-grade output.
| Leading Market Players |
|---|
| SABIC |
| ExxonMobil |
| Sinopec |
| TotalEnergies |
| Shell |
| PetroChina |
| Reliance Industries |
| Formosa Petrochemical |
| Saudi Aramco |
| Others |
Value Chain & Pricing Dynamics
Overcapacity signals from South Korean para-xylene units are compressing regional spot premiums and forcing integrated producers toward longer contract tenors to stabilize revenue visibility across volatile naphtha feedstock cycles.
Pricing Analysis
Technology-generation pricing gaps separate legacy catalytic reforming outputs from advanced extractive distillation units achieving 99.5% benzene purity specifications. Contract-based long-term offtake structures dominate, with price differentiation anchored in certification grade (REACH-registered vs. standard technical grade) and volume scale commitments. Cost compression in mixed aromatics spot tiers is intensifying because Chinese integrated complexes are flooding Asian markets with reformate streams. Small coatings formulators exhibit the highest price sensitivity, while purified terephthalic acid manufacturers securing para-xylene supply demonstrate the lowest due to substitution impossibility.
Supply Chain Analysis
Tariff exposure between the United States and China is reshaping trans-Pacific benzene cargo routing through Singapore storage terminals. Geographic supply concentration centers on China, South Korea, and Saudi Arabia, with raw material dependencies resting on naphtha feedstock from Middle Eastern crude streams, ethane from US shale basins, and hydrogen for hydrotreating units. Single-source vulnerability concentrates in South Korean para-xylene exports feeding Chinese purified terephthalic acid manufacturers. Distribution runs through integrated refinery-petrochemical complexes with dedicated aromatics extraction units, bypassing merchant market intermediaries for derivative producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized process control engineering talent for aromatics extraction unit optimization is becoming the binding constraint on yield improvements across integrated refining-petrochemical complexes, with shortages most acute in Middle Eastern and Indian greenfield developments.
For Market Incumbents: Build proprietary extraction technology moats by deploying machine learning-enabled predictive maintenance systems that sustain 99.5% benzene purity specifications with reduced solvent circulation rates. Expand capacity in Gujarat chemical corridors to anchor Indian para-xylene demand growth, while securing REACH registration compliance ahead of EU Green Deal carbon border adjustments that threaten non-compliant import economics. For New Entrants and Emerging Players: Build out digital supply chain infrastructure targeting blockchain-enabled cargo tracking between Singapore storage terminals and European offtakers, where documentation virtualization remains underpenetrated. Focus on mixed aromatics feedstock spot trading in Asian markets, where incumbent concentration creates procurement consolidation opportunities for agile trading houses with flexible naphtha sourcing. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across closed-loop aromatics handling systems mandated by China's MEE enforcement near Yangtze River Delta chemical clusters. Long-term viability favors integrated operators with captive naphtha supply and dedicated environmental compliance infrastructure over standalone processors exposed to feedstock volatility. Monitor SABIC and ExxonMobil technology licensing patterns as signals of competitive yield architecture diffusion.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Indian chemical parks in Gujarat and Maharashtra attract integrated refinery-petrochemical investments anchoring domestic para-xylene supply. |
| Backward Integration | Captive naphtha supply from integrated refining complexes insulates aromatics margins against crude-linked feedstock volatility. |
| Green Manufacturing Transition | Closed-loop aromatics handling systems comply with China's MEE VOC controls near Yangtze River Delta manufacturing clusters. |
| Long-term Supply Agreement | South Korean purified terephthalic acid manufacturers secure para-xylene offtake from Thai and Singaporean aromatics platforms. |
| Joint Venture | SABIC leverages Yanbu complex partnerships to anchor high-purity benzene supply for Middle Eastern derivative markets. |
Study Parameters
The analysis maps catalytic reforming, steam cracking, and extractive distillation sub-sectors, each validated through interviews with plant managers at integrated refining-petrochemical complexes, procurement leads at downstream purified terephthalic acid manufacturers, distribution channel partners in Singapore and Rotterdam storage terminals, and technical R&D directors specializing in aromatics extraction processes. Secondary validation draws from customs and trade data, American Chemistry Council and Cefic industry reports, SEC 10-K filings of listed petrochemical operators, and EPA NESHAP compliance disclosures. Bottom-up capacity utilization assessments triangulate against top-down demand modeling from polyester and styrene chain consumption patterns.
Assumptions regarding naphtha-ethane feedstock flexibility economics and regional carbon intensity regulations were held fixed across baseline scenarios while varying Chinese dual carbon policy enforcement stringency and EU Green Deal carbon border adjustment implementation timing in sensitivity runs. Segmentation dimensions modeled include product grade tier (mixed aromatics through high-purity benzene), end-use industry (polyester intermediates, solvents, fuels), and regional production hub configuration. CAGRs were derived from iterative convergence of demand elasticity estimates and supply-side capacity expansion announcements. Industry-specific inputs incorporate steam cracker operating rate data and catalytic reforming severity yield curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by national oil companies prioritizing downstream chemical manufacturing over raw aromatics exports would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Dimethyl Sulfoxide Market
Solvents
Propylene Glycol Market
Solvents
1,2-Ethanedithiol Market
Solvents
North America Acetonitrile Market
Solvents
Fluorinated Solvents Market
Solvents
Europe Acetonitrile Market
Solvents
Phenylacetonitrile Market
Solvents
Lithium-Ion Battery's Electrolyte Solvent Market
Solvents
Propylene Glycol Ether Market
Solvents
Chloromethane Market
Solvents
3-Methyl-3-Penten-2-One (3M3P) Market
Solvents
Global Nitrochlorobenzene Market
Solvents
Trifluoroethanol Market
Solvents
Global Bio Solvents Market
Solvents
Global Aliphatic Hydrocarbon Solvents Market
Solvents
Triacetin Market