
 Monochlorobenzene Market | 2026-2036
Monochlorobenzene Market Size, Share, and Industry Trends Forecast 2026-2036
Monochlorobenzene Market Foresight
Specialty chemical distribution is narrowing as regional distributors consolidate around qualified monochlorobenzene suppliers. BASF SE leverages its integrated aromatic complexes in Europe to sustain captive feedstock advantages. Henan Kaipu Chemical Co. Ltd. anchors supply to Asian agrochemical formulators through dedicated chlorobenzene production lines. Lanxess AG competes on pharmaceutical-grade specifications with tight impurity controls.
Monochlorobenzene is an aromatic organochlorine compound produced via benzene chlorination, typically yielding 99.5% purity material used as a chemical intermediate and selective solvent in nitrochlorobenzene and diphenyl ether synthesis. Solvent-grade material dominates volume flows into dyes and rubber processing, while intermediate-grade product commands premium positioning in pharmaceutical and agrochemical precursor chains. End-use demand in coatings and adhesives applications is expanding fastest as formulation chemists seek controlled-evaporation aromatic carriers.
EPA oversight of chlorinated benzene emissions and REACH registration requirements in Europe are elevating analytical certification burdens for importers and domestic producers alike. China's MEE standards on chlorinated aromatic effluents are forcing capacity upgrades at Shandong and Jiangsu manufacturing clusters. Stakeholders must monitor regulatory divergence between jurisdictions to determine where capital deployment for purification and environmental compliance yields durable access advantages.
Market Dynamics
REACH registration deadlines and EPA emission caps are forcing purification investments that bifurcate the supplier base between integrated aromatic complexes and standalone chlorinators.
Growth Catalysts
- Agrochemical precursor demand:Nitrochlorobenzene synthesis for herbicide intermediates consumes rising volumes of intermediate-grade material in China and India.
- REACH compliance deadlines:European registration requirements for chlorinated aromatics are consolidating qualified supplier lists and locking in volume commitments from compliant producers.
- Coatings formulation expansion:Controlled-evaporation solvent properties are penetrating automotive refinish and industrial maintenance coatings in Germany and the United States.
Market Restraints
- Benzene feedstock volatility:Crude-linked aromatic pricing compresses margins for non-integrated chlorinators without captive naphtha crackers.
- China supply concentration:Shandong and Jiangsu province clusters control over half of exportable capacity, creating single-geography disruption exposure.
- Chlorinated solvent substitution:Diphenyl ether and alternative aromatic carriers are displacing monochlorobenzene in select European textile processing applications.
Strategic Opportunities
- India agrochemical formulators:Domestic pesticide production under PLI scheme incentives is creating import-substitution demand for pharmaceutical-grade material.
- Pharmaceutical-grade certification:USP and EP monograph compliance opens precursor supply to regulated API manufacturers in Switzerland and Ireland.
- Continuous chlorination technology:Membrane-cell integration with catalytic benzene conversion is reducing effluent loads and unlocking site expansion permits.
Industry Challenges
- Analytical chemist scarcity:Chlorinated aromatic impurity profiling at ppb levels requires specialized GC-MS expertise that competes with pharmaceutical QA budgets.
- Legacy asset retrofit costs:Batch chlorinators face eight-figure capex burdens to meet MEE effluent standards without production shutdowns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Monochlorobenzene Market |
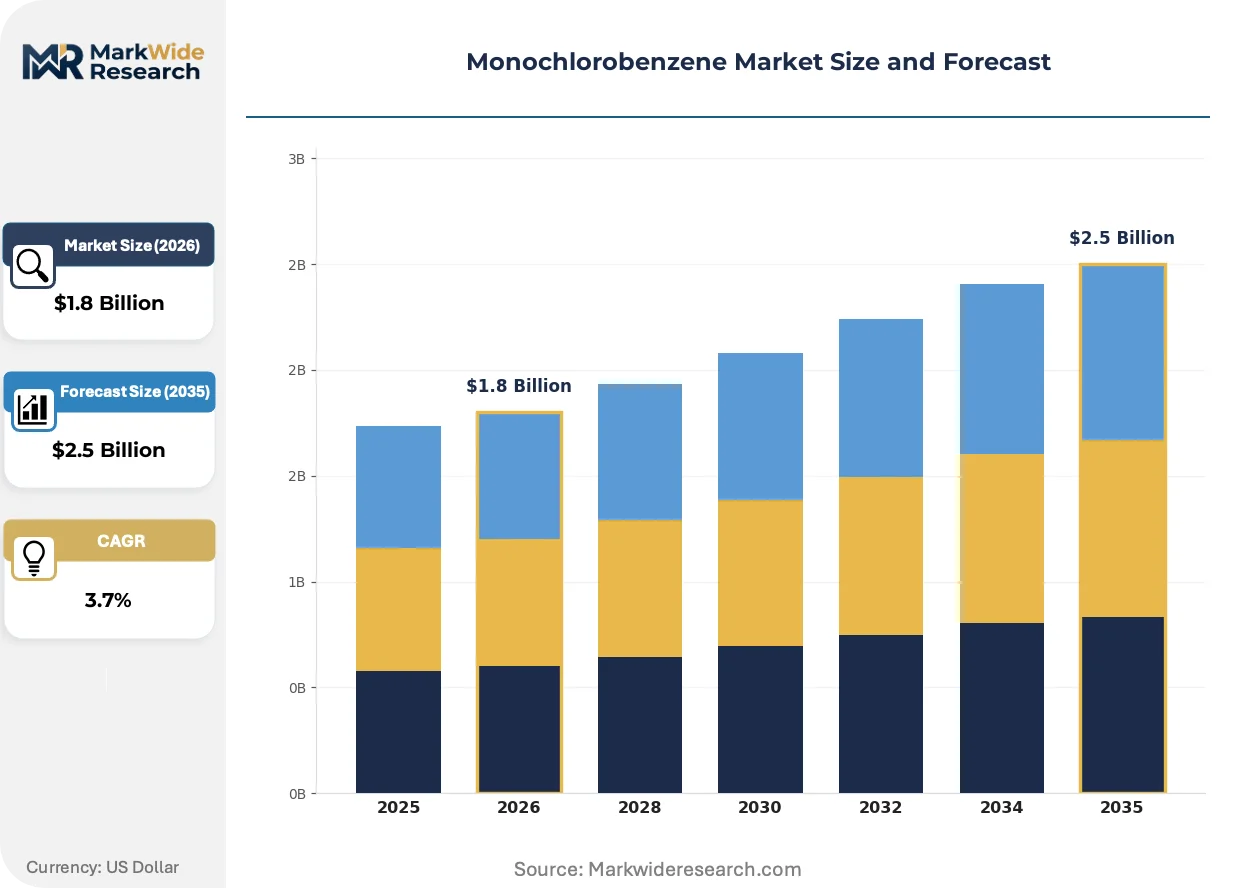
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent, Intermediate, Chemical Reagent, Pesticide End Use Industry: Aromatics, Pharmaceuticals, Agrochemicals, Coatings Application: Dyes, Rubber, Adhesives, Inks Form: Liquid, Solid, Concentrate, Emulsion |
| Companies Covered | Arkema SA, Bayer AG, Kureha Corporation, Henan Kaipu Chemical Co. Ltd., PPG Industries Inc., BASF SE, Dow Chemical Company, Lanxess AG, China Petrochemical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Monochlorobenzene Market Shifts & Advancements
Catalytic process intensification and regulatory analytics are compressing the viable production base while opening premium-grade niches for compliant operators.
Membrane-based chlorination catalysts are replacing ferric chloride systems in European and Chinese facilities. Agrochemical formulators in Jiangsu province are adopting the technology fastest, driven by MEE enforcement timelines. The shift is rendering obsolete conventional batch reactors with their higher effluent treatment burdens and energy intensity.
EPA Method 8260D revisions for chlorinated benzene detection in air emissions are tightening reporting thresholds for US-based processors. The rule changes are forcing capital allocation toward closed-loop sampling systems and real-time mass spectrometry monitoring. Pharmaceutical-grade producers in New Jersey and Texas are absorbing the largest compliance costs, passing through specifications to agrochemical customers.
Direct mill supply contracts are displacing distributor intermediaries in Asian dye and rubber chemical procurement. Large formulators in Zhejiang province now negotiate annual volume commitments with Shandong producers, bypassing regional traders. The disintermediation is most visible in solvent-grade material flows, where price transparency from integrated producers compresses trader margins to single-digit percentages.
Monochlorobenzene Market Segmentation
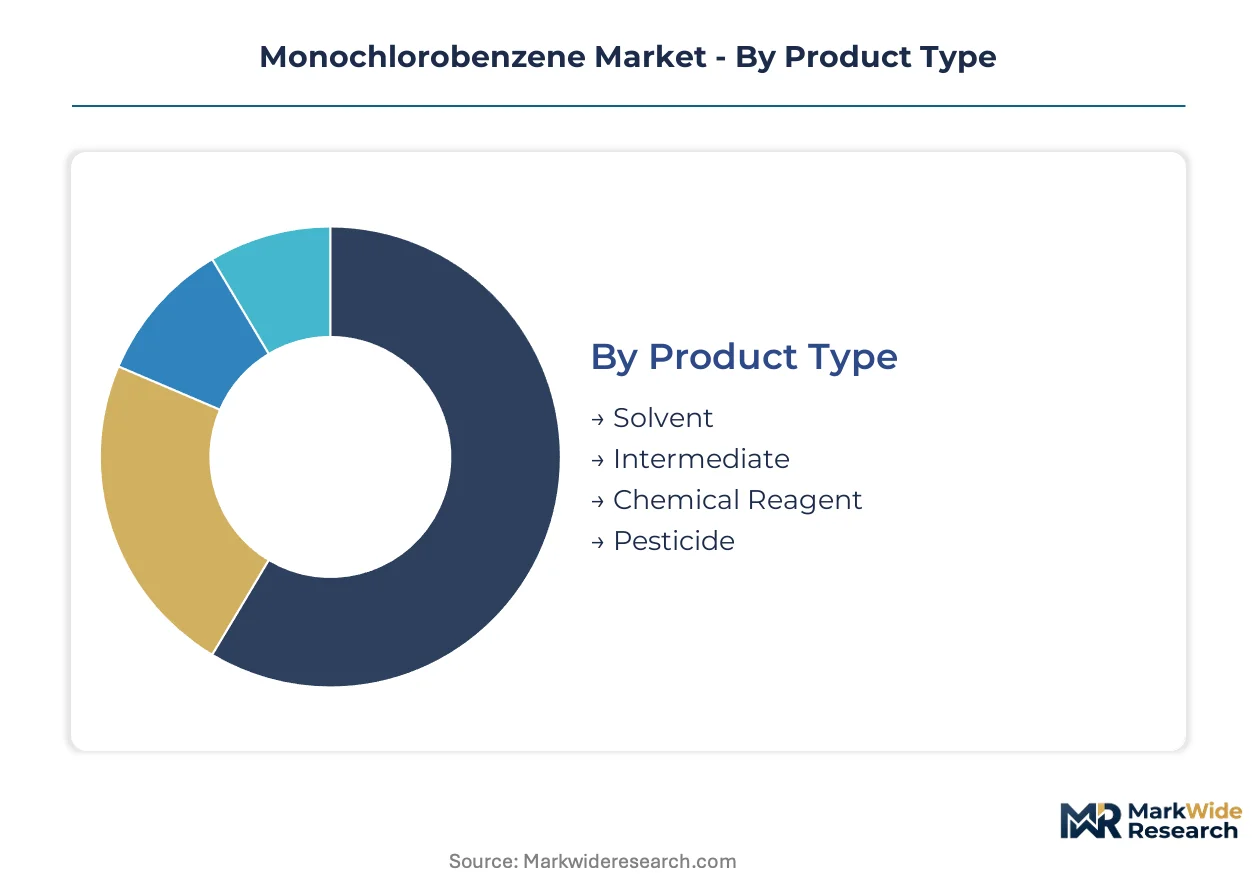
Segmentation in monochlorobenzene markets separates volume-driven solvent flows from specification-sensitive pharmaceutical and agrochemical precursor chains. Distinct purity, certification, and handling requirements create non-overlapping procurement channels that shape supplier qualification strategies.
Product Type:
Cost tier differentiation separates commodity solvent material from premium-grade certified products.
- Solvent:Technical-grade material at 99.5% purity serves dye manufacturing and rubber processing. Demand concentrates in Shandong province dye houses seeking controlled-evaporation carriers for textile coloration.
- Intermediate:Tighter impurity specifications support nitrochlorobenzene synthesis for herbicide precursors. Agrochemical formulators in Jiangsu province drive volume as domestic chlorination capacity expands downstream derivative production.
- Chemical Reagent:Laboratory and analytical applications require sub-ppm impurity profiles for chromatography standards.
- Pesticide:Registered-grade material meets FAO/WHO specifications for active ingredient synthesis in regulated markets.
Solvent commands the established base. The steepest expansion runs through Intermediate.
End Use Industry:
Application maturity varies sharply across regulated pharmaceutical channels versus commoditized aromatic derivative processing.
- Aromatics:Captive consumption within integrated benzene-chlorination complexes supplies diphenyl ether and polyphenylene oxide resin production. Lanxess AG's European facilities anchor this segment through backward integration into feedstock aromatics.
- Pharmaceuticals:USP and EP monograph compliance opens precursor supply to API manufacturers in Switzerland and Ireland. Analytical chemist scarcity at ppb-level impurity profiling constrains qualified supplier expansion.
- Agrochemicals:Nitrochlorobenzene demand for herbicide intermediates climbs fastest in China and India under PLI scheme incentives.
- Coatings:Automotive refinish and industrial maintenance formulations in Germany absorb controlled-evaporation grades.
Aromatics retains volume leadership. Pharmaceuticals climbs the fastest on certification premiums.
Application:
Customer type separation distinguishes bulk industrial processors from formulation specialists requiring technical service support.
- Dyes:Disperse and reactive dye synthesis in Zhejiang province consumes solvent-grade volumes through direct mill supply contracts bypassing distributors.
- Rubber:Processing aid applications in tire manufacturing favor low-cost solvent material with tolerant impurity specifications.
- Adhesives:Controlled-evaporation properties penetrate automotive assembly and construction sealant formulations in the United States.
- Inks:Gravure and flexographic printing applications require consistent evaporation profiles for film and packaging substrates.
Dye applications anchor established demand. Adhesives gains share fastest on coatings formulation expansion.
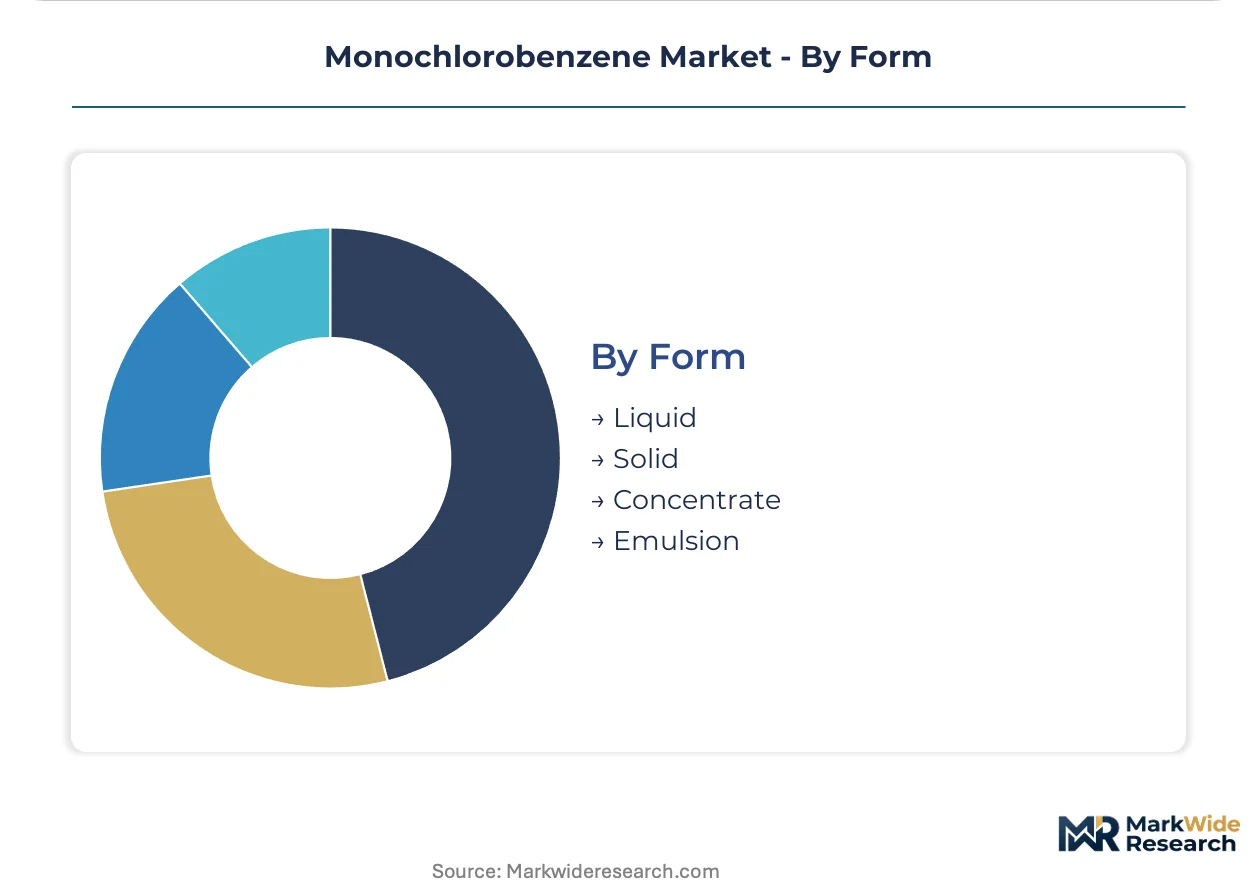
Form:
Supply concentration shapes availability, with liquid dominance reflecting chlorination process economics and handling infrastructure.
- Liquid:Standard drum and tanker delivery of chlorinated benzene at ambient temperature. Batch chlorinators in Jiangsu and Shandong provinces supply this form exclusively.
- Solid:Crystalline or flaked material for specialized handling in laboratory and precision weighing applications.
- Concentrate:High-purity material for dilution at point-of-use in pharmaceutical synthesis requiring solvent flexibility.
- Emulsion:Aqueous-dispersed forms for textile processing applications with water-based formulation requirements.
Liquid holds the volume base. Concentrate expands most quickly on pharmaceutical-grade certification demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MEE standards in China are tightening effluent thresholds faster than EPA timelines in the United States or REACH deadlines in Europe. This regulatory acceleration concentrates investment in purification capacity across Jiangsu and Shandong provinces while forcing importers elsewhere to absorb certification premiums.
China
Agrochemical formulators in Jiangsu province drive intermediate-grade consumption for nitrochlorobenzene synthesis. MEE enforcement on chlorinated aromatic effluents is accelerating membrane-cell technology adoption at Shandong manufacturing clusters. Domestic chlorination capacity expansion now supplies downstream aromatic derivative production that previously relied on imports.
United States
Coatings manufacturers in Texas and New Jersey absorb controlled-evaporation grades for automotive refinish formulations. EPA Method 8260D revisions for chlorinated benzene air emissions are forcing capital allocation toward closed-loop sampling systems. Pharmaceutical-grade producers in these states pass compliance costs through specifications to agrochemical customers.
Germany
Automotive refinish and industrial maintenance coatings in Bavaria and North Rhine-Westphalia consume specification-sensitive solvent grades. REACH registration requirements for chlorinated aromatics are consolidating qualified supplier lists and locking in volume commitments. Lanxess AG's integrated aromatic complexes in these regions sustain captive feedstock advantages through backward integration.
India
Domestic pesticide production under PLI scheme incentives is creating import-substitution demand for pharmaceutical-grade material. CDSCO oversight of active ingredient synthesis is elevating analytical certification burdens for imported chlorobenzene. Maharashtra and Gujarat formulators are negotiating direct supply contracts with Chinese producers to bypass regional distributors.
Switzerland
API manufacturers in Basel and Geneva require USP and EP monograph compliance for precursor supply chains. Swissmedic oversight of pharmaceutical raw materials is tightening impurity profiling requirements at ppb levels. Specialized analytical chemist scarcity constrains qualified supplier expansion into this premium-grade channel.
Monochlorobenzene Market Competitive Landscape
Integrated aromatic complexes and standalone chlorinators split the market into diverging cost structures. The supplier base is bifurcating between captive feedstock operators and merchant producers exposed to benzene volatility. Three archetypes dominate: European integrated chemical conglomerates with backward aromatic control, Chinese provincial specialists with dedicated chlorobenzene lines, and multinational diversified materials groups with pharmaceutical-grade certification. Capacity expansion and M&A consolidation represent the dominant competitive moves as regulatory barriers raise entry costs.
Among European integrated operators, BASF SE and Lanxess AG occupy positions anchored by captive benzene supply and REACH-compliant purification infrastructure. Henan Kaipu Chemical Co. Ltd. exemplifies the Chinese provincial specialist archetype with production concentration in Henan province serving Asian agrochemical formulators. Bayer AG represents the diversified multinational model with pharmaceutical-grade positioning through tight impurity controls.
| Leading Market Players |
|---|
| Arkema SA |
| Bayer AG |
| Kureha Corporation |
| Henan Kaipu Chemical Co. Ltd. |
| PPG Industries Inc. |
| BASF SE |
| Dow Chemical Company |
| Lanxess AG |
| China Petrochemical Corporation |
| Others |
Supply & Pricing Matrix
Shanghai-Ningbo port freight corridors carry Shandong and Jiangsu chlorobenzene volumes to Asian agrochemical formulators, with container rates compressing margins for non-integrated exporters while amplifying price premiums for REACH-certified European material. This logistics-cost wedge reinforces the bifurcation between captive-feedstock operators and merchant chlorinators exposed to benzene volatility.
Pricing Analysis
The customization-premium spread separates standard solvent-grade shipments from pharmaceutical-grade material with USP and EP monograph compliance. Three-tier pricing structure across premium, standard, and economy levels reflects certification burden, volume scale, and geographic delivery cost. Cost compression in standard grades is intensifying because Shandong producers bypass distributors for direct mill supply. Rubber processing houses in Zhejiang province show highest price sensitivity, while Swiss API manufacturers absorb premium tiers without volume elasticity.
Supply Chain Analysis
Extended payment terms from Jiangsu agrochemical formulators are forcing Shandong producers to absorb working-capital strain or cede volume to integrated aromatic complexes. Supply concentrates in China, Germany, and the United States, with benzene feedstock, chlorine supply, and membrane-cell catalysts anchoring input dependencies. Single-source vulnerability runs through Shandong-Jiangsu corridor concentration. Distribution runs through direct mill contracts displacing regional traders in Asian dye and rubber chemical procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Diphenyl ether and alternative aromatic carriers threaten displacement in European textile processing, forcing incumbents to harden specification advantages against substitution.
For Market Incumbents: Pre-empt chlorinated solvent substitution by locking pharmaceutical-grade certification into long-term API supply contracts with Swiss and Irish manufacturers. Deepen backward integration into captive benzene supply at European aromatic complexes to insulate margin structures from crude-linked volatility. Membrane-cell technology adoption at Jiangsu facilities represents the critical lever for MEE compliance without production interruption. For New Entrants and Emerging Players: Build out pharmaceutical-grade purification capacity targeting CDSCO-registered supply to Maharashtra and Gujarat formulators under India's PLI scheme incentives. White-space sits with USP and EP monograph compliance for API precursor chains, where analytical chemist scarcity constrains qualified supplier expansion. Go-to-market leverage rests on direct technical service relationships with agrochemical R&D directors seeking nitrochlorobenzene synthesis partners. For Investors and Strategic Acquirers: REACH-compliant European specialists with integrated aromatic complexes offer durable positioning as regulatory barriers raise entry costs. Long-term viability frames around certification moats rather than volume scale, with membrane-cell technology penetration serving as the inflection signal for operational cost advantage.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane-Cell Technology Adoption | Reduces MEE effluent burdens at Shandong and Jiangsu manufacturing clusters. |
| Backward Integration into Benzene Supply | Captive naphtha cracker access insulates Lanxess and BASF from aromatic volatility. |
| Pharmaceutical-Grade Certification Investment | USP and EP monograph compliance opens Swissmedic-regulated API precursor channels. |
| Direct Mill Supply Contracting | Zhejiang dye houses bypass distributors for price transparency with Shandong producers. |
| Joint Venture with Agrochemical Formulators | Jiangsu province partnerships secure volume commitments for nitrochlorobenzene intermediates. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs/trade data, SEC 10-K filings, and Cefic industry reports through structured interviews with plant managers at chlorobenzene facilities, procurement leads at downstream agrochemical OEMs, distribution channel partners in Asian dye markets, and technical R&D directors overseeing nitrochlorobenzene synthesis. Bottom-up volume modeling triangulates against top-down aromatic derivative consumption estimates.
Forecast inputs include grade tier differentiation, end-use industry concentration, regional production hub evolution, and membrane-cell technology penetration rates across the analysis window. CAGRs derive from segmented demand elasticity and capacity expansion trajectories. Benzene feedstock pricing assumptions and MEE enforcement timelines constitute critical chemical-specific variables.
Stress conditions across benzene volatility bands, MEE compliance acceleration, and chlorinated solvent substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions and scenario boundaries. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Citrus Solvents Market
Solvents
Organic Solvents Market
Solvents
Trichloroacetyl Chloride Market
Solvents
Chloromethane Market
Solvents
Green Solvents and Bio-Solvents Market
Solvents
Global Ethyl Lactate Market
Solvents
2,2-Dimethylbutyryl Chloride Market
Solvents
Crotonaldehyde Market
Solvents
Toluene Derivatives Market
Solvents
Aprotic Solvents Market
Solvents
Chloroacetonitrile Market
Solvents
Hexylene Glycol Market
Solvents
Diethanolamide Market
Solvents
Mineral Turpentine Market
Solvents
Potassium Formate Market
Solvents
Methyl Ethyl Ketone (MEK) Market