
 Solvent Green 7 Market | 2026-2036
Solvent Green 7 Market Size, Share, and Industry Trends Forecast 2026-2036
Solvent Green 7 Market Insights
ISO 14001 environmental management certification is collapsing as a baseline qualifier for Solvent Green 7 suppliers serving EU and North American coatings customers. Clariant AG leverages backward integration into anthraquinone intermediates to sustain margin control across Swiss and German production sites. Sun Chemical Corporation anchors North American ink supply through dedicated liquid dye capacity in Ohio and New Jersey.
Solvent Green 7 denotes an anthraquinone-based solvent dye with a Color Index designation of 59040, exhibiting peak absorption near 670 nm and thermal stability exceeding 280 degrees Celsius in thermoplastic applications. The compound serves primarily as a colorant for synthetic fibers, polyolefin masterbatches, and gravure printing inks where lightfastness requirements exclude azo alternatives. Liquid dye formulations dominate volume throughput in continuous textile dyeing operations, while powder dyes retain margin superiority in small-batch plastics compounding where precise metering justifies premium positioning. Concentrates and pastes accelerate in UV-curable coatings as formulators seek reduced volatile organic compound profiles under tightening air-quality rules.
REACH registration requirements in Europe and EPA TSCA Section 5 premanufacture notifications in the United States elevate compliance costs for new Solvent Green 7 entrants, effectively consolidating supply among incumbent registrants. BIS certification mandates in India and China's GB standards for dye imports further fragment market access along regulatory fault lines. Stakeholders must monitor pending restrictions on halogenated solvents in formulation bases, as these would force rapid reformulation across solvent-based systems without ready aqueous substitutes for high-temperature resin applications.
Market Dynamics
Anthraquinone intermediate supply concentration among Swiss and German producers is compressing margin flexibility for downstream Solvent Green 7 formulators. REACH registration consolidation has eliminated non-incumbent entrants, locking supply relationships around backward-integrated specialty chemical groups.
Growth Catalysts
- REACH compliance mandates:EU coatings and ink formulators face mandatory registration requirements that favor established registrants with dossier completeness, accelerating procurement consolidation toward incumbent suppliers.
- Thermoplastic masterbatch demand:Automotive interior applications in Germany and Japan specify Solvent Green 7 for heat-resistant polyolefin coloration where lightfastness thresholds exclude azo dye alternatives.
- UV-curable coatings conversion:Concentrate and paste formulations gain traction as formulators reduce volatile organic compound emissions to meet tightening air-quality standards in California and Lombardy industrial zones.
Market Restraints
- Anthraquinone feedstock volatility:Crude oil-derived naphthalene and phthalic anhydride price swings transmit directly to Solvent Green 7 production economics, squeezing compounder margins during upstream spikes.
- Swiss-German supply concentration:Backward-integrated producers control critical intermediate streams, creating single-source vulnerability for non-integrated formulators in North America and Asia-Pacific.
- Halogenated solvent dependency:Formulation bases relying on chlorinated carriers face pending restrictions under EU F-Gas Regulation and state-level air-toxic rules in California, with no aqueous substitutes viable above 250 degrees Celsius.
Strategic Opportunities
- India textile corridor expansion:Surat and Tiruppur dyeing clusters seek powder dye alternatives for small-batch polyester processing, creating entry points for REACH-registered suppliers with BIS certification capability.
- UV-LED curing convergence:Narrow-wavelength photoinitiator advances paired with Solvent Green 7 concentrates enable energy-cured wood coatings with sub-5% VOC profiles, opening furniture finishing segments in Bavaria and North Carolina.
- China GB standard alignment:Import dye quality mandates under SAMR supervision create compliance-based differentiation for foreign suppliers with documented heavy-metal testing protocols.
Industry Challenges
- Anthraquinone synthesis expertise scarcity:Specialized chemical engineering talent for Friedel-Crafts acylation and oxidation steps concentrates in Basel-Ludwigshafen corridors, constraining capacity expansion elsewhere.
- ISO 14001 certification timeline compression:Coating customers now demand environmental management system evidence within 90-day supplier qualification windows, straining documentation resources at mid-scale dye houses.
- Liquid-to-powder formulation IP complexity:Proprietary dispersion technologies for continuous textile dyeing systems create licensing friction between equipment OEMs and dye suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solvent Green 7 Market |
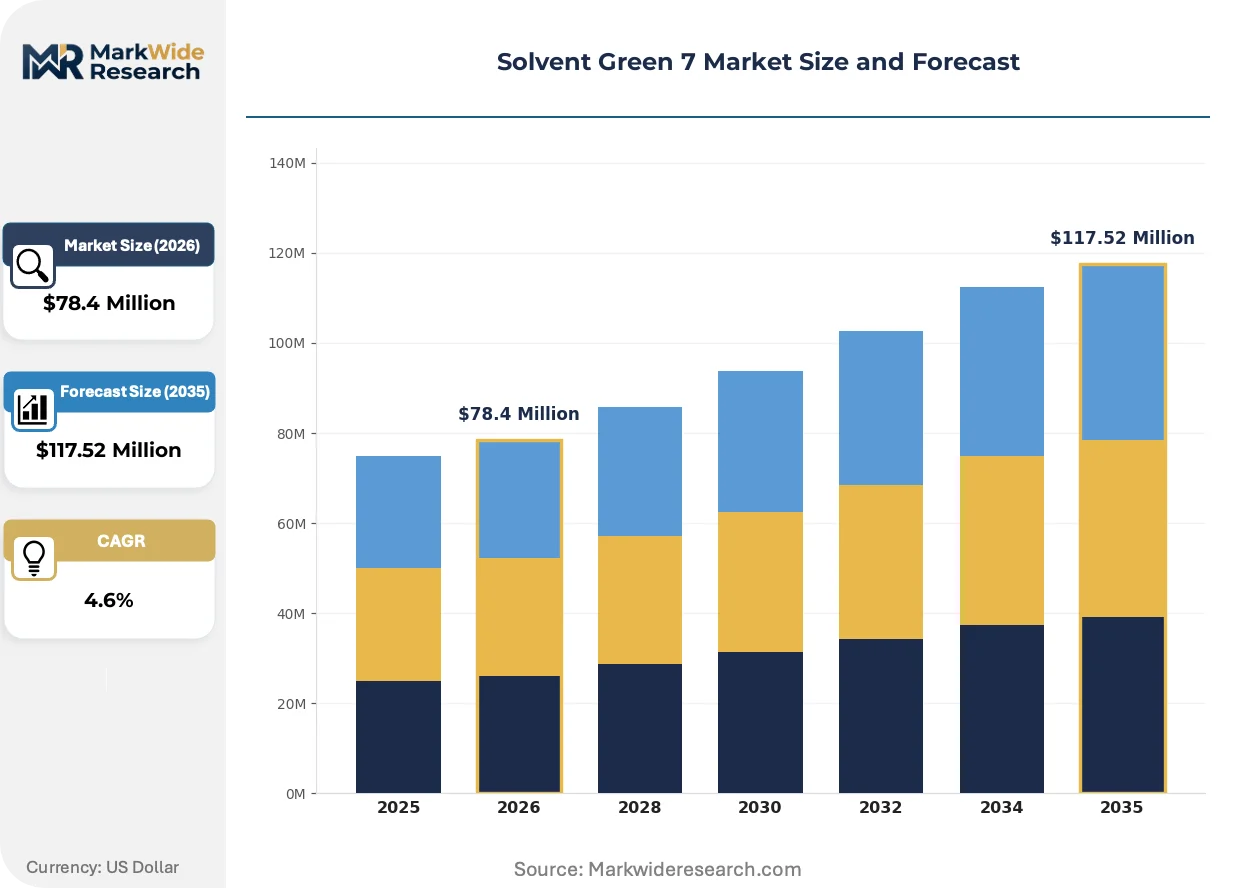
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $117.52 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Dyes, Powder Dyes, Concentrates, Pastes End Use Industry: Textiles, Plastics, Coatings, Inks Formulation Type: Aqueous Solutions, Solvent-Based Systems, UV Curable, Emulsions Packaging Type: Drums, Bags, Bulk Containers, Bottles |
| Companies Covered | Clariant AG, Sun Chemical Corporation, Dystar Group, BASF SE, Anmol Chemical, Deepak Chemtex Private, AkzoNobel, DuPont, LyondellBasell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solvent Green 7 Market Trends and Innovations
Reactive extrusion compounding is displacing conventional masterbatch production for high-temperature resin applications. Formulators now specify dye concentrates with integrated thermal stabilizers rather than separate additive packages.
Encapsulated Solvent Green 7 microspheres with melamine-formaldehyde shells is displacing standard powder grades in polypropylene automotive compounds. Tier-1 suppliers in Stuttgart and Nagoya specify these grades for dashboard and pillar trim where 300-degree Celsius processing temperatures degrade unprotected dyes. The technology compresses color development cycles from three passes to single-pass compounding.
EPA TSCA Section 5 premanufacture notification requirements for new chemical substances now capture modified anthraquinone derivatives with altered substitution patterns. This regulatory expansion delays product line extensions by 18-24 months and elevates legal compliance costs for US market entry. Ink formulators in Ohio and New Jersey respond by sourcing exclusively from TSCA-inventory-listed structures, limiting molecular innovation.
Specification-driven procurement now dominates coatings sector buying. End-users in Bavaria and Michigan issue technical data sheet requirements upfront, eliminating traditional sampling and qualification phases. Distributors with in-house color matching laboratories capture volume previously flowing through merchant chemical traders. This pattern is most visible in automotive refinish and industrial maintenance coatings procurement.
Solvent Green 7 Market Segmentation
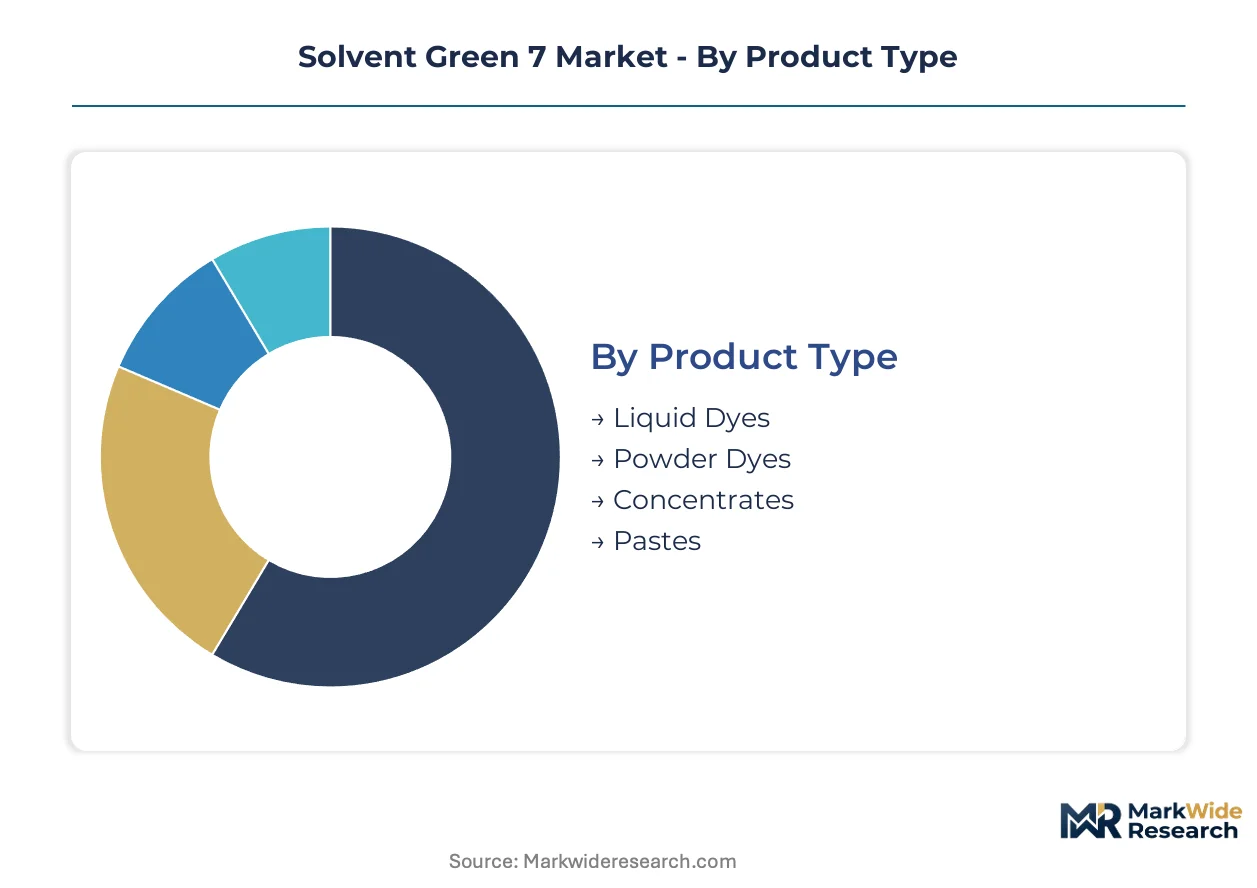
Solvent Green 7 procurement channels diverge sharply by physical form and end-use technical requirements. Powder formulations flow through specialized distributors serving small-batch compounders, while liquid dyes move via direct mill supply agreements with continuous textile operations.
Product Type:
Liquid dyes dominate continuous textile dyeing channels through dedicated tanker deliveries, while powder grades route through regional distributors serving batch compounders. Concentrates and pastes increasingly bypass traditional merchant channels via direct formulation partnerships.
- Liquid Dyes:Homogeneous solutions with dissolved anthraquinone colorant at standardized concentrations enable metered dosing in jet dyeing machines. German and Japanese automotive textile suppliers specify these grades for polyester upholstery where shade consistency across 50,000-meter runs is mandatory.
- Powder Dyes:Spray-dried granules with defined particle size distribution facilitate precise weighing in small-batch plastics compounding. Surat and Tiruppur dye houses in India prefer powder formats for disperse dyeing of polyester fabrics in jig and beam equipment where liquor ratios vary batch-to-batch.
- Concentrates:High-strength preparations with reduced solvent content support UV-curable coating formulators seeking VOC reduction in Lombardy and California regulatory jurisdictions.
- Pastes:Predispersed pigment preparations with rheology modifiers serve gravure ink manufacturers requiring immediate press-ready formulations without milling stages.
Liquid dyes dominate installed base. Concentrates represent where expansion concentrates.
End Use Industry:
Application-driven cost tiers separate commodity textile coloration from specification-grade automotive and electronics applications where lightfastness testing adds margin layers.
- Textiles:Disperse dyeing of polyester and acetate fibers in continuous and batch operations. REACH-registered liquid dyes flow through mill-direct channels to Surat, Tiruppur, and Guangdong corridor processors.
- Plastics:Polyolefin masterbatch production for interior automotive components requiring heat stability above 280 degrees Celsius. Stuttgart and Nagoya compounders specify encapsulated microsphere grades for dashboard applications.
- Coatings:Industrial maintenance and wood finishing segments in Bavaria and North Carolina adopt UV-curable concentrates with sub-5% VOC profiles under tightening air-quality mandates.
- Inks:Gravure and flexographic printing for packaging applications where solvent-based systems retain dominance despite aqueous conversion pressures in EU jurisdictions.
Textiles anchor volume throughput. Coatings is climbing the fastest on regulatory-driven formulation shifts.
Formulation Type:
Supply concentration in anthraquinone intermediates shapes which formulation bases remain economically viable for regional formulators without backward integration.
- Aqueous Solutions:Water-based preparations with surfactant stabilization for textile dyeing operations with effluent treatment capacity. Limited penetration in high-temperature resin applications where water flash-off disrupts processing.
- Solvent-Based Systems:Chlorinated and oxygenated carrier formulations for plastics and coatings where thermal requirements exceed 250 degrees Celsius. EU F-Gas Regulation and California air-toxic rules threaten this segment's continued viability.
- UV Curable:Acrylate-functionalized concentrates with photoinitiator compatibility for energy-cured wood and industrial coatings. Narrow-wavelength LED advances in Bavaria and North Carolina furniture finishing drive specification.
- Emulsions:Oil-in-water dispersions bridging aqueous environmental profiles with solvent-borne performance in selected coating applications.
Solvent-based systems retain installed base dominance. UV curable is gaining share fastest on equipment conversion cycles.
Packaging Type:
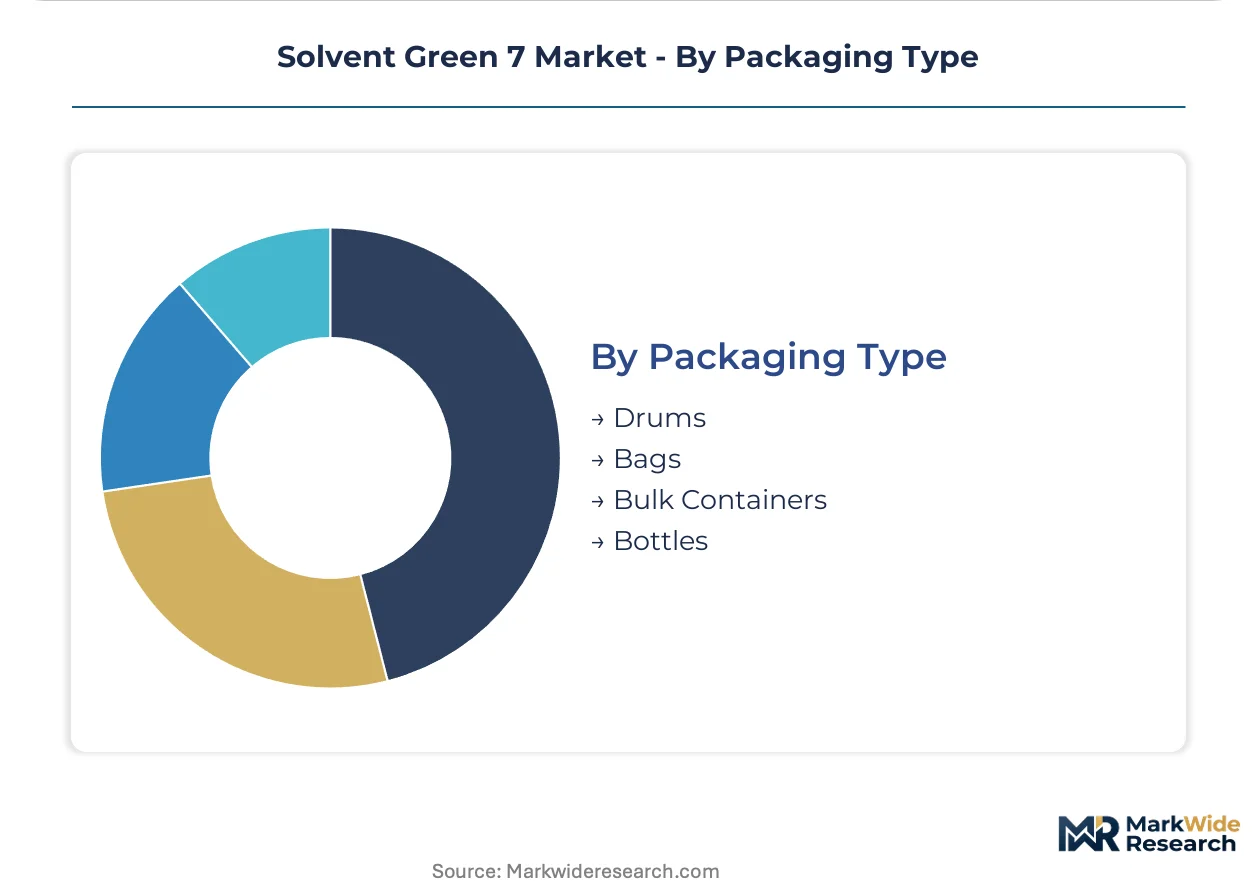
Customer scale and logistics infrastructure determine packaging selection, with bulk formats capturing volume from drum conversions as supply chain integration deepens.
- Drums:Standard 200-liter steel and polyethylene containers for liquid dyes serving mid-scale textile mills and ink manufacturers. Ohio and New Jersey ink compounders specify UN-certified drums for hazardous material compliance.
- Bags:Multi-wall paper and polyethylene sacks for powder dyes in 25-kilogram units. Indian and Chinese textile corridors favor bagged powder for manual handling in smaller dye house operations.
- Bulk Containers:Intermediate bulk containers and tanker deliveries for continuous textile dyeing mills with dedicated storage and metered dosing systems. German automotive textile suppliers specify bulk liquid to minimize handling stages.
- Bottles:Laboratory and sampling quantities for color matching and qualification trials in coatings and plastics laboratories.
Drums constitute the broadest installed base. Bulk containers is where procurement consolidation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive textile buyers in Germany and ink manufacturers in the United States concentrate procurement volumes, while polyester dyeing clusters in India and China absorb powder formulations through regional distribution networks.
Germany
Automotive interior compounders in Stuttgart specify encapsulated Solvent Green 7 microspheres for dashboard and pillar trim applications requiring 300-degree Celsius thermal stability. ECHA REACH registration mandates favor incumbent suppliers with complete dossier submissions. Bavarian furniture finishers adopt UV-curable concentrates with sub-5% VOC profiles under tightening EU F-Gas Regulation enforcement.
United States
Gravure ink manufacturers in Ohio and New Jersey source liquid dye formulations through dedicated tanker deliveries from TSCA-inventory-listed suppliers. EPA Section 5 premanufacture notification requirements delay new anthraquinone derivative introductions by 18-24 months. California air-toxic rules on halogenated solvents force reformulation efforts without viable aqueous substitutes for high-temperature resin applications.
India
Surat and Tiruppur textile dyeing clusters seek powder dye alternatives for small-batch polyester processing in jig and beam equipment. BIS certification mandates create compliance barriers for unregistered foreign suppliers. Maharashtra-based masterbatch compounders specify REACH-registered liquid dyes for automotive upholstery contracts with German OEMs.
China
Guangdong corridor processors drive continuous textile dyeing volumes through mill-direct liquid dye procurement. SAMR GB standards for dye imports require documented heavy-metal testing protocols that fragment market access. Shandong-based plastics compounders favor powder grades for precise metering in small-batch polyolefin coloration.
Japan
Nagoya automotive suppliers specify encapsulated dye grades for heat-resistant interior components matching German performance benchmarks. METI chemical substance regulations align with REACH principles, streamlining procurement from EU-registered suppliers. Osaka-based ink formulators maintain solvent-based gravure capacity despite aqueous conversion pressures in export markets.
Solvent Green 7 Market Competitive Landscape
Player mix skews toward backward-integrated specialty chemical groups with captive anthraquinone intermediate production. Supply relationships have consolidated around incumbent REACH registrants, eliminating non-registered entrants from EU procurement channels. Two strategic archetypes dominate: Swiss-German intermediate producers with margin control, and regional formulators with BIS or TSCA compliance capabilities. Competitive moves center on capacity expansion in UV-curable concentrates and geographic licensing partnerships for dispersion technologies.
Among Swiss-German chemical conglomerates, Clariant AG and BASF SE occupy positions exemplifying backward-integrated supply control over critical anthraquinone streams. Sun Chemical Corporation anchors North American representation through liquid dye capacity in Ohio and New Jersey, sitting within the regional compliance-specialist tier that serves TSCA-constrained formulators.
| Leading Market Players |
|---|
| Clariant AG |
| Sun Chemical Corporation |
| Dystar Group |
| BASF SE |
| Anmol Chemical |
| Deepak Chemtex Private |
| AkzoNobel |
| DuPont |
| LyondellBasell |
| Others |
Pricing and Supply Chain Analysis
Minimum efficient scale in anthraquinone intermediate production—typically 5,000 metric tons annually—locks cost advantages to Swiss-German chemical conglomerates with captive naphthalene oxidation capacity. This concentration compresses margin flexibility for non-integrated formulators in North America and Asia-Pacific, establishing price floors indexed to crude oil-derived feedstock volatility.
Pricing Analysis
Cost-plus contracts with naphthalene and phthalic anhydride indexation dominate long-term supply agreements between backward-integrated producers and automotive compounders. Three-tier pricing structure across REACH-registered premium grades, ISO 14001-certified standard tiers, and economy powder formulations for Indian textile houses separates procurement channels. Cost compression in liquid dye grades is intensifying because automotive textile buyers in Germany consolidate volumes through mill-direct tanker deliveries. Small-batch plastics compounders in Surat and Tiruppur exhibit highest price sensitivity, while Stuttgart automotive suppliers accept premium positioning for encapsulated microsphere grades with integrated thermal stabilizers.
Supply Chain Analysis
Strategic stockpiling of anthraquinone intermediates prevails among non-integrated formulators buffering against Swiss-German supply concentration, while just-in-time liquid dye deliveries dominate continuous textile mills with dedicated storage infrastructure. Manufacturing gravity centers on Switzerland, Germany, and China, with India emerging as a formulation hub for powder grades. Critical input streams draw from crude oil-derived naphthalene, phthalic anhydride, and chlorinated solvent carriers. Single-source vulnerability from Basel-Ludwigshafen intermediate concentration threatens supply continuity. Distribution runs through specialized chemical distributors with in-house color matching laboratories serving coatings sector procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UV-LED curing convergence and pending F-Gas Regulation restrictions on halogenated solvents are disrupting formulation economics, compressing timelines for incumbent repositioning and opening white-space for compliance-ready entrants.
For Market Incumbents: Consolidate backward integration into anthraquinone intermediates through long-term offtake agreements with Ludwigshafen corridor producers, insulating margin control against naphthalene price spikes. Expand UV-curable concentrate capacity in Ohio and Bavaria to capture furniture finishing demand as California and Lombardy air-toxic rules tighten. Defend against regional formulators with BIS certification by accelerating REACH dossier updates for modified substitution patterns.
For New Entrants and Emerging Players: BIS certification fast-track through Maharashtra-based testing laboratories unlocks Surat and Tiruppur textile corridor access where powder dye demand exceeds registered supplier capacity. Target small-batch polyester processing in Indian jig and beam equipment where liquor ratio variability favors powder format flexibility. Pursue licensing partnerships with Japanese dispersion technology holders to bypass proprietary liquid-to-powder IP friction in continuous dyeing systems.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors backward-integrated specialty chemical groups with captive intermediate streams and established REACH dossier completeness. Long-term viability rests on regulatory moat durability rather than volume scale, with five-to-ten year windows favoring incumbent consolidation over de novo entry. Monitor EPA TSCA Section 5 notification backlogs as inflection indicator for US market access friction and stranded innovation risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Anthraquinone Intermediates | Captive naphthalene oxidation capacity in Basel-Ludwigshafen corridors locks margin control against feedstock volatility. |
| UV-Curable Concentrate Capacity Expansion | Bavarian and North Carolina furniture finishers specify sub-5% VOC grades under tightening F-Gas Regulation enforcement. |
| BIS Certification Fast-Track Investment | Maharashtra-based testing capability unlocks Surat and Tiruppur dye house procurement previously blocked to unregistered foreign suppliers. |
| Encapsulated Microsphere Technology Licensing | Stuttgart and Nagoya automotive compounders specify melamine-formaldehyde shell grades for 300-degree Celsius processing temperatures. |
| REACH Dossier Update Acceleration | ECHA registration completeness defends EU procurement channel access against regional formulators with partial compliance. |
Research Methodology
Initial hypotheses were tested against primary input from plant managers at anthraquinone intermediate facilities, procurement leads at German automotive textile suppliers, distribution channel partners serving Indian dye houses, and technical R&D directors at ink formulators in Ohio and New Jersey, and refined through secondary validation against customs and trade data, SEC 10-K filings from listed chemical conglomerates, ECHA registration dossiers, and BIS certification records. Bottom-up volume modeling across powder, liquid, concentrate, and paste formulations triangulated against top-down value estimates from regional production cluster analysis.
Variance decomposition across product type, end-use industry, formulation base, packaging format, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation with macroeconomic drivers including automotive production cycles and textile processing capacity expansion. Industry-specific forecast inputs incorporated UV-LED curing equipment installation rates and pending F-Gas Regulation implementation timelines.
Decision-makers should treat outputs as directional under assumptions of continued REACH registration consolidation and stable crude oil-derived feedstock pricing; material deviation would warrant model refresh. Forecasts reflect base-case assumptions regarding regulatory enforcement intensity and intermediate supply concentration durability. Revision becomes warranted when halogenated solvent restriction thresholds or anthraquinone synthesis capacity expansion crosses materiality thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Propylene Glycol Methyl Ether Market
Solvents
Hydrocarbon Solvents Market
Solvents
C2 Chlorinated Solvents Market
Solvents
Tetraethyl Benzene Market
Solvents
North America Toluene Market
Solvents
Global Dipropylene Glycol N-Butyl Ether Market
Solvents
Electronic Cleaning Solvents Market
Solvents
Asia-Pacific Ethane Market
Solvents
Pharmaceutical Solvent Market
Solvents
Global 2-Ethoxyethanol Market
Solvents
Global Green and Bio-Based Solvents Market
Solvents
Triacetin Market
Solvents
2-Butanone Market
Solvents
Diethylene Glycol Monobutyl Ether Market
Solvents
1, 1-Difluoroethane Market
Solvents
Global Glycol Market