
 Diethanolamide Market | 2026-2036
Diethanolamide Market Size, Share, and Industry Trends Forecast 2026-2036
Diethanolamide Market Intelligence
EU REACH registration requirements for fatty acid amides is decoupling legacy supply chains from European personal care markets. BASF SE leverages integrated oleochemical feedstock access to sustain cost-competitive cosmetic-grade output. Dow anchors North American industrial-grade supply through proprietary ethoxylation technology. LG Chem competes on scale in Asian detergent-grade production, operating multi-product surfactant facilities in South Korea.
Diethanolamide refers to the condensation product of diethanolamine with fatty acids, typically exhibiting a pH of 8.5-10.5 in aqueous solution and functioning primarily as a non-ionic surfactant, foam stabilizer, and viscosity builder in formulated consumer and industrial products. Cosmetic-grade diethanolamide leads value contribution due to stringent impurity limits and certification overhead, while industrial-grade diethanolamide sustains volume throughput across institutional cleaning and metalworking fluid applications. Detergent-grade material occupies the price-sensitive middle tier, with margin pools concentrating in personal care and home care end-user channels where formulation differentiation commands premium positioning.
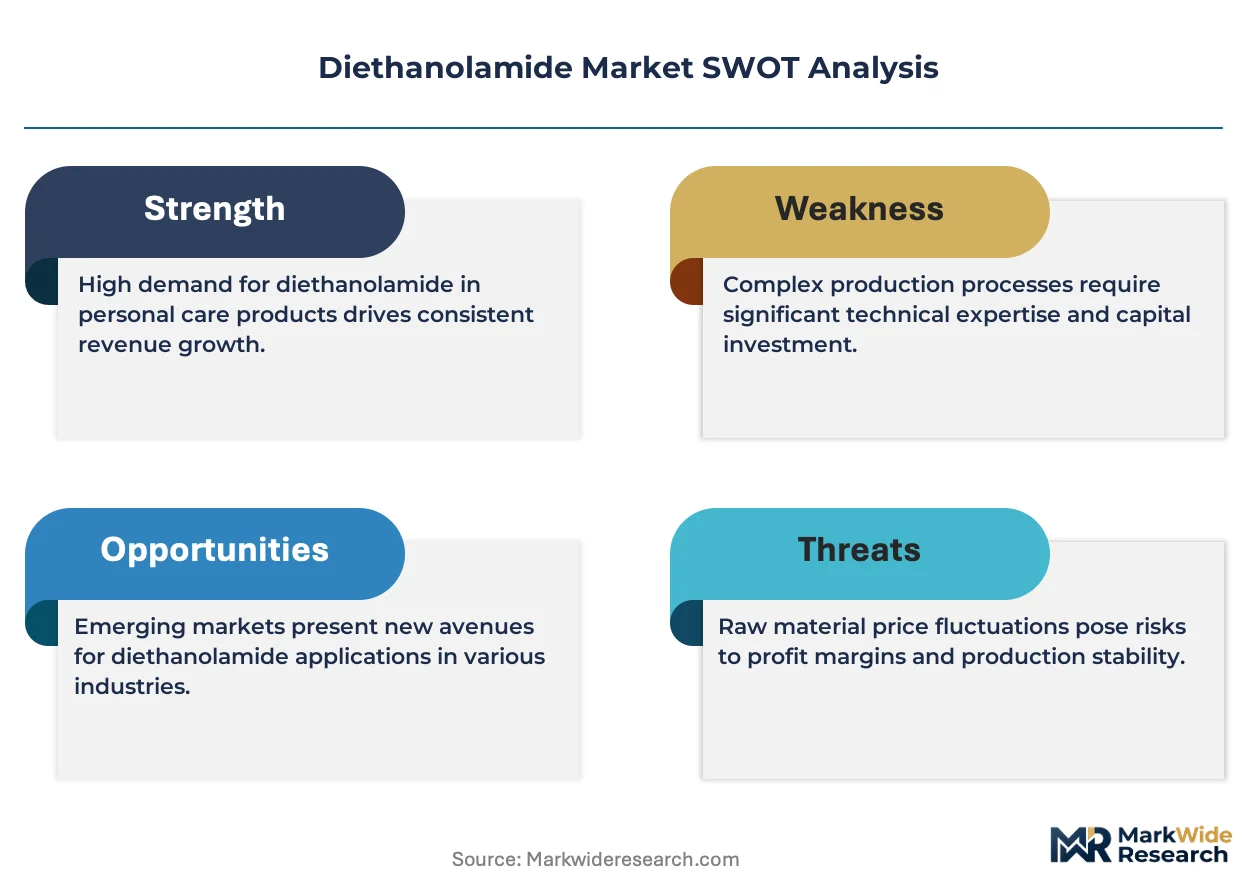
EPA oversight under the Toxic Substances Control Act shapes US market access for imported diethanolamide, while REACH Annex XVII restrictions on diethanolamine content in cosmetics steer European product standards. China's GB standards for surfactant purity, administered by SAMR, create parallel compliance obligations for suppliers targeting domestic cosmetic manufacturers. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether regional formulation customization or unified global specifications offer superior capital efficiency.
Market Dynamics
REACH Annex XVII restrictions on diethanolamine content in cosmetics are forcing European formulators to redesign mild cleansing systems, while Southeast Asian manufacturing clusters absorb displaced volume through cost-advantaged oleochemical feedstock access.
Growth Catalysts
- Thailand cosmetic manufacturing expansion:Thai formulators are scaling diethanolamide procurement for export-oriented personal care products, leveraging regional palm kernel oil derivatives and ASEAN trade integration.
- EPA TSCA import screening:Stricter US environmental compliance is filtering out non-compliant Asian suppliers, creating clearance advantages for certified producers with established dossiers.
- Non-ionic surfactant substitution:Alkyl polyglucoside cost inflation is redirecting mild surfactant demand back toward diethanolamide in institutional cleaning formulations.
Market Restraints
- Coconut oil price volatility:La Niña-driven harvest disruptions in Indonesia and Philippines create feedstock cost instability for fatty acid amide producers.
- Chinese GB standard divergence:SAMR-administered surfactant purity thresholds differ from REACH specifications, forcing dual certification costs for multinational suppliers.
- MEA (monoethanolamide) technical displacement:Lower viscosity alternatives are capturing metalworking fluid applications where foam stabilization is secondary.
Strategic Opportunities
- Indonesia downstream integration:Domestic oleochemical producers are backward-integrating into amide production, capturing margin pools previously exported to Malaysian refiners.
- EU Green Deal bio-based mandates:Renewable carbon certification is creating premium positioning for RSPO-mass balance diethanolamide in European personal care channels.
- Direct-to-compounder digital platforms:Specialty chemical marketplaces are disintermediating traditional distributor networks for mid-volume detergent-grade orders.
Industry Challenges
- Cosmetic-grade impurity analytics:Nitrosamine detection at ppb levels requires capital-intensive LC-MS/MS capabilities that smaller producers struggle to justify.
- REACH registration timeline compression:Legacy substance dossier updates for diethanolamide variants are consuming regulatory affairs bandwidth ahead of 2026 deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diethanolamide Market |
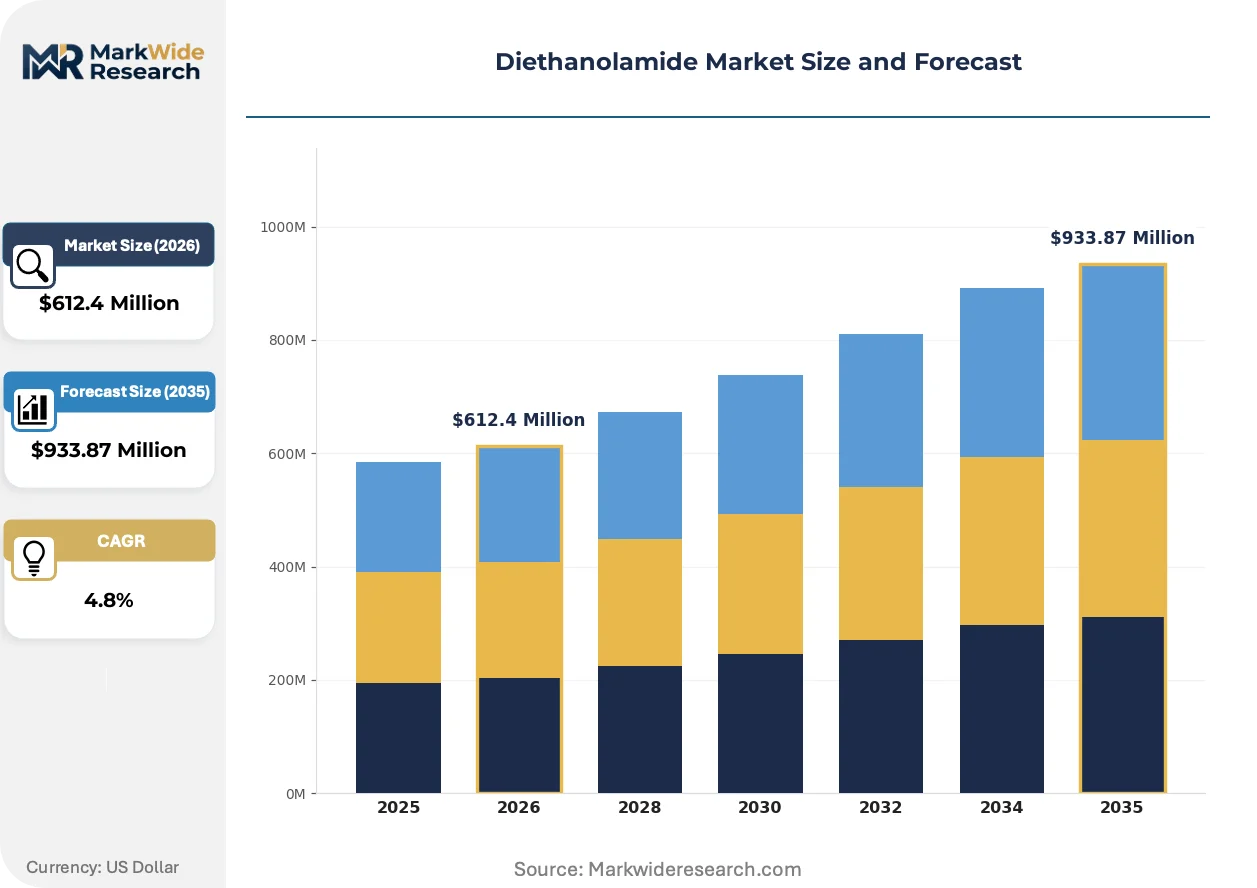
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $933.87 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cosmetic Grade, Industrial Grade, Pharmaceutical Grade, Detergent Grade Application: Personal Care, Home Care, Industrial Cleaners, Textile Processing End User: Cosmetic Manufacturers, Cleaning Product Suppliers, Textile Manufacturers, Pharmaceutical Companies Distribution Channel: Online Retailers, Distributors, Direct Sales, Wholesalers |
| Companies Covered | SABIC, Air Liquide, Dow, Formosa Plastics Corporation, Exxon Mobil Corporation, BASF SE, Merck KGaA, LG Chem, INEOS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diethanolamide Market Strategic Shifts & Innovations
Formulation science is converging with supply chain traceability demands, creating pressure for verified sustainable feedstocks alongside performance-optimized surfactant architectures.
Enzymatic amidation processes are unifying mild reaction conditions with reduced energy intensity. European specialty chemical producers are piloting lipase-catalyzed routes to cosmetic-grade diethanolamide, eliminating high-temperature distillation steps. This technology is compressing capital requirements for entry-grade production while enabling carbon footprint claims that satisfy CSRD reporting obligations.
REACH restriction updates are tightening nitrosamine limits across rinse-off cosmetics. ECHA guidance documents now specify analytical methodologies that exceed prior industry practice, forcing reformulation of legacy diethanolamide-containing products. German personal care manufacturers are responding with supply chain segregation protocols and dedicated nitrosamine-free production lines.
Compounders are consolidating surfactant procurement around certified sustainable palm derivatives. Large European home care brands are mandating Mass Balance or Segregated supply chain certification for foam stabilizers, displacing uncertified Asian supply. This preference shift is most visible in German and French detergent markets, where retail private label specifications now exclude conventional feedstock sourcing.
Diethanolamide Market Segmentation
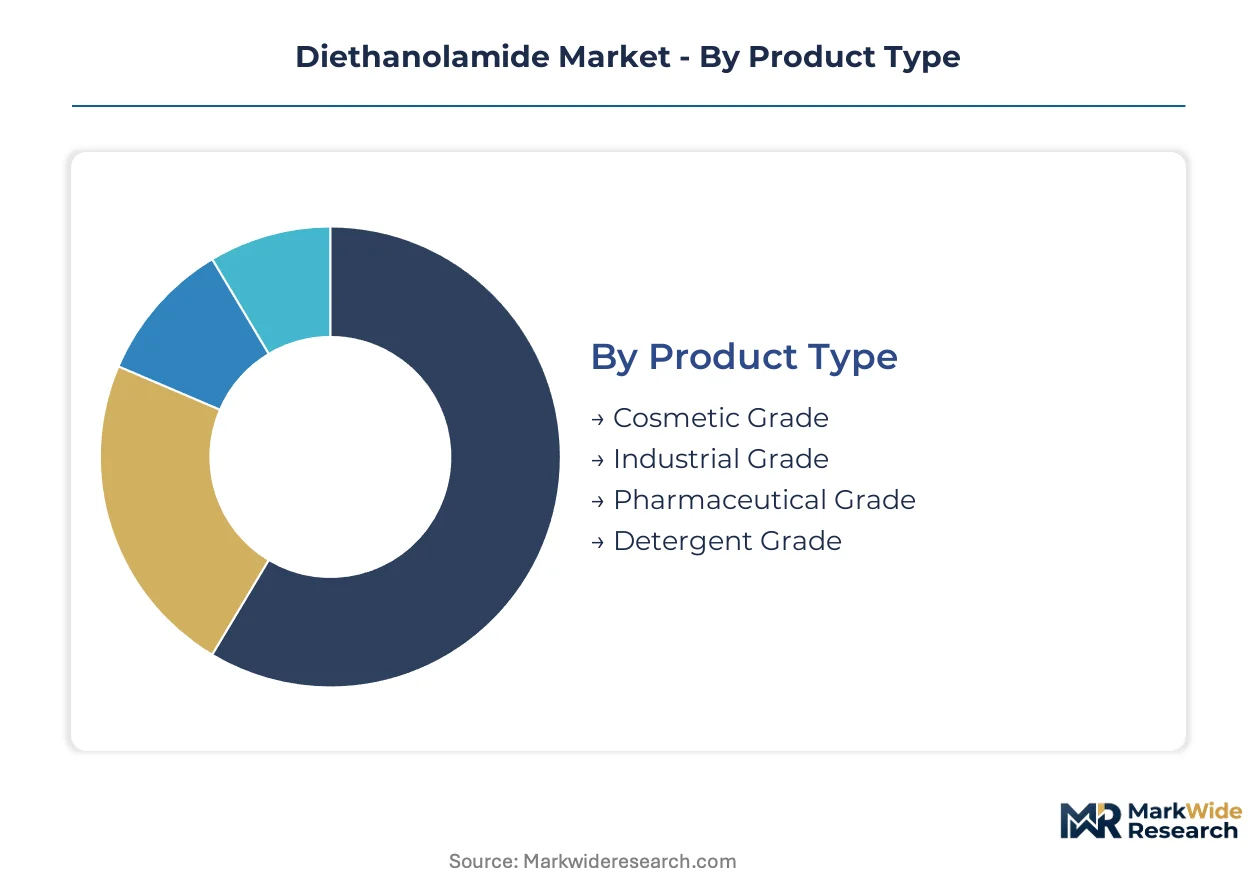
Diethanolamide procurement decisions hinge on purity thresholds that vary sharply across end-use channels. Formulators upgrade specifications when switching from industrial cleaning to cosmetic applications, triggering reformulation cycles and supplier requalification.
Product Type:
Grade selection follows a replacement cycle driven by regulatory tightening rather than performance degradation. European REACH deadlines and US EPA screening protocols are pushing industrial users toward cosmetic-grade specifications even where technical requirements would permit lower purity.
- Cosmetic Grade:Nitrosamine limits measured at parts-per-billion levels using LC-MS/MS protocols. German personal care manufacturers are segregating production lines to guarantee contamination-free output for rinse-off applications. REACH Annex XVII compliance consumes substantial regulatory affairs bandwidth.
- Industrial Grade:Foam stabilization and viscosity building in metalworking fluids and institutional cleaners. Dow anchors North American supply through proprietary ethoxylation technology. EPA TSCA import screening filters out non-compliant Asian suppliers.
- Pharmaceutical Grade:Stringent impurity documentation for excipient applications.
- Detergent Grade:Price-sensitive mid-tier positioning for home care formulators.
Industrial Grade sits at the top of the volume ranking, with Cosmetic Grade climbing the fastest.
Application:
Application selection concentrates where formulation differentiation commands premium positioning. Margin pools align with end-user willingness to pay for certified sustainable feedstocks and verified supply chain traceability.
- Personal Care:Mild cleansing systems for shampoos and body washes. Thai formulators are scaling procurement for export-oriented products, leveraging regional palm kernel oil derivatives and ASEAN trade integration.
- Home Care:Foam stabilizers in dishwashing liquids and laundry detergents. Large European brands mandate Mass Balance or Segregated RSPO certification, displacing uncertified Asian supply in German and French retail channels.
- Industrial Cleaners:Alkyl polyglucoside cost inflation redirects mild surfactant demand back toward diethanolamide in institutional formulations.
- Textile Processing:Wetting agents and softening auxiliaries in fabric finishing.
Home Care generates the largest revenue pool, with Personal Care expanding most quickly.
End User:
Customer type determines procurement channel preferences and certification requirements. Direct compounder relationships are displacing traditional distributor networks for mid-volume orders.
- Cosmetic Manufacturers:Nitrosamine-free production lines require dedicated supply chain segregation protocols. ECHA guidance documents specify analytical methodologies exceeding prior industry practice.
- Cleaning Product Suppliers:Institutional and household formulators balance cost against foam performance specifications.
- Textile Manufacturers:Fabric finishing operations in Southeast Asian manufacturing clusters.
- Pharmaceutical Companies:Excipient applications with documentation-intensive qualification processes.
Cosmetic Manufacturers command the steepest pricing tiers, with Cleaning Product Suppliers representing the broadest volume base.
Distribution Channel:
Channel configuration reflects order scale and technical service intensity. Specialty chemical marketplaces are disintermediating traditional networks for standardized detergent-grade material.
- Online Retailers:Digital platforms consolidating mid-volume procurement for compounders seeking price transparency.
- Distributors:Traditional networks retaining relevance for cosmetic-grade material requiring technical support and certification documentation.
- Direct Sales:Strategic accounts with volume commitments and collaborative formulation development.
- Wholesalers:Bulk throughput for industrial-grade applications with standardized specifications.
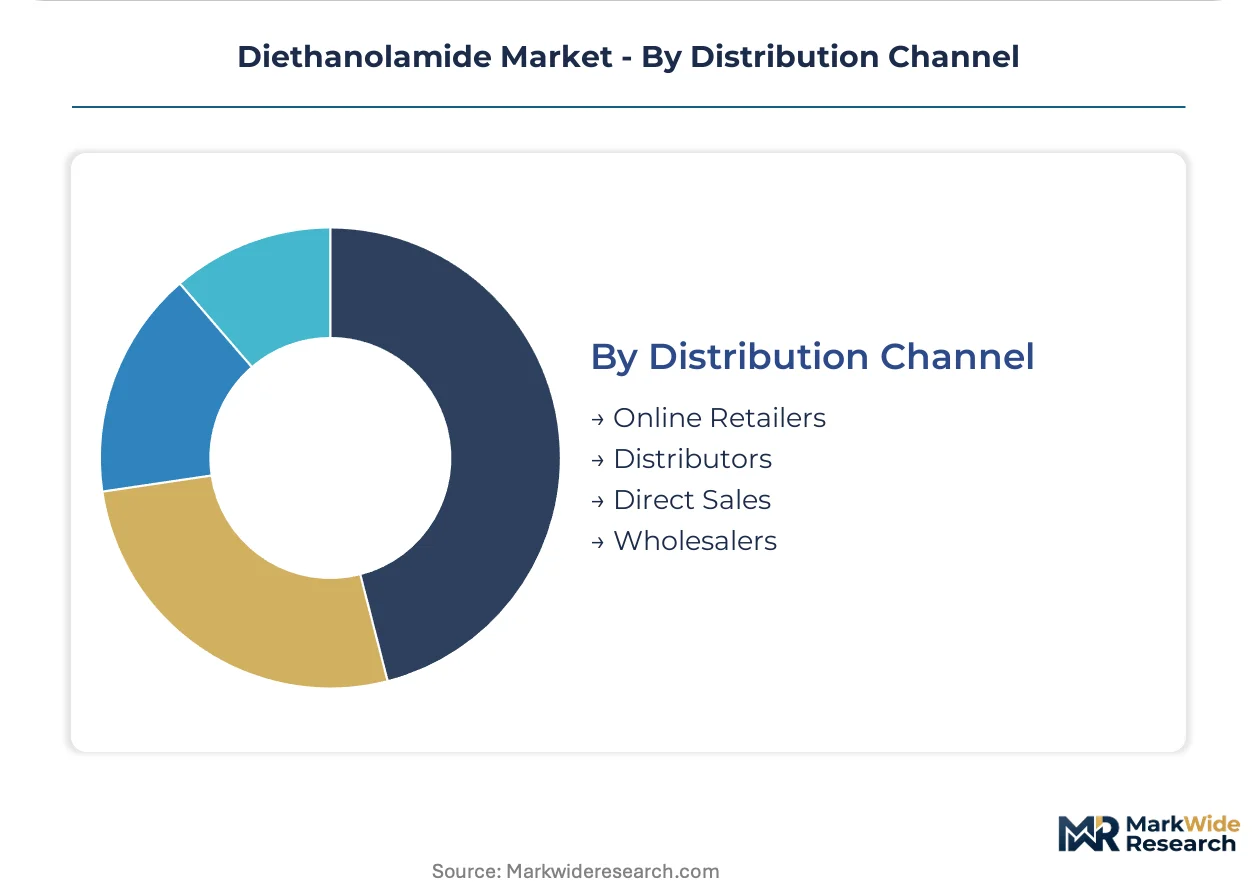
Distributors still handle the majority of cosmetic-grade volume, with Online Retailers gaining share fastest in detergent-grade segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diethanolamide production scaled through European oleochemical hubs before Southeast Asian palm kernel oil clusters captured cost-advantaged feedstock access. Regional demand patterns now diverge between REACH-regulated European cosmetic channels and EPA-screened US industrial applications.
Germany
Personal care formulators in North Rhine-Westphalia drive cosmetic-grade procurement for rinse-off applications. ECHA guidance on nitrosamine detection protocols exceeds prior industry analytical standards. BASF SE leverages integrated Ludwigshafen oleochemical infrastructure to sustain cost-competitive output.
United States
Metalworking fluid compounders anchor industrial-grade consumption across Midwest manufacturing corridors. EPA TSCA import screening filters out non-compliant Asian suppliers, creating clearance advantages for certified producers. Dow operates proprietary ethoxylation capacity along the Gulf Coast.
Thailand
ASEAN trade integration positions Thai formulators as export-oriented personal care manufacturing hubs. National cosmetic regulator requirements align with emerging regional harmonization frameworks. Bangkok-centered cosmetic clusters scale diethanolamide procurement leveraging regional palm kernel oil derivatives.
Indonesia
Domestic oleochemical producers backward-integrate into amide production, capturing margin pools previously exported to Malaysian refiners. SAMR-administered GB standards for surfactant purity create parallel compliance obligations for China-bound shipments. Surabaya manufacturing zones concentrate downstream surfactant formulation capacity.
China
Detergent-grade volume concentrates in Yangtze River Delta home care manufacturing clusters. GB standards divergence from REACH specifications forces dual certification costs for multinational suppliers. Shanghai and Zhejiang province surfactant producers serve both domestic cosmetic brands and export markets.
Diethanolamide Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification-grade tiers, with cosmetic-grade purity thresholds separating price-insensitive personal care channels from industrial-grade volume throughput. The vendor base stratifies between integrated oleochemical majors, specialty surfactant houses, and regional detergent-grade suppliers. Three archetypes dominate: backward-integrated feedstock controllers, multi-product surfactant platform operators, and certification-focused cosmetic-grade specialists. Capacity expansion and supply chain traceability investments constitute the dominant competitive moves.
Among integrated German chemical majors, BASF SE and Merck KGaA exemplify archetypes spanning cosmetic-grade certification depth and pharmaceutical-grade documentation intensity. Dow anchors North American positioning through Gulf Coast ethoxylation infrastructure. LG Chem represents scale-driven Asian platform operations with multi-product surfactant facility integration.
| Leading Market Players |
|---|
| SABIC |
| Air Liquide |
| Dow |
| Formosa Plastics Corporation |
| Exxon Mobil Corporation |
| BASF SE |
| Merck KGaA |
| LG Chem |
| INEOS |
| Others |
Cost & Logistics Intelligence
Crude palm kernel oil futures on Bursa Malaysia Derivatives cascade through fatty acid amide production into three distinct pricing tiers, with cosmetic-grade premiums widening against industrial-grade benchmarks as REACH nitrosamine compliance costs accumulate.
Pricing Analysis
Three-tier pricing structure across cosmetic, detergent, and industrial grades separates value pools by certification intensity. Cosmetic-grade diethanolamide commands substantial premiums driven by LC-MS/MS nitrosamine documentation and RSPO-Mass Balance feedstock verification. Cost compression in detergent-grade material is intensifying as Indonesian oleochemical producers backward-integrate into captive amide output. Cleaning product suppliers exhibit the highest price sensitivity, while German personal care manufacturers absorb premium positioning with minimal volume elasticity.
Supply Chain Analysis
Reverse-logistics flows for surfactant packaging and container reuse remain underdeveloped, with most bulk diethanolamide moving in single-use intermediate bulk containers from production sites to formulators. Supply concentrates in Indonesia, Malaysia, and Germany as the primary manufacturing nodes. Production draws from palm kernel oil, coconut fatty acid distillates, and diethanolamine feedstocks. Single-source vulnerability runs through Indonesian oleochemical complexes exposed to La Niña harvest disruptions. Distribution runs through regional distributor networks for cosmetic-grade material and direct bulk shipment for industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Diethanolamide procurement functions as a geographic-arbitrage play between Southeast Asian feedstock cost advantages and European regulatory premium capture, with REACH compliance costs in Germany diverging sharply from SAMR-administered GB standard obligations in China.
For Market Incumbents: Anticipate enzymatic amidation technology disrupting thermal process economics by compressing capital requirements for cosmetic-grade entry. Defend position by deepening RSPO-Segregated certification coverage across European personal care channels and anchoring Gulf Coast ethoxylation capacity against EPA TSCA import screening advantages. For New Entrants and Emerging Players: Specialty chemical marketplaces offer the most penetrable route for mid-volume detergent-grade orders, bypassing entrenched distributor relationships. Target Indonesian domestic formulators with backward-integrated oleochemical supply and leverage direct-to-compounder digital platforms to capture price-transparent procurement shifts in ASEAN home care manufacturing. For Investors and Strategic Acquirers: Consolidation pressure builds where nitrosamine-free production line segregation requires capital-intensive LC-MS/MS capabilities that smaller cosmetic-grade specialists cannot justify. Long-term viability favors acquisition targets with integrated palm kernel oil derivatives access and established REACH dossier bandwidth. Monitor ECHA guidance document updates for nitrosamine analytical methodology as the signal for regulatory-driven supplier displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oleochemical Feedstocks | Captures margin pools previously exported to Malaysian refiners while securing supply continuity. |
| Enzymatic Amidation Process Adoption | Reduces energy intensity and enables carbon footprint claims satisfying CSRD reporting obligations. |
| RSPO-Mass Balance Certification Investment | Unlocks premium positioning in German and French retail private label detergent specifications. |
| Nitrosamine-Free Production Line Segregation | Meets ECHA guidance protocols exceeding prior industry analytical standards for rinse-off cosmetics. |
| Direct-to-Compounder Digital Platform Launch | Disintermediates traditional distributor networks for standardized mid-volume detergent-grade procurement. |
Research Approach
Coverage spans Southeast Asian oleochemical hubs, European personal care manufacturing corridors, and North American industrial surfactant markets, with primary inputs from each. The analysis combines structured interviews with plant managers at integrated oleochemical facilities, procurement leads at downstream cosmetic and home care formulators, distribution channel partners, and technical R&D directors specializing in surfactant amidation processes. Secondary validation draws from customs and trade flow databases, Cefic surfactant industry reports, SEC 10-K filings of disclosed chemical majors, and ECHA REACH registration dossiers. Bottom-up capacity and consumption estimates triangulate against top-down market size calculations derived from trade value flows and regional production statistics.
Rate-of-change decomposition separates volume growth from price evolution across the projection horizon. The analytical framework models segmentation dimensions including grade tier (cosmetic, detergent, industrial), end-use industry (personal care, home care, metalworking fluids), and regional production hub concentration. CAGRs derive from trend extrapolation of oleochemical feedstock availability, regulatory compliance cost trajectories, and substitution dynamics with alkyl polyglucoside alternatives. Industry-specific forecast inputs include palm kernel oil harvest forecasts and REACH Annex XVII restriction implementation timelines.
La Niña recurrence, REACH dossier update deadlines, and alkyl polyglucoside cost volatility are the dominant revision risks to modeled outputs. Forecasts reflect assumptions regarding regulatory enforcement intensity and feedstock harvest stability. Practitioners should monitor Bursa Malaysia palm kernel oil futures, ECHA substance evaluation conclusions, and Thai cosmetic export licensing trends for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Butyl Acetate (BAC) Market
Solvents
Hydrosol Market
Solvents
4-Dichlorobenzyl Alcohol (DCBA) Market
Solvents
Ethyl Pyruvate Market
Solvents
Trichloroacetyl Chloride Market
Solvents
Methyl Undecylenate Market
Solvents
Ethoxydiglycol Market
Solvents
Piperylene Market
Solvents
Global Ink Solvents Market
Solvents
5-Isopropyl-M-Xylene Market
Solvents
Dimethyl Ether (DME) Market
Solvents
North America Toluene Market
Solvents
Global Aliphatic Hydrocarbon Solvents Market
Solvents
Aliphatic Solvents Market
Solvents
Organic Solvents Market
Solvents
Phenol Derivatives Market