
 North America Accounts Payable Automation Market | 2026-2036
North America Accounts Payable Automation Market Size, Share, and Industry Trends Forecast 2026-2036
North America Accounts Payable Automation Market Analytics
Market Context
Paper-based invoice processing is decoupling from enterprise finance operations as digital alternatives deliver measurable cost reductions. Bottomline Technologies leverages its banking connectivity infrastructure to anchor payment network dominance across United States commercial corridors. SAP Ariba sustains competitive positioning through deep ERP integration and procurement-to-pay workflow unification.
Technical Definition and Segment Structure
Accounts payable automation encompasses software platforms that capture, validate, route, and reconcile supplier invoices through configurable workflow engines, typically integrating optical character recognition with enterprise resource planning systems to eliminate manual data entry and accelerate payment cycles. Cloud-based solutions lead deployment preferences as manufacturing sector buyers prioritize scalable infrastructure with minimal capital commitment. Optical character recognition technology occupies the fastest-expanding technology tier as healthcare providers demand accurate extraction from diverse invoice formats.
Regulatory Environment and Outlook
The Sarbanes-Oxley Act shapes internal control requirements that drive United States enterprises toward auditable automated workflows, while Canadian federal e-payments directives and Mexico's CFDI electronic invoicing standards create complementary compliance pressures across the tri-national landscape. Stakeholders must monitor evolving state-level e-invoicing mandates and cross-border tax reporting harmonization to anticipate platform upgrade cycles and geographic expansion timing.
Market Dynamics
State-level e-invoicing mandates across the United States are compressing procurement timelines and forcing mid-market enterprises to abandon paper-based workflows before full federal standardization arrives. Healthcare providers and manufacturers face the steepest compliance cliffs.
Growth Catalysts
- Sarbanes-Oxley Act:United States public companies must maintain auditable internal controls over financial reporting, driving systematic replacement of manual invoice approval chains with timestamped digital workflows.
- OCR-ERP convergence:Healthcare providers demand extraction accuracy from diverse invoice formats, accelerating platform upgrades that embed optical character recognition directly within enterprise resource planning interfaces.
- Texas and California mid-market density:Cloud-native deployment preferences concentrate in these states, creating regional demand clusters that vendors target with localized implementation support.
Market Restraints
- Legacy system integration costs:Enterprises running decade-old enterprise resource planning installations face prohibitive customization expenses to connect modern automation platforms.
- Supplier onboarding friction:Small vendors in the United States lack technical capacity to receive electronic invoices, creating adoption bottlenecks that slow network effects.
- Data residency requirements:Canadian federal privacy frameworks and provincial health data laws restrict cross-border cloud processing, complicating platform architecture for North American deployments.
Strategic Opportunities
- Mexico CFDI compliance expansion:Mexican electronic invoicing standards create adjacent demand for cross-border automation among United States enterprises with maquiladora supply chains.
- Artificial intelligence-OCR fusion:Machine learning models trained on invoice variance patterns enable exception handling without human intervention, opening premium pricing tiers.
- Mid-market channel innovation:Accounting software marketplaces and reseller networks replace direct enterprise sales, lowering customer acquisition costs in underserved segments.
Industry Challenges
- Accounts payable specialist scarcity:United States labor markets lack sufficient personnel who understand both invoice exception resolution and automated platform configuration.
- Multi-entity consolidation complexity:Enterprises operating across United States state lines face divergent sales tax calculation rules that automation platforms must reconcile in real time.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Accounts Payable Automation Market |
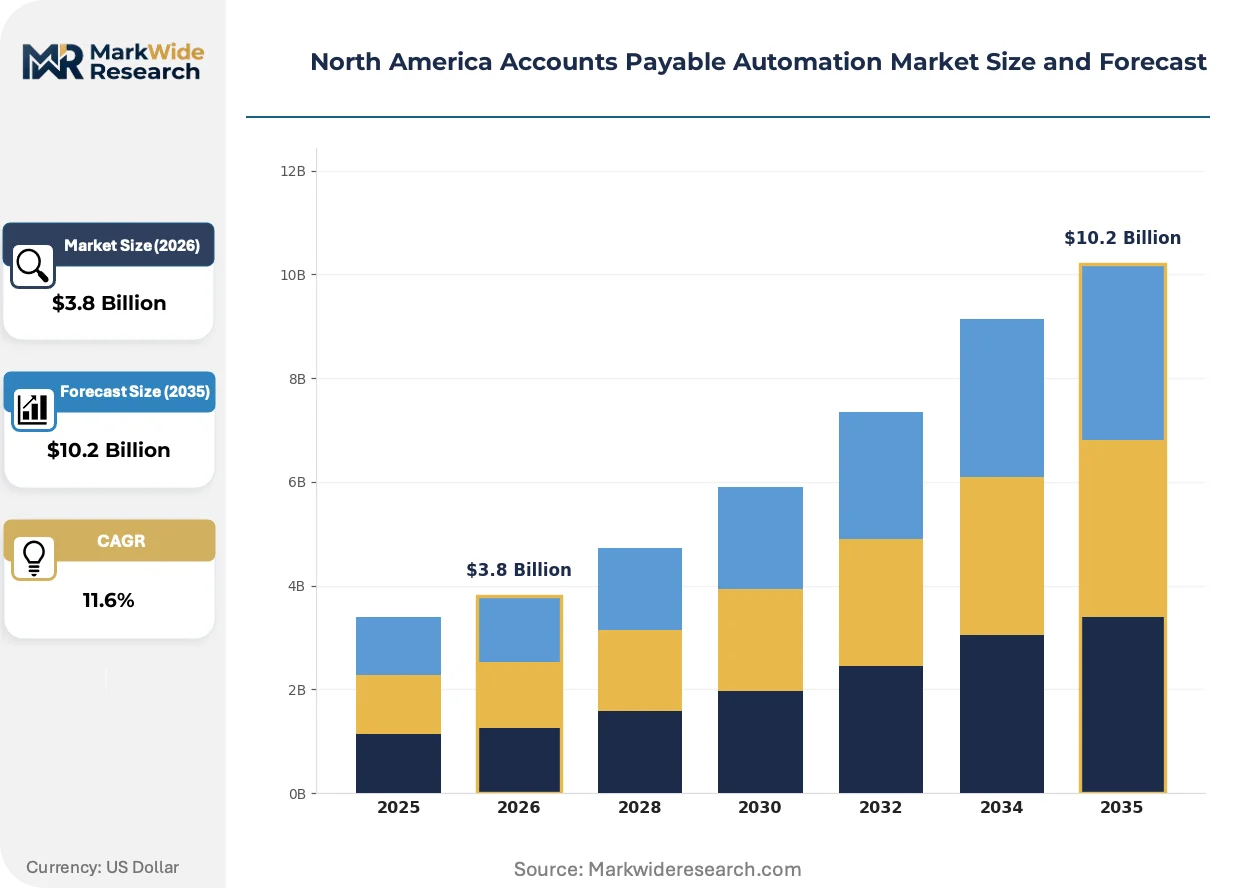
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.2 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-based Solutions, On-premise Solutions, Hybrid Solutions, Mobile Applications End User: Manufacturing Sector, Retail Businesses, Healthcare Providers, Educational Institutions Deployment: Public Cloud, Private Cloud, On-premise, Managed Services Technology: Artificial Intelligence, Machine Learning, Optical Character Recognition, Workflow Automation |
| Companies Covered | Zycus, Bottomline Technologies, SAP Ariba, Stampli, FreshBooks, Coupa Software, Sage Software, FIS, Tipalti, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Accounts Payable Automation Market Evolving Landscape
Invoice processing infrastructure is fragmenting into composable components that buyers assemble rather than purchasing monolithic suites. Vendors respond with API-first architectures and pre-built connectors.
Optical character recognition technology is modularizing into discrete microservices that enterprises embed within existing workflow tools rather than replacing entire procurement stacks. Healthcare providers in the United States adopt these components fastest, driven by accuracy requirements for insurance documentation. This decomposition is compressing vendor switching costs and enabling best-of-breed procurement strategies.
The Sarbanes-Oxley Act's audit trail requirements are tightening documentation standards for automated approval workflows across United States public companies. Financial controllers now demand immutable logs that timestamp every invoice touchpoint. Mid-market enterprises in California and Texas are upgrading platforms specifically to satisfy external auditor scrutiny.
Subscription pricing models are displacing perpetual licenses among North American buyers who prefer operational expenditure classification. Manufacturing sector procurement teams negotiate usage-based contracts that scale with invoice volume rather than user seats. This shift is most visible in United States cloud-native deployments where finance leaders prioritize cash flow flexibility over long-term asset ownership.
North America Accounts Payable Automation Market Segmentation
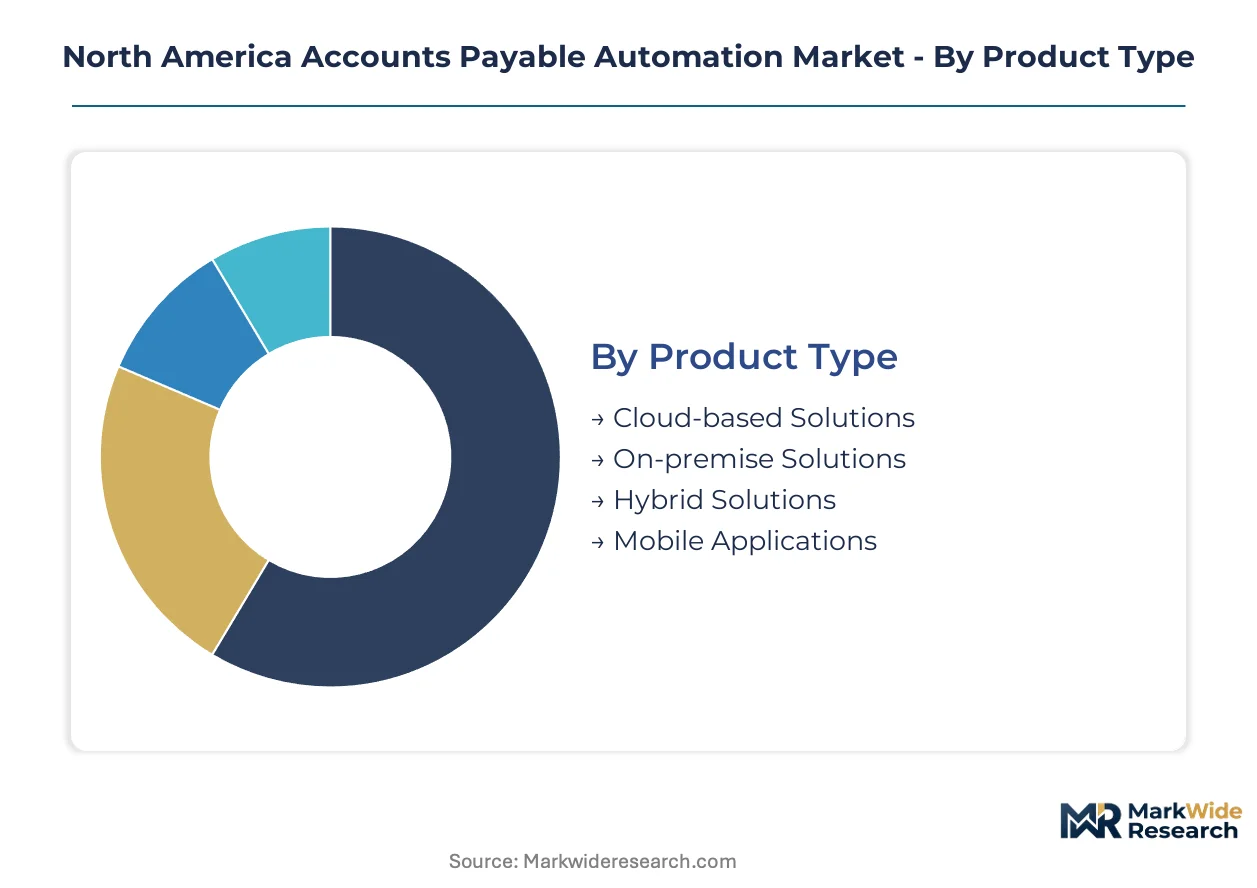
Accounts payable automation vendors configure platform architectures around buyer infrastructure constraints and compliance requirements. Segmentation reveals where standardization yields economies of scale versus where customization commands premium pricing.
Product Type:
Standardization dominates the lower tiers while hybrid architectures absorb the most customization engineering hours.
- Cloud-based Solutions:Multi-tenant architectures with API-first design enable rapid deployment across United States mid-market enterprises. Texas and California buyers drive demand for subscription models that convert capital expenditure to operational expenditure.
- On-premise Solutions:Single-tenant installations within enterprise data centers serve Canadian healthcare providers with strict data residency requirements under federal privacy frameworks. These deployments require dedicated implementation teams and carry higher total cost of ownership.
- Hybrid Solutions:Split processing between cloud and on-premise environments accommodates Mexican maquiladora operations with cross-border invoice routing needs.
- Mobile Applications:Native iOS and Android interfaces for approval workflows target field-based procurement managers in United States manufacturing.
Leading the category by volume: Cloud-based Solutions. Growing fastest: Hybrid Solutions.
End User:
Application intensity varies sharply by sector regulatory burden and invoice complexity.
- Manufacturing Sector:High-volume invoice environments with complex purchase order matching requirements. United States automotive suppliers deploy automation to reconcile supplier receipts against production schedules.
- Healthcare Providers:Insurance documentation and patient billing integration demands specialized extraction accuracy. HIPAA compliance mandates audit trails that timestamp every invoice touchpoint.
- Retail Businesses:Seasonal volume spikes require elastic processing capacity that scales with merchandise receipt cycles.
- Educational Institutions:Grant-funded procurement with restricted-use accounting codes creates exception-heavy workflows requiring human-in-the-loop design.
Highest deployment density: Manufacturing Sector. Steepest compliance-driven replacement cycle: Healthcare Providers.
Deployment:
Infrastructure control preferences cluster by enterprise size and IT staffing levels.
- Public Cloud:Shared infrastructure with automatic patching and scaling serves United States mid-market buyers lacking dedicated IT operations. California enterprises favor this model for rapid disaster recovery.
- Private Cloud:Dedicated virtual environments within hyperscaler regions satisfy Canadian provincial health data laws restricting cross-border processing. Single-tenant isolation commands 40-60% pricing premiums over public alternatives.
- On-premise:Physical server installations persist among Mexican enterprises with unreliable connectivity to United States cloud regions.
- Managed Services:Outsourced platform administration with SLA-guaranteed uptime targets appeals to educational institutions with limited technical staff.
Dominant deployment mode: Public Cloud. Fastest-expanding alternative: Managed Services.
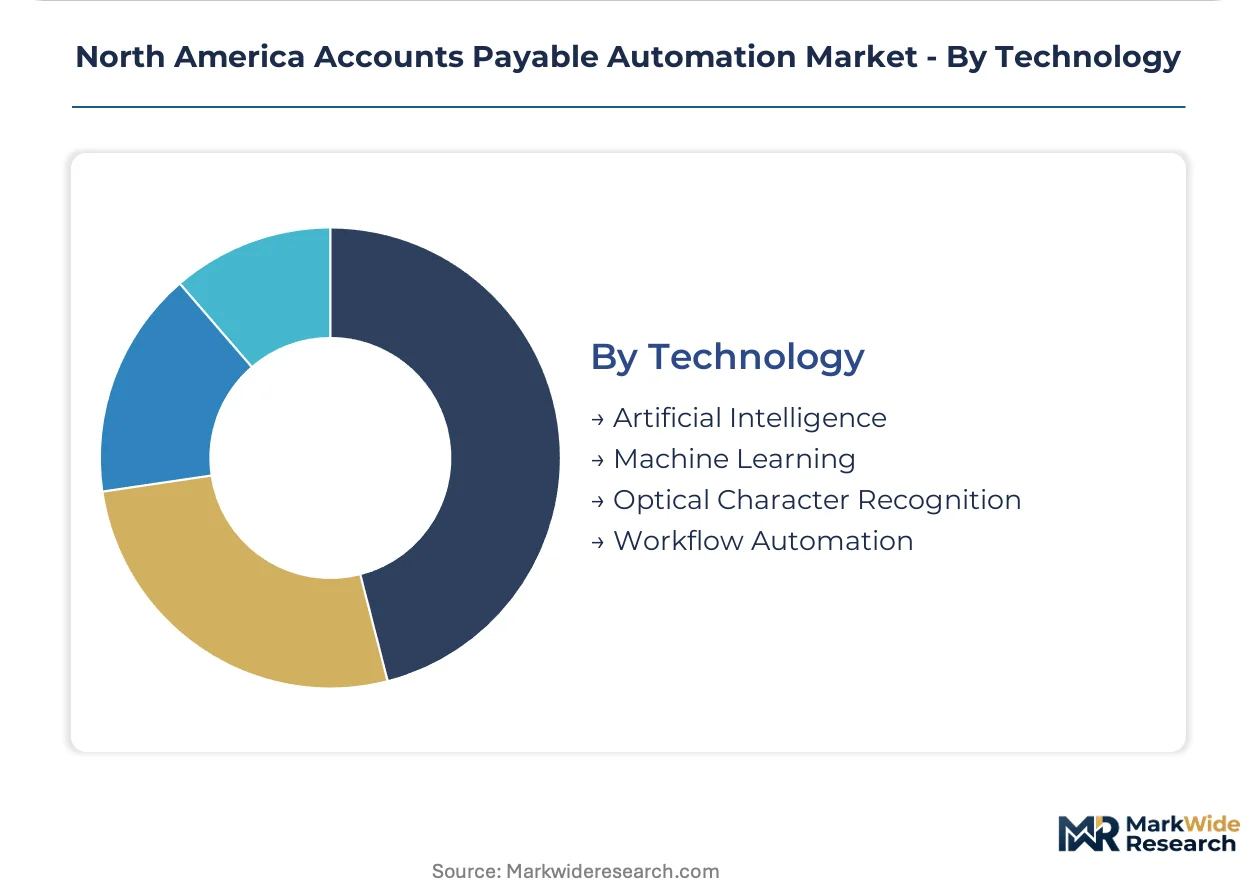
Technology:
Capability layering determines which automation tasks require human intervention.
- Optical Character Recognition:Document scanning and data extraction engines process scanned invoices and PDF attachments. Healthcare providers in the United States demand sub-1% error rates for insurance claim documentation.
- Artificial Intelligence:Neural network models trained on invoice variance patterns enable autonomous exception handling without manual review queues.
- Machine Learning:Pattern recognition algorithms improve extraction accuracy over time based on user correction feedback.
- Workflow Automation:Configurable routing engines enforce approval hierarchies and Sarbanes-Oxley Act documentation requirements.
Widest installed base: Optical Character Recognition. Steepest capability advancement curve: Artificial Intelligence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mid-market enterprises in Texas and California concentrate North American demand for cloud-native accounts payable automation, driven by state-level e-invoicing mandates and Sarbanes-Oxley Act compliance pressures.
United States
Healthcare providers and manufacturers dominate procurement activity, with HIPAA audit trail requirements and SEC disclosure rules under Sarbanes-Oxley compelling timestamped digital workflows. Dallas-Fort Worth and Houston enterprise clusters drive cloud deployment adoption among mid-market energy and logistics firms.
California
Technology sector buyers prioritize API-first architectures and subscription pricing models that convert capital expenditure to operational expenditure. Los Angeles and San Francisco Bay Area healthcare networks deploy automated invoice processing to reconcile insurance documentation with patient billing systems.
Texas
Manufacturing suppliers and oilfield services firms demand scalable infrastructure with minimal capital commitment, aligning with cloud-native deployment preferences. Austin and Dallas mid-market enterprises accelerate replacement of paper-based approval chains ahead of anticipated federal e-invoicing standardization.
Canada
Federal privacy frameworks and provincial health data laws restrict cross-border cloud processing, creating demand for private cloud and on-premise installations. Toronto and Vancouver healthcare providers mandate single-tenant isolation for patient financial data, commanding pricing premiums over public alternatives.
Mexico
CFDI electronic invoicing standards create compliance requirements for maquiladora operations with cross-border supply chains. Mexico City and Nuevo León manufacturing clusters adopt hybrid processing architectures to route invoices between cloud and on-premise environments.
North America Accounts Payable Automation Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors integrate optical character recognition engines with enterprise resource planning systems to capture procurement-to-pay workflows. The market structure consolidates around three tiers: banking connectivity specialists, ERP-integrated suite providers, and cloud-native challengers with API-first architectures. Vertical integration into payment networks and artificial intelligence-OCR fusion represent the two most active competitive vectors reshaping platform capabilities.
Within the banking infrastructure tier, Bottomline Technologies anchors payment network dominance through commercial corridor connectivity. SAP Ariba exemplifies ERP-integrated suite positioning with procurement-to-pay workflow unification. Among cloud-native challengers, Stampli occupies a position emphasizing rapid deployment for mid-market enterprises in Texas and California.
| Leading Market Players |
|---|
| Zycus |
| Bottomline Technologies |
| SAP Ariba |
| Stampli |
| FreshBooks |
| Coupa Software |
| Sage Software |
| FIS |
| Tipalti |
| Others |
Value Network & Pricing Analysis
Mid-market enterprises in Texas and California concentrate procurement volume for cloud-native accounts payable automation, compressing vendor margins through standardized subscription benchmarking while rewarding API-first architectures with faster sales cycles.
Pricing Analysis
Volume concentrates in subscription tiers while margins accrue to AI-augmented exception-handling modules. Three-tier pricing structure across premium, standard, and economy levels separates HIPAA-compliant healthcare deployments from basic mid-market offerings. Cost compression in the standard tier is intensifying because hyperscaler infrastructure commoditizes core workflow engines. Healthcare providers exhibit least price sensitivity due to audit trail mandates, while educational institutions demand usage-based contracts that minimize fixed commitments.
Supply Chain Analysis
Dual-sourcing requirements for optical character recognition engines compel platform vendors to qualify multiple extraction providers, preventing single-source dependency on any one computer vision supplier. Software development concentrates in the United States, India, and Eastern Europe, with implementation services drawing from domestic consulting networks. Cloud compute and API middleware form critical input dependencies. Single-source vulnerability in banking connectivity partnerships poses structural risk. Distribution runs through accounting software marketplaces and reseller channels that replace direct enterprise sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from Sarbanes-Oxley compliance costs will force subscale vendors without ERP integration depth to exit or sell, concentrating market share among banking-connected incumbents and AI-native challengers.
For Market Incumbents: To counter API-first challengers eroding mid-market share, anchor payment network dominance through deeper banking corridor integration and acquire OCR specialists to fuse extraction accuracy with workflow automation. Channel control through accounting software marketplaces replaces high-cost direct sales.
For New Entrants and Emerging Players: Begin with managed services deployment for educational institutions and regional healthcare networks in Canada, where data residency requirements create defensible moats against US-based competitors. Partner with existing ERP resellers rather than building direct sales infrastructure.
For Investors and Strategic Acquirers: Distressed-cycle entries favor AI-OCR fusion specialists with HIPAA-compliant architectures in the United States, where compliance-driven replacement cycles sustain premium pricing. Long-term viability hinges on cross-border tax reporting harmonization enabling geographic expansion. Watch state-level e-invoicing mandate acceleration as the inflection signal for platform upgrade demand.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-OCR Fusion Development | Machine learning models trained on invoice variance patterns enable autonomous exception handling without manual review queues. |
| Banking Connectivity Expansion | Deeper integration with commercial payment networks anchors platform stickiness through transaction revenue sharing. |
| HIPAA Compliance Certification | Healthcare provider procurement mandates immutable audit trails that timestamp every invoice touchpoint. |
| Channel Partner Recruitment | Accounting software marketplaces and reseller networks lower customer acquisition costs in underserved mid-market segments. |
| Mexico CFDI Integration | Cross-border automation for maquiladora supply chains captures adjacent demand from US enterprises with Mexican operations. |
Research Methodology
Independent corroboration across CFO interviews, IT procurement officers, and accounts payable specialists underwrites the qualitative findings, with secondary validation drawing from SEC filings, healthcare GPO contracts, and state e-invoicing mandate databases. Bottom-up sizing of cloud deployment volumes triangulates against top-down expenditure estimates from mid-market enterprise surveys.
Comparable historical periods anchored the forecast window to post-Sarbanes-Oxley compliance investment cycles and prior state mandate implementation waves. The analytical framework models deployment model, organization size, vertical regulatory burden, and integration complexity across the projection horizon. CAGR derivation incorporates invoice volume elasticity, cloud infrastructure cost curves, and OCR accuracy improvement trajectories.
State mandate acceleration delays, banking partnership consolidation, and AI extraction accuracy breakthroughs are the dominant revision risks. Forecasts reflect documented assumptions about compliance timeline adherence and mid-market cloud migration velocity. Deviation in state-level e-invoicing enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Germany Real Time Payments Market
Payments
Hong Kong Credit Cards Market
Payments
Canada Buy Now Pay Later Market
Payments
Hong Kong Payments Market
Payments
US Gift Card and Incentive Card Market
Payments
Japan Virtual Cards Market
Payments
Payment Processing Solutions Market
Payments
Asia Pacific Buy Now Pay Later Service Market
Payments
Italy Payments Market
Payments
EMV Card Market
Payments
Electronic Payment Processing Software Market
Payments
Cross-Border Payment Platform Market
Payments
Epayment System Market
Payments
Cryptocurrency Payment Apps Market
Payments
UAE POS Terminal Market
Payments
Global Mobile Point of Sale (Mpos) Terminals Market