
 EMV Card Market | 2026-2036
EMV Card Market Size, Share, and Industry Trends Forecast 2026-2036
EMV Card Market Intelligence
Intensified competition among semiconductor suppliers in Asia is repositioning the cost structure and availability of secure microcontroller units for card manufacturing. This dynamic benefits large-scale card producers with global supply chains. Gemalto leverages its extensive patent portfolio in secure element technology to maintain a strong market presence. Giesecke & Devrient specializes in integrated security solutions for financial institutions, while IDEMIA competes through its focus on augmented identity and digital security services.
An EMV card is a payment card that stores its data on an integrated circuit chip rather than only on a magnetic stripe. This chip, a secure microcontroller, performs cryptographic processing to authenticate transactions according to standards set by EMVCo. Debit card issuance now outpaces credit cards in many developing nations, propelled by financial inclusion programs. Within authentication methods, contactless functionality has become a standard offering, displacing older chip & PIN or chip & signature as the primary transaction mode for everyday purchases.
Payment Card Industry Data Security Standard (PCI DSS) compliance governs the secure handling of cardholder information across the ecosystem. Concurrently, data privacy regulations such as Europe's GDPR and Brazil's LGPD impose strict requirements on how card issuers and processors manage personal data. The next phase of product evolution will center on integrating biometric authentication features and providing support for emerging central bank digital currency (CBDC) frameworks.
Market Dynamics
The liability shift mandated by major payment networks remains the central structural force compelling the migration to EMV technology. This policy transfers fraud liability to the entity, whether merchant or issuer, with the less secure technology, creating a powerful economic incentive for universal adoption.
Growth Catalysts
- Financial Inclusion Programs:Government and central bank initiatives in nations like India and Brazil to provide banking services to unbanked populations directly drive mass issuance of debit EMV cards as a primary account access tool.
- Contactless Technology Adoption:Consumer and merchant demand for faster, more convenient transactions in high-volume environments such as public transit and quick-service retail has made contactless functionality a standard feature.
- Payment Network Mandates:Persistent fraud losses associated with magnetic stripe cards prompted payment networks to establish clear timelines and liability rules, effectively forcing a system-wide upgrade to the more secure EMV standard.
Market Restraints
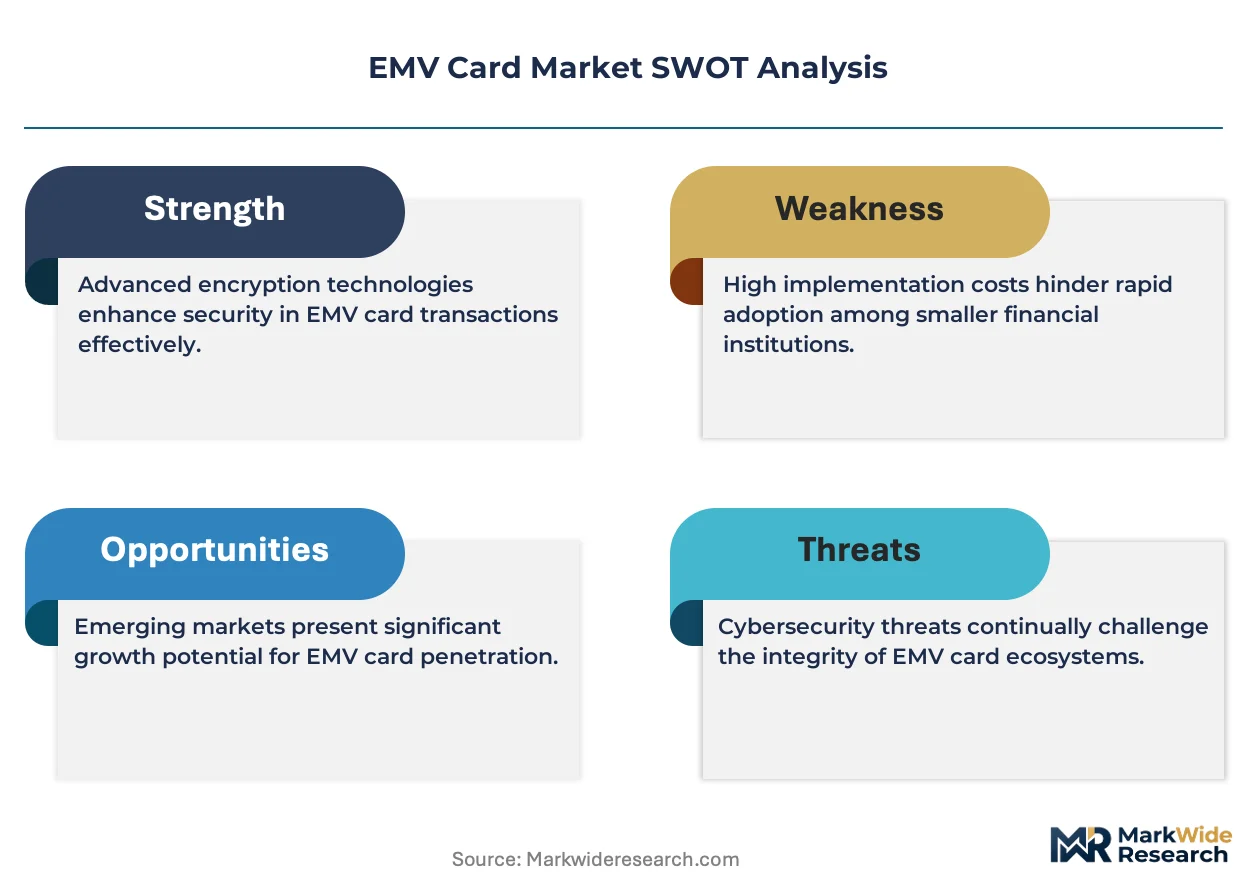
- Higher Unit Cost:Secure microcontrollers and the associated chip-embedding processes make EMV cards significantly more expensive to produce per unit than traditional magnetic stripe cards, impacting issuer margins.
- POS Terminal Certification:The cost and complexity for merchants to upgrade or replace point-of-sale terminals and get them certified for EMV compliance can be a barrier, especially for smaller businesses.
- Mobile Payment Substitution:The growth of NFC-enabled smartphone wallets provides an alternative to physical cards for contactless payments, potentially reducing card usage frequency for some consumer segments.
Strategic Opportunities
- Biometric Integration:Incorporating fingerprint sensors directly onto the card offers a next-generation security feature that enhances user verification without requiring PINs, creating a premium product tier.
- CBDC Enablement:Developing secure hardware wallets in a card form factor presents an opportunity to provide an interface for offline transactions and access to emerging central bank digital currencies.
- Transit System Upgrades:As major metropolitan transit authorities worldwide move to open-loop payment systems, there is a significant opportunity to supply co-branded contactless EMV cards for fare payment.
Industry Challenges
- Regulatory Compliance Burden:Adhering to a complex web of data privacy laws, such as Europe's GDPR and Brazil's LGPD, requires significant investment in secure data handling and consent management infrastructure.
- Semiconductor Supply Chain:Heavy reliance on a concentrated group of Asian semiconductor foundries for secure microcontrollers exposes the entire card manufacturing ecosystem to geopolitical risks and supply disruptions.
- Legacy System Interoperability:Ensuring new card features, like biometric or dynamic CVCs, work seamlessly with the vast and diverse global infrastructure of existing payment terminals and backend systems is a major technical hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EMV Card Market |
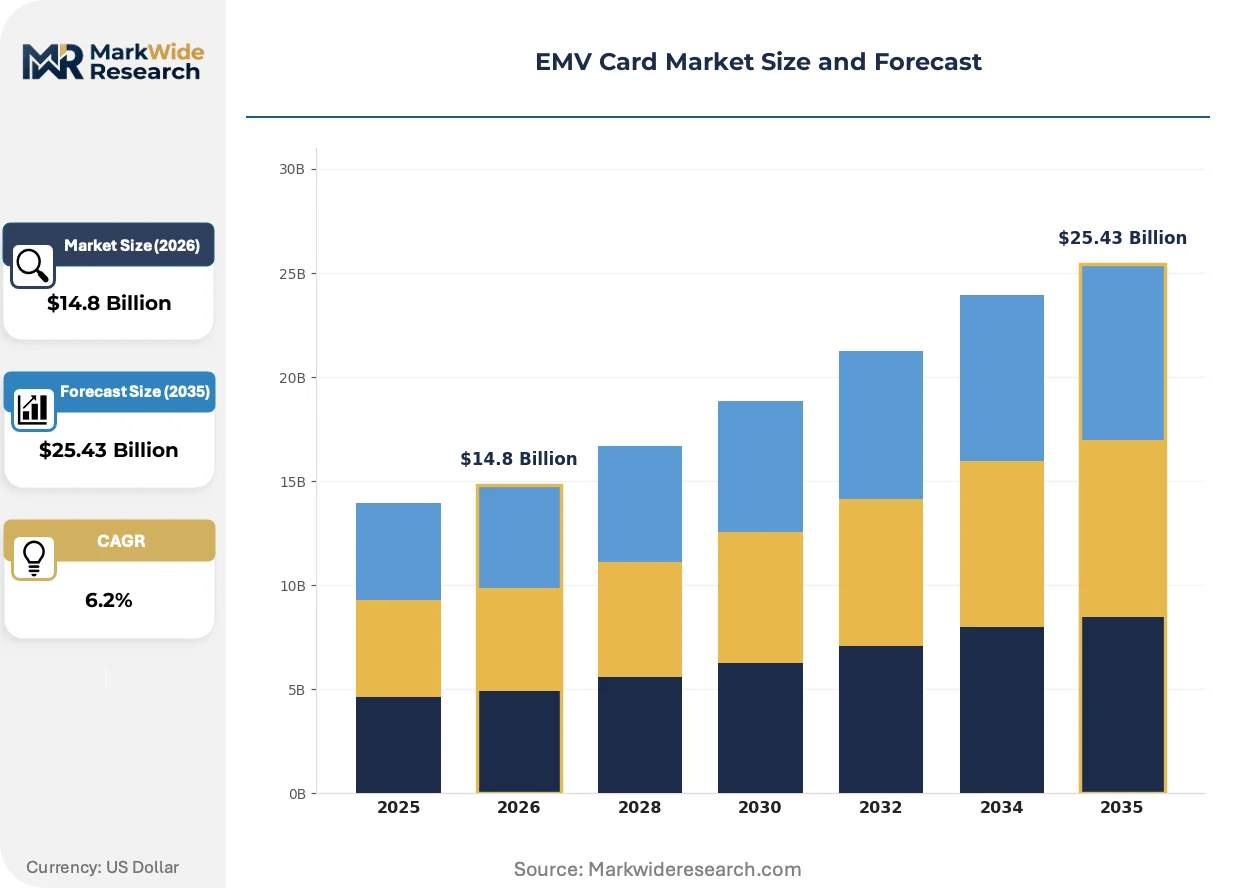
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Card Type: Credit Card, Debit Card, Prepaid Card, Hybrid Card Authentication Method: Chip & PIN, Chip & Signature, Contactless, Magnetic Stripe End User: Banks, Retailers, Payment Processors, Government Agencies Distribution Channel: Online Retail, Physical Retail, Financial Institutions, Mobile Apps |
| Companies Covered | Perfect Plastic Printing, CPI Card, IDEMIA, Goldpac, Tianyu, Gemalto, ABCorp, Hengbao, Giesecke & Devrient, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EMV Card Market Strategic Shifts & Innovations
The physical payment card is evolving beyond a simple transaction instrument into a multipurpose secure token for identity and access. This transformation is driven by the convergence of authentication technologies and the need for a tangible link to an increasingly digital financial ecosystem.
Biometric-on-card technology integrates fingerprint sensors directly onto the card itself, allowing for on-device user verification. High-value consumer segments and corporate card programs are the primary early adopters, seeking to eliminate PINs and enhance security against fraud. This innovation is modularizing the authentication process, moving it from the network or terminal directly onto the secure element of the card.
Data privacy frameworks, most notably Europe's GDPR, are setting a global standard for how personal information is managed. The regulation imposes strict requirements on card issuers and processors regarding data consent, storage, and portability, forcing a complete re-architecture of customer data platforms. Financial institutions are most affected, investing in privacy-enhancing technologies to maintain compliance and avoid substantial fines.
A notable behavioral shift involves the expectation for payment cards to also function as digital identity credentials. This is displacing single-function cards in government and corporate environments, where consolidating physical building access, logical network access, and payment capabilities onto one secure EMV card simplifies management. This convergence is particularly evident in European markets exploring synergies between national ID schemes and payment infrastructures.
EMV Card Market Segmentation

The EMV card market segments across card type, authentication method, end-user, and distribution channel, reflecting diverse operational needs and transaction environments. Understanding these distinctions is crucial for identifying areas of concentrated demand and evolving security standards. Each segment exhibits unique adoption drivers and technological requirements within the payment ecosystem.
Card Type:
The EMV card market differentiates based on the underlying financial product and its associated transaction characteristics.
- Credit Card:Credit cards offer revolving credit lines, enabling deferred payments and often incorporating loyalty programs. High-value consumer transactions in developed economies like the United States drive demand, supported by robust issuer infrastructure.
- Debit Card:Debit cards link directly to a cardholder's bank account, facilitating immediate fund deduction for purchases. Financial inclusion programs in nations such as India and Brazil significantly boost debit card issuance, providing primary account access.
- Prepaid Card:Prepaid cards load funds in advance, serving as a budgeting tool or for gift programs, particularly in retail environments.
- Hybrid Card:Hybrid cards combine features of credit and debit, offering flexible payment options for specific corporate or consumer needs.
Mature deployment sits with Credit Card products. Newer deployment is concentrated in Debit Card issuance.
Authentication Method:
Transaction security and user convenience define the various authentication methods employed by EMV cards.
- Contactless:Contactless authentication uses Near Field Communication (NFC) for tap-and-go transactions, enhancing speed at the point of sale. Public transit systems in cities like London and New York increasingly adopt contactless payments, driven by efficiency requirements.
- Chip & PIN:Chip & PIN requires a personal identification number entered by the cardholder at the terminal to verify transactions. European markets historically relied on Chip & PIN for secure transactions, establishing a strong base in financial services.
- Chip & Signature:Chip & Signature authenticates transactions with a cardholder's handwritten signature, a method less common for everyday purchases.
- Magnetic Stripe:Magnetic Stripe technology stores data on a magnetic band, serving as a fallback option for older terminals or specific card types.
Contactless functionality exhibits the steepest expansion trajectory. Magnetic Stripe authentication experiences declining adoption.
End User:
The adoption and deployment of EMV cards vary significantly across different institutional end-users based on their operational requirements.
- Banks:Banks are primary issuers of EMV cards, managing cardholder accounts, fraud prevention, and transaction processing. Global financial institutions drive EMV card issuance as part of their core retail banking services, ensuring compliance with payment network mandates.
- Retailers:Retailers implement EMV-compliant point-of-sale systems to accept secure card payments and mitigate fraud liability. Large retail chains across Europe and North America prioritize EMV adoption to enhance security and streamline customer checkout experiences.
- Payment Processors:Payment processors facilitate secure transaction routing and settlement between merchants, issuers, and payment networks.
- Government Agencies:Government agencies issue EMV cards for social benefit programs, national identity schemes, or employee expense management.
Banks represent the largest volume of EMV card issuance. Government Agencies are expanding their EMV card programs for various public services.
Distribution Channel:
Accessibility and convenience dictate the primary distribution channels for EMV cards to reach end-users effectively.
- Financial Institutions:Financial institutions directly issue EMV cards to their customers through branch networks, online applications, and mail. Traditional banks and credit unions globally remain the dominant channel for new EMV card issuance, leveraging existing customer relationships.
- Online Retail:Online retail platforms facilitate the ordering and delivery of EMV cards, often linked to digital banking or fintech solutions. Fintech companies in markets like Brazil leverage online retail channels to distribute EMV debit cards for digital-first banking solutions.
- Physical Retail:Physical retail outlets, such as supermarkets or electronics stores, offer co-branded or gift EMV cards for immediate purchase.
- Mobile Apps:Mobile apps enable virtual EMV card issuance and management, particularly for digital wallets and instant payment solutions.
Financial Institutions maintain a foundational role in EMV card distribution. Online Retail channels are gaining share fastest for new card activations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China anchors the global production of secure microcontroller units, a critical component for EMV card manufacturing. This concentration influences global supply chains and cost structures for card producers. India and Brazil represent significant demand centers for EMV card issuance.
China
China's rapid digital economy expansion drives significant demand for EMV card issuance, particularly for domestic payment schemes. The People's Bank of China (PBOC) supports EMV integration into its emerging central bank digital currency (CBDC) frameworks. Shenzhen, a major electronics manufacturing hub, concentrates card production and secure element fabrication.
India
India's financial inclusion programs significantly boost debit EMV card issuance, providing essential banking access to unbanked populations. The Reserve Bank of India (RBI) actively promotes secure digital payments and EMV adoption. Bangalore, a prominent fintech innovation center, drives new payment solution development.
Brazil
Brazil experiences strong demand for EMV cards due to widespread financial inclusion efforts and a large consumer base. The country's LGPD data privacy regulation imposes strict requirements on card issuers and processors. São Paulo, a key financial hub, hosts major banking and payment processing operations.
Germany
Germany maintains high EMV card adoption, especially for Chip & PIN transactions, reflecting a preference for robust security protocols. European GDPR compliance dictates stringent data handling practices for financial institutions operating within the nation. Frankfurt, a central European financial services city, anchors significant card issuance and processing activities.
United States
The United States market continues its EMV migration, driven by liability shift mandates from major payment networks. The Federal Reserve encourages modern payment system upgrades to enhance security and efficiency across the banking sector. New York City, a global financial capital, serves as a primary base for large credit card issuers.
EMV Card Market Key Industry Players
Global majors compete with regional champions across card manufacturing and secure element supply. The market exhibits a tiered structure, with a few large integrated players alongside numerous specialized card producers. Strategic partnerships for technology licensing and geographic expansion characterize competitive moves. Capacity expansion in secure microcontroller production also influences market dynamics.
Specialists in secure identity solutions include IDEMIA, which occupies a position focusing on augmented identity and digital security services. Gemalto, now part of Thales, represents a major player leveraging its extensive patent portfolio in secure element technology. Giesecke & Devrient exemplifies providers concentrating on integrated security solutions for financial institutions. These firms collectively anchor the premium segment of the EMV card market.
| Leading Market Players |
|---|
| Perfect Plastic Printing |
| CPI Card |
| IDEMIA |
| Goldpac |
| Tianyu |
| Gemalto |
| ABCorp |
| Hengbao |
| Giesecke & Devrient |
| Others |
Cost & Logistics Intelligence
Specialized secure element manufacturing expertise in Shenzhen influences global pricing tiers for EMV cards. Labor-cost differentials within Asian production hubs directly shape the spread between premium and standard card offerings.
Pricing Analysis
Card personalization and software integration services often bundle into premium EMV card pricing. This value-based pricing model accounts for advanced security features like biometric integration and specialized software. Price differentiation stems from customization levels and the volume scale of card orders. Pricing softness reflects intense competition among Asian semiconductor suppliers. Financial inclusion programs, driving mass debit card issuance, represent the most price-sensitive buyer segment.
Supply Chain Analysis
Secure microcontroller unit supply primarily hinges on a concentrated group of Asian semiconductor foundries. EMV card manufacturing draws from specialized integrated circuits and secure elements. Geographic concentration in China, South Korea, and Taiwan creates single-source vulnerability for card producers. Geopolitical risks and supply disruptions pose a significant structural risk to the ecosystem. Distribution runs through large-scale card producers with global supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EMV card market presents a cost-of-compliance narrative, where adherence to strict standards is paramount. Europe's GDPR establishes a significant barrier-to-entry moat for compliant financial institutions and processors.
For Market Incumbents: Deploy extensive patent portfolios in secure element technology to maintain market dominance against new entrants. Consolidate market share by investing in integrated security solutions for financial institutions. This strategy mitigates the threat of mobile payment substitution. Focus R&D on biometric integration to enhance security and differentiate product offerings.
For New Entrants and Emerging Players: Underserved small businesses, facing high POS terminal certification costs, represent a penetrable segment. Offer simplified, cost-effective EMV card solutions bundled with compliant POS systems. Target financial inclusion programs in developing nations like India and Brazil with digital-first banking solutions. This go-to-market angle leverages online retail channels for rapid card activation.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized secure element technology firms given the increasing demand for advanced authentication. Long-term viability hinges on companies integrating biometric features and supporting central bank digital currency frameworks. Acquisition targets include agile fintechs developing secure hardware wallets for emerging payment ecosystems. The signal to watch is the widespread adoption of biometric-on-card solutions for everyday purchases.
| Strategic Initiative | Industry Significance |
|---|---|
| Biometric-on-Card Product Launch | This initiative enhances EMV card security and user convenience for high-value consumer segments. |
| CBDC Framework Integration Partnership | Strategic alliances position firms to interface with emerging central bank digital currency systems. |
| Transit System Payment Rollouts Expansion | Expanding into public transit offers high-volume contactless transaction opportunities in major metropolitan areas. |
| Digital Identity Solutions Firm Acquisition | Acquiring specialists strengthens augmented identity offerings and digital security services for customers. |
| Next-Gen Secure Elements R&D Investment | Investing in advanced microcontrollers ensures long-term competitiveness in the EMV card manufacturing ecosystem. |
Research Approach
Payment network mandates, central bank reports, and financial institution filings anchored secondary inputs for this analysis. Primary interviews engaged card manufacturing executives, payment network compliance officers, and fintech platform developers. This approach combined bottom-up data collection with top-down market validation. Secondary research was triangulated against expert insights to ensure data integrity.
Market volume and value were modeled across card type, authentication method, end-user, and distribution channel. An additional dimension, security features, was analyzed for its impact on pricing and adoption over the projection horizon. Compound annual growth rates were derived from historical data trends and future adoption curves. Key forecast inputs included financial inclusion program expansion rates and contactless transaction volumes.
Revisions become necessary when significant shifts in semiconductor supply chain dynamics or payment network mandates materialize. Forecasts reflect assumptions regarding regulatory stability and the pace of biometric technology adoption. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
France Buy Now Pay Later Services Market
Payments
Latin America Subscription and Billing Management Market
Payments
Vietnam Mobile Payments Market
Payments
Contactless Payment Market
Payments
Poland Payments Market
Payments
Smart Bands Payments Market
Payments
Contactless Payment Terminals Market
Payments
China Real Time Payments Market
Payments
Japan Payments Market
Payments
Vietnam E-Wallet Market
Payments
South Korea Mobile Payment Market
Payments
Belgium POS Terminals Market
Payments
Asia-Pacific Crypto Payment Gateway Market
Payments
Norway POS Terminals Market
Payments
Asia-Pacific Accounts Payable Automation Market
Payments
Canada Gift Card and Incentive Card Market