
 Global Antipyretic Drugs for Children Market | 2026-2036
Global Antipyretic Drugs for Children Market Size, Share, and Industry Trends Forecast 2026-2036
Global Antipyretic Drugs for Children Market Foresight
Pediatric clinic procurement is pivoting toward centralized purchasing networks in Southeast Asia and Latin America. Johnson & Johnson leverages its established pediatric brand architecture across retail pharmacy channels. Sanofi S.A. anchors its position through sustained investment in age-appropriate dosage form innovation. GlaxoSmithKline plc competes aggressively in public health tenders across Commonwealth nations.
Antipyretic drugs for children are pharmaceutical agents that reduce elevated body temperature through prostaglandin synthesis inhibition, formulated with weight-calibrated dosing precision and palatability-enhancing excipients to ensure therapeutic adherence in patients aged zero to twelve years. Oral suspension formulations dominate volume due to ease of administration in infants, while suppository segments capture premium positioning in acute febrile seizure management where oral tolerance is compromised. Paracetamol retains the largest share of pediatric prescriptions globally, though ibuprofen segments expand in markets where anti-inflammatory adjunct therapy is prioritized alongside fever reduction.
The FDA maintains stringent pediatric labeling requirements through its Pediatric Exclusivity Provision, while the EMA enforces pediatric investigation plans under Regulation EC No 1901/2006, collectively elevating development costs but narrowing the competitive field to well-capitalized manufacturers. India's CDSCO aligns its pediatric drug approval pathways with WHO prequalification standards, accelerating market entry for domestic producers. Stakeholders must monitor evolving pharmacovigilance mandates for hepatotoxicity risk communication, as regulatory divergence between agencies threatens to fragment formulation strategies and label harmonization efforts.
Market Dynamics
Centralized pediatric procurement networks across Southeast Asia and Latin America are consolidating purchasing power, forcing manufacturers to reconfigure distribution architectures and volume-commitment structures to retain formulary access.
Growth Catalysts
- National Immunization Program Expansion:India's Universal Immunization Programme and Brazil's PNI are embedding fever management protocols into routine pediatric care, creating systematic demand for weight-calibrated antipyretic formulations.
- Pediatric Investigation Plans:EMA Regulation EC No 1901/2006 mandates age-appropriate clinical data, accelerating investment in palatability-enhancing excipient technologies by sponsors seeking exclusivity extensions.
- Acute Febrile Seizure Protocols:Pediatric emergency departments in tertiary hospitals are standardizing suppository administration pathways for patients with compromised oral tolerance, expanding the addressable patient base for rectal dosage forms.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Paracetamol and ibuprofen API supply clusters in China and India expose finished dose manufacturers to export license volatility and geopolitical trade friction.
- Pharmacovigilance Compliance Burden:FDA's Pediatric Exclusivity Provision and evolving hepatotoxicity risk communication requirements are extending development timelines and elevating post-market surveillance costs for sponsors.
- Generic Substitution Pressure:Retail pharmacy chains in price-sensitive markets are driving rapid commoditization of standard oral suspensions, compressing margin structures for originator brands.
Strategic Opportunities
- Sub-Saharan Africa Distribution Gaps:WHO prequalification alignment by India's CDSCO enables domestic Indian manufacturers to supply centralized procurement mechanisms for pediatric fever management in underpenetrated markets.
- Fixed-Dose Combination Innovation:Convergence of antipyretic APIs with antihistamine or decongestant moieties is creating differentiated positioning for multi-symptom pediatric cold and flu segments.
- Direct-to-Clinic Digital Platforms:E-procurement portals linking regional hospital networks with manufacturers are disintermediating traditional pharmaceutical wholesale channels in Southeast Asian markets.
Industry Challenges
- Pediatric Formulation Expertise Scarcity:Shortages of pharmaceutical scientists specializing in taste-masking technologies and age-appropriate excipient selection are constraining R&D throughput for novel dosage forms.
- Label Harmonization Complexity:Divergent hepatotoxicity warning requirements between FDA, EMA, and national regulators are fragmenting packaging specifications and complicating multi-market launches.
- Cold Chain Integrity for Suppositories:Maintaining thermal stability through last-mile distribution in tropical climates requires capital-intensive logistics infrastructure that exceeds capabilities of regional distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Antipyretic Drugs for Children Market |
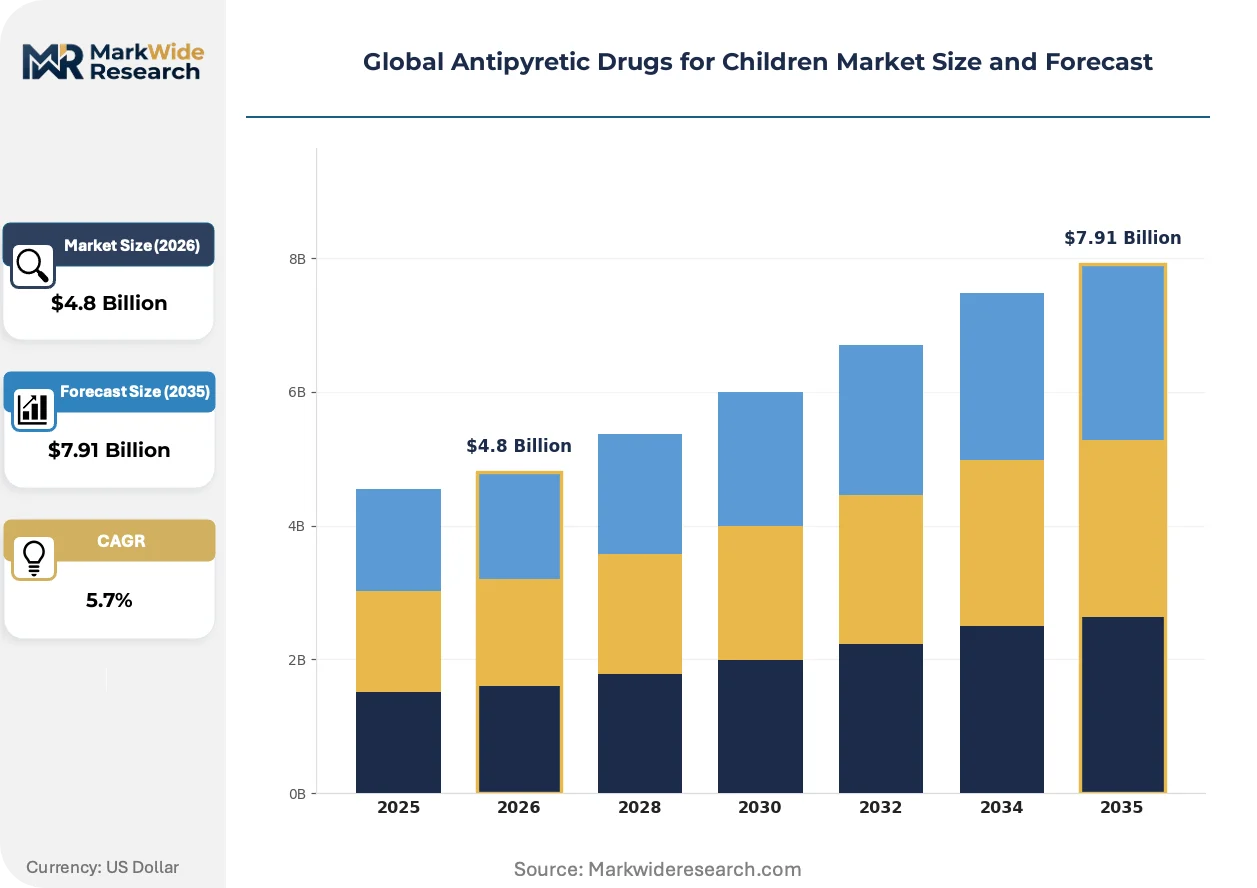
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paracetamol, Ibuprofen, Aspirin, Ketoprofen, Dexibuprofen Dosage Form: Oral Suspension, Tablet, Syrup, Suppository, Drops Route of Administration: Oral, Rectal, Topical, Sublingual, Buccal End User: Pediatric Clinics, Pharmacies, Hospitals, Home Care, Nursing Centers |
| Companies Covered | Bayer AG, Sanofi S.A., Pfizer Inc., Reckitt Benckiser Group, GlaxoSmithKline plc, Johnson & Johnson, Novartis AG, Perrigo Company plc, Merck & Co. Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Antipyretic Drugs for Children Market Shifts & Advancements
Orally disintegrating tablet technologies and real-world evidence generation methodologies are converging to reshape how pediatric antipyretic efficacy and safety are demonstrated to regulators and prescribers.
Orally disintegrating tablet formulations containing microencapsulated ibuprofen are expanding into preschool-aged patient segments previously restricted to liquid suspensions. Pediatric neurologists in European tertiary centers are adopting these formats for febrile seizure prophylaxis where rapid buccal absorption matters. The technology is expanding into home-care settings, enabling caregiver administration without water or measuring devices.
EMA's updated pediatric investigation plan templates now mandate real-world evidence components for post-authorization safety studies, compelling sponsors to invest in electronic health record infrastructure and patient registry partnerships. This regulatory evolution is elevating development costs but creating competitive moats for manufacturers with established pharmacovigilance capabilities. Smaller sponsors lacking these systems are withdrawing from pediatric indication expansions.
Hospital formulary committees in Brazil and India are consolidating purchasing decisions through regional cooperative networks, displacing fragmented clinic-level procurement. These aggregators are demanding outcome guarantees and total-cost-of-therapy metrics rather than unit price concessions. The shift is most visible in public hospital systems where centralized tenders now cover 60-80 percent of institutional volume.
Global Antipyretic Drugs for Children Market Segmentation
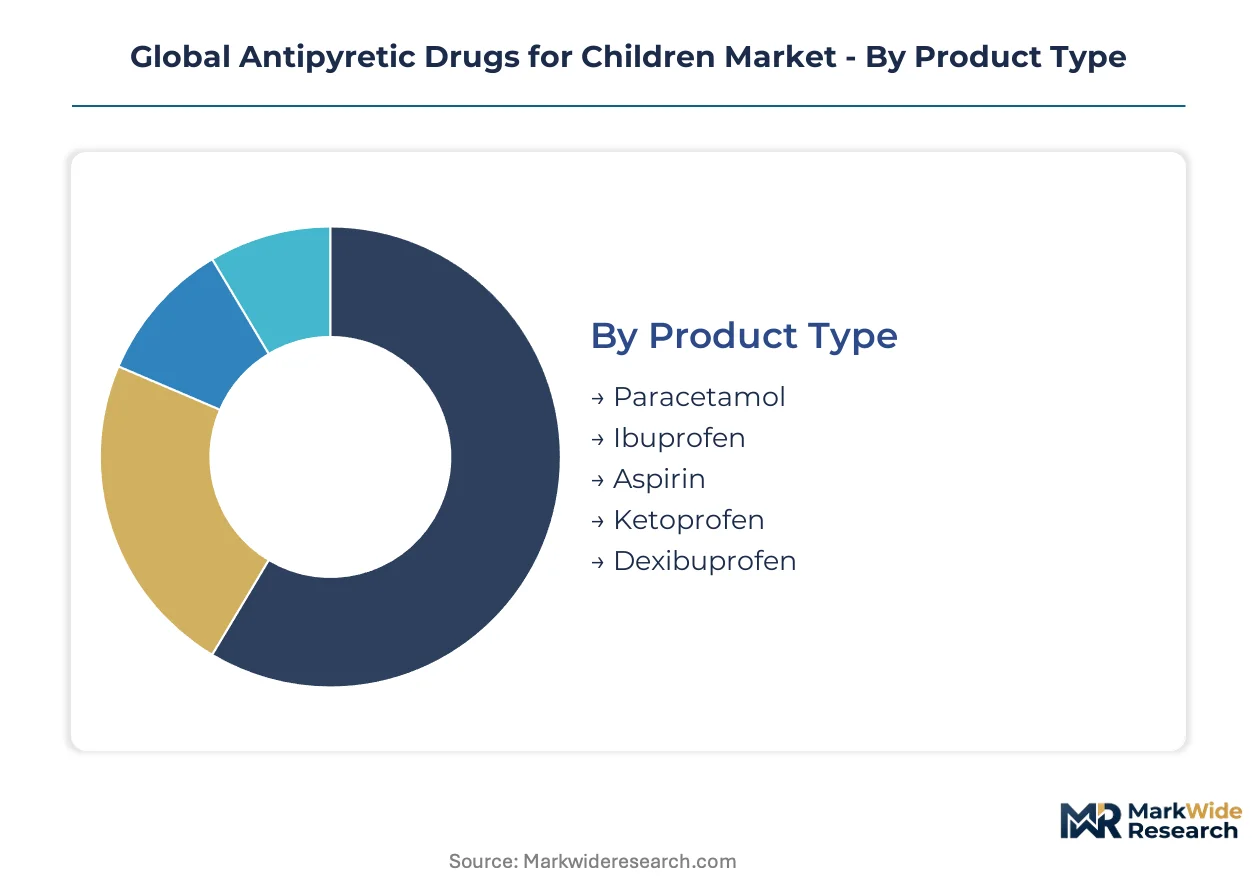
Pediatric antipyretic markets fragment across formulation technologies, procurement channels, and patient age bands. Manufacturers must align R&D investments with where regulatory pathways and reimbursement converge. Each segmentation dimension carries distinct margin profiles and competitive intensity.
Product Type:
API supply concentration in Chinese and Indian manufacturing clusters shapes competitive dynamics across pediatric antipyretic categories.
- Paracetamol:Acetaminophen-based formulations dominate prescription volumes through established hepatotoxicity monitoring protocols and WHO Essential Medicines List inclusion. India's CDSCO-approved domestic producers supply centralized procurement networks across Southeast Asia and Sub-Saharan Africa, where cost-calibrated tender specifications prioritize this API.
- Ibuprofen:Propionic acid derivative with anti-inflammatory adjunct properties expands in markets where febrile seizure prophylaxis protocols favor NSAID mechanisms. European pediatric neurologists in tertiary centers are standardizing ibuprofen-first pathways for specific age brackets, displacing paracetamol in institutional formularies.
- Aspirin:Salicylate compound restricted to niche applications given Reye's syndrome risk profile in viral illness contexts.
- Ketoprofen:Phenylpropionic acid NSAID with limited pediatric labeling due to gastrointestinal tolerability concerns in younger age groups.
- Dexibuprofen:Single-enantiomer ibuprofen variant commanding premium positioning in Western European markets with pharmacoeconomic justification requirements.
Today's leader: Paracetamol. Tomorrow's challenger: Ibuprofen.
Dosage Form:
Palatability engineering investments concentrate where caregiver compliance directly determines therapeutic outcomes.
- Oral Suspension:Aqueous dispersions with viscosity-calibrated flow properties dominate infant and toddler administration. Brazil's public health tenders specify suspension formulations for 70 percent of institutional volume, reflecting caregiver preference in home-care settings.
- Suppository:Lipid-based rectal dosage forms capture acute febrile seizure management where oral tolerance is compromised. Cold chain requirements for tropical distribution limit penetration to hospital-based procurement in Southeast Asian markets.
- Tablet:Compressed solid dosage forms with fracture-scored designs address school-age patient segments.
- Syrup:Viscous liquid preparations with sucrose-based sweetening systems retain volume in price-sensitive retail pharmacy channels.
- Drops:Concentrated solutions with calibrated dropper systems target neonatal and low-weight infant populations.
Oral suspension holds institutional volume leadership. Suppository formats are climbing the fastest in emergency medicine procurement.
Route of Administration:
Patient age and acute clinical presentation dictate route selection, with formulation innovation expanding non-oral alternatives.
- Oral:Gastrointestinal absorption pathway dominates routine fever management across all pediatric age bands. India's Universal Immunization Programme embeds oral antipyretic distribution alongside vaccine administration.
- Rectal:Hepatic first-pass avoidance enables rapid systemic exposure in vomiting or seizure-compromised patients. European tertiary pediatric emergency departments are standardizing rectal administration protocols.
- Topical:Transdermal absorption systems remain investigational for pediatric fever management.
- Sublingual:Buccal mucosa absorption gaining traction in orodispersible tablet formats for preschool populations.
- Buccal:Rapid onset formulations are expanding in home-care settings where water-free administration matters.
Oral routes maintain volume dominance. Buccal and sublingual formats represent the steepest expansion trajectory for formulation innovation.
End User:
Procurement centralization is reshaping channel economics, with institutional aggregators displacing fragmented clinic-level purchasing.
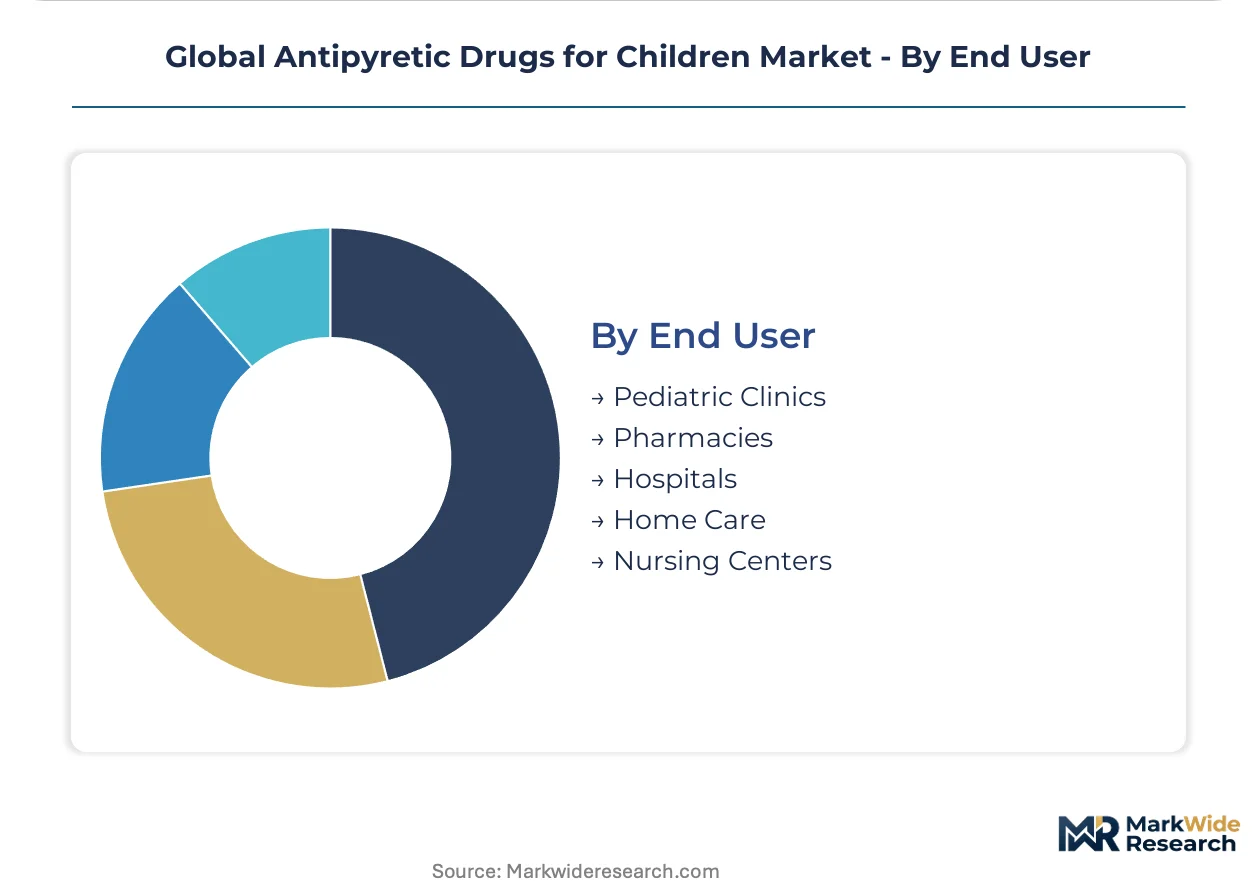
- Pediatric Clinics:Outpatient specialty practices drive volume in Brazil and India through national immunization program integration. Regional cooperative networks in São Paulo and Mumbai are consolidating purchasing decisions.
- Hospitals:Tertiary pediatric centers in European and Commonwealth nations standardize suppository protocols for febrile seizure management. Public hospital systems now cover 60-80 percent of institutional volume through centralized tenders.
- Pharmacies:Retail dispensing channels face generic substitution pressure in price-sensitive markets.
- Home Care:Caregiver-directed administration expanding with orally disintegrating tablet technologies.
- Nursing Centers:Long-stay pediatric facilities represent niche demand for chronic fever management protocols.
Hospital procurement anchors premium positioning. Pediatric clinic networks are gaining share fastest in emerging market expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pediatric pharmaceutical scientists and formulation specialists cluster in Mumbai, Basel, and New Jersey, anchoring R&D gravity for age-appropriate drug development. These talent concentrations shape where clinical trials, regulatory submissions, and manufacturing investments flow. National immunization programs and pediatric procurement networks then determine commercial uptake across distinct geographic markets.
United States
Pediatric emergency departments in Boston and Philadelphia drive suppository protocol standardization for febrile seizure management. The FDA's Pediatric Exclusivity Provision mandates age-specific clinical data, extending development timelines for sponsors seeking market entry. New Jersey-based pharmaceutical clusters host formulation scientists specializing in taste-masking technologies for oral suspensions.
Germany
EMA pediatric investigation plans under Regulation EC No 1901/2006 elevate development costs, narrowing the competitive field to well-capitalized manufacturers. Frankfurt and Munich anchor pharmacovigilance infrastructure for post-market surveillance of hepatotoxicity signals. German tertiary pediatric centers standardize ibuprofen-first pathways for specific age brackets in febrile seizure prophylaxis.
India
CDSCO alignment with WHO prequalification standards accelerates market entry for domestic producers supplying Sub-Saharan Africa. Mumbai and Hyderabad concentrate formulation manufacturing for weight-calibrated oral suspensions. India's Universal Immunization Programme embeds systematic antipyretic distribution alongside vaccine administration, creating institutional demand.
Brazil
São Paulo-based regional cooperative networks consolidate pediatric clinic procurement, displacing fragmented clinic-level purchasing. ANVISA maintains stringent pediatric labeling requirements that reshape product development priorities for market entrants. Rio de Janeiro and São Paulo anchor public health tender administration covering 60-80 percent of institutional hospital volume.
China
NMPA pediatric drug approval pathways require domestic clinical data, constraining foreign sponsor market entry without local partnership structures. Shanghai and Jiangsu province concentrate active pharmaceutical ingredient manufacturing for paracetamol and ibuprofen. Export license volatility from these clusters exposes finished dose manufacturers to supply disruption risk.
Global Antipyretic Drugs for Children Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation technologies and geographic markets. The vendor base stratifies into three tiers: originator pharmaceutical companies with established pediatric brand architectures, generic manufacturers supplying centralized procurement networks, and regional specialists dominating niche dosage forms. Consolidation pressures intensify as retail pharmacy chains drive rapid commoditization of standard oral suspensions. Two dominant competitive moves define current positioning: strategic partnerships with e-procurement platforms disintermediating wholesale channels, and backward integration into API supply to mitigate concentration risk in Chinese and Indian manufacturing clusters.
Among diversified healthcare conglomerates, Johnson & Johnson and Sanofi S.A. exemplify archetypes with established pediatric brand recognition across retail pharmacy channels. GlaxoSmithKline plc occupies a position within the institutional tender-focused tier, competing aggressively in public health procurement across Commonwealth nations. These three anchors represent distinct strategic postures: one leveraging consumer health infrastructure, one emphasizing age-appropriate dosage innovation, and one optimizing for centralized purchasing network access.
| Leading Market Players |
|---|
| Bayer AG |
| Sanofi S.A. |
| Pfizer Inc. |
| Reckitt Benckiser Group |
| GlaxoSmithKline plc |
| Johnson & Johnson |
| Novartis AG |
| Perrigo Company plc |
| Merck & Co. Inc. |
| Others |
Supply & Pricing Matrix
Microencapsulation technology migration for orally disintegrating tablets is simultaneously elevating R&D cost structures and concentrating manufacturing capability among sponsors with captive formulation expertise, tightening supply-side capacity for novel dosage forms while enabling premium positioning for rapid-onset pediatric products.
Pricing Analysis
Bundle-unbundle splits separate premium orodispersible tablet formats from commodity oral suspensions across procurement channels. Three-tier pricing structure across premium, standard, and economy levels stratifies by formulation complexity and regulatory exclusivity status, with originator brands commanding differential margins in hospital formulary segments. Cost compression in standard oral suspensions is intensifying because retail pharmacy chains in India and Brazil are consolidating generic substitution protocols. Public hospital tenders exhibit highest price sensitivity; private pediatric clinics in Western European markets demonstrate lowest sensitivity due to outcome-based reimbursement frameworks.
Supply Chain Analysis
Dual-sourcing mandates from EMA and FDA pediatric investigation plans are forcing sponsors to qualify secondary API suppliers beyond primary Chinese and Indian manufacturing clusters. Active pharmaceutical ingredient supply draws from China, India, and Germany for paracetamol, ibuprofen, and dexibuprofen respectively. Raw material dependencies rest on 4-aminophenol precursors, propionic acid derivatives, and specialized taste-masking excipients. Single-source vulnerability concentrates in Shanghai and Jiangsu province paracetamol API manufacturing. Distribution runs through centralized procurement networks in Southeast Asia and Latin America, disintermediating traditional wholesale pharmaceutical channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pediatric antipyretic markets offer margin expansion through formulation premiumization and API supply chain rationalization, with taste-masking technology investments and backward integration into Indian manufacturing clusters driving unit economics improvement.
For Market Incumbents: Acquire captive taste-masking formulation capabilities to defend against generic substitution pressure in retail pharmacy channels. Secure dual-qualified API supply from Indian CDSCO-approved manufacturers beyond Chinese manufacturing clusters to mitigate export license volatility. Reinforce hospital formulary positioning through real-world evidence infrastructure investments meeting EMA post-authorization study mandates. For New Entrants and Emerging Players: CDSCO-WHO prequalification alignment in India opens a window for Sub-Saharan Africa institutional tender participation, bypassing saturated Western European and North American markets. Target underpenetrated pediatric clinic cooperative networks in São Paulo and Mumbai with weight-calibrated oral suspension formats. Pursue direct-to-clinic digital procurement platform partnerships as the primary go-to-market channel, disintermediating legacy pharmaceutical distribution. For Investors and Strategic Acquirers: Valuations sit cheapest among regional Indian manufacturers with WHO prequalification status and limited formulation R&D depth. Long-term viability centers on sponsors with established pharmacovigilance systems capable of meeting evolving FDA hepatotoxicity risk communication requirements. Watch EMA pediatric investigation plan template revisions as the signal for regulatory compliance cost inflection and competitive field narrowing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Manufacturing | Captive paracetamol and ibuprofen production in Indian clusters mitigates Chinese export license volatility for finished dose sponsors. |
| Orally Disintegrating Tablet Platform Launch | Microencapsulated ibuprofen formats penetrate preschool segments previously restricted to liquid suspensions in European tertiary centers. |
| EMA Pediatric Investigation Plan Advancement | Age-appropriate clinical data packages under Regulation EC No 1901/2006 secure exclusivity extensions and narrow competitive fields. |
| Direct-to-Clinic E-Procurement Partnership | Digital platforms linking Southeast Asian hospital networks disintermediate wholesale channels and capture institutional volume. |
| Real-World Evidence Infrastructure Investment | Electronic health record partnerships and patient registry capabilities meet EMA post-authorization safety study mandates. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with pediatric drug development executives, regulatory affairs leads at EMA and FDA, hospital formulary directors, and pharmaceutical procurement managers with secondary validation against FDA pediatric exclusivity filings, EMA pediatric investigation plan submissions, ClinicalTrials.gov pediatric antipyretic entries, and WHO prequalification databases. Bottom-up volume modeling and top-down market sizing triangulated across formulation segment, API type, and regional regulatory cluster dimensions.
Segment-weighting approaches distributed volume and value projections across dosage form, route of administration, patient age band, and procurement channel categories throughout the forecast period. Compound annual growth rates derived from regression analysis of historical tender volumes, immunization program expansion trajectories, and formulation technology adoption curves. Forecast inputs incorporated pediatric clinic procurement centralization rates in Brazil and India, suppository protocol standardization in European tertiary hospitals, and orodispersible tablet penetration assumptions for preschool populations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under API export restriction scenarios or pediatric pharmacovigilance mandate acceleration. Projections reflect documented assumptions regarding national immunization program expansion timelines and centralized procurement network consolidation rates. Deviation in EMA-FDA hepatotoxicity warning harmonization would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Sterile Injectable Drugs Market
Pharmaceuticals
Latin America FMD Vaccine Market
Pharmaceuticals
Cough Suppressant Drugs Market
Pharmaceuticals
Direct Oral Anticoagulants Market
Pharmaceuticals
Ophthalmic Drug Delivery Systems Market
Pharmaceuticals
Multiple System Atrophy (MSA) Therapeutics Market
Pharmaceuticals
Global Plasma Derived Therapy Market
Pharmaceuticals
Gonorrhea Therapeutics Market
Pharmaceuticals
Methylphenidate Hydrochloride Market
Pharmaceuticals
Structured Product Label Management Market
Pharmaceuticals
Middle East and Africa Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
Bone Degeneration Therapeutics Market
Pharmaceuticals
Global Gastroparesis Drug Market
Pharmaceuticals
Aminophylline Market
Pharmaceuticals
Global Nasal Drug Delivery Technology Market
Pharmaceuticals
Global Diphenhydramine Market