
 Mitotane Market | 2026-2036
Mitotane Market Size, Share, and Industry Trends Forecast 2026-2036
Mitotane Market Foresight
Oncology research institutes are gaining procurement share as the demand base is bifurcating between traditional hospital purchasers and academic medical centers running investigator-led trials. HRA Pharma Rare Diseases anchors European supply through its orphan drug exclusivity and dedicated rare disease infrastructure. Bristol-Myers Squibb Company leverages its oncology portfolio breadth to cross-sell mitotane alongside immuno-oncology protocols in major cancer centers. Novartis Pharmaceuticals Corporation competes through its established hospital formulary relationships and specialty pharmacy distribution networks.
Mitotane is a dichlorodiphenyltrichloroethane derivative with adrenolytic properties, administered orally at doses titrated between 2-16 grams daily based on plasma concentration monitoring, and functions primarily as an adjuvant or palliative therapy for unresectable adrenal cortex carcinoma. Tablet formulations dominate current prescription volumes due to established bioavailability profiles and patient compliance familiarity, while injectable formats represent the fastest-expanding segment as hospitals seek acute care administration options for critically ill patients. Off-label applications in Cushing's Syndrome management constitute a concentrated margin pool where specialty clinicians command premium pricing for protocol oversight.
The FDA's orphan drug regulations govern U.S. market entry incentives and post-approval reporting obligations for mitotane sponsors, while EMA's centralized procedure dictates European authorization timelines and pediatric investigation requirements. These frameworks shape clinical trial investment decisions and geographic launch sequencing for manufacturers. Stakeholders must monitor evolving plasma concentration monitoring guidelines and competitive generic entry timelines to optimize portfolio positioning and patient access programs.
Market Dynamics
Plasma concentration monitoring protocols are tightening dosage precision requirements, forcing manufacturers to invest in companion diagnostic infrastructure and specialized pharmacy services to maintain therapy adherence.
Growth Catalysts
- EMA Orphan Drug Pathways:Streamlined authorization timelines accelerate European market entry for rare disease therapeutics, reducing regulatory friction for adrenal cortex carcinoma treatments.
- Academic Medical Centers:Investigator-led trials at oncology research institutes expand off-label protocol development for Cushing's Syndrome management, creating new prescription volume pools.
- Injectable Formulations:Hospitals seeking acute care administration options for critically ill patients drive fastest-expanding segment demand alongside established tablet volumes.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Single-source dichlorodiphenyltrichloroethane derivative supply creates vulnerability to production disruption or quality variability.
- FDA Post-Approval Reporting Obligations:Orphan drug regulations impose sustained compliance costs and pharmacovigilance infrastructure requirements on sponsors.
- Plasma Monitoring Complexity:Therapeutic drug monitoring necessity limits prescribing to specialized oncology centers, constraining addressable prescriber base.
Strategic Opportunities
- Pediatric Investigation Requirements:EMA mandates for pediatric study plans create first-mover advantage for sponsors completing age-appropriate efficacy trials.
- Specialty Pharmacy Networks:Direct distribution to hospital outpatient clinics bypasses traditional wholesale channels, capturing margin from formulary placement.
- Generic Entry Timing:Orphan exclusivity expiration windows present portfolio expansion opportunities for manufacturers with bioequivalence capabilities.
Industry Challenges
- Adrenolytic Toxicity Management:Dose titration between 2-16 grams daily requires specialized nursing protocols and patient education infrastructure that strains community oncology practices.
- Cross-Border Supply Coordination:Temperature-controlled logistics for plasma samples and drug product create customs clearance friction between European member states.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mitotane Market |
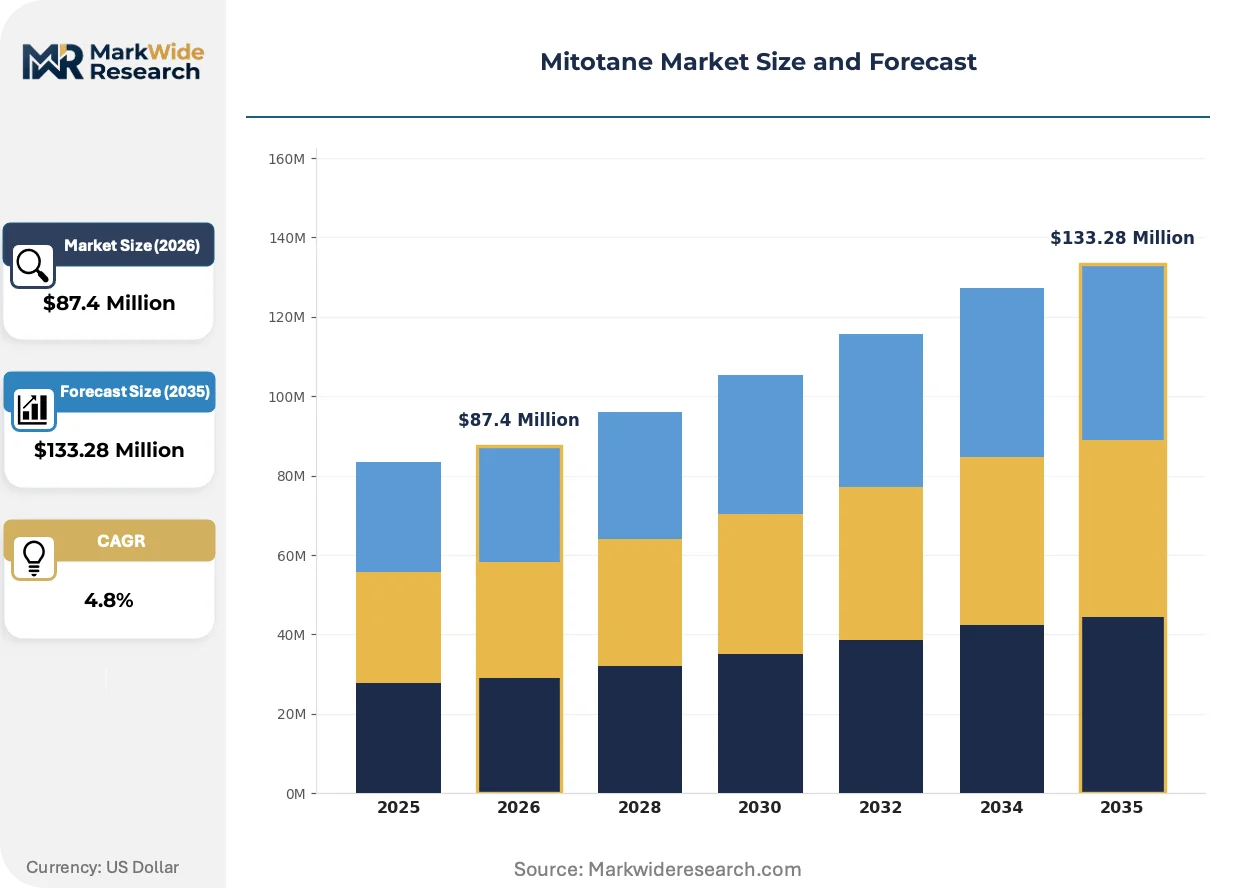
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $133.28 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Injectable, Liquid Application: Cushing's Syndrome, Adrenal Cortex Carcinoma, Off-label Uses, Oncology Research End User: Hospitals, Clinics, Research Institutes, Pharmacies Distribution Channel: Direct Sales, Online Pharmacies, Wholesalers, Retail Pharmacies |
| Companies Covered | HRA Pharma Rare Diseases, Bristol-Myers Squibb Company, TherDose Pharma Pvt. Ltd, Hikma Pharmaceuticals, Tizig Pharma Pvt. Ltd, Aspen Pharmacare, Prime Therapeutics, Novartis Pharmaceuticals Corporation, ESTEVE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mitotane Market Shifts & Advancements
Companion diagnostic integration and real-world evidence collection are restructuring how mitotane therapy is initiated, monitored, and reimbursed across specialized cancer centers.
Liquid chromatography-tandem mass spectrometry for plasma mitotane quantification is supplanting older immunoassay methods in reference laboratories. Major cancer centers in the United States and Germany are adopting this platform to reduce assay variability and shorten turnaround times. The shift is compressing the window between dose adjustment and clinical response assessment, enabling tighter therapeutic control.
REACH registration requirements for dichlorodiphenyltrichloroethane derivatives are tightening substance volume tracking and environmental release reporting across European manufacturing sites. Chemical suppliers must now document lifecycle stewardship from synthesis through waste disposal. This is elevating compliance costs for API producers and favoring integrated manufacturers with captive environmental remediation capabilities.
Hospital formulary committees now require pharmacoeconomic justification bundled with clinical efficacy data for mitotane placement. Specialty pharmacy distributors are responding with outcomes-tracking platforms that document progression-free survival metrics tied to reimbursement. This behavioral shift is most pronounced in United States academic medical centers where value-based oncology contracts predominate.
Mitotane Market Segmentation
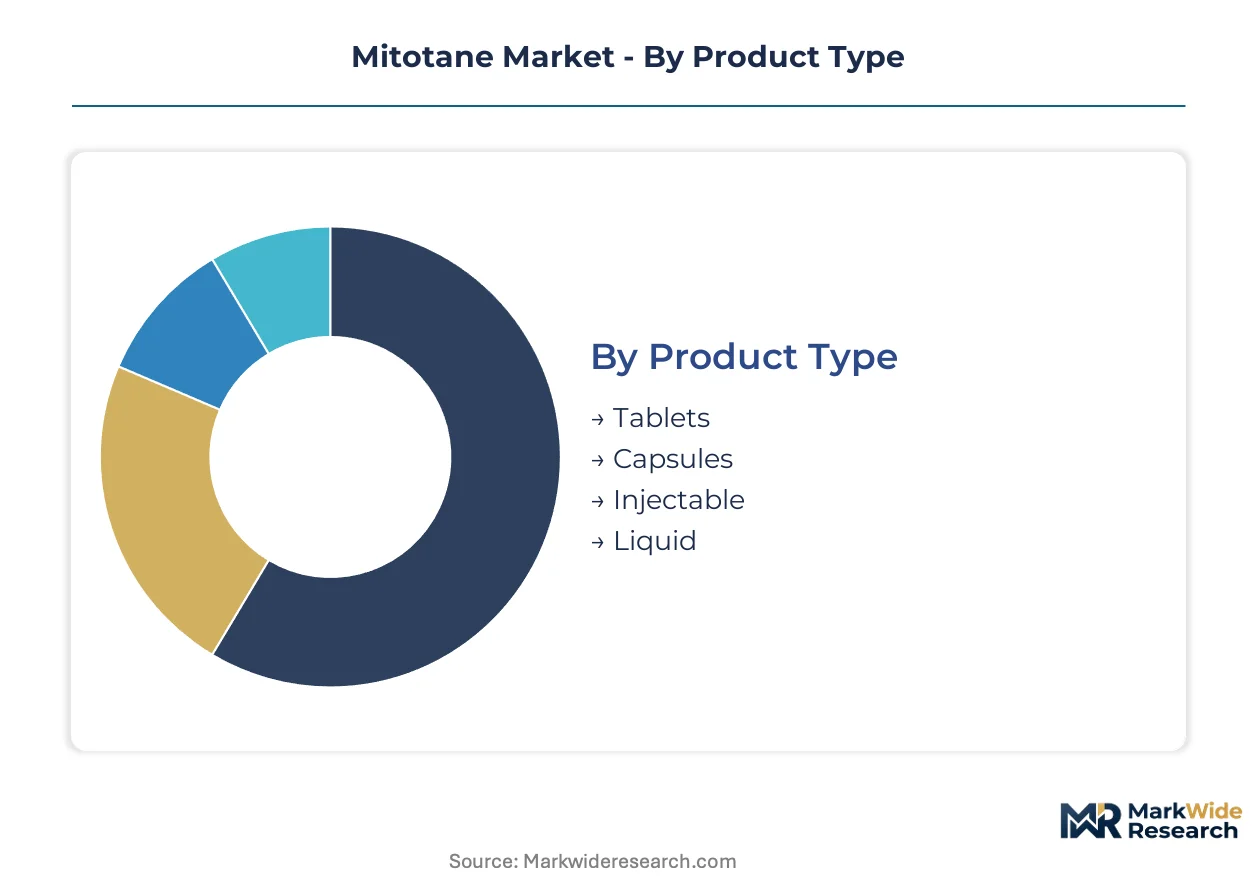
Mitotane's therapeutic complexity demands precise segmentation across formulation types, clinical applications, and institutional access points. Each dimension carries distinct regulatory, logistical, and reimbursement implications that shape procurement patterns and manufacturer strategy.
Product Type:
Domestic prescription volumes cluster around oral formulations with established bioavailability profiles, while export-led growth concentrates in acute-care injectable formats serving hospital systems.
- Tablets:Oral solid dosage forms with standardized 500mg strength dominate outpatient maintenance therapy. United States cancer centers anchor demand through established titration protocols and plasma monitoring infrastructure.
- Capsules:Gelatin-encapsulated formulations offer alternative delivery for patients with tablet intolerance. European hospital outpatient clinics in Germany and France drive concentrated procurement alongside tablet volumes.
- Injectable:Parenteral formulations enable acute administration for critically ill patients unable to tolerate oral intake. Hospital emergency departments and intensive care units in academic medical centers represent the fastest-expanding demand pool.
- Liquid:Oral suspension formats serve pediatric populations and patients with swallowing difficulties. Compounding pharmacies in specialized cancer networks handle most volume.
Tablets command the established base. The steepest expansion runs through Injectable formats.
Application:
Cost tier stratification separates premium-priced orphan indications from lower-margin off-label protocols, with research applications occupying a distinct reimbursement band.
- Adrenal Cortex Carcinoma:FDA-approved indication for adjuvant and palliative therapy in unresectable disease. United States oncology practices with designated rare disease programs concentrate prescription authority and reimbursement negotiation leverage.
- Cushing's Syndrome:Off-label management of hypercortisolism generates concentrated margin pools where endocrinology specialists command premium protocol oversight fees. Academic medical centers in Boston and Houston anchor investigator-led use.
- Off-label Uses:Experimental protocols in hormone-refractory malignancies and metabolic disorders. Research institutes with dedicated endocrine oncology divisions handle most volume.
- Oncology Research:Preclinical and clinical trial supply for mechanism-of-action studies and combination therapy development. National Cancer Institute-designated centers and European comprehensive cancer networks drive procurement.
Adrenal Cortex Carcinoma anchors the revenue base. The steepest expansion trajectory belongs to Cushing's Syndrome as protocol maturation expands prescriber comfort.
End User:
Customer type fragmentation reflects the therapy's concentration in specialized settings, with volume scale inversely correlated with prescriber base breadth.
- Hospitals:Inpatient administration, emergency dosing, and plasma concentration monitoring infrastructure. Major cancer centers in the United States, Germany, and France concentrate procurement through centralized pharmacy operations.
- Clinics:Outpatient maintenance therapy and dose titration management. Community oncology practices with rare disease expertise in suburban markets handle growing volume.
- Research Institutes:Investigator-initiated trials and pharmacokinetic studies. National institutes and university-affiliated cancer centers drive demand.
- Pharmacies:Specialty and retail dispensing for stable outpatients on maintenance regimens. Limited to accredited rare disease pharmacy networks.
Hospitals command the established base. The steepest expansion runs through Research Institutes as academic trial portfolios broaden.
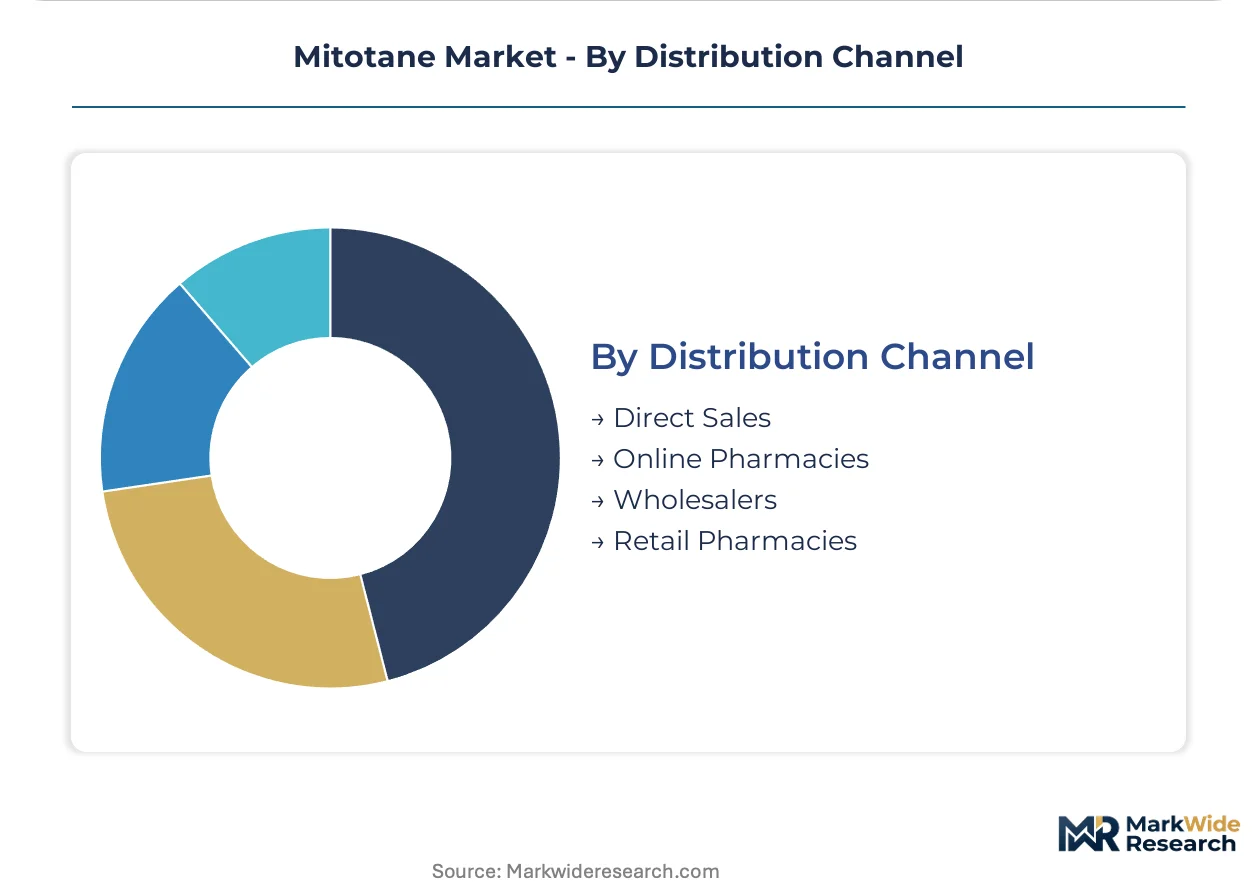
Distribution Channel:
Supply concentration favors direct manufacturer-to-institution pathways, with margin compression in intermediary-heavy channels.
- Direct Sales:Manufacturer contracts with hospital systems and specialty pharmacy networks. Bypasses wholesale markups and enables formulary placement negotiation.
- Wholesalers:Traditional three-tier distribution for retail and community pharmacy access. Faces margin pressure from direct channel expansion.
- Online Pharmacies:Digital dispensing platforms for patient home delivery. Limited by controlled substance scheduling and cold-chain requirements.
- Retail Pharmacies:Community pharmacy pickup for stable maintenance patients. Minimal volume due to specialty handling requirements.
Direct Sales commands the established base. The steepest expansion runs through Online Pharmacies as patient convenience preferences shift.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold-chain infrastructure anchors European distribution for temperature-sensitive oncology compounds. Specialized logistics corridors connecting Rotterdam to the Rhine-Ruhr industrial belt enable rapid transit of plasma monitoring samples and finished drug product.
United States
MD Anderson Cancer Center in Houston and Memorial Sloan Kettering in New York anchor prescription volumes for adrenal cortex carcinoma protocols. FDA orphan drug regulations govern post-approval reporting obligations and market exclusivity incentives for rare disease therapeutics. The National Cancer Institute's designated comprehensive cancer centers in Boston and Seattle concentrate investigator-led trials and plasma concentration monitoring infrastructure.
Germany
EMA centralized authorization procedures streamline market entry for orphan-designated compounds treating rare malignancies. REACH registration requirements for dichlorodiphenyltrichloroethane derivatives mandate substance volume tracking across manufacturing sites in North Rhine-Westphalia. Heidelberg University Hospital and Charité Berlin anchor European plasma monitoring standardization and reference laboratory services.
France
ANSM oversight of hospital pharmacy operations shapes formulary placement for adrenolytic therapies in public cancer centers. The country's national rare disease plan coordinates referral networks connecting regional hospitals to specialized endocrine oncology units in Paris and Lyon. Gustave Roussy in Villejuif concentrates pediatric investigation protocols and combination therapy research.
United Kingdom
NHS specialized commissioning frameworks determine reimbursement eligibility for mitotane in adrenal cortex carcinoma through designated cancer centers. The Medicines and Healthcare products Regulatory Agency's orphan drug pathway aligns with EMA procedures for rare disease authorization. Royal Marsden Hospital and Christie Manchester anchor plasma therapeutic drug monitoring services and clinical trial recruitment.
India
CDSCO manufacturing license requirements for scheduled formulations govern domestic production of dichlorodiphenyltrichloroethane derivatives. The country's pharmaceutical export corridors through Mumbai and Ahmedabad supply API to European formulation facilities. Tata Memorial Centre in Mumbai and AIIMS Delhi concentrate investigator-initiated protocols for off-label Cushing's Syndrome management.
Mitotane Market Competitive Landscape
Listed leaders compete with private specialists across orphan drug infrastructure and rare disease distribution networks. The market structure concentrates around three archetypes: integrated pharmaceutical conglomerates with oncology portfolios, dedicated rare disease specialists with European orphan exclusivity, and contract manufacturers supplying API and finished dosage forms. Competitive positioning hinges on plasma monitoring service bundling and direct hospital formulary relationships rather than traditional wholesale channels.
Within the rare disease specialist tier, HRA Pharma Rare Diseases occupies a position exemplifying European orphan drug infrastructure and dedicated distribution networks. Among integrated pharmaceutical conglomerates, Bristol-Myers Squibb Company and Novartis Pharmaceuticals Corporation represent archetypes of oncology portfolio breadth and hospital formulary leverage. TherDose Pharma Pvt. Ltd anchors the contract manufacturing segment, supplying finished dosage forms to markets where specialized production capabilities concentrate.
| Leading Market Players |
|---|
| HRA Pharma Rare Diseases |
| Bristol-Myers Squibb Company |
| TherDose Pharma Pvt. Ltd |
| Hikma Pharmaceuticals |
| Tizig Pharma Pvt. Ltd |
| Aspen Pharmacare |
| Prime Therapeutics |
| Novartis Pharmaceuticals Corporation |
| ESTEVE |
| Others |
Supply & Pricing Matrix
Ninety-day plasma concentration assay turnaround times concentrate pricing power with reference laboratories in Germany and the United States, anchoring cost structures to specialized diagnostic infrastructure rather than commodity drug manufacturing. This temporal dependency shapes how manufacturers bundle monitoring services with product supply to defend margin pools.
Pricing Analysis
Volume-discount tiering separates academic medical center consortiums from individual hospital purchasers, with the former capturing standard-tier pricing through multi-year formulary commitments while community oncology practices absorb premium-tier rates for sporadic procurement. Price differentiation hinges on plasma monitoring service bundling and orphan drug exclusivity status. Pricing pressure stems from REACH compliance cost pass-through from European API suppliers. Academic research institutes exhibit highest price sensitivity due to grant-funded procurement constraints.
Supply Chain Analysis
Strategic stockpiling of dichlorodiphenyltrichloroethane derivative API dominates inventory strategy among European manufacturers confronting REACH substance volume tracking requirements, while United States formulators maintain leaner just-in-time positions anchored to specialized pharmacy networks. Supply concentrates in India, Germany, and the United States for API synthesis and finished dosage form production. Raw material dependencies encompass chlorinated benzene feedstocks, specialized reactor vessels, and reference standard materials for plasma assay calibration. Single-source API vulnerability creates exposure to environmental remediation compliance disruptions. Distribution runs through direct manufacturer-to-hospital contracts bypassing wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized plasma monitoring expertise functions as the scarce capability separating viable competitors from marginal participants, with proficiency in liquid chromatography-tandem mass spectrometry protocols determining formulary access velocity.
For Market Incumbents: Consolidate control over reference laboratory partnerships to lock in diagnostic workflow integration before generic entrants replicate service bundling. Deepen backward integration into dichlorodiphenyltrichloroethane derivative API production to mitigate REACH-driven supplier concentration risk. Priority defensive moves center on captive plasma assay capacity in Heidelberg and Houston cancer center clusters. For New Entrants and Emerging Players: Companion diagnostic software gaps in real-world evidence collection platforms present white-space targets where incumbents under-serve community oncology practices lacking integrated outcomes-tracking infrastructure. Penetrable entry points concentrate in Cushing's Syndrome protocol development at suburban clinic networks. Go-to-market positioning through specialty pharmacy accreditation programs bypasses formulary committee friction. For Investors and Strategic Acquirers: Carve-out targets emerge from pharmaceutical conglomerates orphan drug portfolios facing post-exclusivity revenue cliffs, particularly European assets with established EMA pediatric investigation waivers. Long-term viability frames around plasma monitoring service attach rates rather than molecule patent life. Signal to watch: generic bioequivalence study initiations crossing threshold volumes in United States ANDA filings.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Monitoring Service Integration | Bundled diagnostic workflows lock hospital formulary placement against generic substitution at MD Anderson and Memorial Sloan Kettering. |
| REACH Compliance Infrastructure Investment | Captive environmental remediation capabilities at German manufacturing sites reduce API supply disruption exposure from ECHA enforcement actions. |
| Pediatric Investigation Completion | EMA-mandated age-appropriate efficacy trials at Gustave Roussy create first-mover exclusivity extension opportunities in rare disease protocols. |
| Specialty Pharmacy Network Accreditation | Direct distribution to hospital outpatient clinics bypasses wholesale markups and captures margin from formulary placement negotiations. |
| Injectable Formulation Capacity Expansion | Acute care administration options for critically ill patients in intensive care units represent the fastest-expanding demand pool segment. |
Research Methodology
Desk research of FDA orphan drug filings, EMA centralized procedure documentation, and ClinicalTrials.gov protocol registries preceded structured interviews with drug development executives, hospital formulary directors, regulatory affairs leads, and specialty pharmacy procurement managers. Secondary validation drew from formulary database audits, SEC pharmaceutical segment disclosures, and REACH substance volume tracking records. Bottom-up prescription volume modeling triangulated against top-down orphan drug market sizing across the analysis window.
Variance-decomposition framing separated volume drivers from price mix effects, with analytical framework outputs reflecting patient population segmentation by treatment line, dosage form preference, and regional regulatory cluster throughout the forecast period. CAGRs derived from log-linear trend fitting to historical prescription data adjusted for plasma monitoring protocol adoption curves and generic entry probability distributions. Forecast inputs incorporated orphan drug exclusivity expiration schedules and pediatric investigation plan completion timelines.
Underlying assumptions cover sustained EMA orphan pathway authorization velocity and REACH compliance cost pass-through stability, with deviation risk concentrated in single-source API supply disruptions and plasma assay standardization delays. Revision becomes warranted when generic ANDA submission volumes cross thresholds triggering accelerated price erosion in United States oncology practices.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Anorexiants Market
Pharmaceuticals
Hepatic Antiviral Drugs Market
Pharmaceuticals
PDE Inhibitors Market
Pharmaceuticals
Risedronate Sodium Market
Pharmaceuticals
Antiepilepsy Drugs Market
Pharmaceuticals
Dopamine and Norepinephrine Reuptake Inhibitor Market
Pharmaceuticals
Thrombosis Drugs Market
Pharmaceuticals
Global Bacterial Vaccines Market
Pharmaceuticals
Drug-Induced Dyskinesia Market
Pharmaceuticals
Fast Melt Tablets Market
Pharmaceuticals
Global Fluorouracil (5FU) Market
Pharmaceuticals
Intelligent Pills Market
Pharmaceuticals
US Hormone Replacement Therapy Market
Pharmaceuticals
Digital Pharmaceutical Supply Chain Management Market
Pharmaceuticals
Middle East and Africa Adenomyosis Drugs Market
Pharmaceuticals
Cough Oral Solution Market