
 Global Veterinary Infectious Disease Diagnostics Market | 2026-2036
Global Veterinary Infectious Disease Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Veterinary Infectious Disease Diagnostics Market Foresight
CLIA-waived point-of-care standards is bifurcating the competitive landscape between centralized reference laboratories and field-deployable assay providers. IDEXX Laboratories Inc. leverages its SNAP platform installed base to dominate companion animal clinic channels. Zoetis Services LLC anchors its position through integrated livestock diagnostics bundled with vaccine portfolios. Thermo Fisher Scientific Inc. extends its Applied Biosystems PCR franchise into veterinary pathogen panels for bovine and porcine screening.
Veterinary infectious disease diagnostics encompasses laboratory and point-of-care testing systems designed to detect, identify, and quantify pathogenic agents in animal specimens, with PCR assays typically achieving analytical sensitivity thresholds of 10–100 copies per reaction for nucleic acid targets. These technologies serve commercial purposes spanning herd health management, regulatory trade certification, zoonotic disease containment, and antimicrobial stewardship compliance. ELISA Kits retain the largest revenue share across livestock and poultry operations where high-throughput serological surveillance remains economically essential. Real-Time PCR represents the fastest-expanding technology segment as veterinary reference laboratories replace legacy culture methods with quantitative pathogen detection. Next-Generation Sequencing is displacing conventional typing approaches for emerging strain characterization in avian influenza and African swine fever monitoring programs.
FDA Center for Veterinary Medicine oversees diagnostic assay validation for animal health applications, while USDA APHIS mandates interstate movement testing for reportable diseases such as brucellosis and tuberculosis. The OIE Terrestrial and Aquatic Animal Health Codes establish international harmonization standards that shape export-oriented diagnostic requirements for trading nations. Stakeholders must monitor evolving regulatory convergence between human and veterinary antimicrobial resistance surveillance frameworks to anticipate future assay specification demands.
Market Dynamics
CLIA-waived point-of-care standards are bifurcating competitive positioning between centralized reference laboratories and field-deployable assay providers, compressing turnaround times from days to hours for companion animal infectious disease screening.
Growth Catalysts
- EU Green Deal livestock mandates:The EU Green Deal and Farm-to-Fork Strategy tighten pathogen surveillance requirements across member states, forcing diagnostic kit procurement upgrades for bovine and porcine operations.
- Real-Time PCR technology transition:Veterinary reference laboratories are replacing legacy culture methods with quantitative nucleic acid detection, expanding assay menus for brucellosis and tuberculosis screening.
- USDA APHIS interstate movement rules:Mandatory testing for reportable diseases creates recurring demand for validated ELISA and PCR kits among US livestock exporters.
Market Restraints
- PCR reagent supply concentration:Taq polymerase and probe chemistries concentrate among specialized biochemical suppliers, exposing assay manufacturers to input cost volatility and allocation constraints.
- Validation timeline friction:FDA Center for Veterinary Medicine diagnostic assay validation protocols extend commercialization cycles for novel pathogen panels by 18-36 months.
- Culture method substitution inertia:Legacy phenotypic identification retains cost advantages in resource-constrained poultry operations, slowing molecular adoption in price-sensitive segments.
Strategic Opportunities
- Next-Generation Sequencing convergence:NGS platforms are decomposing conventional serotyping approaches for African swine fever and avian influenza strain characterization, opening subscription-based surveillance models.
- India livestock health modernization:The country's national veterinary regulator is expanding laboratory network capacity for foot-and-mouth disease and peste des petits ruminants diagnostics.
- Antimicrobial stewardship compliance:OIE Terrestrial Animal Health Code harmonization is creating export certification demand for quantitative susceptibility testing integration with infectious disease panels.
Industry Challenges
- Veterinary molecular diagnostics skill scarcity:Clinical pathologists with dual training in bioinformatics and infectious disease epidemiology remain concentrated in academic medical centers, constraining reference laboratory expansion.
- Point-of-care device integration complexity:Field-deployable readers must interface with practice management software systems lacking standardized data exchange protocols, delaying clinic adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Veterinary Infectious Disease Diagnostics Market |
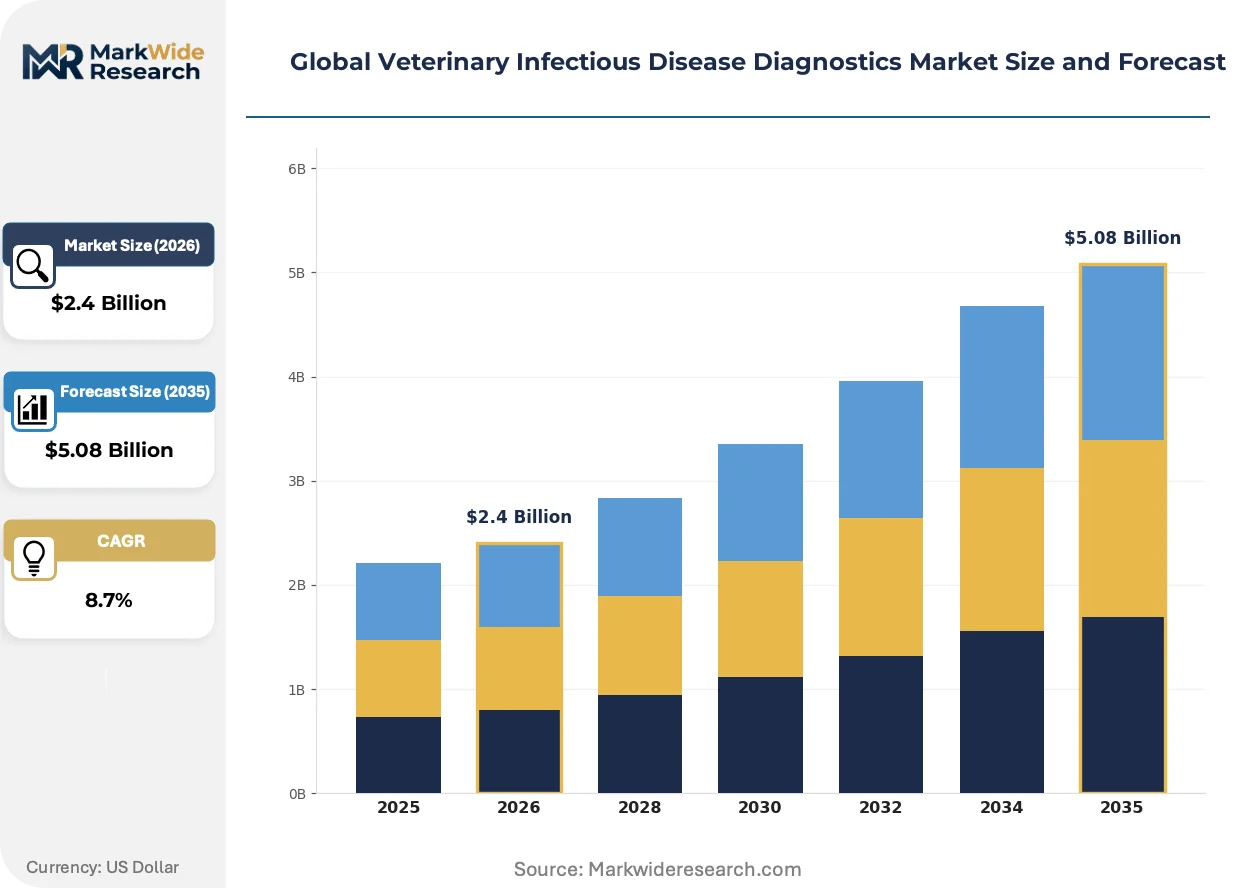
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ELISA Kits, PCR Assays, Lateral Flow Tests, Immunofluorescence Assays, Hemagglutination Assays Application: Canine Diseases, Feline Disorders, Livestock Infection Testing, Avian Pathogen Detection, Aquatic Animal Diagnostics End User: Veterinary Clinics, Diagnostic Laboratories, Research Institutes, Animal Health Companies, Zoos Technology: Real-Time PCR, Microarray, Immunochromatography, Next-Generation Sequencing, Flow Cytometry |
| Companies Covered | IDEXX Laboratories Inc., Zoetis Services LLC, Thermo Fisher Scientific Inc., bioMérieux SA, Virbac, Neogen Corporation, Bio-Rad Laboratories Inc., IDvet, Antech Diagnostics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Veterinary Infectious Disease Diagnostics Market Shifts & Advancements
Multiplexed nucleic acid detection and cloud-connected instrumentation are compressing assay development cycles while expanding pathogen surveillance from targeted screening to broad respiratory and enteric panel approaches.
CRISPR-based diagnostic chemistry is decomposing traditional PCR amplification requirements for veterinary point-of-care applications. Companion animal clinics in the United States are piloting lateral flow readers with nucleic acid detection capabilities. This technology convergence is collapsing the cost differential between reference laboratory accuracy and field-deployable convenience.
REACH and RoHS substance restrictions in the European Union are forcing reagent reformulation for veterinary ELISA kits containing hazardous conjugates. Manufacturers serving EU member states are redesigning detection antibodies and enzyme labels to maintain CE marking compliance. The livestock diagnostics segment bears the highest reformulation burden due to kit volume scale.
Subscription-based assay access contracts are replacing capital-intensive instrument purchases among mid-sized veterinary practice groups. Reference laboratory networks in Germany and France are unbundling equipment placement from per-test pricing, shifting risk to diagnostic providers. This model is concentrating fastest in companion animal infectious disease screening where test menu breadth determines clinic loyalty.
Global Veterinary Infectious Disease Diagnostics Market Segmentation
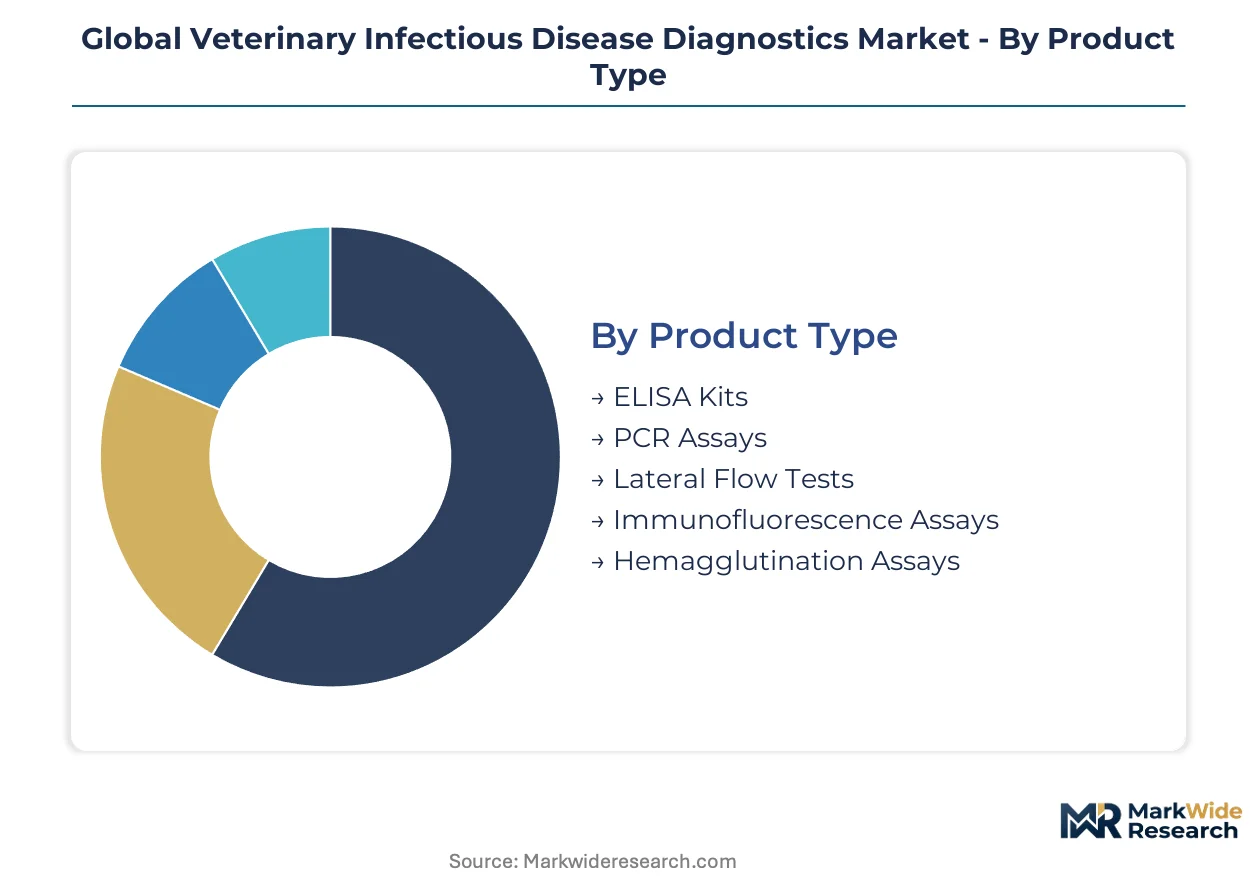
Veterinary diagnostic procurement splits across distinct channel economics. Reference laboratories favor high-throughput automation while field-deployable formats serve decentralized companion animal practice networks.
Product Type:
Channel economics concentrate ELISA and PCR volumes through reference laboratory networks while lateral flow and point-of-care formats penetrate clinic direct purchasing.
- ELISA Kits:Enzyme-linked immunosorbent assay platforms detect antibodies or antigens in serum and tissue samples with established protocols for brucellosis and tuberculosis screening. Herd health management programs across the United States and EU member states sustain bulk procurement contracts for livestock serological surveillance.
- PCR Assays:Polymerase chain reaction systems amplify nucleic acid targets with analytical sensitivity reaching 10–100 copies per reaction for quantitative pathogen detection. Veterinary reference laboratories in Germany and France are replacing legacy culture methods with TaqMan probe-based panels for bovine and porcine respiratory pathogen screening.
- Lateral Flow Tests:Immunochromatographic strip assays deliver qualitative results within 15 minutes for field-deployable canine parvovirus and feline leukemia screening.
- Immunofluorescence Assays:Fluorescent antibody techniques visualize viral antigens in tissue sections for confirmatory rabies and avian influenza diagnostics.
- Hemagglutination Assays:Red blood cell agglutination methods remain cost-effective for Newcastle disease and influenza A subtyping in poultry operations.
By volume, ELISA Kits lead. By growth pace, PCR Assays is ahead.
Application:
Species-specific testing intensity correlates with commercial animal value and regulatory movement restrictions.
- Livestock Infection Testing:Bovine and porcine disease panels support interstate commerce certification under USDA APHIS mandates and EU Green Deal surveillance requirements. Export-oriented operations in the United States, Germany, and Denmark drive recurring demand for validated tuberculosis and brucellosis assay menus.
- Canine Diseases:Companion animal infectious disease screening encompasses parvovirus, distemper, and Lyme disease detection through clinic-based rapid test platforms. United States veterinary practice groups are consolidating procurement through subscription-based assay access contracts that bundle respiratory and tick-borne panels.
- Feline Disorders:Feline leukemia virus and immunodeficiency virus testing concentrates in high-volume spay-neuter clinic networks.
- Avian Pathogen Detection:Avian influenza and Newcastle disease surveillance operates under OIE Terrestrial Animal Health Code harmonization for trade certification.
- Aquatic Animal Diagnostics:Shrimp and finfish pathogen panels address white spot syndrome and infectious salmon anemia in aquaculture export zones.
Livestock Infection Testing commands the highest absolute spend. Canine Diseases is climbing the fastest as pet insurance penetration expands diagnostic utilization.
End User:
Customer procurement sophistication spans from CLIA-waived point-of-care standards to GLP-validated research protocols.
- Diagnostic Laboratories:Centralized reference networks process high-throughput serological and molecular panels for commercial livestock operations and regulatory compliance. USDA-backed animal health programs in the United States channel substantial kit procurement through state veterinary diagnostic laboratory systems.
- Veterinary Clinics:Companion animal practice groups prioritize rapid turnaround infectious disease screening with integrated practice management software connectivity. CLIA-waived point-of-care standards are compressing turnaround times from days to hours for canine and feline pathogen detection.
- Research Institutes:Academic veterinary medical centers drive assay development for emerging pathogen characterization and antimicrobial resistance surveillance.
- Animal Health Companies:Integrated vaccine-diagnostic portfolios leverage in-house testing for product efficacy and safety validation.
- Zoos:Exotic animal collections require specialized panels for tuberculosis screening and herpesvirus monitoring in conservation breeding programs.
Diagnostic Laboratories dominate absolute throughput. Veterinary Clinics is expanding most quickly as point-of-care molecular platforms penetrate mid-sized practice groups.
Technology:
Technology selection balances analytical sensitivity requirements against capital investment and technical staffing constraints.
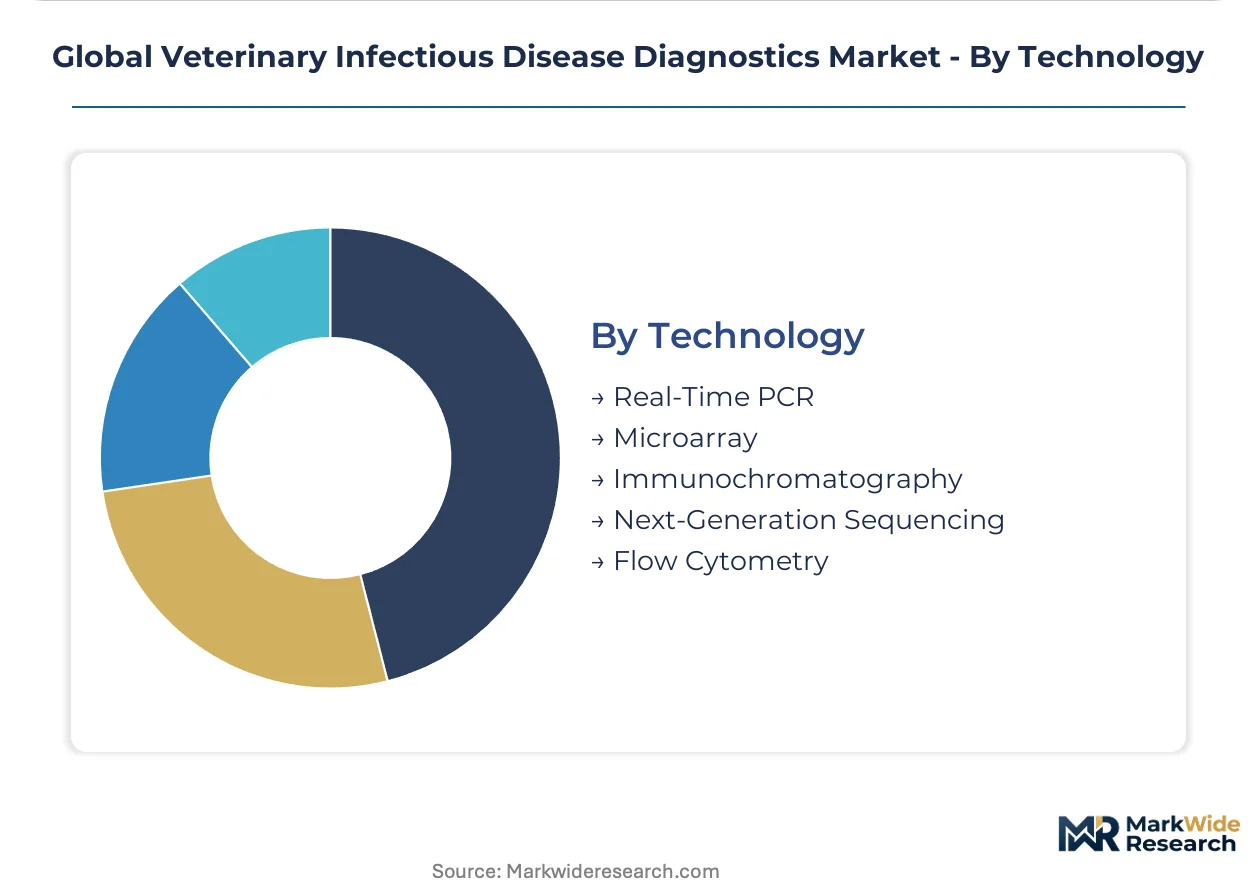
- Real-Time PCR:Quantitative nucleic acid amplification with fluorogenic probe detection achieves pathogen quantification for antimicrobial stewardship compliance. Veterinary reference laboratories are displacing legacy culture methods with automated extraction and qPCR workflows for bovine respiratory disease and porcine reproductive syndrome panels.
- Next-Generation Sequencing:Massively parallel sequencing platforms enable whole-genome characterization of African swine fever and avian influenza strains without prior target knowledge. National veterinary institutes in Germany and the Netherlands are deploying NGS for outbreak source attribution and transmission chain reconstruction.
- Microarray:Solid-phase nucleic acid hybridization supports multiplexed respiratory pathogen detection in research settings.
- Immunochromatography:Lateral flow antibody-antigen binding generates visual results without instrumentation for field-deployable screening.
- Flow Cytometry:Fluorescence-activated cell sorting quantifies immune cell populations for vaccine response evaluation in research applications.
Real-Time PCR leads in commercial deployment. Next-Generation Sequencing shows the steepest expansion trajectory as surveillance programs adopt genomic epidemiology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export certification requirements and livestock movement regulations create divergent procurement intensities across major veterinary diagnostic markets. The United States maintains the deepest reference laboratory infrastructure, while Germany and China scale molecular capacity for trade-compliant pathogen surveillance.
United States
USDA APHIS interstate movement mandates drive recurring kit demand for brucellosis and tuberculosis screening among cattle exporters. The National Animal Health Laboratory Network channels federal funding into state diagnostic laboratory capacity expansion. Kansas State Veterinary Diagnostic Laboratory and Cornell University Animal Health Diagnostic Center anchor high-throughput PCR workflows for bovine respiratory disease panels.
Germany
Friedrich-Loeffler-Institut operates the EU's largest veterinary reference laboratory network for African swine fever and avian influenza genomic surveillance. EU Green Deal Farm-to-Fork Strategy implementation tightens pathogen monitoring obligations for member state livestock operations. Bavarian and Lower Saxony veterinary authorities coordinate regional laboratory accreditation for export certification to third-country markets.
China
Foot-and-mouth disease eradication programs concentrate national laboratory investment in Lanzhou and Harbin veterinary research institutes. The Ministry of Agriculture and Rural Affairs mandates African swine fever screening for all interstate pig movements. Yangtze River Delta and Pearl River Delta clusters host the densest commercial diagnostic laboratory networks serving integrated pork production systems.
India
Peste des petits ruminants control campaigns expand state veterinary laboratory capacity for small ruminant serological surveillance. The Indian Council of Agricultural Research funds molecular diagnostic platform deployment at regional veterinary universities. Karnataka and Maharashtra veterinary universities operate reference laboratories for southern and western India livestock export zones.
Brazil
Beef export certification to China and EU markets requires validated bovine tuberculosis and brucellosis testing through MAPA-accredited laboratories. Minas Gerais and São Paulo veterinary diagnostic networks process the highest livestock sample volumes for international trade compliance. Embrapa Beef Cattle maintains national reference standards for molecular pathogen detection in export-oriented herds.
Global Veterinary Infectious Disease Diagnostics Market Competitive Landscape
Listed leaders compete with private specialists across reference laboratory networks and point-of-care distribution channels. The market structures around three tiers: integrated animal health conglomerates with vaccine-diagnostic bundles, standalone diagnostic platform specialists, and regional reagent suppliers serving national veterinary laboratory systems. Competitive positioning hinges on CLIA waiver attainment for clinic-deployable formats and USDA/FDA validation hold for livestock export assay menus. M&A activity concentrates on PCR platform acquisitions and reference laboratory network consolidation.
Within the integrated conglomerate tier, IDEXX Laboratories Inc. and Zoetis Services LLC exemplify divergent channel strategies—one anchoring companion animal clinic penetration through point-of-care platforms, the other bundling livestock diagnostics with vaccine portfolios. Thermo Fisher Scientific Inc. occupies a position bridging human clinical and veterinary applications through Applied Biosystems PCR chemistry franchises. These three entities represent the dominant competitive archetypes shaping procurement patterns across reference laboratory and field-deployable segments.
| Leading Market Players |
|---|
| IDEXX Laboratories Inc. |
| Zoetis Services LLC |
| Thermo Fisher Scientific Inc. |
| bioMérieux SA |
| Virbac |
| Neogen Corporation |
| Bio-Rad Laboratories Inc. |
| IDvet |
| Antech Diagnostics Inc. |
| Others |
Supply & Pricing Matrix
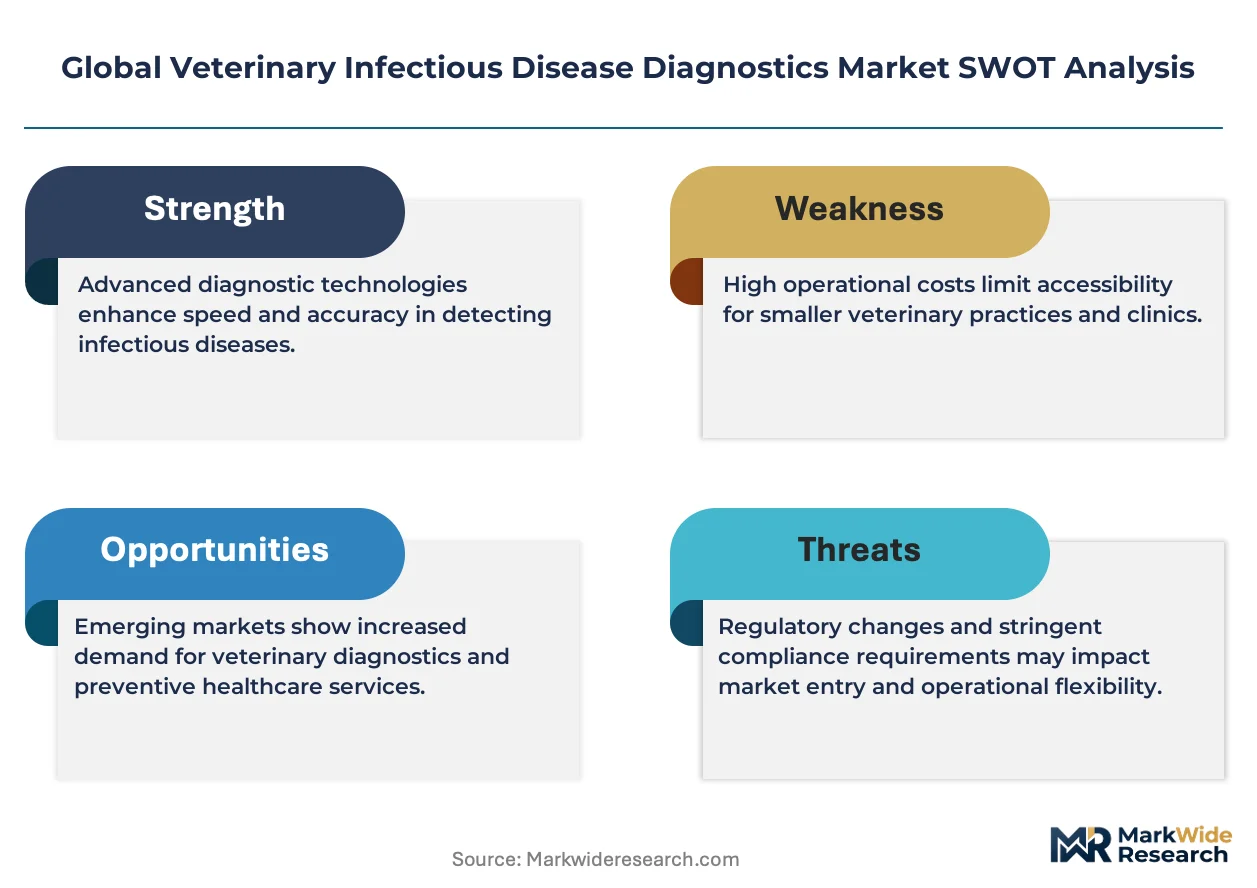
Taq polymerase and probe chemistry substitution for legacy enzyme conjugates is simultaneously shifting procurement geography toward specialized biochemical suppliers in Germany and the United States while compressing assay kit margins across veterinary reference laboratory networks.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the veterinary diagnostics market. Price differentiation rests on USDA validation tier and CLIA waiver status, with subscription-based assay access contracts gaining share among mid-sized practice groups. Cost compression in the economy tier is intensifying because Taq polymerase supply constraints expose manufacturers to input allocation volatility. Livestock export operations demonstrate the lowest price sensitivity due to regulatory compliance mandates, while independent companion animal clinics exhibit acute sensitivity to per-test economics.
Supply Chain Analysis
Strategic stockpiling of PCR reagents dominates inventory strategy among veterinary reference laboratories confronting Taq polymerase supply concentration. Manufacturing concentrates in Germany, the United States, and China, with probe synthesis anchored in specialized biochemical suppliers near Frankfurt and Boston. Raw material dependencies include Taq polymerase, fluorogenic probe chemistries, and ELISA plate substrates. Single-source vulnerability in thermostable enzyme production creates structural exposure. Distribution runs through state veterinary diagnostic laboratory networks and integrated animal health conglomerates with captive logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in point-of-care molecular platforms where CLIA waiver attainment creates defendable niches against reference laboratory incumbents. Companion animal practice consolidation generates demand for integrated practice management connectivity that legacy platform architectures under-serve.
For Market Incumbents: Shield reference laboratory market share through backward integration into probe chemistry production, reducing exposure to Taq polymerase allocation constraints. Prioritize CLIA waiver expansion for field-deployable PCR formats to preempt emerging entrant capture of mid-sized veterinary practice groups consolidating procurement through subscription contracts. For New Entrants and Emerging Players: Cloud-connected instrument data layers represent the most penetrable service gap where incumbents under-serve practice management software integration demands. Target veterinary clinic networks in India and Brazil where national laboratory expansion programs lack established platform loyalty. Pursue regulatory validation partnerships with Friedrich-Loeffler-Institut or Kansas State Veterinary Diagnostic Laboratory to accelerate assay menu credibility. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed reference laboratory networks in Germany and France pursuing geographic consolidation. Five-to-ten-year viability hinges on antimicrobial stewardship compliance integration with infectious disease panels. Monitor EU Green Deal Farm-to-Fork Strategy enforcement intensity as inflection signal for livestock diagnostic kit procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA Waiver Expansion | Unlocks companion animal clinic channel penetration against reference laboratory competition. |
| Probe Chemistry Backward Integration | Reduces Taq polymerase supply concentration risk for high-volume assay manufacturers. |
| Cloud Platform Integration | Addresses practice management software connectivity gaps delaying point-of-care adoption. |
| Reference Laboratory Acquisition | Consolidates state network capacity under USDA-backed animal health program contracts. |
| NGS Surveillance Subscription Launch | Captures African swine fever and avian influenza genomic epidemiology demand from national veterinary institutes. |
Research Methodology
A standing panel of veterinary diagnostic laboratory directors, ELISA kit procurement managers, reference laboratory network executives, and companion animal clinic practice owners provided ongoing calibration across primary interview rounds. Secondary validation drew from USDA APHIS regulatory filings, OIE Terrestrial Animal Health Code documentation, EU Green Deal implementation reports, and state veterinary diagnostic laboratory annual procurement disclosures. Bottom-up assay volume estimates triangulated against top-down market size benchmarks.
Consistency checks validated segment-level outputs against external reference points including Friedrich-Loeffler-Institut surveillance program disclosures and National Animal Health Laboratory Network capacity expansion announcements. The analytical framework modeled product type, application species, end-user channel, and technology platform dimensions across the projection horizon. CAGRs derived from logistic adoption curves for molecular technology substitution and regulatory mandate implementation schedules. Forecast inputs incorporated EU Farm-to-Fork Strategy enforcement timelines and USDA interstate movement rule expansion scenarios.
Underlying assumptions cover Taq polymerase supply stabilization, CLIA waiver processing timelines, and reference laboratory network consolidation pace, with deviation risk concentrated in antimicrobial resistance surveillance framework convergence between human and veterinary health authorities. Revision becomes warranted when EU member state pathogen surveillance mandate enforcement crosses acceleration thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
Infectious Disease Treatments Market
Infectious Disease
Japanese Encephalitis Market
Infectious Disease
Mycobacterium Infections Treatment Market
Infectious Disease
Bronchitis Market
Infectious Disease
Viral Gastroenteritis Market
Infectious Disease
Q Fever Market
Infectious Disease
Viral Hemorrhagic Fever Market
Infectious Disease
Herpes Infection Treatment Market
Infectious Disease
Global Herpes Zoster Infection Treatment Market
Infectious Disease
Burkholderia Infections Market
Infectious Disease
Global Infectious Disease Therapeutics Market
Infectious Disease
Acute Viral Rhinosinusitis Treatment Market
Infectious Disease
Italy Infectious Disease in-Vitro Diagnostics Market
Infectious Disease
Chronic Hepatitis B (CHB) Market
Infectious Disease
Infectious Disease Molecular Diagnostics Market
Infectious Disease
Retropharyngeal Abscess Market