
 India Cold Chain Logistics Market | 2026-2036
India Cold Chain Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
India Cold Chain Logistics Market Outlook
Refrigerated warehousing revenue is rewriting profit structures across the India cold chain sector. Snowman Logistics Ltd leverages its pan-India network of temperature-controlled facilities to anchor pharmaceutical and dairy corridors. Coldman Warehousing & Distribution sustains margins through specialized frozen-food distribution across South and West India. DHL Supply Chain India competes on integrated end-to-end visibility platforms that merge warehousing with last-mile refrigerated delivery.
India cold chain logistics encompasses the temperature-controlled movement and storage of perishable goods through refrigerated transport, insulated containers, and monitored environments maintained between below 0°C and 25°C depending on product sensitivity. The system preserves biochemical stability across pharmaceuticals, fresh produce, and processed foods through continuous cold integrity from origin to consumption. Warehousing commands the dominant margin pool among service types, as ambient-to-refrigerated conversion of existing godown stock requires capital-intensive retrofitting that limits new entrants. The 0°C to 5°C band carries structural premiums due to pharmaceutical vaccine storage compliance and high-value dairy distribution, while below 0°C frozen segments face margin compression from energy cost volatility. Food & Beverage end users generate the highest volume throughput, though Pharmaceuticals delivers superior yield per pallet given temperature-documentation requirements and liability exposure.
FSSAI mandates HACCP-aligned temperature logging for all perishable food movement, while CDSCO enforces GDP (Good Distribution Practice) standards for pharmaceutical cold chains that require validated equipment qualification and continuous monitoring. The PLI scheme for food processing incentivizes integrated cold storage investments, creating regulatory pull for backward integration into captive warehousing by large food processors. Stakeholders must weigh energy transition costs against compliance timelines as grid reliability and renewable-powered refrigeration become decisive variables in site selection and operating cost structures.
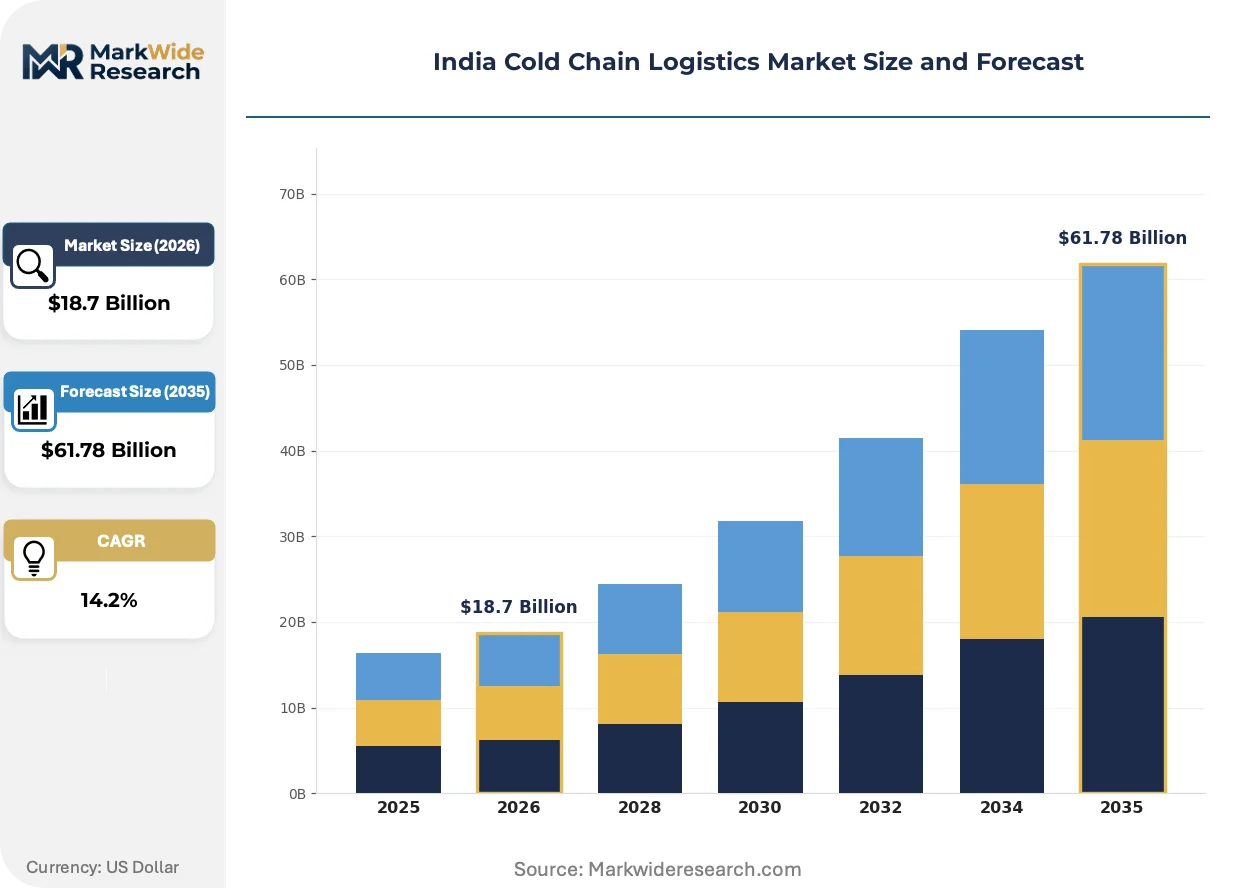
Market Dynamics
PLI scheme disbursements for food processing infrastructure are concentrating capital deployment around multi-commodity cold storage clusters, fundamentally restructuring how refrigerated warehousing capacity scales across India's agricultural belts and pharmaceutical corridors.
Growth Catalysts
- FSSAI temperature-compliance mandates:HACCP-aligned logging requirements for perishable food movement are forcing ambient godown retrofits, expanding the addressable market for monitored cold storage.
- Pharmaceutical corridor expansion:CDSCO's GDP standards for vaccine distribution are pulling validated refrigerated infrastructure into tier-2 cities previously served by ambient transport.
- Grid-tied solar refrigeration:Falling photovoltaic costs combined with unreliable grid supply are enabling distributed cold storage deployment in rural Maharashtra and Gujarat without diesel dependency.
Market Restraints
- Refrigerant input volatility:Hydrofluorocarbon phase-down schedules under India's cooling action plan are compressing margins for existing mechanical compression fleets facing retrofit costs.
- Land concentration in peri-urban zones:Cold storage site selection clusters around Mumbai, Ahmedabad, and Bengaluru peripheries, creating bidding wars for plots with reliable power infrastructure.
- Validated equipment scarcity:CDSCO qualification requirements for pharmaceutical-grade sensors and backup systems limit supplier pools to import-dependent channels.
Strategic Opportunities
- North-east corridor penetration:Assam and Meghalaya horticulture belts remain drastically under-served by temperature-controlled distribution, offering first-mover warehouse positioning.
- Blockchain-IoT convergence:Immutable temperature documentation layered on cellular-tracked reefer containers creates audit-ready pharmaceutical chain-of-custody records.
- Dairy processor backward integration:Amul-patterned cooperatives are captive-building chilled milk collection centers, opening equipment and monitoring service contracts.
Industry Challenges
- Certified technician scarcity:FSSAI-mandated cold chain supervisor qualifications outpace vocational training output, inflating wage costs for warehouse operations.
- Multi-temperature zone integration:Single facilities must now maintain 0°C to 5°C pharmaceutical vaults alongside -25°C frozen zones and 15°C ripening chambers, complicating HVAC design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Cold Chain Logistics Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Distribution, Packaging Temperature Range: Below 0°C, 0°C to 5°C, 5°C to 15°C, 15°C to 25°C End User: Food & Beverage, Pharmaceuticals, Chemicals, Biotech Technology: Refrigerated Trucks, Cold Storage, Insulated Containers, Monitoring Systems |
| Companies Covered | DHL Supply Chain India, Coldman Warehousing & Distribution, Snowman Logistics Ltd, Indicold, Coldrush Logistics, ColdEx Logistics Pvt Ltd, Mahindra Logistics Ltd, Cold Care Group, TCI Express Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Cold Chain Logistics Market Strategic Shifts
Digital twin architecture is virtualizing how cold chain operators simulate thermal load scenarios before capital deployment, compressing design-validation cycles from months to weeks.
IoT-enabled warehouse management systems are virtualizing inventory visibility across distributed cold storage networks. Pharmaceutical distributors in Hyderabad and Pune are piloting these platforms to merge real-time temperature telemetry with automated quarantine triggers. The technology is virtualizing compliance documentation that previously required manual logger downloads and spreadsheet reconciliation.
FSSAI's 2022 amendment to the Food Safety and Standards Act mandates continuous temperature monitoring with tamper-evident data storage for all perishable transport exceeding 150 kilometers. Cold chain operators are responding by retrofitting reefer trucks with cellular-enabled data loggers that auto-upload to central dashboards. Dairy and frozen food distributors face the steepest compliance curves given their high trip frequencies and fragmented fleet ownership.
Direct procurement from farm-gate collection centers is displacing traditional mandi-based aggregation for premium produce exporters. Grape and pomegranate shippers in Nashik and Sangli now contract chilled transport straight from village packhouses to Jawaharlal Nehru Port. This channel compression eliminates double-handling heat spikes and reduces transit time by 18 to 24 hours for EU-bound shipments.
India Cold Chain Logistics Market Segmentation
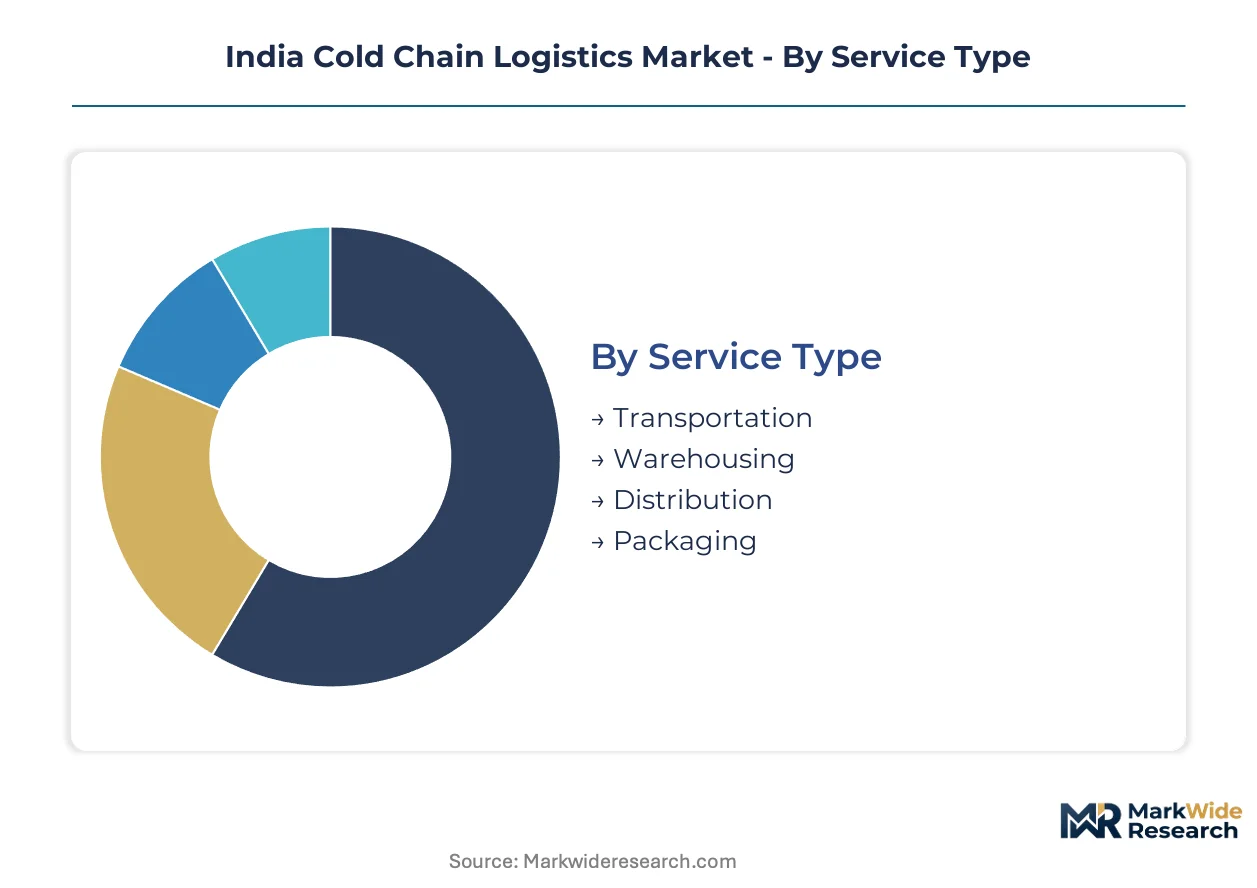
Cold chain logistics demands precise segment alignment between thermal requirements and service capabilities. Each category reveals distinct margin profiles and capital intensity patterns that shape competitive positioning across India's temperature-controlled infrastructure.
Service Type:
After-sales service intensity varies sharply across service types, with warehousing requiring continuous equipment maintenance and temperature validation versus transportation's episodic repair cycles.
- Transportation:Refrigerated vehicle fleets and reefer trucks maintain cold integrity through mobile mechanical compression or cryogenic systems. Pharmaceutical distributors in Maharashtra and Gujarat are expanding validated reefer coverage into tier-2 cities under CDSCO GDP mandates, pulling fleet operators toward documented temperature logging.
- Warehousing:Temperature-controlled facilities with multi-zone HVAC systems dominate margin pools due to capital-intensive retrofitting barriers. Conversion of ambient godowns to monitored cold storage requires FSSAI-aligned HACCP compliance and continuous backup power systems.
- Distribution:Consolidated last-mile delivery networks merge cross-docking with temperature-maintained handoffs. Dairy cooperatives in Karnataka leverage captive distribution to reduce thermal breaks between processing plants and retail endpoints.
- Packaging:Insulated shippers, gel packs, and phase-change materials provide passive thermal protection for short-haul pharmaceutical samples. Biotech exporters near Hyderabad and Bengaluru drive demand for validated packaging qualification documentation.
By volume, Transportation leads. By growth pace, Warehousing is ahead.
Temperature Range:
Cost tier stratification separates premium pharmaceutical-grade zones from commodity frozen storage, with energy input costs driving divergent margin structures.
- Below 0°C:Frozen storage at -18°C to -25°C preserves meat, seafood, and ice cream through mechanical compression or ammonia-based systems. Frozen food processors in Gujarat face margin compression from refrigerant phase-down costs under India's cooling action plan.
- 0°C to 5°C:Chilled environments maintain vaccine stability and dairy freshness with precise humidity control. This band commands structural premiums due to CDSCO validation requirements and pharmaceutical liability exposure.
- 5°C to 15°C:Cool storage suits fresh produce ripening and chocolate confectionery without freezing damage. Nashik grape exporters use controlled-atmosphere chambers in this range to extend shelf life for EU-bound shipments.
- 15°C to 25°C:Ambient-to-cool transition zones handle pharmaceuticals and chemicals requiring protection from heat spikes rather than active refrigeration. Generic drug distributors in Baddi and Ahmedabad utilize these zones for cost-sensitive inventory.
By margin yield, 0°C to 5°C leads. By volume throughput, Below 0°C is expanding most quickly.
End User:
Application-specific compliance requirements fragment service provider capabilities, with pharmaceutical documentation demands creating the steepest capability barriers.
- Food & Beverage:Perishable supply chains spanning dairy, meat, produce, and processed foods generate the highest pallet volume. FSSAI temperature-logging mandates for transport exceeding 150 kilometers are forcing fleet retrofits across Maharashtra and Karnataka corridors.
- Pharmaceuticals:Vaccine, insulin, and biologic distribution requires GDP-validated equipment qualification and continuous monitoring. CDSCO enforcement is pulling compliant infrastructure into tier-2 cities previously served by ambient transport.
- Chemicals:Temperature-sensitive industrial and agricultural chemicals demand controlled storage without pharmaceutical-grade validation. Gujarat's chemical manufacturing clusters near Ahmedabad and Vadodara anchor regional demand.
- Biotech:Cell cultures, reagents, and clinical trial materials require ultra-stable environments with minimal temperature excursion tolerance. Hyderabad and Bengaluru biotech corridors drive specialized cold storage investment.
By revenue concentration, Pharmaceuticals leads. By volume scale, Food & Beverage is climbing the fastest.
Technology:
Supply concentration in import-dependent equipment categories creates procurement bottlenecks, particularly for pharmaceutical-grade monitoring systems.
- Refrigerated Trucks:Mobile cold chain units with mechanical compression or cryogenic cooling enable point-to-point temperature maintenance. Fleet operators are retrofitting cellular-enabled data loggers to meet FSSAI's tamper-evident documentation requirements.
- Cold Storage:Fixed-site warehouses with multi-zone HVAC and ammonia or CO2 refrigeration systems form the infrastructure backbone. Grid-tied solar refrigeration is enabling distributed deployment in rural Maharashtra without diesel dependency.
- Insulated Containers:Passive thermal protection using polyurethane panels and phase-change materials supports short-haul and last-mile delivery. Dairy collection centers in Gujarat and Karnataka deploy these for farm-gate milk aggregation.
- Monitoring Systems:IoT-enabled sensors, data loggers, and blockchain-anchored documentation platforms virtualize compliance record-keeping. Pharmaceutical distributors in Pune pilot automated quarantine triggers tied to real-time temperature telemetry.
By installed base, Cold Storage leads. By investment velocity, Monitoring Systems is gaining share fastest.
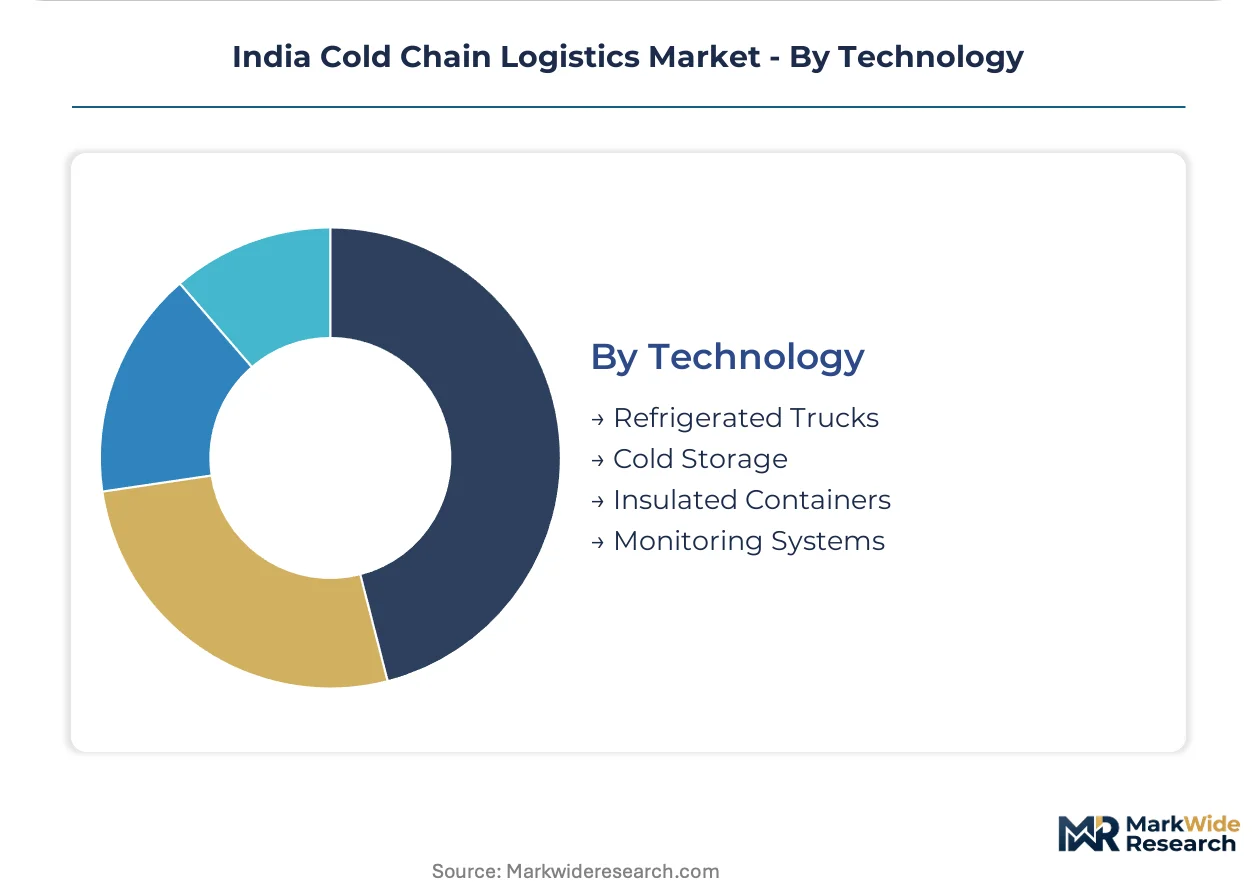
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across Indian states. Gujarat and Maharashtra buyers absorb premium pricing for pharmaceutical-grade infrastructure, while Rajasthan and Madhya Pradesh markets remain acutely price-sensitive on frozen food logistics.
Maharashtra
Nashik grape exporters and Mumbai pharmaceutical distributors drive refrigerated warehousing demand. FSSAI mandates HACCP-aligned temperature logging for perishable transport exceeding 150 kilometers, forcing fleet retrofits across the Mumbai-Pune corridor. The Jawaharlal Nehru Port cold storage cluster anchors EU-bound produce exports with direct farm-gate procurement bypassing traditional mandi aggregation.
Gujarat
Dairy cooperatives and frozen food processors generate concentrated throughput in the Ahmedabad-Vadodara belt. The PLI scheme for food processing incentivizes integrated cold storage investments, pulling capital toward multi-commodity clusters near agricultural belts. Grid-tied solar refrigeration enables distributed deployment in rural Saurashtra without diesel dependency.
Karnataka
Bengaluru biotech corridors and Hassan dairy belts sustain differentiated demand profiles. CDSCO GDP standards for vaccine distribution pull validated infrastructure into tier-2 cities previously served by ambient transport. The state builds multi-commodity cold storage clusters near pharmaceutical manufacturing zones in Peenya and Electronic City.
Telangana
Hyderabad pharmaceutical distributors pilot IoT-enabled warehouse management systems merging real-time temperature telemetry with automated quarantine triggers. FSSAI's 2022 Food Safety and Standards Act amendments mandate continuous monitoring with tamper-evident data storage. The Genome Valley biotech cluster drives specialized cold storage investment for cell cultures and clinical trial materials.
Tamil Nadu
Chennai port-centric seafood exporters and Coimbatore dairy processors anchor regional demand. Certified technician scarcity for FSSAI-mandated cold chain supervisor qualifications outpaces vocational training output, inflating wage costs for warehouse operations. The state concentrates peri-urban cold storage site selection around Chennai periphery with reliable power infrastructure.
India Cold Chain Logistics Market Competitive Environment
Capability concentration sits with specialized temperature-control operators; scale advantage sits with diversified logistics conglomerates. The market structures around three tiers: pharmaceutical-validated specialists, multi-temperature food logistics providers, and integrated supply chain platforms. Strategic moves concentrate on backward integration into captive warehousing and blockchain-anchored documentation partnerships.
Within the pharmaceutical-validated tier, Snowman Logistics Ltd and Coldman Warehousing & Distribution occupy anchor positions. DHL Supply Chain India represents the integrated platform archetype, merging warehousing with last-mile refrigerated delivery networks. These three exemplify divergent competitive vectors: pan-India network coverage, regional frozen-food specialization, and end-to-end visibility platforms respectively.
| Leading Market Players |
|---|
| DHL Supply Chain India |
| Coldman Warehousing & Distribution |
| Snowman Logistics Ltd |
| Indicold |
| Coldrush Logistics |
| ColdEx Logistics Pvt Ltd |
| Mahindra Logistics Ltd |
| Cold Care Group |
| TCI Express Ltd |
| Others |
Value Chain & Pricing Dynamics
Refrigerant phase-down schedules under India's cooling action plan compress margins across mechanical compression fleets, forcing tiered pricing spreads between ammonia-retrofitted facilities and legacy HFC-dependent operations while reshaping procurement toward validated equipment channels.
Pricing Analysis
After-sales service contracts for temperature validation and continuous monitoring equipment drive lifetime value capture. Three-tier pricing structure across pharmaceutical-grade, F&B-compliant, and ambient-converted facilities separates CDSCO-validated vaults from HACCP-aligned food storage and basic retrofit godowns. Price differentiation rests on certification grade and backup power redundancy. Pricing pressure stems from energy cost volatility in diesel-dependent rural deployments. Generic drug distributors in Baddi exhibit acute price sensitivity; vaccine exporters absorb premium positioning.
Supply Chain Analysis
Contract manufacturing concentration for pharmaceutical-grade sensors and GDP-validated data loggers sits with German and Japanese precision equipment suppliers, with domestic assembly emerging in Pune and Bengaluru electronics corridors. Critical component dependencies include ammonia compressors, phase-change materials, and cellular-enabled telemetry modules. Supply chain risk centers on single-source vulnerability for CDSCO-qualified backup systems. Distribution runs through integrated logistics platforms merging warehousing with captive fleet operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among dairy cooperatives and pharmaceutical distributors scaling backward into captive cold storage, fragmenting spot-market demand for third-party warehousing.
For Market Incumbents: Insulate margin pools by locking in multi-year temperature-compliance contracts with FSSAI-mandated HACCP documentation, while accelerating ammonia refrigeration retrofits ahead of HFC phase-down deadlines. Grid-tied solar installations in Maharashtra and Gujarat anchor defensible cost positions against diesel-dependent competitors. For New Entrants and Emerging Players: Assam and Meghalaya horticulture corridors offer first-mover warehouse positioning with minimal validated competition. Target pharmaceutical distribution in tier-2 cities where CDSCO GDP enforcement is pulling compliant infrastructure into previously ambient-served markets. Lead with blockchain-anchored temperature documentation as audit-ready differentiation. For Investors and Strategic Acquirers: The market sits at a regulatory-acceleration phase that favors vertically integrated cold storage operators with captive renewable energy assets. Long-term viability hinges on backward integration into farm-gate collection centers and last-mile fleet ownership. Monitor FSSAI enforcement intensity in South India as inflection signal for compliance-driven capacity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Farm-Gate Collection | Amul-patterned cooperatives in Gujarat reduce thermal breaks and capture upstream margin pools. |
| Ammonia Refrigeration Retrofit Program | HFC phase-down compliance under India's cooling action plan protects operating cost structures. |
| Grid-Tied Solar Cold Storage Deployment | Maharashtra and Gujarat rural installations bypass diesel dependency and grid reliability constraints. |
| Blockchain-IoT Documentation Partnership | Hyderabad pharmaceutical distributors pilot immutable temperature records for CDSCO audit readiness. |
| Multi-Commodity Cluster Expansion | Karnataka builds integrated capacity near Peenya pharmaceutical zones and Hassan dairy belts. |
Study Parameters
The analysis maps refrigerated warehousing, transportation fleets, packaging solutions, and monitoring systems, each validated through cold chain operations directors, FSSAI compliance officers, pharmaceutical distribution managers, and dairy cooperative procurement leads. Primary interviews with warehouse facility managers and fleet operators combined with secondary validation from CDSCO guidance documents, FSSAI notification archives, PLI scheme disbursement records, and state-level agricultural export data. Bottom-up capacity assessments triangulated against top-down sectoral spending estimates.
Assumptions held FSSAI enforcement timelines and PLI scheme continuation fixed, while refrigerant cost trajectories and grid reliability patterns varied across scenarios. Segmentation dimensions modeled include service type, temperature band, end-use vertical, and technology platform, with regional adoption patterns and regulatory compliance tiers as cross-cutting variables. CAGRs derived from installed base expansion rates and revenue-per-pallet benchmarks across the projection horizon. Industry-specific inputs include pharmaceutical corridor penetration curves and solar refrigeration deployment economics.
The forecast holds incumbent behavior within observed patterns; aggressive moves by integrated logistics conglomerates or renewable-energy-backed entrants would shift outcomes. Quarterly review of CDSCO enforcement actions, FSSAI amendment notifications, and PLI scheme beneficiary announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Asia Pacific Event Logistics Market
Logistics and Shipping
Air Freight Software Market
Logistics and Shipping
Asia-Pacific Courier Market
Logistics and Shipping
North America Sea Freight Forwarding Market
Logistics and Shipping
Uruguay Freight and Logistics Market
Logistics and Shipping
Estonia Freight and Logistics Market
Logistics and Shipping
Indonesia Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
GCC Air Freight and Logistics Market
Logistics and Shipping
Indonesia Freight and Logistics Market
Logistics and Shipping
ASEAN Domestic Courier Market
Logistics and Shipping
Fleet of Containers Market
Logistics and Shipping
Air Cargo Container Market
Logistics and Shipping
US Courier, Express, and Parcel Market
Logistics and Shipping
Asia Pacific Freight and Logistics Market
Logistics and Shipping
Australia Freight Forwarding Market
Logistics and Shipping
Egypt 3PL Market