
 Brush and Dauber Caps Market | 2026-2036
Brush and Dauber Caps Market Size, Share, and Industry Trends Forecast 2026-2036
Brush and Dauber Caps Market Outlook
Pharmaceutical-grade sealing performance is bifurcating the Brush and Dauber Caps Market into premium specification tiers and commodity alternatives. AptarGroup Inc. leverages its precision molding expertise to dominate high-barrier segments for solvent-sensitive formulations. Silgan Holdings Inc. anchors North American supply through integrated metal-plastic hybrid production platforms. Berry Global Inc. competes on scale across multi-cavity injection lines serving household and industrial buyers simultaneously.
Brush and dauber caps are threaded or snap-fit closures integrating filament brushes, foam daubers, or spray actuators, typically molded from polypropylene or HDPE with internal seals rated for chemical resistance; they function as integrated dispensing tools that eliminate separate applicator procurement and reduce product contamination in field or factory use. Plastic material formulations lead volume due to cost-efficient injection molding and color customization flexibility, while metal-reinforced composite variants capture margin pools in industrial coatings requiring torque stability and repeated use cycles. Dauber caps represent the fastest-growing product type as water-based stain and adhesive brands adopt mess-reducing applicator formats for consumer convenience.
FDA material contact regulations and EPA volatile organic compound emission standards shape permissible resin chemistries and liner compositions for solvent-bearing products distributed in the United States. REACH substance restrictions and the EU Packaging and Packaging Waste Directive drive substitution of certain plasticizers and mandate recyclability disclosures for closures sold into European coatings and cosmetics channels. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to regionalize formulation platforms or pursue unified global SKUs with modular liner systems.
Market Dynamics
Precision applicator closures are capturing value from solvent-sensitive industrial coatings as manufacturers face tightening EPA volatile organic compound standards and REACH substance restrictions across multiple jurisdictions.
Growth Catalysts
- Water-based formulation conversion:Coatings producers in China and Germany are retrofitting lines for low-VOC chemistries that require specialized dauber seals and liner materials.
- Extended Producer Responsibility frameworks:The EU Packaging and Packaging Waste Directive mandates recyclability disclosures, pushing converters toward mono-material polypropylene designs with embedded brushes.
- Industrial coatings automation:Factory-applied wood finishes and automotive touch-up systems are standardizing on torque-stable threaded closures to reduce rework rates.
Market Restraints
- Polypropylene resin price volatility:Feedstock fluctuations tied to naphtha cracking economics compress margin pools for high-volume injection molders serving household segments.
- Tooling concentration in Zhejiang Province:Multi-cavity mold fabrication for precision filament alignment relies on a concentrated supplier base, creating lead-time vulnerability.
- REACH Annex XVII restrictions:Phthalate plasticizer bans limit flexibility in liner formulations for solvent-bearing products, forcing reformulation cycles.
Strategic Opportunities
- Underpenetrated Latin American DIY retail:Brazil and Mexico home improvement chains lack dedicated applicator-cap SKUs for wood stain and adhesive categories.
- Pharmaceutical topical packaging:FDA-compliant brush caps for dermal solutions represent a white space adjacent to core industrial coatings demand.
- Digital printing integration:Direct-to-object decoration on closure bodies enables lot-level traceability for counterfeit-sensitive coatings brands.
Industry Challenges
- Multi-material separation for recycling:Brush filaments, foam daubers, and plastic bodies require disassembly infrastructure that most municipal waste systems lack.
- REACH registration timelines:Novel liner polymer introductions face 18-24 month pre-market notification windows that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brush and Dauber Caps Market |
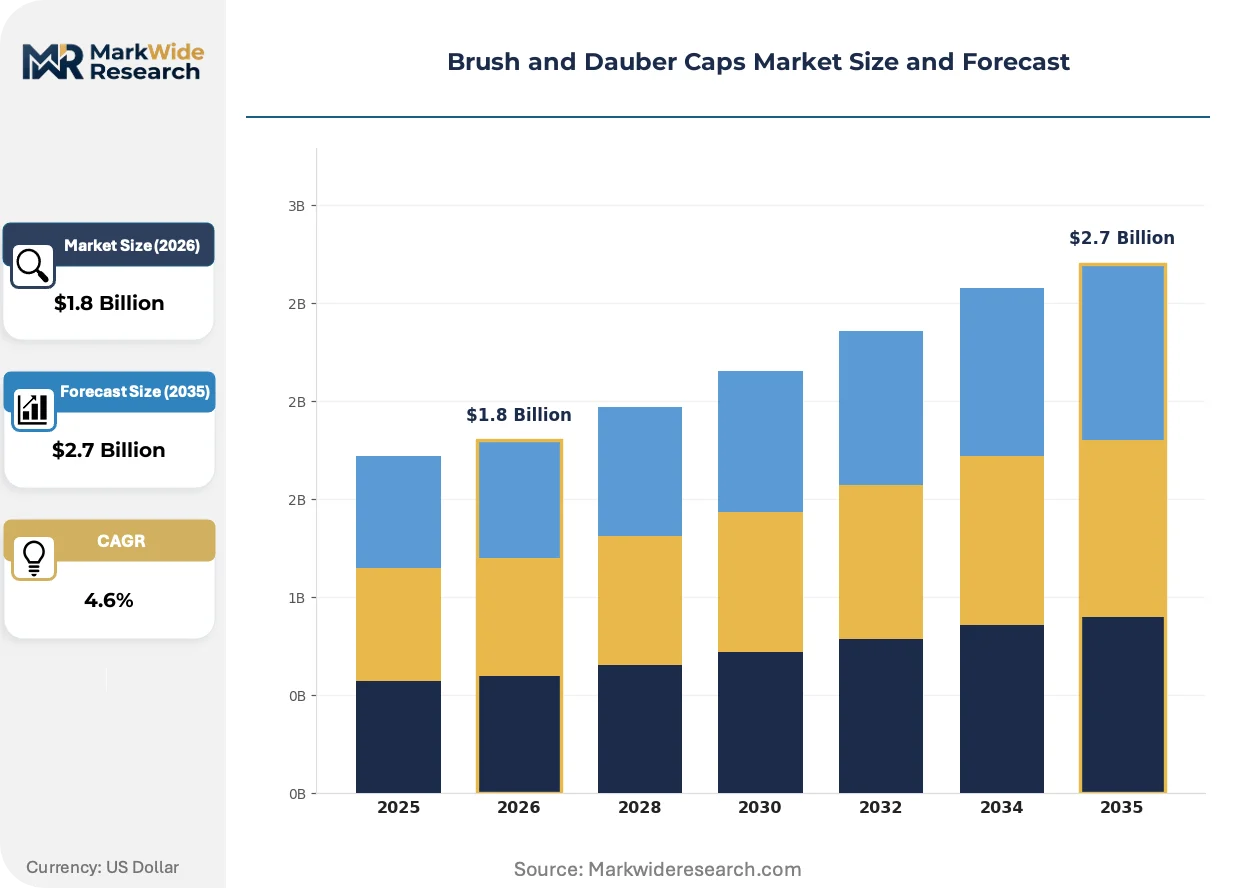
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brush Caps, Dauber Caps, Spray Caps, Refill Caps Material: Plastic, Metal, Rubber, Composite Application: Cosmetics, Arts & Crafts, Industrial Coatings, Household Use Distribution Channel: Retail, E-commerce, Wholesale, Direct Sales |
| Companies Covered | AptarGroup Inc., Silgan Holdings Inc., Berry Global Inc., Crown Holdings Inc., Amcor Plc, Closure Systems International, Bericap, Guala Closures, RPC Group Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brush and Dauber Caps Market Strategic Shifts
Material science advances and regulatory chemistry constraints are compressing traditional closure design cycles while opening adjacent specification tiers for barrier-engineered solutions.
Hot-runner sequential valve-gating technology is supplanting conventional cold-runner systems in high-cavity brush-cap molding. Tier-one automotive coatings suppliers in Germany and Japan are specifying sub-0.1mm filament positioning tolerances that only precision valve-gated tooling achieves. This capability gap is fragmenting the supplier base between precision specialists and commodity molders.
REACH SVHC candidate list expansions are forcing systematic substitution of bisphenol-A-based epoxy liners in solvent-contact applications. Industrial coatings distributors in France and the Netherlands now require full material disclosure certificates to maintain shelf placement. The response has accelerated bio-based polyester liner development for high-aromatic formulations.
Direct procurement relationships between coatings brand-owners and specialized closure converters are shortening traditional distribution hierarchies. Large North American wood-finish manufacturers are bypassing regional packaging distributors to specify custom torque profiles and filament densities. This channel compression is most pronounced in factory-applied coatings where batch consistency requirements override price sensitivity.
Brush and Dauber Caps Market Segmentation
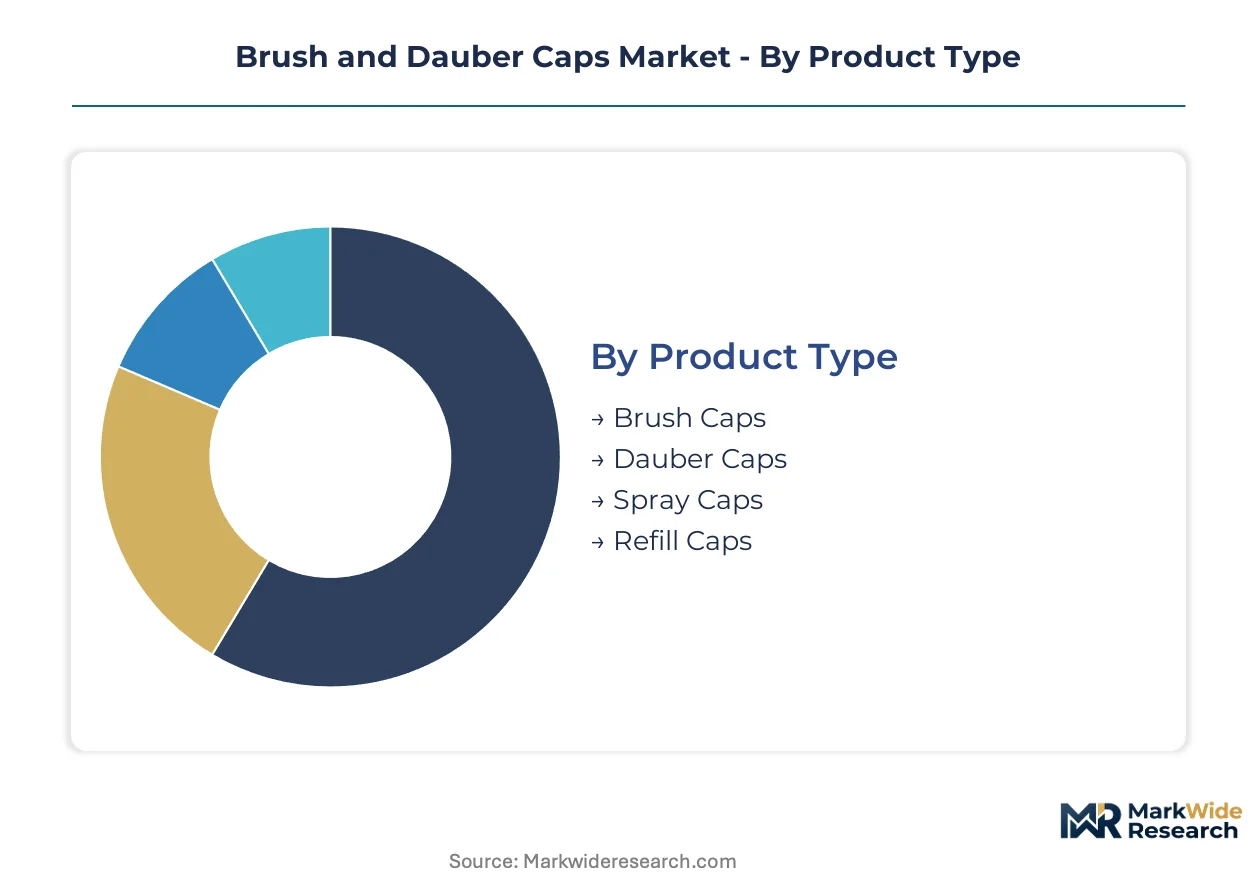
Segmentation in the Brush and Dauber Caps Market reveals distinct procurement patterns across channels. Industrial coatings buyers prioritize torque stability and chemical resistance through direct sales relationships, while household and DIY segments flow through retail and e-commerce with greater price sensitivity.
Product Type:
Channel mix varies sharply by applicator format. Brush caps dominate wholesale and direct sales channels serving industrial coatings manufacturers. Dauber caps concentrate in retail and e-commerce serving consumer stain and adhesive brands. Spray caps and refill caps split across professional supply houses and specialty craft retailers.
- Brush Caps:Molded polypropylene or HDPE bodies with filament brushes secured through crimped metal ferrules or ultrasonic welding. Industrial coatings manufacturers in Germany and Japan specify sub-0.1mm filament positioning tolerances for factory-applied wood finishes. REACH SVHC restrictions on bisphenol-A epoxy liners force systematic reformulation of high-barrier variants.
- Dauber Caps:Foam-tipped applicators integrated into snap-fit or threaded closures, typically specified for water-based stains and adhesives. Home improvement chains in Brazil and Mexico lack dedicated SKUs, creating white space for format conversion. Water-based formulation adoption in China drives specialized seal requirements for low-VOC chemistries.
- Spray Caps:Actuator mechanisms with precision orifice controls for aerosol or pump-dispensed products. Cosmetic and automotive touch-up applications dominate demand.
- Refill Caps:Threaded closures designed for repeated opening and resealing in professional workshop environments. Arts & crafts supply distributors favor these for bulk pigment systems.
By volume, brush caps lead. By growth pace, dauber caps are ahead.
Material:
Cost tier alignment separates commodity injection molders from precision specialists. Polypropylene occupies the economy-to-standard band. Metal-reinforced composites and advanced rubber formulations command premium positioning in solvent-sensitive industrial applications.
- Plastic:Polypropylene and HDPE formulations dominate through cost-efficient multi-cavity injection molding. Color customization flexibility serves private-label cosmetics and household brands. Naphtha cracking feedstock volatility compresses margins for high-volume molders serving price-sensitive segments.
- Metal:Aluminum and steel components provide torque stability for repeated industrial use cycles. Factory-applied automotive coatings specify metal-reinforced threaded closures to reduce rework rates from application inconsistency.
- Rubber:EPDM and nitrile liners deliver chemical resistance for solvent-bearing formulations. EPA volatile organic compound standards constrain permissible liner compositions in US-distributed products.
- Composite:Hybrid metal-plastic constructions balance structural integrity with weight reduction. Berry Global and Silgan Holdings anchor North American supply through integrated production platforms.
Plastic captures the highest shipment volumes. Composite materials deliver the steepest margin expansion.
Application:
Customer type determines specification intensity. Industrial coatings buyers enforce torque profiles and filament densities through direct procurement. Cosmetics and household segments accept standardized formats through retail distribution.
- Industrial Coatings:Factory-applied wood finishes, automotive touch-up systems, and protective coatings demand precision applicator performance. Tier-one automotive suppliers in Germany specify hot-runner sequential valve-gated tooling for sub-0.1mm tolerances.
- Cosmetics:Nail care and hair dye applications require FDA material contact compliance. Pharmaceutical-grade sealing performance bifurcates demand into premium specification tiers.
- Arts & Crafts:Hobbyist pigment and adhesive dispensing favors convenience-oriented dauber formats. E-commerce channels capture growing share as specialty retailers consolidate.
- Household Use:Furniture polish, shoe care, and general maintenance products prioritize cost efficiency over precision. Private-label concentration in big-box retail drives price compression.
Industrial coatings generate the highest per-unit value. Cosmetics applications show the strongest pricing power.
Distribution Channel:
Supply concentration shapes access patterns. Direct relationships between coatings brand-owners and specialized converters are shortening traditional distribution hierarchies in industrial segments. Retail and e-commerce fragmentation persists in consumer-facing categories.
- Direct Sales:Large North American wood-finish manufacturers bypass regional packaging distributors to specify custom torque profiles. Batch consistency requirements override price sensitivity in factory-applied coatings procurement.
- Wholesale:Industrial coatings distributors in France and Netherlands now require full material disclosure certificates to maintain shelf placement. REACH compliance documentation flows through this channel.
- Retail:Home improvement chains and mass merchants serve DIY stain and adhesive demand. Underpenetrated Latin American markets lack dedicated applicator-cap SKUs for wood finish categories.
- E-commerce:Direct-to-consumer pigment and craft supply brands leverage digital channels for niche format experimentation. Lot-level traceability requirements from counterfeit-sensitive coatings brands favor digital printing integration.
Direct sales command the highest margins. E-commerce is gaining share fastest in consumer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-bound coatings brands in China drive applicator-cap demand while European REACH compliance and US EPA standards reshape material specifications across trade corridors.
China
Domestic packaging converters in Zhejiang Province build dedicated applicator-cap lines for coatings exports to North America and Europe. MEE enforcement of dual carbon goals accelerates factory retrofits for low-VOC water-based formulations. Ningbo tooling clusters face lead-time pressure as multi-cavity mold demand outpaces precision machining capacity.
Germany
Tier-one automotive coatings suppliers specify hot-runner sequential valve-gated tooling for sub-0.1mm filament tolerances in factory-applied wood finishes. KBA safety standards intersect with REACH SVHC restrictions on bisphenol-A epoxy liners. Stuttgart industrial corridors anchor precision molding specialization for solvent-sensitive barrier applications.
United States
Large wood-finish manufacturers bypass regional distributors to procure custom torque-profile closures directly from specialized converters. EPA volatile organic compound emission standards constrain permissible liner chemistries for solvent-bearing products. Ohio and Indiana injection molding clusters serve household segments through high-volume multi-cavity production.
Brazil
Home improvement chains lack dedicated applicator-cap SKUs for wood stain and adhesive categories, creating format conversion white space. ANVISA pharmaceutical regulations open adjacent demand for FDA-compliant topical packaging. São Paulo industrial districts concentrate domestic converters serving Mercosur coatings distribution.
France
Industrial coatings distributors require full material disclosure certificates to maintain shelf placement under REACH compliance documentation mandates. ANSM pharmaceutical oversight extends to dermal solution packaging specifications. Lyon chemical corridors host liner reformulation labs responding to bio-based polyester demand.
Brush and Dauber Caps Market Competitive Environment
Listed leaders compete with private specialists across precision molding capability and regulatory documentation depth. The supplier base stratifies between scale-driven commodity molders and barrier-engineering specialists serving solvent-sensitive formulations. Three archetypes dominate: integrated metal-plastic hybrid producers, precision filament-alignment specialists, and multi-cavity injection scale operators. Capacity expansion in Zhejiang tooling clusters and backward integration into resin compounding represent the primary competitive vectors reshaping supply relationships.
Among North American packaging conglomerates, AptarGroup Inc., Silgan Holdings Inc., and Berry Global Inc. occupy distinct positioning tiers. AptarGroup exemplifies the precision-molding archetype through its pharmaceutical-grade sealing expertise. Silgan Holdings anchors integrated metal-plastic hybrid production platforms. Berry Global represents scale-driven multi-cavity capacity serving simultaneous household and industrial procurement channels.
| Leading Market Players |
|---|
| AptarGroup Inc. |
| Silgan Holdings Inc. |
| Berry Global Inc. |
| Crown Holdings Inc. |
| Amcor Plc |
| Closure Systems International |
| Bericap |
| Guala Closures |
| RPC Group Plc |
| Others |
Value Chain & Pricing Dynamics
Sixteen-week lead times for multi-cavity precision molds from Zhejiang Province concentrate pricing power among integrated converters serving industrial coatings manufacturers, while naphtha-derived polypropylene feedstock volatility compresses margins for high-volume household segment suppliers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers command position through REACH-compliant liner certifications and sub-0.1mm filament tolerance guarantees from hot-runner sequential valve-gated tooling. Price differentiation rests on torque stability specifications and chemical resistance ratings. Cost compression in the household tier intensifies because private-label concentration at big-box retailers drives volume-based procurement. DIY retail segments exhibit highest price sensitivity; factory-applied automotive coatings buyers show least sensitivity due to batch consistency requirements.
Supply Chain Analysis
Port congestion on Ningbo-Shanghai trade lanes elevates inbound logistics costs for European and North American coatings brands sourcing from Chinese packaging converters. Manufacturing concentrates in China, Germany, and the United States. Raw material flows draw from Saudi naphtha crackers for polypropylene resin, Belgian epoxy compounders for liner formulations, and Japanese precision steel for filament ferrules. Single-source vulnerability concentrates in Zhejiang tooling clusters where multi-cavity mold fabrication capacity lags demand. Distribution runs through direct procurement relationships between coatings brand-owners and specialized converters in industrial segments, while retail and e-commerce fragmentation persists in consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision filament alignment capabilities and REACH documentation depth constitute the scarce assets separating viable competitors from margin-compressed commodity suppliers in this market.
For Market Incumbents: Secure backward integration into resin compounding to hedge naphtha feedstock volatility threatening household segment margins. Lock in multi-year mold fabrication capacity reservations with Zhejiang tooling clusters before lead-time extensions strand growth. AptarGroup's pharmaceutical-grade sealing expertise and Silgan's metal-plastic hybrid platforms demonstrate how certification depth defends position against emerging precision specialists. For New Entrants and Emerging Players: Lead with water-based formulation compatibility as German and Chinese coatings producers retrofit lines for low-VOC chemistries. Brazil and Mexico home improvement chains lack dedicated applicator-cap SKUs, creating format conversion white space for dauber-cap specialists. Target pharmaceutical topical packaging adjacent to core industrial demand, leveraging FDA material contact compliance as a differentiated entry credential. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates where brush and dauber cap divisions lack strategic priority despite holding precision molding assets. Five-to-ten year viability favors converters with captive hot-runner sequential valve-gating capabilities and established REACH documentation workflows. Watch for EPA volatile organic compound standard revisions as an inflection indicator that would accelerate liner reformulation demand and reward pre-positioned barrier-engineering specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive polypropylene supply hedges naphtha volatility for high-volume molders serving household segments. |
| Hot-Runner Sequential Valve-Gating Capacity Expansion | Sub-0.1mm filament tolerance capability captures tier-one automotive coatings specifications in Germany and Japan. |
| REACH-Compliant Liner Certification Investment | Full material disclosure certificates maintain shelf placement with French and Dutch industrial coatings distributors. |
| Direct Procurement Relationship Development | Bypassing regional distributors captures custom torque-profile specifications from large North American wood-finish manufacturers. |
| Digital Printing Integration for Lot-Level Traceability | Direct-to-object decoration satisfies counterfeit-sensitive coatings brands in e-commerce channels. |
Study Parameters
Desk research of customs trade databases, SEC 10-K filings from packaging conglomerates, and ECHA REACH registration databases preceded structured interviews with injection molding plant managers, coatings procurement leads at industrial OEMs, distribution channel partners in DIY retail, and technical R&D directors for liner formulation. Primary fieldwork combined with secondary validation through triangulation of bottom-up production capacity estimates and top-down demand segmentation.
Variance decomposition across product type, material grade, application intensity, and regional regulatory cluster shaped the analytical framework over the projection horizon. Modeled segmentation dimensions included applicator format, barrier specification tier, end-use industry, and distribution channel structure. CAGRs derived from production capacity build-out timelines, coatings formulation conversion rates, and trade flow intensities. Industry-specific forecast inputs incorporated MEE dual carbon goal enforcement timelines in China and KBA safety standard evolution in Germany.
Forecasts assume regulatory continuity in EPA volatile organic compound standards, REACH SVHC candidate list expansions, and EU Packaging and Packaging Waste Directive implementation; material policy shifts would require re-modeling of liner formulation demand and recyclability disclosure compliance costs. Specific risk factors include polypropylene resin price volatility from naphtha cracking economics and tooling concentration vulnerability in Zhejiang Province. Recalibration cycles align with material shifts in coatings formulation chemistry, extended producer responsibility framework adoption, and precision molding technology diffusion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
US Caps and Closure Market
Caps and Closures
Non-Aerosol Overcaps Market
Caps and Closures
United Arab Emirates Plastic Caps and Closures Market
Caps and Closures
Aerosol Valves Market
Caps and Closures
Box Latch Market
Caps and Closures
Spain Plastic Cap and Closure Market
Caps and Closures
Child Resistant Dropper Caps Market
Caps and Closures
Plunger Stopper Market
Caps and Closures
Child Resistant Pipette Closures Market
Caps and Closures
Heat Induction Cap Liner Market
Caps and Closures
Vietnam Plastic Caps and Closures Market
Caps and Closures
China Plastic Caps and Closures Market
Caps and Closures
Aluminium ROPP Closures Market
Caps and Closures
Resealable Closures and Spouts Packaging Market
Caps and Closures
Bi-Injected Snap Hinge Closure Market
Caps and Closures
Fixed Length Seals Market