
 United Kingdom Electric Vehicle (EV) Market | 2026-2036
United Kingdom Electric Vehicle (EV) Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Electric Vehicle (EV) Market Insights
Fleet procurement channels is reshaping how volume flows into the United Kingdom Electric Vehicle (EV) Market. Tesla leverages its Supercharger network to sustain direct-to-consumer dominance in premium segments. Vauxhall anchors fleet supply through Stellantis manufacturing capacity at Ellesmere Port. BYD competes on battery cost structure to extend its commercial vehicle positioning.
United Kingdom Electric Vehicle encompasses road-certified automobiles propelled by electric motors drawing energy from rechargeable battery packs, typically employing lithium-ion cells with energy densities exceeding 250 Wh/kg and operating voltages between 400V and 800V architectures. Battery Electric Vehicle commands the dominant product position as powertrain simplification reduces maintenance and total cost of ownership for fleet operators. DC Fast Charging infrastructure attracts capital deployment fastest among charging technologies, though AC Charging retains volume leadership in residential settings where dwell times accommodate slower replenishment cycles.
The Department for Transport enforces Zero Emission Vehicle sales mandates that compel manufacturers to phase out internal combustion offerings, while Ofgem regulates grid connection standards for charging infrastructure deployment. The Vehicle Certification Agency applies UN ECE type approval requirements that shape battery safety testing protocols and electromagnetic compatibility thresholds. Stakeholders must monitor how grid capacity constraints in urban corridors interact with permitting timelines for high-power charging hubs.
Market Dynamics
Fleet procurement channels are consolidating volume flows around charging infrastructure density, with the Zero Emission Vehicle mandate forcing manufacturer compliance investments ahead of 2030 phase-out deadlines. This structural pressure redistributes competitive advantage toward players with captive charging networks and Stellantis-scale domestic manufacturing footprint.
Growth Catalysts
- Zero Emission Vehicle mandate:The Department for Transport's sales floor mechanism compels manufacturers to electrify line-ups, accelerating model availability and price parity timelines.
- Last-mile logistics electrification:Parcel carriers and grocery delivery operators are converting van fleets to battery electric powertrains to access clean air zones and reduce operating expenditure.
- Silicon carbide inverters:Power electronics employing wide-bandgap semiconductors are extending vehicle range and reducing charging dwell times for commercial operators.
Market Restraints
- Lithium supply concentration:Cathode material processing capacity clusters in East Asia, exposing UK-based assemblers to input cost volatility and currency risk.
- Grid connection queues:Ofgem's distribution network operator approval timelines for high-power charging hubs extend 18-36 months in Greater London corridors.
- Residual value uncertainty:Fleet buyers hesitate on battery degradation risk without standardized state-of-health certification protocols from the Vehicle Certification Agency.
Strategic Opportunities
- West Midlands manufacturing cluster:Battery gigafactory development around Coventry and Birmingham offers localized cell supply and reduced logistics expenditure for domestic OEMs.
- Vehicle-to-grid integration:Bidirectional charging protocols enable fleet operators to monetize parked assets through frequency response services.
- Scotland's renewable electricity surplus:North Sea wind generation capacity supports ultra-low carbon intensity charging for commercial fleets operating in Glasgow and Edinburgh corridors.
Industry Challenges
- High-voltage technician scarcity:The Institute of the Motor Industry reports insufficient certified workforce to service 800V architectures rolling out across premium and commercial segments.
- Permitting fragmentation:Local authority planning departments apply inconsistent standards for charging hub deployment, delaying capital deployment in priority urban corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Electric Vehicle (EV) Market |
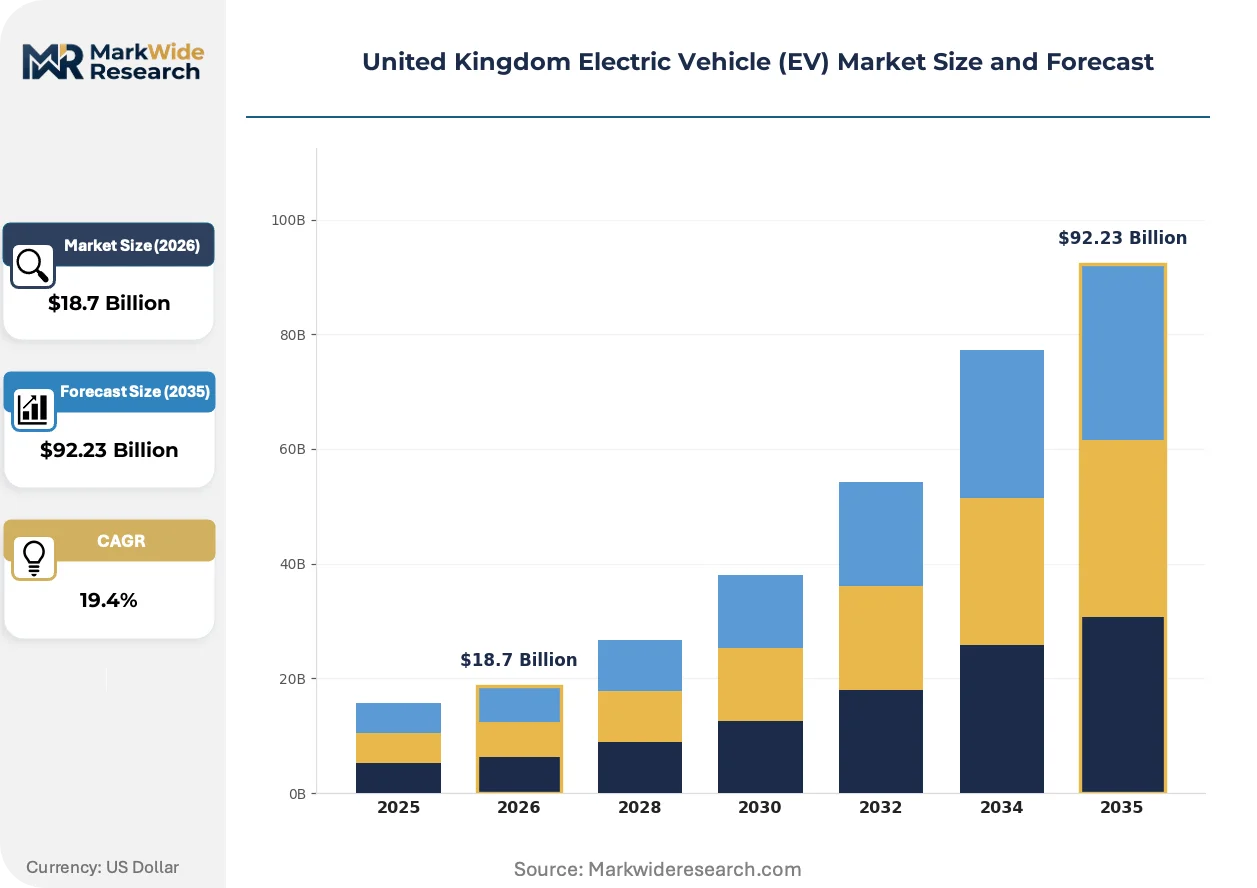
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $92.23 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery Electric Vehicle, Plug-in Hybrid Electric Vehicle, Hydrogen Fuel Cell Vehicle, Extended Range Electric Vehicle End User: Private Consumers, Fleet Operators, Government Agencies, Ride-Sharing Services Charging Technology: AC Charging, DC Fast Charging, Wireless Charging, Battery Swap Systems Vehicle Size: Compact, Midsize, SUV, Luxury |
| Companies Covered | Tesla, BYD, Volkswagen, Mercedes-Benz Group, BMW, Kia, Vauxhall, Ford Motor, Renault Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Electric Vehicle (EV) Market Trends and Innovations
Battery chemistry and power electronics are converging to compress total cost of ownership gaps against diesel equivalents. Three material and architectural shifts are reconfiguring competitive positioning across passenger and commercial segments.
Cell chemistry is migrating from nickel-manganese-cobalt formulations toward lithium-iron-phosphate architectures for commercial vehicle applications. Fleet operators prioritizing cycle life over energy density are specifying LFP packs for depot-charged vans and rigid trucks. This chemistry shift is compressing cathode material cost exposure and extending warranty coverage terms.
The Department for Transport's tightening CO2 standards under the Department for Transport are forcing manufacturer compliance investments ahead of 2030 deadlines. OEMs must achieve escalating zero-emission sales shares or face per-vehicle penalties. Commercial vehicle segments face the steepest compliance gradients, accelerating electric van and truck model introductions.
Direct fleet purchasing is displacing traditional retail channels for volume acquisition. Logistics operators and public sector procurement bodies are negotiating multi-year supply agreements with guaranteed charging infrastructure co-investment. This channel concentration is most visible in Greater London, where clean air zone enforcement and congestion charging exemptions create immediate operating cost differentials.
United Kingdom Electric Vehicle (EV) Market Segmentation
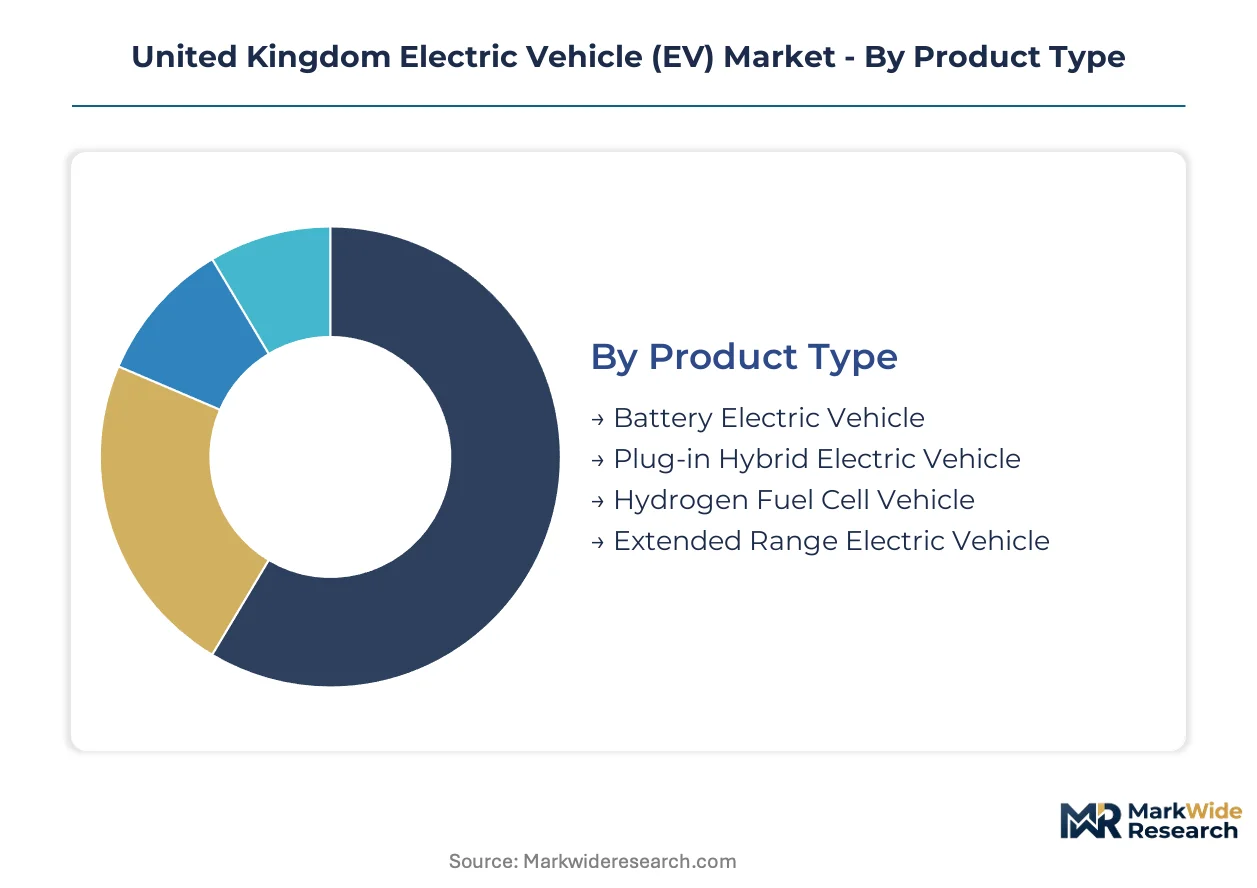
Segmentation reveals how fleet procurement channels and charging infrastructure density concentrate volume flows across distinct customer and technology configurations. Understanding these divisions exposes where compliance investments under the Zero Emission Vehicle mandate translate into commercial opportunity.
Product Type:
After-sales service intensity varies sharply across powertrain architectures, with battery complexity and thermal management requirements driving differentiated maintenance protocols.
- Battery Electric Vehicle:Pure electric architecture eliminates transmission and exhaust systems, reducing scheduled maintenance intervals. Fleet operators in Greater London prioritize this segment for clean air zone compliance and total cost of ownership compression.
- Plug-in Hybrid Electric Vehicle:Dual powertrain retains internal combustion range extender, demanding parallel maintenance streams for electric and mechanical components. Private consumers in suburban corridors favor this segment where charging infrastructure remains sparse.
- Hydrogen Fuel Cell Vehicle:Proton exchange membrane stacks require specialized technician certification and limited refueling infrastructure.
- Extended Range Electric Vehicle:Series hybrid configuration uses combustion engine exclusively as generator, simplifying drivetrain versus parallel hybrids.
By volume, Battery Electric Vehicle leads. By growth pace, Plug-in Hybrid Electric Vehicle is ahead among retail channels bridging infrastructure gaps.
End User:
Customer type determines procurement scale and contract structure, with volume concentration shifting toward institutional buyers negotiating multi-year supply agreements.
- Private Consumers:Individual purchasers respond to purchase incentives and residential charging availability. West Midlands households show strongest conversion rates where workplace charging provisions complement home infrastructure.
- Fleet Operators:Logistics and parcel delivery operators convert van fleets under total cost of ownership models, securing guaranteed charging co-investment from manufacturers. This segment concentrates procurement volume around depot-charged commercial vehicles.
- Government Agencies:Public sector procurement mandates specify minimum zero-emission shares, creating predictable demand anchors.
- Ride-Sharing Services:High-utilization operators prioritize vehicles with DC fast charging compatibility and battery warranty terms matching mileage intensity.
By contract value, Fleet Operators dominate. By conversion velocity, Ride-Sharing Services are expanding most quickly.
Charging Technology:
Capital deployment intensity and grid connection timelines segment infrastructure investors by dwell time economics and power rating requirements.
- AC Charging:Alternating current Level 2 systems operate at 7-22 kW, matching residential and workplace dwell periods. Residential installations across Greater London concentrate here, supported by Ofgem connection standards.
- DC Fast Charging:Direct current systems deliver 50-350 kW, compressing commercial vehicle turnaround times. Motorway service areas and urban freight hubs attract capital fastest where utilization rates justify equipment premiums.
- Wireless Charging:Inductive pad systems eliminate connector wear but require precise vehicle positioning and higher capital expenditure.
- Battery Swap Systems:Automated exchange stations target commercial fleets with standardized pack geometries, bypassing charging dwell entirely.
By installation base, AC Charging leads. By capital deployment rate, DC Fast Charging is gaining share fastest.
Vehicle Size:
Platform economics and battery pack sizing separate segments by manufacturing scale and pricing architecture.
- Compact:Sub-4.5 meter vehicles optimize urban maneuverability and battery efficiency. Metropolitan private consumers and car-sharing operators in Edinburgh and Glasgow corridors specify this segment for parking-constrained environments.
- Midsize:Family saloons and hatchbacks balance interior volume with aerodynamic efficiency, anchoring mainstream fleet procurement.
- SUV:Higher ride height and cargo capacity command battery pack premiums, with demand concentrating among suburban private buyers.
- Luxury:Premium positioning justifies 800V architectures and advanced driver assistance, with residual value performance critical to leasing structures.
By unit registrations, Midsize leads. By margin contribution, Luxury is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The M6 motorway corridor and West Coast Main Line electrification program anchor the United Kingdom's EV manufacturing and logistics infrastructure, connecting battery gigafactory sites in the Midlands to Scottish wind generation capacity and Greater London demand centers.
Greater London
Ultra Low Emission Zone enforcement and congestion charging exemptions drive fleet electrification among parcel carriers and ride-sharing operators. Transport for London coordinates rapid charging hub deployment across borough boundaries. The Royal Docks enterprise zone concentrates last-mile logistics depots converting van fleets under total cost of ownership models.
West Midlands
Stellantis manufacturing capacity at Ellesmere Port and emerging battery cell production around Coventry attract supplier clustering. The region's automotive heritage infrastructure supports high-voltage technician training programs through local technical colleges. Birmingham's Clean Air Zone accelerates commercial vehicle replacement cycles among regional distributors.
Scotland
North Sea offshore wind generation capacity delivers ultra-low carbon intensity electricity for commercial fleet charging in Glasgow and Edinburgh corridors. Transport Scotland administers interest-free loans for taxi and private hire electrification. The Forth Valley industrial cluster hosts emerging hydrogen fuel cell trials for heavy freight applications.
South East England
Channel port logistics corridors and proximity to continental European supply chains position Kent and Sussex for battery import and distribution functions. Oxfordshire's motorsport technology cluster transfers power electronics expertise to EV component suppliers. Gatwick and Heathrow airport ground support equipment electrification creates concentrated commercial vehicle demand.
United Kingdom Electric Vehicle (EV) Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying battery management systems and thermal management hardware. The United Kingdom Electric Vehicle market structure concentrates around vertically integrated multinational OEMs with captive European manufacturing footprints, while emerging Chinese battery specialists compete on cell cost structure. Three archetypes dominate: direct-to-consumer premium brands with proprietary charging networks, fleet-focused domestic assemblers leveraging Stellantis-scale production capacity, and battery cost leaders targeting commercial vehicle specifications. Competitive moves center on strategic partnerships for charging infrastructure co-investment and backward integration into cell manufacturing through joint ventures with Asian suppliers.
Among the established premium-tier players, Tesla anchors direct-to-consumer distribution with its Supercharger network infrastructure. Vauxhall occupies a central position in fleet procurement channels through its Stellantis manufacturing presence at Ellesmere Port. BYD represents the battery cost leadership archetype, competing on lithium-iron-phosphate cell economics for commercial vehicle applications.
| Leading Market Players |
|---|
| Tesla |
| BYD |
| Volkswagen |
| Mercedes-Benz Group |
| BMW |
| Kia |
| Vauxhall |
| Ford Motor |
| Renault Group |
| Others |
Pricing and Supply Chain Analysis
The M6 motorway corridor's freight cost dynamics concentrate supply-side leverage among cathode material processors while forcing three-tier pricing stratification across premium, standard, and economy vehicle tiers for UK fleet buyers.
Pricing Analysis
Volume-discount tiering separates fleet procurement contracts from retail transactions, with multi-year supply agreements commanding 15-20% unit cost reductions against spot purchases. Price differentiation rests on battery chemistry grade and DC fast charging capability bundling. Cost compression in the standard tier intensifies as Chinese cell manufacturers extend lithium-iron-phosphate economics. Fleet operators exhibit highest price sensitivity, while luxury private buyers prioritize residual value guarantees over upfront expenditure.
Supply Chain Analysis
Export-control regimes restricting semiconductor manufacturing equipment flows to Chinese fabs are fragmenting power electronics sourcing strategies for UK-based OEMs. Cathode active material production concentrates in China, South Korea, and Japan, with UK assemblers drawing from East Asian cell supply. Lithium carbonate, nickel sulfate, and cobalt hydroxide dependencies expose margins to commodity volatility. Single-source vulnerability in silicon carbide wafer supply threatens inverter production schedules. Distribution runs through Stellantis manufacturing at Ellesmere Port and inbound battery logistics via Channel ports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet procurement consolidation around multi-year supply agreements has shifted buyer power toward logistics operators negotiating charging infrastructure co-investment, fragmenting traditional retail channel influence.
For Market Incumbents: Harden domestic manufacturing positioning through battery gigafactory joint ventures near Coventry, insulating against cathode material currency exposure. Deepen captive charging network density across Greater London corridors to lock in fleet contract renewals. Prioritize silicon carbide inverter sourcing diversification ahead of export-control tightening. For New Entrants and Emerging Players: Mid-market commercial van segments in Scotland's Glasgow-Edinburgh corridor represent the most penetrable entry point, where North Sea wind generation enables ultra-low carbon intensity charging propositions. Battery swap infrastructure for rigid truck depots offers differentiated service models against incumbent DC fast charging. Target public sector procurement frameworks with guaranteed renewable electricity sourcing. For Investors and Strategic Acquirers: High-voltage technician training providers with Institute of the Motor Industry accreditation pathways offer acquisition exposure to service capacity bottlenecks. Long-term viability hinges on grid connection permit acceleration and battery state-of-health certification standardization. Watch Ofgem distribution network operator approval timeline compression as inflection signal for charging infrastructure capital deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Stellantis gigafactory partnerships secure lithium-iron-phosphate cell volumes for Ellesmere Port van production. |
| Charging Infrastructure Partnership | Transport for London hub coordination accelerates fleet depot electrification across borough boundaries. |
| Platform Standardization | 800V architecture migration reduces charging dwell times for commercial vehicle turnaround economics. |
| Geographic Manufacturing Footprint | West Midlands supplier clustering compresses logistics expenditure for domestic OEM assembly operations. |
| Software-Defined Vehicle Investment | Vehicle-to-grid protocol integration enables frequency response revenue for parked fleet assets. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet procurement directors, OEM platform engineers, charging infrastructure developers, and Ofgem regulatory affairs specialists. Secondary validation drew from Department for Transport Zero Emission Vehicle mandate filings, Vehicle Certification Agency type approval databases, Ofgem grid connection registers, and Stellantis production disclosures. Bottom-up fleet conversion models and top-down automotive sector expenditure estimates were triangulated against regional registration data.
Calibration anchored volume projections to observed fleet procurement contract values and residential charging installation permits across Greater London, West Midlands, and Scotland. Segmentation dimensions modeled encompassed vehicle class, propulsion architecture, end-user type, and charging technology tier. CAGRs were derived from exponential smoothing of annual fleet penetration rates and battery cost decline curves. Silicon carbide adoption timelines and lithium-iron-phosphate chemistry share shifts informed power electronics and battery pack forecasts.
Practitioners should monitor grid connection queue lengths and cathode material spot price volatility for early signals of forecast deviation. Material shifts in Department for Transport mandate enforcement intensity or Ofgem distribution network investment timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Plug-In Hybrid Electric Vehicle Battery Market
Electric Vehicles
Electric Vehicle Battery Cases Market
Electric Vehicles
United States Electric Car Market
Electric Vehicles
Used EV Market
Electric Vehicles
Europe Automotive High Performance Electric Vehicle Market
Electric Vehicles
Light Electric Vehicle Market
Electric Vehicles
Electric Passenger Cars Market
Electric Vehicles
Global EV on-Board Chargers Market
Electric Vehicles
Global Electric Cars Market
Electric Vehicles
Global Electric Classic Car Market
Electric Vehicles
France Electric Vehicle Market
Electric Vehicles
E-Bike Battery Market
Electric Vehicles
Electric Vehicle Electric Heating Film Market
Electric Vehicles
Compact E-Scooter Market
Electric Vehicles
Russia Electric Cars Market
Electric Vehicles
Middle East Wireless EV Charging Market