
 China Solar E-Bike Market | 2026-2036
China Solar E-Bike Market Size, Share, and Industry Trends Forecast 2026-2036
China Solar E-Bike Market Insights
Direct-to-fleet distribution is reconfiguring how manufacturers reach high-volume buyers in China's solar e-bike sector. Yadea Technology Group leverages its dealership density across tier-two cities to sustain volume leadership. BYD Co., Ltd. anchors its position through captive cell production and in-house battery management systems. NIU Technologies differentiates via connected-vehicle software and premium urban positioning.
A China solar e-bike integrates photovoltaic panels into the frame or cargo surfaces, typically generating 15-50 watts to supplement lithium-ion or lead-acid battery packs during daylight operation, with primary purpose of extending range for urban commuters and commercial delivery operators. Lithium-ion battery configurations command the dominant margin pool due to energy density requirements under MIIT efficiency rules, while delivery services application segments show the fastest structural expansion driven by fleet electrification mandates in major municipalities. Solar charging method adoption concentrates among premium urban commuting models where parking exposure justifies panel cost.
MIIT sets mandatory energy efficiency grades and battery recycling protocols, while GB standards govern photovoltaic integration safety and electrical system interoperability, with SAMR administering market access certification that filters out non-compliant imports. The country's dual carbon goals channel subsidy eligibility toward vehicles demonstrating measurable fossil-fuel displacement. Stakeholders must track how provincial subsidy tiers and grid-integration pilots for solar charging infrastructure reshape total cost of ownership calculations across buyer segments.
Market Dynamics
MIIT's dual carbon goals are compressing battery efficiency standards while concentrating procurement power among municipal fleet operators in the Yangtze River Delta corridor.
Growth Catalysts
- Fleet electrification mandates:Shanghai and Shenzhen municipal authorities now require last-mile delivery operators to meet zero-emission quotas, pulling solar-assisted e-bike volumes into structured procurement programs.
- Photovoltaic integration protocols:GB standards governing panel-to-frame electrical interoperability have reduced system integration costs for qualified manufacturers.
- Subsidized charging infrastructure:Provincial grid-integration pilots in Jiangsu and Zhejiang are defraying total cost of ownership for commercial operators with daytime parking exposure.
Market Restraints
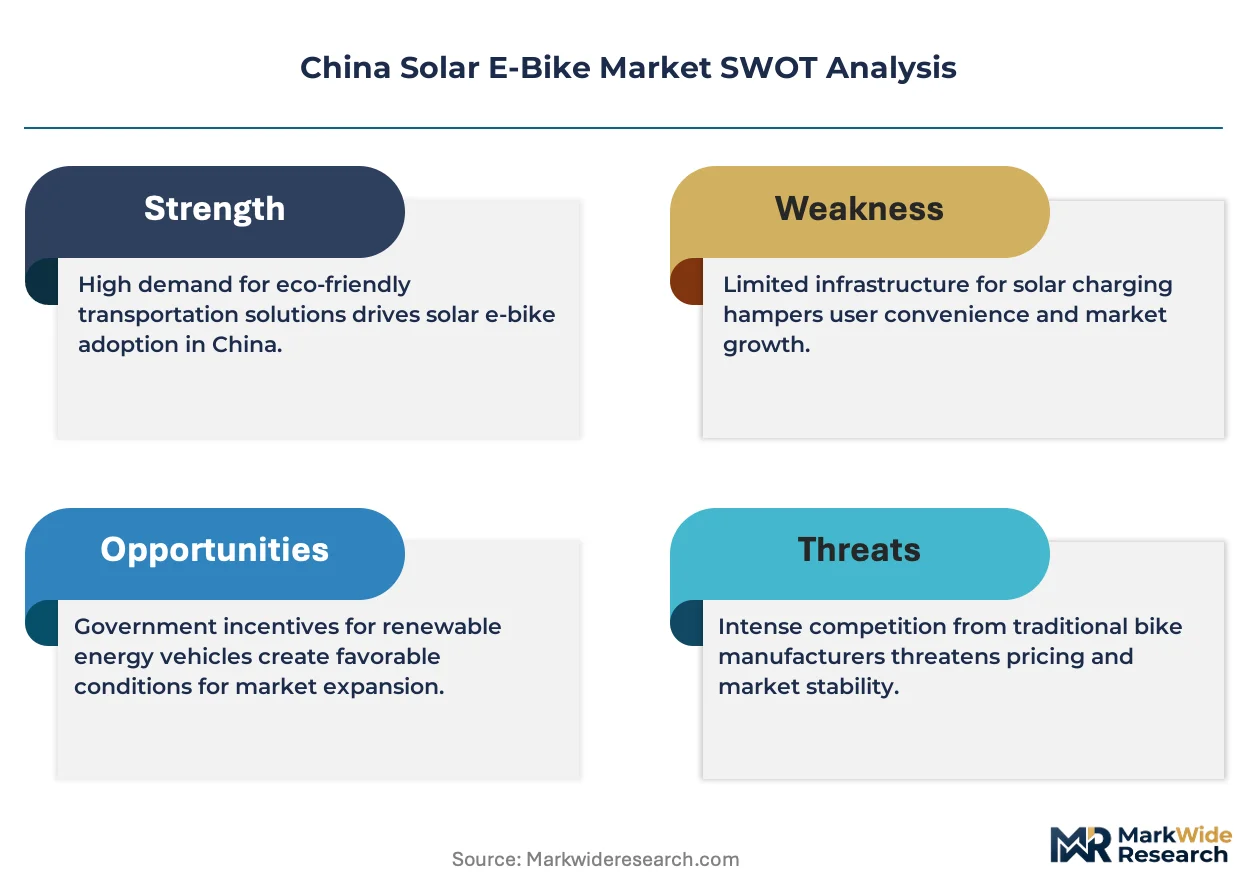
- Polysilicon price volatility:Raw material input costs for photovoltaic cells fluctuate with solar-grade silicon ingot supply from Xinjiang-based smelters.
- Lead-acid battery displacement friction:Legacy lead-acid configurations retain cost advantage in rural sub-markets despite MIIT efficiency grade penalties.
- Solar yield seasonality:Northern China provinces experience 40-60% winter irradiance reduction, compressing effective range extension during peak delivery periods.
Strategic Opportunities
- Western China corridor expansion:Chengdu-Chongqing urban agglomeration lacks mature solar e-bike penetration despite comparable fleet electrification policies.
- Intermodal cargo integration:Solar panel-equipped cargo trikes are penetrating parcel-sorting hub feeder routes where grid charging access remains constrained.
- Battery-as-a-service models:Swappable lithium-ion pack subscriptions are decoupling upfront capital burden from solar range extension benefits.
Industry Challenges
- Photovoltaic technician scarcity:Frame-integrated panel installation and diagnostic skills lag behind production scaling in Anhui and Jiangsu manufacturing zones.
- MIIT certification timeline compression:Revised GB standard cycles are forcing redesign cycles faster than legacy validation protocols accommodate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Solar E-Bike Market |
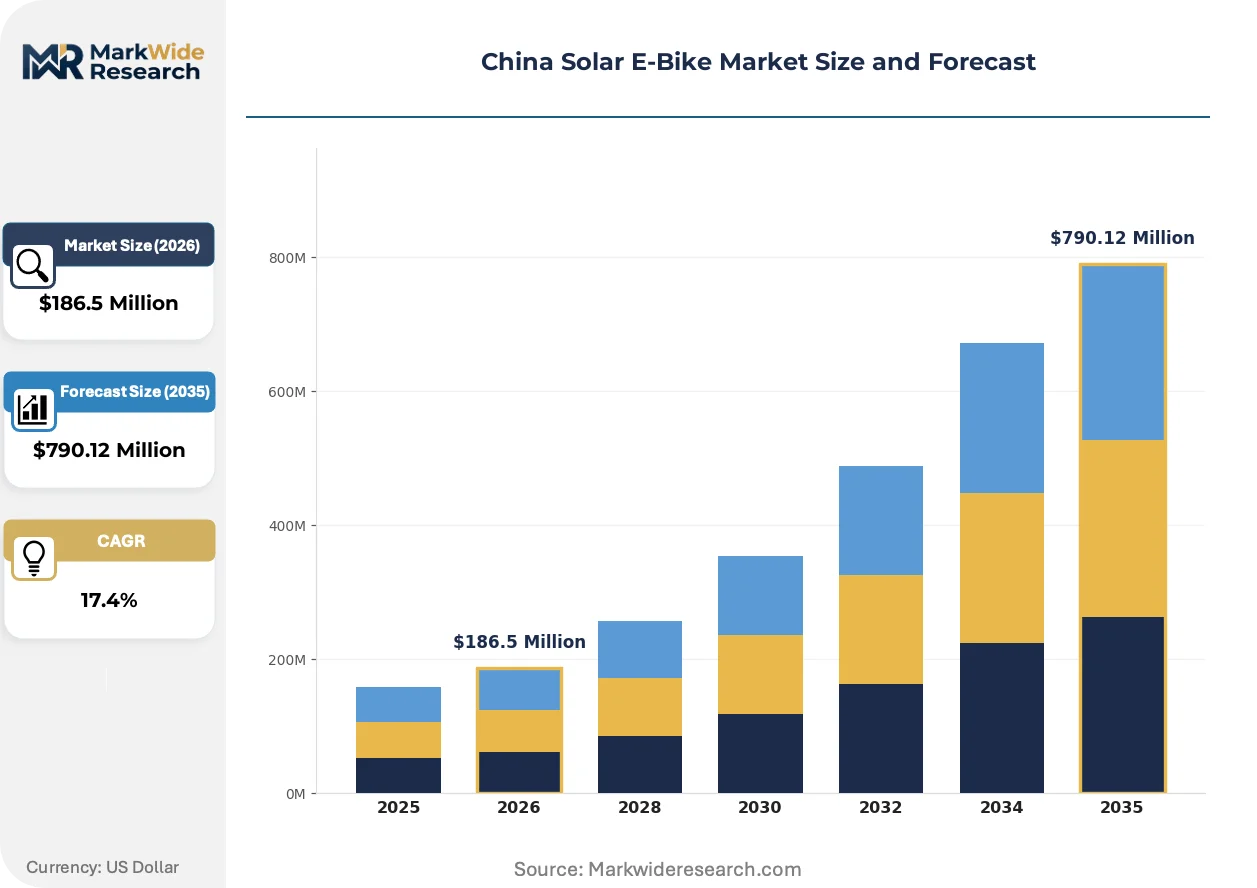
| Market Size in 2026 | $186.5 Million |
| Market Size in 2035 | $790.12 Million |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium-ion, Lead-acid, Nickel Metal Hydride, Others Application: Urban Commuting, Delivery Services, Leisure, Recreational Charging Method: Solar Charging, Standard Plug-in, Hybrid, Regenerative Weight Capacity: Up to 100kg, 100kg-150kg, 150kg-200kg, Over 200kg |
| Companies Covered | Wuxi ALP Technology Co., Ltd., Yadea Technology Group Co., Ltd., Jiangsu Xinri E-Vehicle Co., Ltd., Luyuan Group Co., Ltd., BYD Co., Ltd., Aima Technology Group Co. Ltd, Shenzhen TAILG Technology Group Co., LTD., NIU Technologies, Sunra Electric Vehicle, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Solar E-Bike Market Trends and Innovations
Connected-vehicle architectures are rewiring how fleet operators monitor solar yield and battery state-of-charge in real time. Three developments are compressing competitive differentiation windows.
Telematics integration is digitizing operational visibility for distributed delivery fleets. Solar charge controllers now stream panel output and battery health metrics to centralized dispatch platforms. Meituan and Ele.me food delivery contractors in Hangzhou and Nanjing are piloting these systems to optimize route planning around predicted solar gain. The data layer is digitizing fleet management from reactive maintenance toward predictive deployment.
MIIT's 2024 efficiency grade recalibration is tightening permissible standby power draw and charging loss ratios. Manufacturers must redesign battery management systems to meet Grade 1 thresholds or forfeit subsidy eligibility in tier-one cities. Premium urban commuting models with integrated photovoltaics face the steepest compliance burden because panel-to-battery conversion losses now factor into aggregate efficiency scores.
Direct fleet contracting is displacing traditional dealer networks for high-volume buyers. Municipal procurement offices and logistics platforms now negotiate frame-integrated solar configurations at specification rather than selecting from retail SKUs. This channel compression is most advanced in Shanghai, where district-level fleet operators aggregate demand across food delivery, postal, and sanitation services.
China Solar E-Bike Market Segmentation
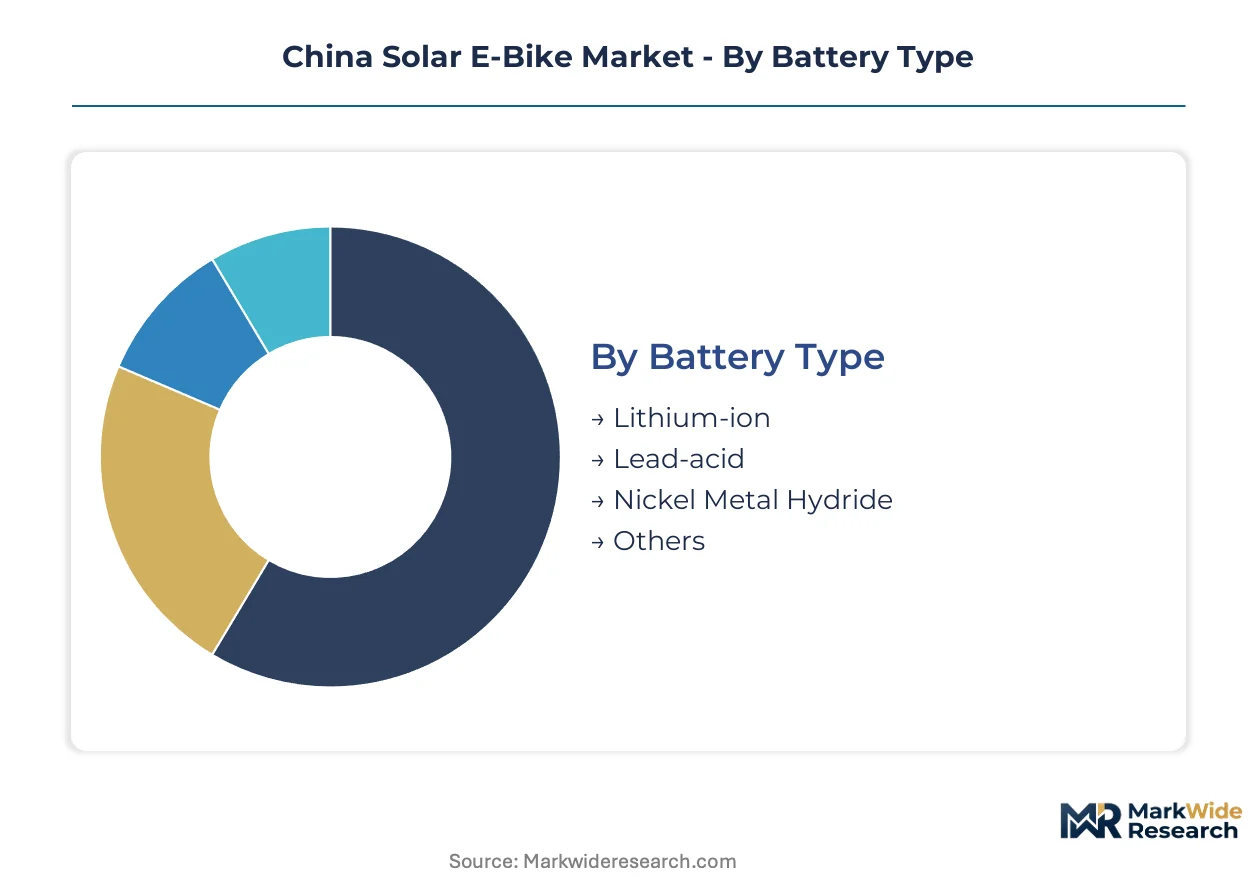
Segmentation in the China solar e-bike market reveals how MIIT efficiency grades and fleet procurement patterns concentrate value across distinct technical configurations. Battery chemistry and charging architecture determine subsidy eligibility and total cost of ownership for commercial operators.
Battery Type:
Lithium-ion packs turn over fastest in fleet procurement cycles as MIIT Grade 1 efficiency mandates accelerate replacement schedules, while lead-acid configurations persist longest in rural sub-markets despite regulatory penalties.
- Lithium-ion:High energy density cells (typically 18650 or 21700 format) dominate premium urban commuting and delivery fleet specifications. Demand clusters around Shanghai and Shenzhen municipal procurement programs where Grade 1 efficiency thresholds filter out alternatives.
- Lead-acid:Flooded and AGM variants retain cost advantage in tier-three and rural markets where upfront capital constraints outweigh operating cost penalties. Jiangsu and Anhui manufacturing corridors still produce these configurations for price-sensitive independent operators.
- Nickel Metal Hydride:Transitional chemistry occupying niche applications in temperature-extreme northern provinces where lithium-ion cold-weather performance degrades.
- Others:Emerging solid-state and sodium-ion prototypes under pilot evaluation by MIIT-certified research consortia.
Lithium-ion anchors the volume base while Others gains share at the steepest rate.
Application:
Cost tier stratification separates subsidy-eligible commercial fleets from discretionary consumer purchases, with delivery services commanding premium specifications and urban commuters balancing panel integration against parking economics.
- Urban Commuting:Premium frame-integrated photovoltaic models target white-collar workers in Hangzhou and Nanjing with daytime parking exposure. Solar yield optimization justifies panel cost for riders with predictable daylight routes.
- Delivery Services:Heavy-duty cargo configurations with reinforced frames and expanded panel surface area dominate Meituan and Ele.me contractor fleets. Municipal zero-emission mandates in Shanghai and Shenzhen pull volume through structured procurement.
- Leisure:Mid-range specifications balance aesthetic panel integration against recreational usage patterns with lower daily mileage requirements.
- Recreational:Entry-tier models prioritize cost containment over solar yield, often employing detachable panel accessories rather than frame integration.
Delivery Services commands the revenue concentration while Urban Commuting expands most quickly as parking infrastructure matures.
Charging Method:
Volume concentration favors hybrid architectures that mitigate solar yield seasonality, with pure solar charging remaining confined to premium segments where parking exposure is guaranteed.
- Solar Charging:Frame-integrated or cargo-mounted panels (15-50W typical) supplement battery packs during daylight operation. Adoption concentrates among premium urban commuting models in Jiangsu and Zhejiang where grid-integration pilots reduce range anxiety.
- Standard Plug-in:Conventional AC charging dominates legacy fleet configurations and rural markets with reliable grid access.
- Hybrid:Dual-mode systems combining photovoltaic supplementation with overnight AC charging capture the broadest commercial applicability. Fleet operators in the Yangtze River Delta prioritize this flexibility for year-round route reliability.
- Regenerative:Kinetic recovery systems augment braking energy capture in hilly Chengdu-Chongqing terrain where elevation changes justify additional hardware cost.
Hybrid captures the broadest installed base while Solar Charging climbs the fastest as panel integration costs decline.
Weight Capacity:
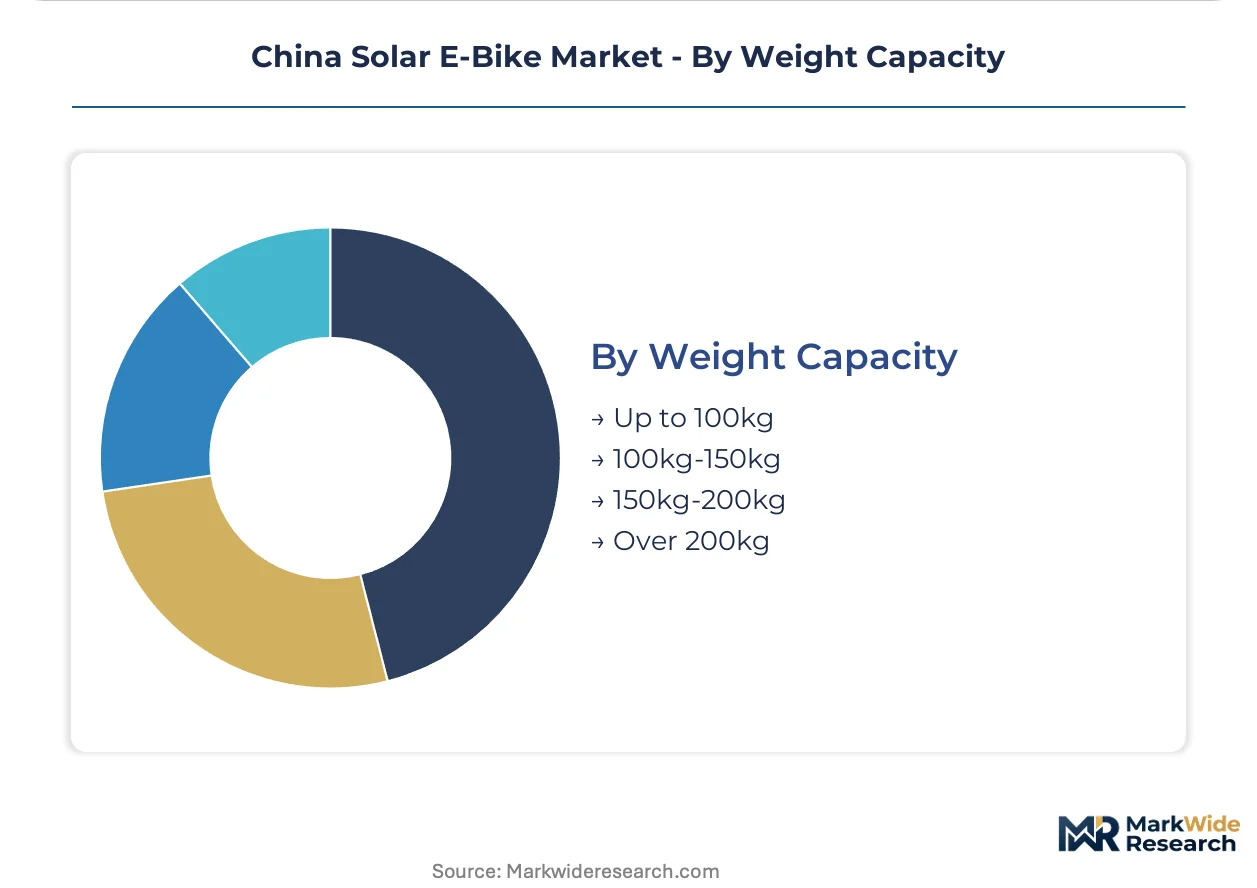
Supply concentration in Anhui and Jiangsu manufacturing zones favors mid-range capacity platforms, with extreme ratings requiring specialized frame engineering that fragments production economics.
- Up to 100kg:Lightweight urban commuting frames optimize for agility and parking convenience. Standard specifications for individual riders in dense tier-one cities.
- 100kg-150kg:Reinforced cargo configurations serve parcel-sorting hub feeder routes and multi-stop delivery circuits. This tier captures the densest production volume from integrated manufacturers.
- 150kg-200kg:Heavy-duty trike platforms penetrate municipal sanitation and postal services with standardized procurement specifications.
- Over 200kg:Specialized industrial applications including mobile vending and equipment transport with custom frame fabrication requirements.
100kg-150kg anchors production volume while 150kg-200kg gains share fastest as municipal fleet electrification broadens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai-Nanjing intercity high-speed rail corridor anchors the Yangtze River Delta's solar e-bike manufacturing density, enabling just-in-time component flows between Anhui assembly plants and Jiangsu photovoltaic suppliers.
Yangtze River Delta
Shanghai municipal fleet procurement aggregates demand across food delivery, postal, and sanitation services. MIIT's dual carbon goals channel subsidy eligibility toward vehicles demonstrating measurable fossil-fuel displacement. Wuxi and Changzhou manufacturing clusters concentrate frame-integrated panel production for premium urban commuting specifications.
Pearl River Delta
Shenzhen's zero-emission delivery mandates pull solar-assisted e-bike volumes through structured procurement programs. GB standards governing panel-to-frame electrical interoperability reduce system integration costs for qualified manufacturers. Dongguan and Foshan industrial zones supply reinforced cargo configurations for heavy-duty commercial applications.
Beijing-Tianjin-Hebei
Capital region fleet electrification policies target last-mile logistics operators with compliance deadlines. SAMR market access certification filters out non-compliant imports from neighboring manufacturing provinces. Tianjin port infrastructure handles polysilicon ingot imports for photovoltaic cell production.
Sichuan-Chongqing
Chengdu-Chongqing urban agglomeration lacks mature solar e-bike penetration despite comparable fleet electrification policies. Provincial grid-integration pilots in Chongqing defray total cost of ownership for commercial operators with daytime parking exposure. Local manufacturers occupy the mid-range cargo trike segment for parcel-sorting hub feeder routes.
Shandong Peninsula
Jinan and Qingdao manufacturing bases produce lead-acid configurations for price-sensitive rural sub-markets. MIIT efficiency grade penalties compress margins but do not eliminate demand in tier-three cities. Regional distributors maintain inventory for independent operators outside municipal procurement networks.
China Solar E-Bike Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in photovoltaic cells and battery management systems. Market structure concentrates among vertically integrated manufacturers with captive lithium-ion cell production and in-house frame fabrication. Three archetypes dominate: dealership-dense volume leaders, captive-cell technology anchors, and connected-vehicle software differentiators. Competitive moves center on direct fleet contracting displacement of retail networks and MIIT certification pre-emption through early Grade 1 efficiency compliance.
Among Yangtze River Delta-based fabricators, Yadea Technology Group Co., Ltd. and Jiangsu Xinri E-Vehicle Co., Ltd. represent the dealership-dense volume archetype, while BYD Co., Ltd. exemplifies the captive-cell technology anchor with in-house battery management systems. NIU Technologies occupies a position within the connected-vehicle software tier, differentiating through telematics integration rather than manufacturing scale. These three companies illustrate how strategic positioning splits between physical distribution density, upstream cell control, and digital service layers.
| Leading Market Players |
|---|
| Wuxi ALP Technology Co., Ltd. |
| Yadea Technology Group Co., Ltd. |
| Jiangsu Xinri E-Vehicle Co., Ltd. |
| Luyuan Group Co., Ltd. |
| BYD Co., Ltd. |
| Aima Technology Group Co. Ltd |
| Shenzhen TAILG Technology Group Co., LTD. |
| NIU Technologies |
| Sunra Electric Vehicle |
| Others |
Pricing and Supply Chain Analysis
The Shanghai-Nanjing intercity freight corridor channels polysilicon ingots from Xinjiang-based smelters to Jiangsu photovoltaic fabricators, compressing logistics costs for frame-integrated panel producers while amplifying price differentiation between MIIT Grade 1-certified fleet configurations and uncertified rural alternatives.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement dynamics. Premium urban commuting models with integrated photovoltaics command substantial markups based on MIIT Grade 1 efficiency certification and connected-vehicle software bundles. Cost compression in the economy tier intensifies because lead-acid battery displacement friction forces manufacturers to absorb margin erosion. Municipal fleet operators exhibit the lowest price sensitivity due to structured subsidy programs, while independent rural buyers remain highly cost-conscious.
Supply Chain Analysis
Contract manufacturing concentrates among Anhui and Jiangsu-based frame fabricators with captive lithium-ion cell assembly lines. Geographic supply concentration centers on China for photovoltaic cells and battery packs, with South Korea and Japan contributing high-grade electrolyte materials. Raw material dependencies include solar-grade polysilicon from Xinjiang, lithium carbonate from Qinghai salt lakes, and rare-earth magnets for hub motors. Single-source vulnerability in Xinjiang polysilicon ingot supply poses structural risk. Distribution runs through direct fleet contracting channels that displace traditional dealer networks for high-volume buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery-as-a-service subscription models expand faster than hardware sales, creating a service-attach opportunity where recurring revenue from swappable pack networks outpaces one-time vehicle transactions.
For Market Incumbents: Pre-empt MIIT certification timeline compression by accelerating Grade 1 efficiency compliance investments before revised GB standard cycles take effect. Defend position against connected-vehicle software differentiators by deepening telematics integration or acquiring specialized battery management system developers. Channel control through direct municipal fleet contracting remains essential. For New Entrants and Emerging Players: The Chengdu-Chongqing urban agglomeration represents the most penetrable entry point, lacking mature solar e-bike penetration despite fleet electrification policies comparable to coastal municipalities. Mid-range cargo trike specifications for parcel-sorting hub feeder routes offer lower competitive density than premium urban commuting. A go-to-market angle anchored to provincial grid-integration pilots in Chongqing defrays customer total cost of ownership concerns. For Investors and Strategic Acquirers: Connected-vehicle software specialists with proven telematics platforms and municipal fleet deployment records offer the strongest acquisition profile. Long-term viability hinges on regulatory alignment with tightening MIIT efficiency mandates rather than manufacturing scale alone. Watch for inflection signals in provincial subsidy tier adjustments that reshape total cost of ownership calculations across buyer segments.| Strategic Initiative | Industry Significance |
|---|---|
| MIIT Grade 1 Certification Investment | Secures subsidy eligibility in Shanghai and Shenzhen municipal procurement programs. |
| Direct Fleet Contracting Expansion | Displaces dealer networks for Meituan and Ele.me contractor volume aggregation. |
| Telematics Platform Integration | Enables predictive deployment optimization for food delivery route planning. |
| Battery-as-a-Service Model Launch | Decouples upfront capital burden from solar range extension benefits for operators. |
| Western China Manufacturing Footprint | Captures Chengdu-Chongqing demand before incumbent dealership density solidifies. |
Research Methodology
Cross-validation between MIIT regulatory filings and municipal procurement databases anchors the qualitative findings. Primary interviews with fleet operations managers at Meituan and Ele.me contractors, photovoltaic cell procurement leads at Jiangsu manufacturing clusters, and SAMR certification specialists combined with secondary validation from GB standards documentation, provincial subsidy tier announcements, and polysilicon trade flow records. Bottom-up and top-down triangulation reconciles manufacturer shipment data with municipal fleet electrification mandate compliance tracking.
Calibration against historical MIIT efficiency grade adoption curves and lithium-ion battery cost decline trajectories shapes the analytical framework. Segmentation dimensions modeled include battery chemistry tier, application use case, charging architecture, and weight capacity class across the projection horizon. CAGRs derive from polynomial fitting to observed procurement volume patterns and subsidy eligibility phase-out schedules. Forecast inputs incorporate seasonal solar yield variation across northern and southern provinces and fleet replacement cycle acceleration under zero-emission mandates.
Practitioners should monitor MIIT efficiency grade recalibration announcements and polysilicon ingot supply disruptions from Xinjiang-based smelters for early signals requiring forecast revision. Quarterly review of municipal procurement tender volumes and provincial grid-integration pilot expansion rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Transporters Market
Electric Vehicles
Lithium Battery Electric Scooters Market
Electric Vehicles
China Automotive High Performance Electric Vehicle Market
Electric Vehicles
Electric Vehicle Transmission Market
Electric Vehicles
United Kingdom Hybrid Electric Vehicle Battery Market
Electric Vehicles
Extended Range Electric Vehicle (EREV) Market
Electric Vehicles
Asia-Pacific Train Battery Market
Electric Vehicles
Oman Electric Vehicle (EV) Market
Electric Vehicles
North America Electric Bus Market
Electric Vehicles
Germany Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
Global Automotive High-Performance Electric Vehicles Market
Electric Vehicles
Canada E-Bike Market
Electric Vehicles
Electric Car Rental Market
Electric Vehicles
Global Solar Powered Car Market
Electric Vehicles
Electric Vehicle HVAC Market
Electric Vehicles
E-Rickshaw Market