
 GCC Electronic Toll Collection Market | 2026-2036
GCC Electronic Toll Collection Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Electronic Toll Collection Market Intelligence
Modular service bundling is repositioning how toll operators procure electronic toll collection systems, shifting from hardware-centric contracts to integrated transaction-processing and maintenance packages. Kapsch TrafficCom AG leverages its end-to-end system integration capabilities across Middle Eastern deployments. Siemens AG anchors its position through deep manufacturing scale in roadside unit production. Thales Group differentiates via encryption-heavy back-office platforms that appeal to security-conscious highway authorities.
Electronic toll collection encompasses automated systems that identify vehicles and collect fees without requiring drivers to stop, typically employing RFID transponders, dedicated short-range communication at 5.8 GHz, automatic number plate recognition with infrared illumination, and video analytics for enforcement and audit trails. Its primary commercial purpose is to maximize throughput on congested corridors while ensuring revenue integrity for infrastructure financing. RFID and DSRC technologies dominate installed capacity across Gulf Cooperation Council states, though ANPR is gaining share where transponder penetration remains uneven. Transaction processing services command the most stable margin pools because operators sign multi-year contracts with built-in escalation clauses, while data analytics represents the fastest-expanding service type as authorities seek origin-destination patterns for urban planning.
Saudi Arabia's Communications, Space and Technology Commission sets interoperability mandates for DSRC protocols, while the UAE's Telecommunications and Digital Government Regulatory Authority governs spectrum allocation for tolling applications. Qatar's Ministry of Transport enforces compliance with Gulf Standardization Organization technical regulations for cross-border tag recognition. Stakeholders must monitor how each regulator's timeline for next-generation 5G-V2X trials could obsolete current roadside communication hardware before depreciation cycles complete.
Market Dynamics
Highway authorities across Saudi Arabia, the UAE, and Qatar are consolidating procurements under multi-decade concession frameworks that bundle roadside infrastructure, back-office transaction processing, and enforcement services into single-source contracts.
Growth Catalysts
- Saudi Arabia's National Transport Strategy:The strategy mandates interoperable DSRC protocols across the Riyadh-Dammam logistics corridor, compelling coordinated roadside unit deployment.
- Urban congestion pricing:Municipal authorities in Dubai and Abu Dhabi are converting free-flowing arterial roads into tolled express lanes to manage peak-hour throughput.
- 5.8 GHz spectrum harmonization:Gulf Standardization Organization technical regulations enable cross-border tag recognition, supporting seamless vehicle movement between member states.
Market Restraints
- Semiconductor supply concentration:Roadside unit production depends on specialized RF chipsets sourced from a limited supplier base in East Asia, creating delivery volatility.
- Depreciation cycle misalignment:Current DSRC hardware carries 10-12 year amortization schedules while 5G-V2X trials threaten technical obsolescence within 7-8 years.
- Transponder penetration gaps:Rental vehicle fleets and cross-border commercial traffic exhibit uneven tag adoption, forcing parallel ANPR infrastructure investment.
Strategic Opportunities
- Qatar's Lusail smart city integration:The greenfield urban development offers embedded tolling infrastructure without legacy system retrofit constraints.
- Data monetization frameworks:Origin-destination analytics derived from tolling transactions are expanding into urban planning and logistics optimization services.
- Multi-modal payment convergence:Integration with national digital wallet platforms enables seamless toll settlement alongside parking and transit fares.
Industry Challenges
- RF engineering specialization shortage:The region lacks sufficient technicians trained in 5.8 GHz antenna calibration and roadside unit field maintenance.
- Legacy gantry integration complexity:Existing toll plazas with mixed-lane configurations require phased retrofitting that disrupts revenue collection during construction windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Electronic Toll Collection Market |
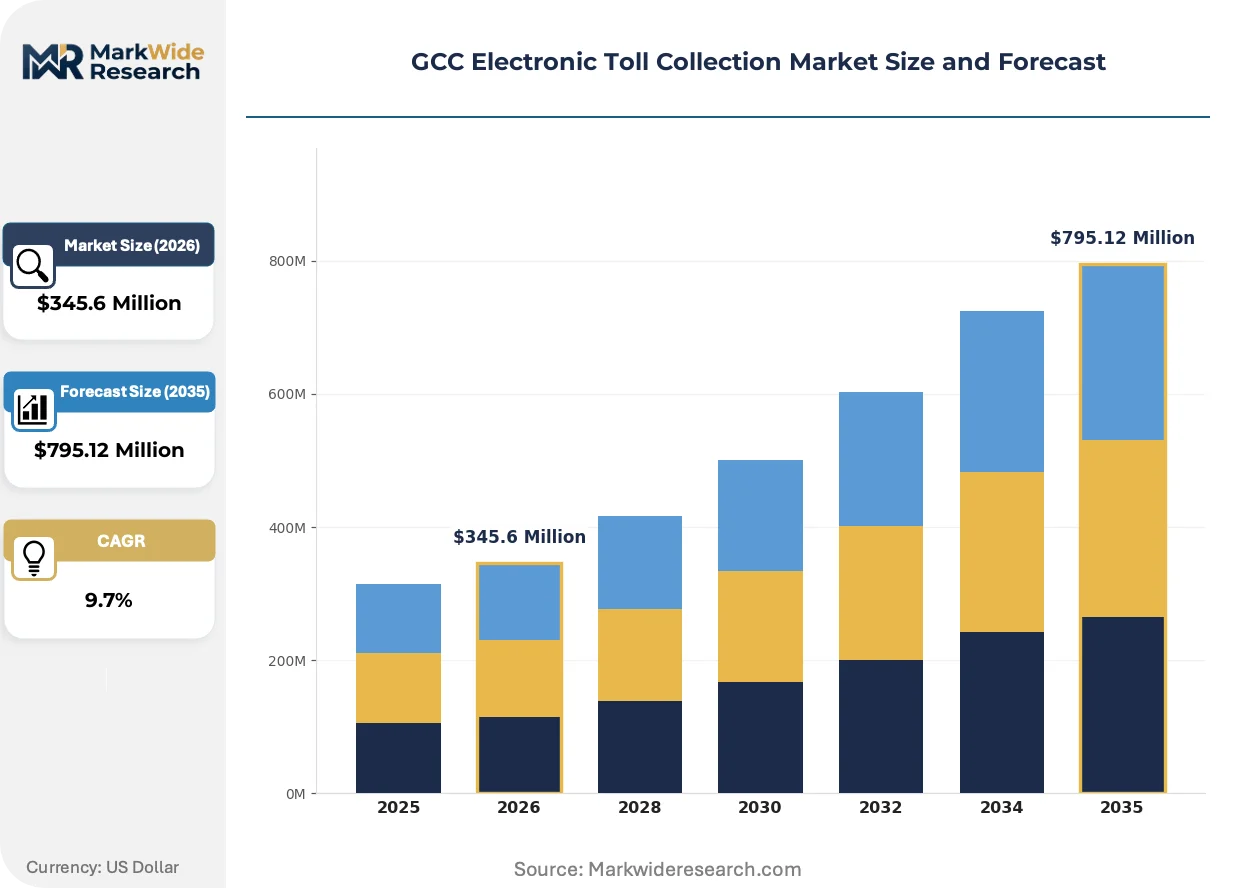
| Market Size in 2026 | $345.6 Million |
| Market Size in 2035 | $795.12 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: RFID, ANPR, DSRC, Video Processing End User: Public Agencies, Toll Operators, Highway Authorities, Private Investors Service Type: Transaction Processing, Customer Support, Data Analytics, Maintenance Deployment: Cloud-Based, On-Premise, Hybrid, Mobile |
| Companies Covered | Kapsch TrafficCom AG, Thales Group, EFKON GmbH, TransCore, Conduent Incorporated, Cubic Corporation, Siemens AG, Q-Free, ST Engineering, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Electronic Toll Collection Market Strategic Shifts & Innovations
Technology roadmaps across Gulf highway authorities are pivoting from standalone tolling systems toward integrated mobility platforms that fuse vehicle identification with congestion management and emissions monitoring.
Multi-lane free-flow tolling is expanding into urban arterial networks beyond traditional highway applications. Dubai's Roads and Transport Authority is retrofitting Sheikh Zayed Road corridors with gantry-less ANPR arrays that eliminate physical infrastructure footprint. The technology is compressing deployment timelines from 18-month construction cycles to 4-month software-calibration rollouts.
Saudi Arabia's Communications, Space and Technology Commission has issued interoperability mandates requiring all new DSRC deployments to support dual-protocol roadside units capable of both 5.8 GHz and emerging C-V2X standards. The regulation forces equipment vendors to engineer backward-compatible hardware that protects authority capital investments against spectrum reallocation. Suppliers are responding with modular roadside unit architectures that permit field-upgradable communication modules.
Service contracting patterns among highway authorities are unbundling long-term maintenance obligations from initial capital procurements. Saudi Arabia's Riyadh-Dammam corridor operator now separates 5-year roadside infrastructure warranties from 15-year transaction processing service agreements. The shift permits specialized fintech providers to compete against integrated system vendors for back-office revenue streams. Qatar's Ministry of Transport has adopted this bifurcated model for its upcoming North-South expressway phase.
GCC Electronic Toll Collection Market Segmentation
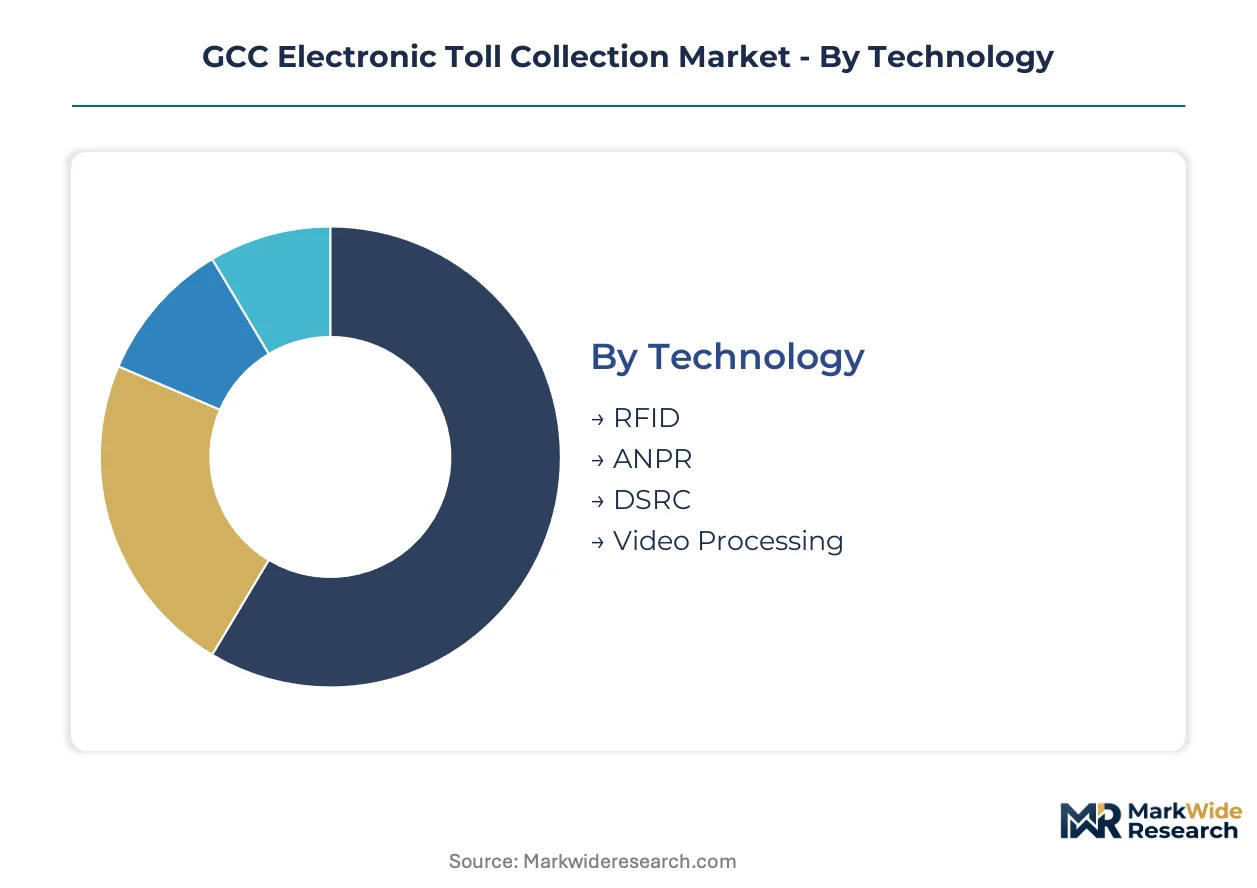
Technology choices in GCC tolling infrastructure carry long capital cycles and regulatory lock-in effects. Procurement patterns across Saudi Arabia, the UAE, and Qatar reveal how authorities balance interoperability mandates against obsolescence risk when segmenting system investments.
Technology:
RF chipset sourcing from East Asian foundries concentrates supply risk for roadside unit vendors serving Gulf highway authorities.
- RFID:Passive transponders operating at 5.8 GHz remain the workhorse for vehicle identification across Saudi Arabia's Riyadh-Dammam corridor. The Communications, Space and Technology Commission mandates backward-compatible readers, protecting installed base investments while constraining vendor innovation cycles.
- ANPR:Infrared-illuminated camera arrays with neural-network classification now handle enforcement gaps where rental fleets and cross-border commercial traffic lack tags. Dubai's Roads and Transport Authority deploys gantry-less configurations on Sheikh Zayed Road to eliminate physical infrastructure footprint.
- DSRC:Active transponder systems enable two-way communication for congestion pricing and priority lane access. Qatar's Ministry of Transport specifies dual-protocol units supporting future C-V2X migration.
- Video Processing:Edge-computing analytics for license plate recognition and vehicle classification run on roadside servers with localized inference. The UAE's Telecommunications and Digital Government Regulatory Authority governs data residency for captured imagery.
Today's leader: RFID. Tomorrow's challenger: ANPR.
End User:
Procurement consolidation under multi-decade concessions is compressing the vendor base serving Gulf tolling clients.
- Public Agencies:Municipal transport departments in Dubai and Abu Dhabi specify open-road tolling for urban congestion management. Budget cycles align with federal infrastructure spending programs.
- Toll Operators:Concession holders on Saudi Arabia's logistics corridors bundle roadside infrastructure with transaction processing under unified service contracts. Revenue-sharing clauses with highway authorities determine technology refresh timelines.
- Highway Authorities:Saudi Arabia's National Transport Strategy and the UAE's smart mobility mandates drive standardization across interoperable networks. Procurement teams prioritize multi-vendor compatibility to avoid single-source dependency.
- Private Investors:Infrastructure funds participating in GCC public-private partnerships demand predictable maintenance cost structures. Fifteen-year service agreements with built-in escalation clauses attract yield-focused capital.
Primary volume flows through highway authorities. Private investors command the steepest expansion trajectory as concession frameworks proliferate.
Service Type:
Margin stability varies sharply across service tiers, with multi-year contracts creating divergent competitive dynamics.
- Transaction Processing:Back-office platforms handling toll settlement, account management, and payment reconciliation generate recurring revenue under 10-15 year agreements. Saudi Arabia's Riyadh-Dammam operator now unbundles these services from infrastructure warranties.
- Customer Support:Call center operations and transponder distribution networks serve account holders across tag lifecycle events. The UAE's integration with national digital wallet platforms is compressing traditional support touchpoints.
- Data Analytics:Origin-destination pattern extraction from tolling transactions expands into urban planning and logistics optimization. Qatar's Lusail smart city embeds these capabilities without legacy data silos.
- Maintenance:Field service for roadside units requires RF engineering specialization that the region currently undersupplies. Vendors with captive technician training programs defend renewal rates.
Transaction processing anchors current revenue. Data analytics is gaining share fastest as authorities commercialize mobility intelligence.
Deployment:
Architecture choices reflect sovereignty requirements and latency constraints for enforcement-critical applications.
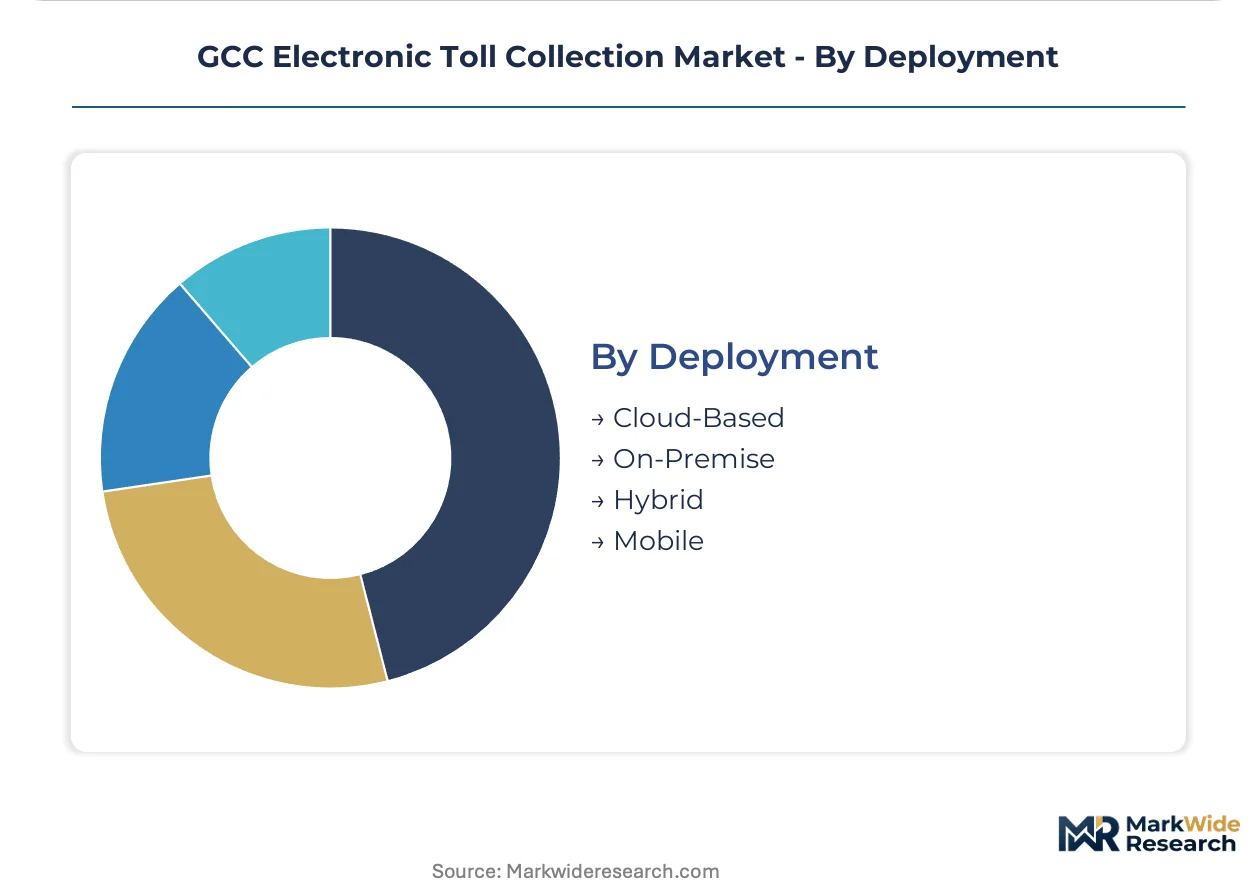
- Cloud-Based:Scalable transaction processing and analytics workloads run on hyperscaler infrastructure with regional data centers. Saudi Arabia's regulatory frameworks govern financial data residency for toll settlements.
- On-Premise:Air-gapped systems serve high-availability requirements for enforcement and revenue protection. Critical roadside controllers maintain local autonomy during network outages.
- Hybrid:Edge processing for real-time vehicle identification couples with cloud analytics for pattern recognition. The configuration balances latency requirements against computational cost.
- Mobile:Smartphone-based toll settlement via GPS geofencing and app-mediated payment gains traction for occasional users. Adoption remains constrained by transponder mandates on heavy commercial routes.
Hybrid architectures dominate new procurements. Pure cloud deployment is climbing the fastest as regulatory clarity on data sovereignty solidifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The GCC electronic toll collection industry traces its commercial roots to Dubai's 2007 Salik system deployment, which established the region's first open-road tolling precedent and subsequently shaped procurement standards across Gulf highway authorities.
Saudi Arabia
The Riyadh-Dammam logistics corridor drives DSRC infrastructure demand as freight volumes surge along the eastern seaboard. The Communications, Space and Technology Commission enforces interoperability mandates for 5.8 GHz protocols. Jeddah's urban expansion is converting arterial roads into free-flow tolled expressways to manage peak congestion.
United Arab Emirates
Dubai's Roads and Transport Authority anchors regional innovation with gantry-less ANPR arrays on Sheikh Zayed Road corridors. The Telecommunications and Digital Government Regulatory Authority governs spectrum allocation for tolling applications. Abu Dhabi is retrofitting arterial networks with congestion pricing to manage inter-emirate commuter flows.
Qatar
The Lusail smart city greenfield offers embedded tolling without legacy retrofit constraints. The Ministry of Transport enforces Gulf Standardization Organization technical regulations for cross-border tag recognition. Doha's North-South expressway phase adopts bifurcated procurement separating infrastructure from transaction processing services.
Kuwait
Planned logistics corridor upgrades are prompting feasibility studies for interoperable tolling systems. The Ministry of Public Works coordinates with Gulf Standardization Organization harmonization timelines. The Jahra Road industrial zone is evaluating congestion management infrastructure to support port connectivity.
GCC Electronic Toll Collection Market Key Industry Players
Premium-margin players sit above commodity-margin players across integration depth and service bundling sophistication. The vendor base concentrates around three tiers: end-to-end system integrators commanding concession-scale contracts, component specialists supplying roadside hardware at volume, and transaction processing fintechs unbundling back-office services. Consolidation pressures are intensifying as highway authorities favor single-source procurement frameworks. Technology licensing partnerships and modular hardware architectures represent the dominant competitive vectors.
Within the integrated systems tier, Kapsch TrafficCom AG and Siemens AG exemplify European engineering heritage applied to Gulf deployment scale. Thales Group occupies a position emphasizing encryption-intensive platforms for security-sensitive highway authorities. These three anchors illustrate how vendor selection increasingly hinges on backward-compatible hardware roadmaps that protect authority capital investments against spectrum evolution.
| Leading Market Players |
|---|
| Kapsch TrafficCom AG |
| Thales Group |
| EFKON GmbH |
| TransCore |
| Conduent Incorporated |
| Cubic Corporation |
| Siemens AG |
| Q-Free |
| ST Engineering |
| Others |
Cost & Logistics Intelligence
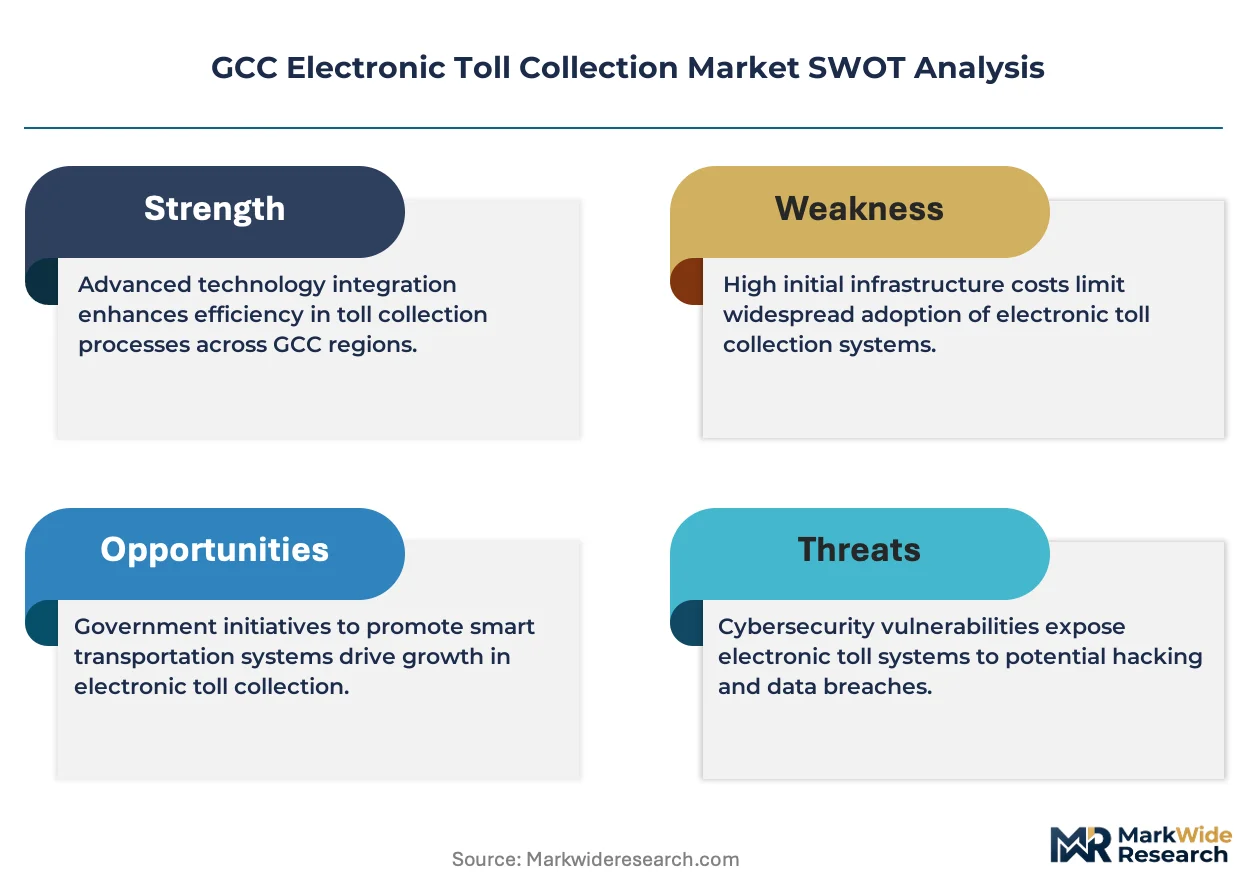
Highway authority procurement consolidation across Saudi Arabia, the UAE, and Qatar anchors pricing power with multi-decade concession holders who negotiate bundled infrastructure-and-service contracts. These buyers extract volume discounts from roadside unit vendors while accepting premium pricing for encryption-intensive back-office platforms that protect revenue integrity.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates end-to-end system integrators from component specialists and transaction-processing fintechs. Price differentiation rests on certification grade for Gulf Standardization Organization compliance and after-sales service bundling with multi-year maintenance clauses. Cost compression in standard-tier roadside hardware is intensifying because semiconductor supply concentration in East Asian foundries limits vendor margin flexibility. Toll operators exhibit the sharpest price sensitivity due to revenue-sharing clauses with highway authorities, while private infrastructure funds accept premium pricing for predictable 15-year service agreements.
Supply Chain Analysis
RF engineering technician shortages in the GCC region and specialized antenna calibration expertise gaps in European manufacturing hubs constrain roadside unit production scaling. Hardware assembly draws from Germany, Austria, and South Korea for precision RF components and edge-computing modules. Supply chain risk centers on single-source vulnerability for 5.8 GHz chipsets sourced from Taiwan-based foundries. Distribution runs through direct procurement frameworks where highway authorities issue concession-scale tenders to integrated system vendors rather than component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market is accelerating through unbundled transaction-processing contracts that separate high-margin back-office services from capital-intensive roadside infrastructure. This shift permits specialized fintech providers to capture recurring revenue streams without bearing hardware depreciation risk.
For Market Incumbents: Extend backward integration into RF chipset sourcing to defend against East Asian supply volatility threatening roadside unit delivery timelines. Deepen captive technician training programs across Saudi Arabia and the UAE to counter regional RF engineering specialization gaps that constrain maintenance renewal rates. Prioritize modular roadside unit architectures that permit field-upgradable communication modules, protecting concession holders against 5G-V2X spectrum reallocation before depreciation cycles complete.
For New Entrants and Emerging Players: Capture unbundled transaction-processing service contracts in Qatar's North-South expressway phase and Saudi Arabia's Riyadh-Dammam corridor expansion, where highway authorities now separate 15-year back-office agreements from infrastructure warranties. Target data analytics white space in Qatar's Lusail smart city, where greenfield deployment eliminates legacy data silo integration burdens. Lead with cloud-native origin-destination pattern extraction platforms that appeal to municipal urban planning departments seeking mobility intelligence.
For Investors and Strategic Acquirers: Infrastructure funds with yield-focused mandates are the most active acquirer in this space, drawn to predictable maintenance cost structures and built-in escalation clauses in long-term service agreements. Acquisition target archetypes include transaction-processing fintechs with established highway authority relationships and modular hardware vendors with dual-protocol DSRC-C-V2X capabilities. Watch 5G-V2X trial timelines from the Communications, Space and Technology Commission as the signal indicating potential technical obsolescence risk for current roadside communication hardware.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Protocol Roadside Unit Development | Backward-compatible hardware protects Saudi authority capital investments against spectrum evolution. |
| Transaction Processing Unbundling | Specialized fintechs compete for 15-year back-office revenue streams in Qatar's expressway phase. |
| Gantry-Less ANPR Deployment | Dubai's Roads and Transport Authority compresses deployment timelines from 18-month cycles to 4-month rollouts. |
| Data Monetization Framework | Origin-destination analytics from tolling transactions expand into logistics optimization services. |
| National Digital Wallet Integration | UAE's integration enables seamless toll settlement alongside parking and transit fares. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with highway authority procurement directors, toll operator concession managers, roadside unit field engineers, and transaction-processing platform architects with secondary validation. Regulatory filings from the Communications, Space and Technology Commission, the Telecommunications and Digital Government Regulatory Authority, and the Gulf Standardization Organization provided compliance timeline data. Bottom-up project pipeline tracking across Saudi Arabia's Riyadh-Dammam corridor and Qatar's Lusail development triangulated against top-down concession value estimates.
Historical deployment data across the analysis window anchored forward projections for roadside infrastructure spend, transaction processing contract values, and data analytics service adoption. Segmentation dimensions modeled include technology type, end-user category, service tier, and deployment architecture, with cross-border tag recognition mandates and spectrum harmonization timelines as industry-specific forecast inputs. CAGRs were derived from fitted growth curves applied to disclosed contract values and authority budget allocations.
Regulatory timeline delays, semiconductor supply disruptions, and 5G-V2X commercialization acceleration are the dominant revision risks that could compress or extend hardware replacement cycles. Forecasts reflect documented assumptions regarding interoperability mandate enforcement and concession framework proliferation. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Real-Time Parking System Market
Smart Transportation Solutions
Automotive Platooning Systems Market
Smart Transportation Solutions
Global IoT in Transportation Market
Smart Transportation Solutions
Mobility As a Service Market
Smart Transportation Solutions
Smart Car Digital Key System Market
Smart Transportation Solutions
Smart Parking Systems Market
Smart Transportation Solutions
Road Asset Management Software Market
Smart Transportation Solutions
Semi Height Platform Screen Door Market
Smart Transportation Solutions
Middle East and Africa Passenger Information System Market
Smart Transportation Solutions
Smart Ports Market
Smart Transportation Solutions
Automotive Digital Mapping Market
Smart Transportation Solutions
France Ridesharing Market
Smart Transportation Solutions
Monorail System Market
Smart Transportation Solutions
Automotive V2X Market
Smart Transportation Solutions
Autonomous Warehouse Charging Infrastructure Market
Smart Transportation Solutions
Smart Bus Shelters Market