
 Shared Vehicles Market | 2026-2036
Shared Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Shared Vehicles Market Intelligence
Subscription-based fleet maintenance is shifting how shared vehicle operators monetize asset uptime. Uber Technologies Inc. leverages its driver network density to sustain urban coverage advantages. Beijing Xiaoju Technology Co., Ltd. anchors its position through proprietary mapping and dispatch algorithms. Grab Holdings Inc. differentiates via super-app integration across Southeast Asian markets.
Shared vehicles denote motorized and non-motorized assets deployed through short-term access models rather than ownership transfer, typically integrating GPS telematics, IoT lock systems, and cloud-based reservation platforms for real-time availability management. Car-sharing commands the largest revenue pool due to higher per-trip yields and corporate account penetration, while scooter-sharing records the fastest expansion driven by sub-five-kilometer urban trips and lower capital requirements per deployed unit. Bike-sharing occupies a mature position in European and Chinese cities where docked infrastructure density limits new entrant margin capture.
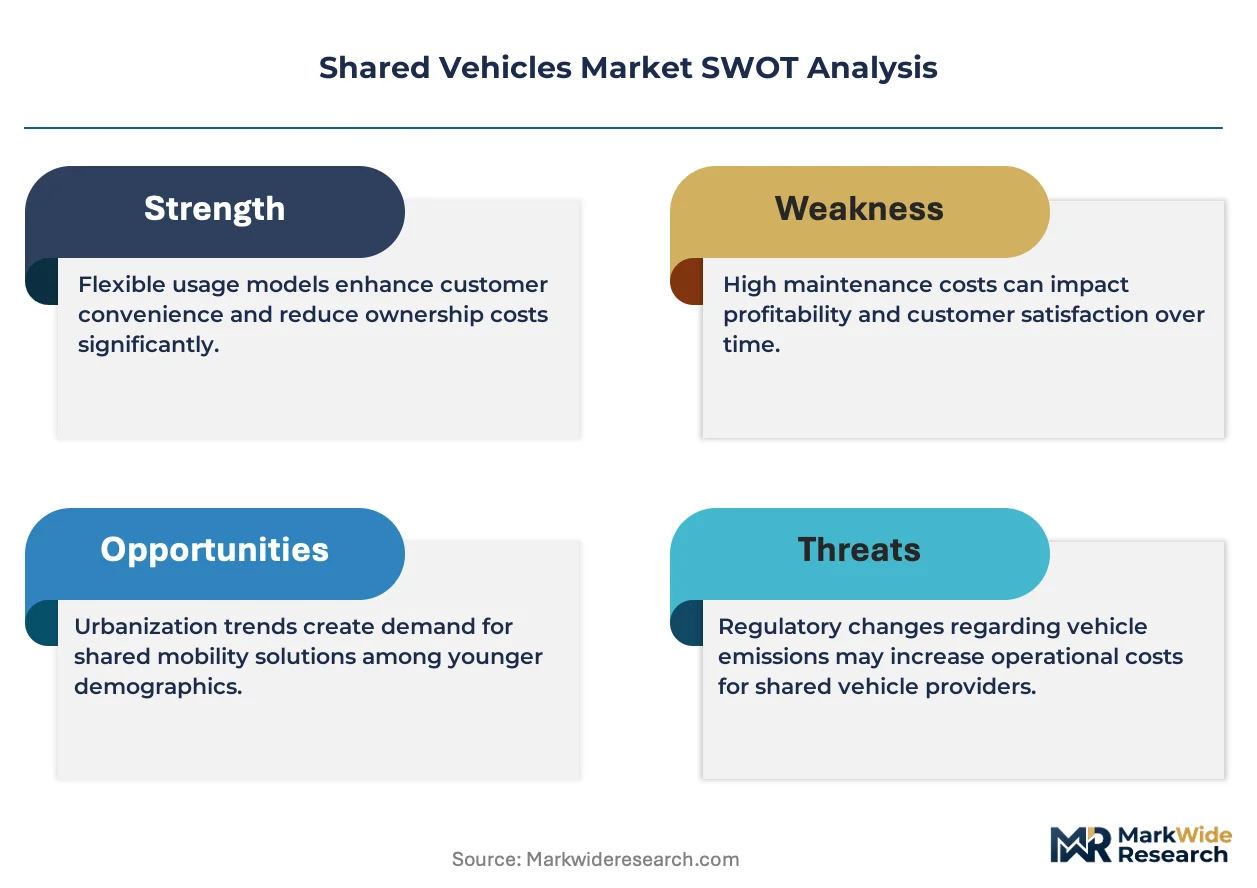
FAA regulations govern drone-based shared mobility pilots in US airspace, while EU Green Deal emission targets pressure fleet operators toward electrification compliance. India's CEA mandates charging infrastructure disclosures for electric shared fleets above threshold vehicle counts. Stakeholders must monitor how software-defined vehicle capabilities reshape liability frameworks between platform operators and individual drivers.
Market Dynamics
Battery-swapping infrastructure standardization from China's MIIT is compressing fleet turnaround times and reshaping capital deployment models for electric two-wheeler operators. Platform economics now hinge on asset utilization rates rather than per-ride margins.
Growth Catalysts
- CEA charging mandates:India's Central Electricity Authority requires infrastructure disclosures for electric fleets above threshold counts, accelerating formalization of charging networks in Delhi, Mumbai, and Bangalore.
- Corporate commuter benefits:Urban employers in Germany and the United States are integrating fleet contracts into employee packages, expanding B2B revenue pools beyond individual ride-hail demand.
- IoT lock systems:Cloud-connected hardware enables real-time availability management and theft reduction, lowering insurance burdens for scooter-sharing operators.
Market Restraints
- Lithium-ion supply concentration:Cathode material processing clusters in China's Jiangsu and Hunan provinces create input cost volatility for battery-dependent fleets.
- FAA airspace restrictions:Drone-based shared mobility pilots in United States urban corridors face altitude and corridor limitations that constrain route density.
- Docked bike infrastructure lock-in:Mature European cities with high station density limit margin capture for new entrants unable to secure municipal permits.
Strategic Opportunities
- Tier-two Indian expansion:Jaipur, Lucknow, and Indore present underpenetrated demand for last-mile connectivity as Ola and Uber concentrate firepower on Delhi and Mumbai.
- EU Green Deal electrification:Emission targets pressure fleet operators toward full-electric compliance, creating first-mover advantages for platforms with charging infrastructure.
- Super-app convergence:Integration of ride-hail, food delivery, and financial services within single interfaces raises switching costs and lifetime value per user in Southeast Asian markets.
Industry Challenges
- Software-defined vehicle liability:Over-the-air updates and autonomous features complicate fault determination between platform operators and individual drivers.
- Telematics technician scarcity:Fleet maintenance networks lack sufficient trained personnel for GPS and IoT hardware diagnostics at scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shared Vehicles Market |
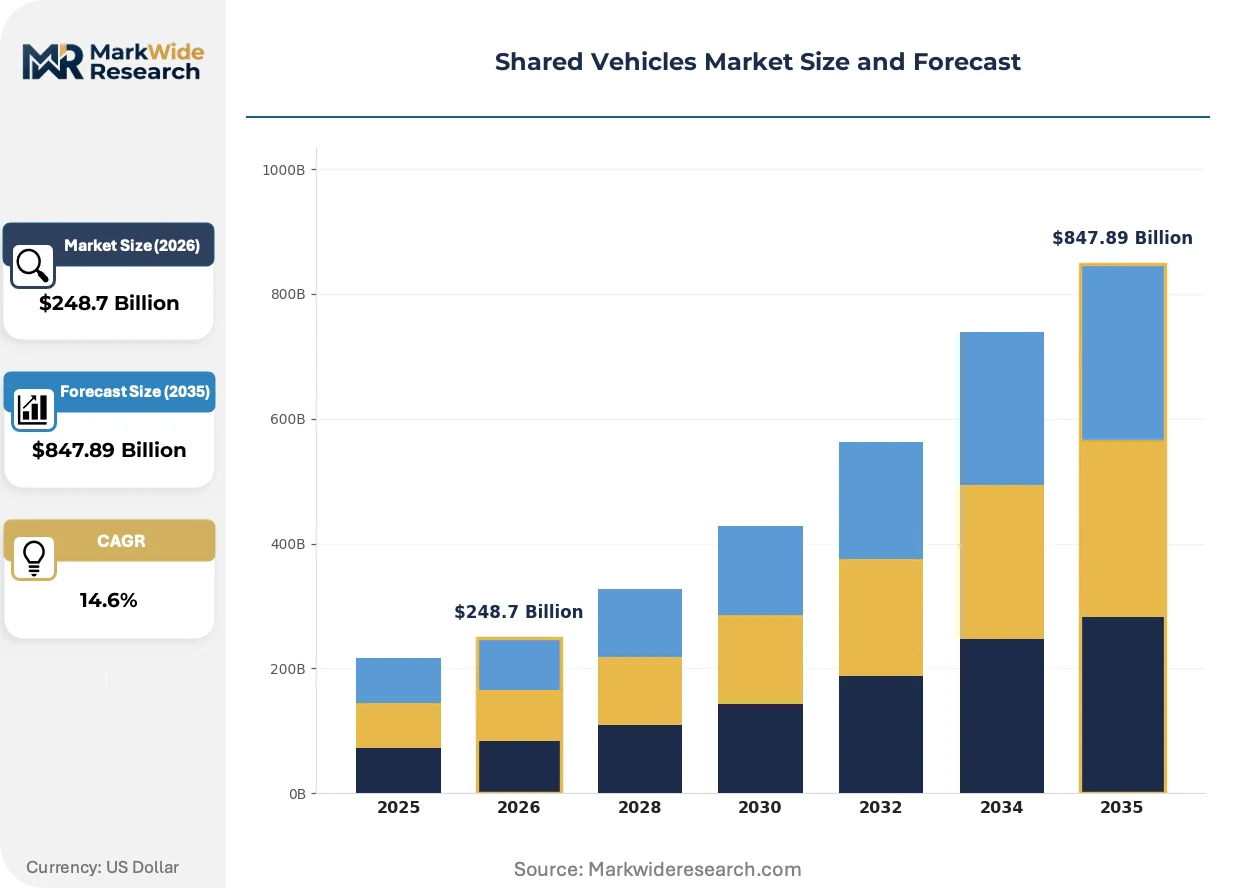
| Market Size in 2026 | $248.7 Billion |
| Market Size in 2035 | $847.89 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Car, Scooter, Bicycle, Van Service Type: Ride-sharing, Car-sharing, Bike-sharing, Scooter-sharing End User: Corporate, Individual, Fleet Operators, Governments Distribution Channel: Mobile App, Website, Kiosk, Third-party Platforms |
| Companies Covered | Uber Technologies Inc., Lyft, Inc., Beijing Xiaoju Technology Co., Ltd. (Didi Chuxing), Grab Holdings Inc., ANI Technologies Pvt. Ltd. (Ola Cabs), Zipcar Inc., SIXT SE, Hertz Global Holdings, Inc., Bolt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shared Vehicles Market Strategic Shifts & Innovations
Telematics hardware, cloud reservation platforms, and payment infrastructure are fusing into unified technology stacks that determine competitive positioning more than vehicle brand or fleet size.
Edge computing for real-time dispatch optimization is converging with 5G network slicing to enable sub-100-millisecond vehicle-to-infrastructure communication. Shared mobility platforms in Seoul and Singapore are deploying these capabilities to compress rider wait times below three minutes during peak hours. The technology is converging with dynamic pricing algorithms to match supply granularity with demand spikes at transit hubs and event venues.
The EU AI Act's risk classification framework for automated decision-making systems imposes documentation and human oversight requirements on route optimization algorithms. Fleet operators must now maintain algorithmic impact assessments for dispatch systems affecting driver earnings. Car-sharing platforms in France and Germany are responding by segregating automated pricing from automated routing to limit regulatory exposure.
Subscription-based fleet access is displacing per-trip purchasing among corporate accounts and frequent urban commuters. Monthly unlimited-ride packages now dominate procurement patterns for technology sector employers in Bangalore and Austin. This shift is most visible in employer-subsidized programs where HR departments negotiate bulk rates in exchange for guaranteed minimum commitments.
Shared Vehicles Market Segmentation
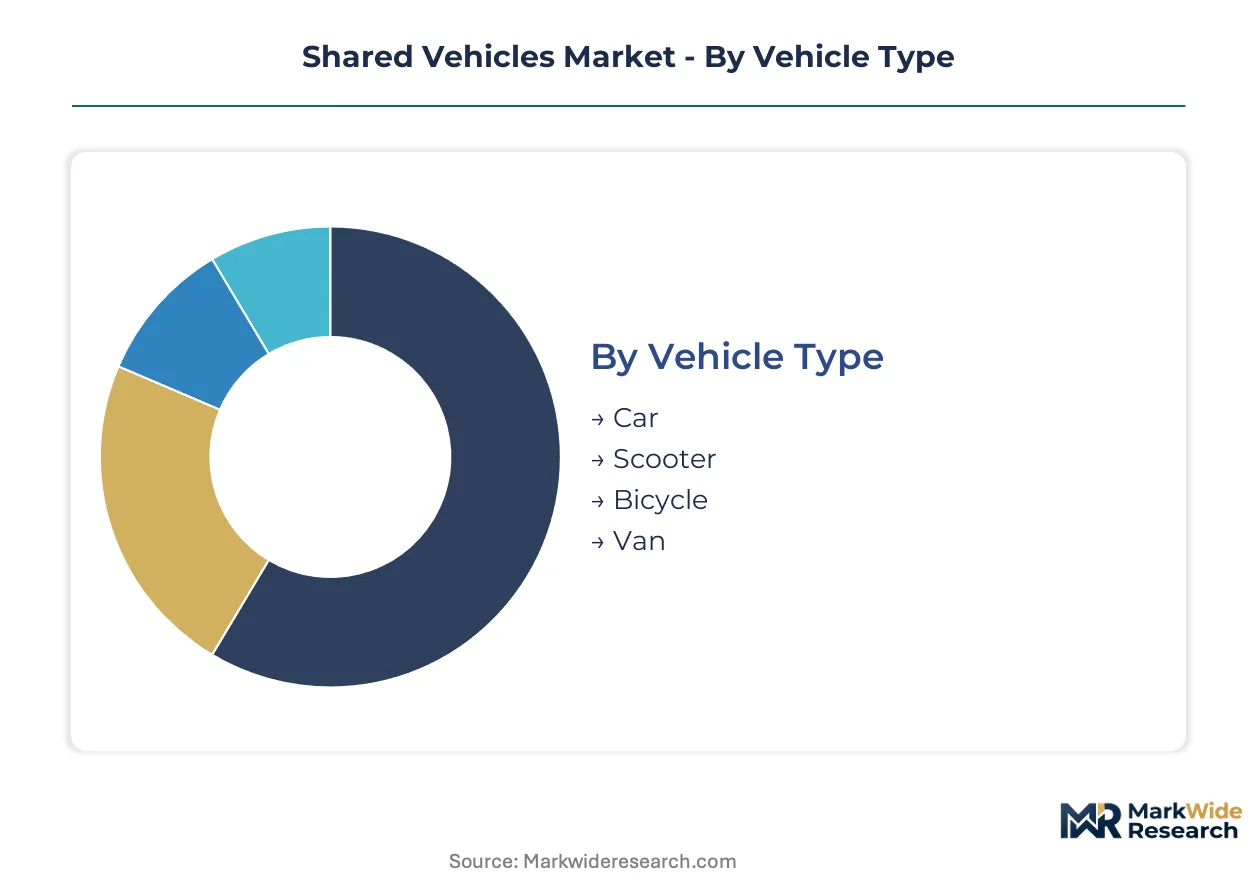
Segmentation in shared vehicles reveals how capital deployment, utilization economics, and regulatory exposure vary across asset classes and access models. Platform operators configure technology stacks and pricing architectures differently for each segment, creating distinct margin profiles and competitive barriers.
Vehicle Type:
Capital intensity and regulatory compliance requirements separate fleet buyers across vehicle categories.
- Car:Four-wheel assets command the highest per-unit acquisition costs and insurance burdens. Demand concentrates in corporate commuter programs across Germany and the United States where employers subsidize monthly access for white-collar workforces.
- Scooter:Electric two-wheelers with swappable battery architectures dominate last-mile connectivity in India's tier-one cities. China's MIIT standardization is compressing turnaround times and lowering capital deployment thresholds for fleet operators.
- Bicycle:Docked and dockless pedal assets occupy mature positions in European and Chinese urban cores where municipal permit density limits new entrant margin capture.
- Van:Light commercial vehicles serve B2B logistics and small-business cargo needs with higher per-trip yields but lower utilization rates than passenger assets.
Volume sits with Car; growth tilts toward Scooter.
Service Type:
Revenue model architecture—asset ownership versus driver-mediated access—determines platform risk exposure and scaling economics.
- Ride-sharing:Driver-mediated trips using privately owned or leased vehicles. Platforms optimize through network density algorithms rather than fleet ownership, concentrating demand in dense urban corridors where wait-time compression drives retention.
- Car-sharing:Station-based or free-floating fleet assets rented by minute or hour. Corporate account penetration in Austin and Bangalore is shifting procurement toward subscription bundles with guaranteed minimum commitments.
- Bike-sharing:Docked infrastructure systems with high fixed-capital requirements. Municipal concession agreements in Paris and Copenhagen create incumbent lock-in that constrains competitive entry.
- Scooter-sharing:Free-floating electric two-wheelers deployed for sub-five-kilometer trips. Lower capital requirements per unit and battery-swapping standardization are accelerating deployment velocity relative to car-based models.
Revenue concentrates in Ride-sharing; Car-sharing claims the steepest expansion trajectory among asset-heavy models.
End User:
Procurement sophistication and contract duration separate customer segments.
- Corporate:Enterprise buyers negotiating bulk rates for employee benefit programs. HR departments in technology sectors favor subscription packages with integrated expense management and sustainability reporting.
- Individual:Occasional and frequent urban commuters purchasing per-trip or prepaid bundles. Price sensitivity and app-based convenience dominate switching behavior.
- Fleet Operators:Professional logistics and rental companies acquiring shared vehicle assets for redeployment. Procurement emphasizes telematics integration and predictive maintenance APIs.
- Governments:Municipal and regional authorities procuring mobility services for public transit integration. Contract awards prioritize emission compliance and equitable geographic coverage mandates.
Contract value peaks with Corporate; volume expansion favors Individual users.
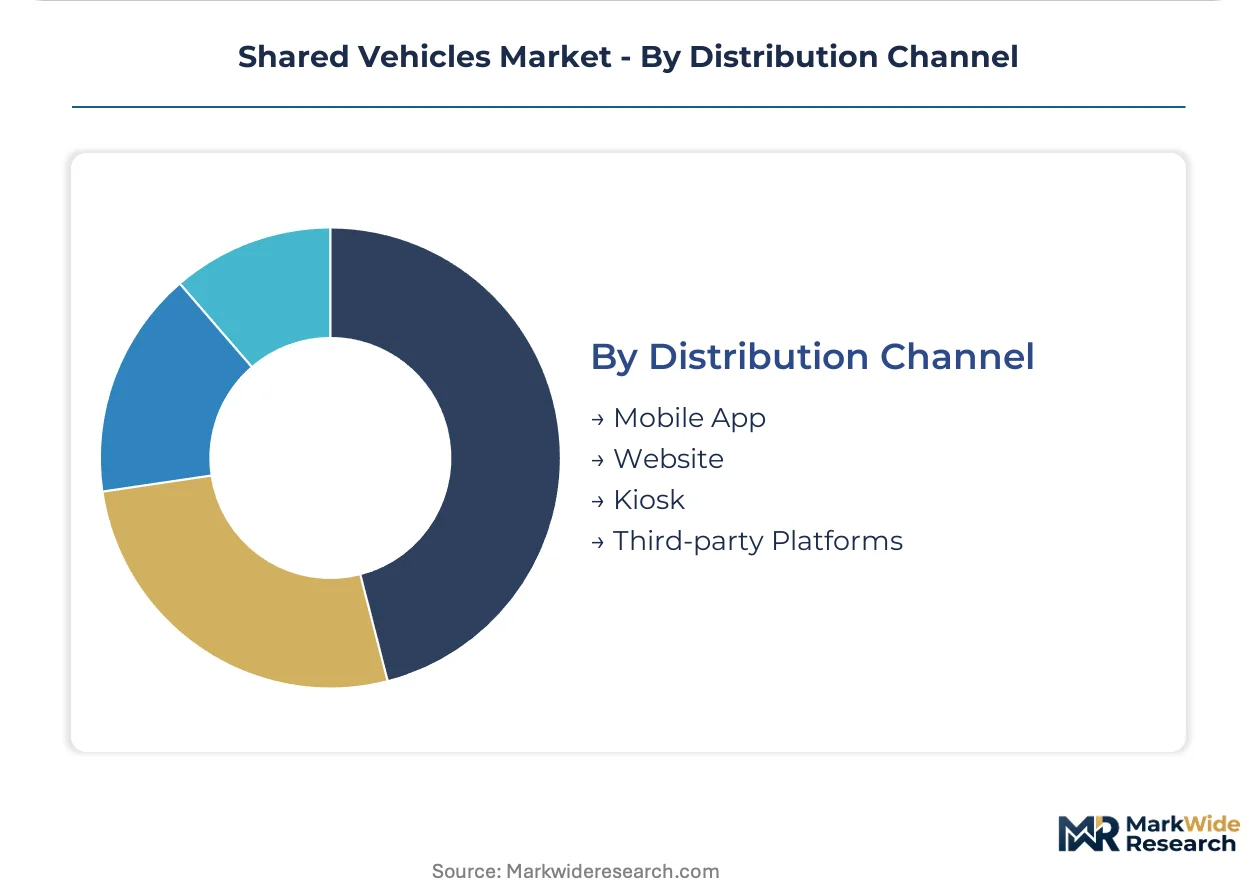
Distribution Channel:
Customer acquisition cost and retention mechanics vary by interface type.
- Mobile App:Primary interface for ride-hail and scooter-sharing, enabling real-time location services and in-app payment. Super-app convergence in Southeast Asia is raising switching costs through service bundling.
- Website:Corporate account management and subscription enrollment portal. Procurement officers utilize web interfaces for bulk user provisioning and invoice reconciliation.
- Kiosk:Physical rental terminals at transit hubs and tourist zones for bike-sharing and car-sharing. Reduces smartphone dependency but constrains deployment flexibility.
- Third-party Platforms:Aggregator integrations with mapping services, travel booking engines, and employer benefit portals. Expands reach but compresses margin through revenue-sharing arrangements.
Transaction volume flows through Mobile App; Third-party Platforms are gaining share fastest as ecosystem integration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bangalore's technology corridor anchors fleet deployment density as corporate campuses negotiate bulk commuter contracts. Delhi-NCR and Mumbai follow with concentrated ride-hail demand at transit interchanges. The geographic distribution reflects where subscription-based employer programs intersect with charging infrastructure mandates.
United States
Corporate commuter benefits in Austin and San Francisco drive B2B fleet contract growth. FAA regulations constrain drone-based mobility pilots to designated urban air corridors below 400 feet. Los Angeles and Dallas-Fort Worth concentrate scooter-sharing deployments near university and entertainment districts.
Germany
Employer-subsidized car-sharing subscriptions dominate procurement in Berlin and Munich technology sectors. EU Green Deal emission targets pressure fleet operators toward full-electric compliance by 2030. The Rhine-Ruhr corridor hosts dense charging infrastructure networks serving corporate account vehicles.
China
Battery-swapping standardization from MIIT compresses turnaround times for electric two-wheeler fleets in Shenzhen and Hangzhou. Municipal governments in Beijing and Shanghai limit new operator permits to control sidewalk congestion. The Yangtze River Delta concentrates manufacturing clusters for IoT lock systems and telematics hardware.
India
CEA charging infrastructure disclosures accelerate network formalization in Delhi, Mumbai, and Bangalore. Ola and Uber concentrate competitive investment on last-mile connectivity in tier-one cities. Jaipur and Lucknow present expansion opportunities as tier-two demand matures.
Singapore
Super-app integration raises switching costs through bundled ride-hail, food delivery, and financial services. Land Transport Authority regulations mandate geofenced parking zones for free-floating scooter fleets. The city-state's 5G network slicing enables sub-100-millisecond vehicle-to-infrastructure communication for dispatch optimization.
Shared Vehicles Market Key Industry Players
Capital-heavy fleet owners compete with asset-light platform operators for margin capture in shared mobility. The market structure fragments across vehicle ownership models, with station-based car-sharing, free-floating scooter fleets, and driver-mediated ride-hail each commanding distinct economics. Three archetypes dominate: technology platforms optimizing network density algorithms, automotive incumbents repurposing dealer infrastructure for mobility services, and pure-play fleet operators managing asset utilization rates. Consolidation pressures favor platforms with integrated telematics stacks and municipal concession agreements.
Among technology-platform specialists, Uber Technologies Inc., Beijing Xiaoju Technology Co., Ltd., and Grab Holdings Inc. exemplify the network-density archetype. Uber leverages driver network concentration to compress urban wait times below competitor thresholds. Didi Chuxing anchors its position through proprietary mapping infrastructure and dispatch algorithm development. Grab occupies the super-app convergence space across Southeast Asian markets where service bundling raises retention economics. These three represent how software-defined capabilities reshape competitive positioning more than fleet scale alone.
| Leading Market Players |
|---|
| Uber Technologies Inc. |
| Lyft, Inc. |
| Beijing Xiaoju Technology Co., Ltd. (Didi Chuxing) |
| Grab Holdings Inc. |
| ANI Technologies Pvt. Ltd. (Ola Cabs) |
| Zipcar Inc. |
| SIXT SE |
| Hertz Global Holdings, Inc. |
| Bolt |
| Others |
Cost & Logistics Intelligence
Corporate fleet procurement officers in Germany and the United States are consolidating ride-hail contracts into subscription bundles with guaranteed minimum commitments, forcing operators to restructure asset ownership models and compress per-trip margins to secure multi-year employer agreements.
Pricing Analysis
Margin tightening in scooter-sharing reflects battery-swapping standardization from China's MIIT lowering capital barriers for new entrants. Pricing stratifies across premium corporate subscriptions, standard individual ride-hail, and economy bike-share tiers. Cost-down pressure on car-sharing accelerates because automotive incumbents repurpose dealer infrastructure for mobility services. Fleet operators exhibit lowest price sensitivity due to telematics integration requirements, while occasional individual commuters drive hardest bargain hunting.
Supply Chain Analysis
Reverse-logistics networks for lithium-ion battery refurbishment and IoT lock system redeployment are emerging as critical cost centers rather than afterthoughts. Manufacturing concentrates in China, South Korea, and Taiwan for battery cells, telematics modules, and GPS hardware. Cathode material processing draws from Jiangsu and Hunan province clusters, creating single-source vulnerability for electric fleet operators. Distribution runs through cloud-based reservation platforms integrating directly with municipal transit APIs and employer benefit portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Shared mobility is becoming a vertical-integration race where control over battery-swapping infrastructure and proprietary dispatch algorithms determines who captures margin from commoditized vehicle assets.
For Market Incumbents: Cement municipal concession agreements in European docked-bike markets before permit windows close. Acquire telematics hardware specialists to reduce dependency on Chinese IoT lock suppliers facing export restriction risk. Lock in corporate HR departments through integrated expense management APIs that raise switching costs. For New Entrants and Emerging Players: Enter via tier-two Indian cities where Ola and Uber underinvest relative to Delhi and Mumbai saturation. Target Jaipur and Lucknow last-mile connectivity with battery-swappable scooter fleets. Pursue super-app integration partnerships with Southeast Asian food delivery platforms rather than building standalone user bases. For Investors and Strategic Acquirers: The window for entry favors fleet operators with captive charging infrastructure and algorithmic dispatch capabilities rather than asset-light platforms. Monitor CEA charging mandate compliance thresholds as inflection indicator for formalization of India's electric fleet economics. Prioritize targets with municipal permits in European bike-sharing markets where incumbent lock-in constrains new competition.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures lithium-ion cell allocation from Jiangsu processors for electric two-wheeler fleet expansion. |
| Platform Integration | Embeds ride-hail modules within Southeast Asian super-apps to capture food delivery user bases. |
| Charging Infrastructure Partnership | Aligns with India's CEA disclosure mandates to accelerate network formalization in Delhi-NCR. |
| Geographic Expansion | Targets tier-two Indian cities before competitive density replicates tier-one saturation patterns. |
| Acquisition of Specialist Firm | Absorbs telematics hardware developers to reduce IoT lock supply chain concentration risk. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with fleet operations directors, municipal transit planners, corporate HR benefits managers, and telematics hardware procurement leads. Bottom-up vehicle deployment counts by city and operator were cross-validated against top-down market sizing from ride-hail platform disclosures and automotive OEM mobility service revenue segments.
Data-stream reconciliation across vehicle type, service model, end-user procurement sophistication, and distribution channel integration complexity shaped the analytical framework over the projection horizon. CAGRs derived from logistic diffusion curves fitted to electric fleet penetration patterns and employer subscription adoption rates. Segmentation modeling incorporated battery chemistry transition timelines and MIIT standardization implementation phases.
Revisions become necessary when FAA airspace rulemaking expands drone mobility corridors, EU AI Act enforcement reshapes algorithmic pricing exposure, or lithium carbonate price volatility alters battery-swapping economics. Practitioners should monitor municipal permit issuance rates in European bike-sharing markets and CEA compliance disclosure thresholds in India for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Smart Mobility Market
Smart Transportation Solutions
Smart Logistic Market
Smart Transportation Solutions
Mobility Technologies Market
Smart Transportation Solutions
Road Profile Laser Sensor Market
Smart Transportation Solutions
North America Smart Transportation Market
Smart Transportation Solutions
Advanced Traffic Management System (ATMS) Market
Smart Transportation Solutions
Global Intelligent Road System Market
Smart Transportation Solutions
Fleet Management Software Market
Smart Transportation Solutions
US Smart Highway Market
Smart Transportation Solutions
Global Smart Commute Market
Smart Transportation Solutions
Transportation by Drone Market
Smart Transportation Solutions
Cellular Vehicle-To-Everything (C-V2X) Market
Smart Transportation Solutions
Global Parking Meter Apps Market
Smart Transportation Solutions
North America Vehicle Tolling System Market
Smart Transportation Solutions
France Ridesharing Market
Smart Transportation Solutions
Long Haul Solutions Market