
 Absorbable Nonwoven Textiles Market | 2026-2036
Absorbable Nonwoven Textiles Market Size, Share, and Industry Trends Forecast 2026-2036
Absorbable Nonwoven Textiles Market Analytics
Biomedical polymer engineering talent scarcity is redrawing competitive boundaries across the absorbable nonwoven textiles sector. Freudenberg Group leverages its European R&D footprint to sustain leadership in surgical-grade nonwovens. Berry Global Inc. anchors North American supply through vertical control of meltblown and spunbond lines. DuPont differentiates via proprietary lactide-glycolide copolymer platforms for controlled resorption timelines.
Absorbable nonwoven textiles comprise fibrous webs manufactured from biodegradable polymers—polycaprolactone, polyglycolic acid, cellulose, or polylactic acid—engineered to degrade through hydrolysis within controlled timeframes ranging from days to months, serving primarily as temporary barriers, fluid management layers, or drug delivery matrices in clinical and hygiene applications. Medical dressings and surgical products command the largest value pools due to stringent certification requirements and recurring hospital procurement contracts, while wound care applications outpace other segments in volume growth as outpatient and home-based treatment protocols expand. Material innovation in polyglycolic acid variants is reshaping margin structures, with faster-resorbing grades capturing premium positioning in emergency and trauma settings.
FDA biocompatibility standards under ISO 10993, the EU MDR framework, and Japan's PMDA quality system regulations collectively govern market access, with compliance costs filtering smaller material suppliers from high-risk surgical segments. The EU Green Deal's circular economy mandates are pressuring producers to validate compostability pathways for cellulose-based hygiene grades. Stakeholders must monitor evolving biodegradation testing protocols as regulators harmonize shelf-life claims with real-world clinical performance data.
Market Dynamics
The EU Medical Device Regulation's 2024 enforcement deadline is compressing certification timelines and filtering sub-scale suppliers from surgical-grade segments, concentrating procurement authority among vertically integrated polymer converters with established notified body relationships.
Growth Catalysts
- EU MDR compliance windows:Hospital systems in Germany and France are consolidating vendor lists to pre-qualified suppliers, accelerating contract migrations toward certified nonwoven producers with ISO 13485 quality systems.
- Polyglycolic acid resorption engineering:Faster-degrading polymer grades are displacing traditional gauze in emergency trauma protocols, capturing preference in military and civilian first-response applications.
- Outpatient wound care expansion:Home-based treatment protocols across the United States and United Kingdom are multiplying consumption volumes for single-use absorbent dressings and hemostatic pads.
Market Restraints
- Lactide-glycolide copolymer feedstock concentration:Precursor chemical supply clusters in China create input cost volatility and geographic dependency for Western nonwoven manufacturers.
- Biocompatibility testing burden:FDA ISO 10993 cytotoxicity and sensitization protocols extend product development cycles, delaying revenue recognition for novel material formulations.
- Cellulose-based substitutes:Compostable regenerated cellulose webs from established hygiene suppliers compete on price in low-acuity wound care segments.
Strategic Opportunities
- Japan's PMDA accelerated review pathways:Breakthrough device designation for antimicrobial-impregnated absorbable meshes creates regulatory tailwind for innovators with Japan-market infrastructure.
- Drug-device combination convergence:Integration of antibiotic-eluting functionality into surgical barrier textiles opens reimbursement codes previously reserved for pharmaceutical interventions.
- Direct-to-hospital digital procurement:E-procurement platforms in the United Kingdom are disintermediating traditional medical distributor networks, enabling margin capture by specialized nonwoven producers.
Industry Challenges
- Biomedical polymer engineering scarcity:Universities in Germany and Switzerland produce insufficient graduates with combined materials science and clinical translation expertise, inflating compensation for experienced formulators.
- Multi-jurisdiction dossier management:Simultaneous FDA 510(k), EU MDR technical documentation, and PMDA shonin filings strain regulatory affairs bandwidth at mid-scale manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Absorbable Nonwoven Textiles Market |
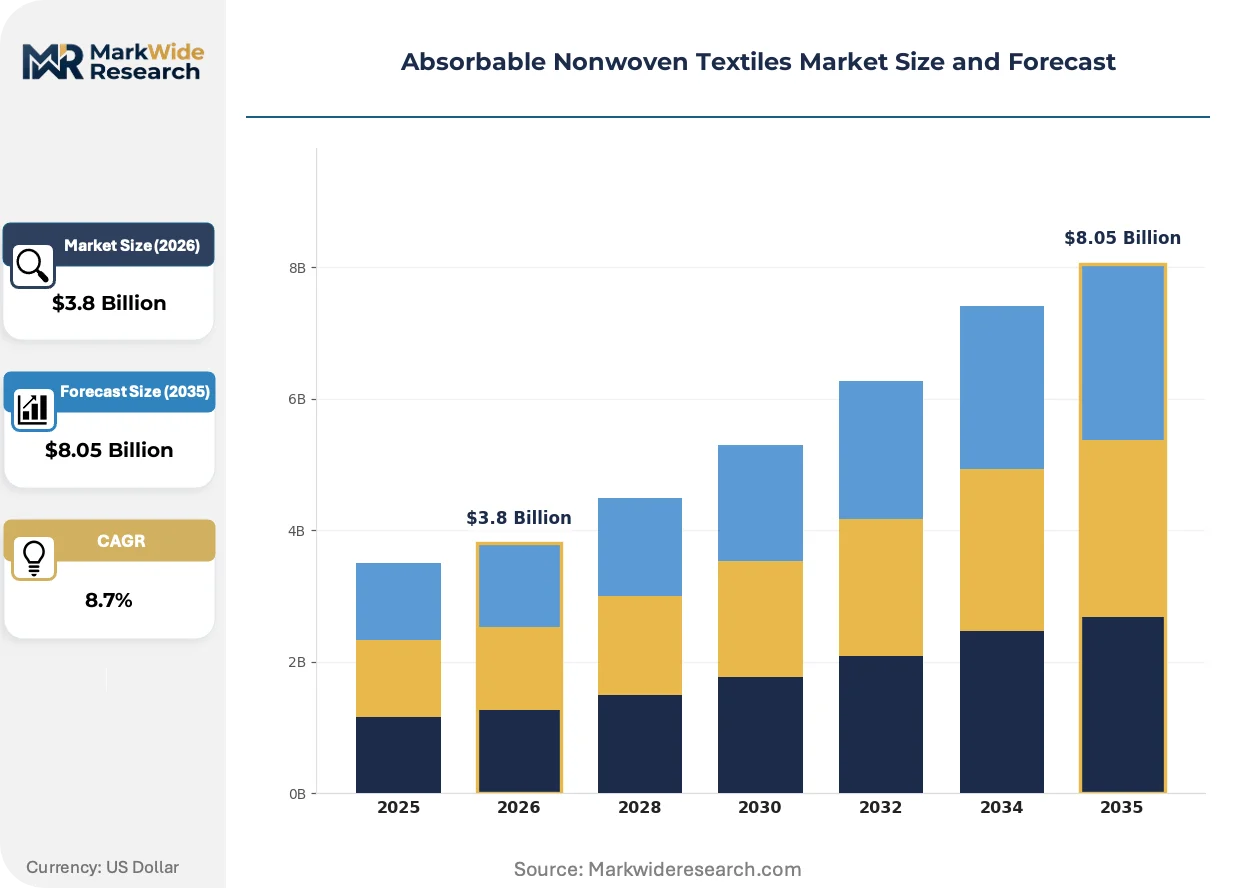
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medical Dressings, Absorbent Pads, Surgical Products, Hygiene Products Material: Polycaprolactone, Polyglycolic Acid, Cellulose, Poly lactic Acid Application: Wound Care, Surgical Procedures, Personal Care, Veterinary Use End User: Healthcare Facilities, Home Care, Veterinary Clinics, Research Laboratories |
| Companies Covered | Ahlstrom-Munksjo, Berry Global Inc., Glatfelter Company, DuPont, Fitesa, Freudenberg Group, TWE Group, PFNonwovens, Lydall Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Absorbable Nonwoven Textiles Market Evolving Landscape
Material science advances and regulatory harmonization efforts are restructuring competitive boundaries across absorbable textile applications, with differentiation increasingly residing in controlled degradation kinetics and sterilization compatibility rather than base polymer selection alone.
Electrospun nanofiber architectures are bifurcating the surgical barrier market into high-porosity rapid-integration grades versus dense impermeable membranes for adhesion prevention. Cardiovascular and orthopedic surgeons in tertiary hospitals are adopting these structures at accelerating cadence. The technology is bifurcating procurement specifications, forcing traditional meltblown suppliers toward equipment retrofits or segment exit.
REACH substance restriction proposals on persistent organic pollutants are compelling European nonwoven producers to validate alternative catalyst systems for polyester synthesis. Industrial consequence includes reformulation costs and supply chain requalification for surgical mesh manufacturers serving EU hospitals. Cellulose-based absorbable grades face accelerated substitution pressure as producers preempt regulatory action.
Hospital value-analysis committees are consolidating purchasing decisions at health-system level, displacing individual surgeon preference as the dominant selection criterion. Specialty distributors with local inventory and clinical support capabilities are losing share to national procurement consortia with direct manufacturer contracts. This concentration is most visible in United States integrated delivery networks and German hospital federations.
Absorbable Nonwoven Textiles Market Segmentation
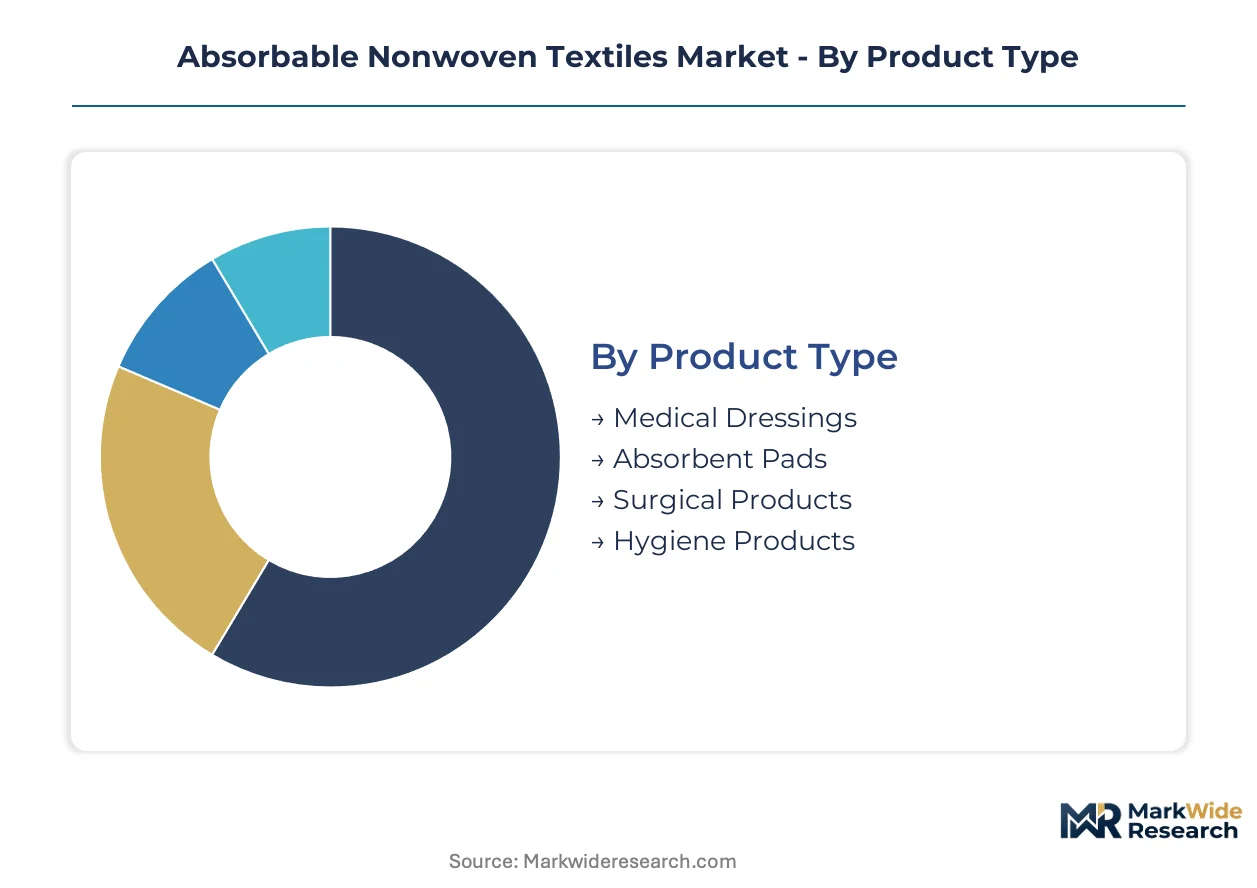
Absorbable nonwoven textiles serve divergent clinical and commercial requirements across product configurations, polymer chemistries, and care settings. Segmentation reveals where regulatory complexity, material innovation, and procurement consolidation create divergent margin structures and competitive moats.
Product Type:
FDA 510(k) clearance pathways and EU MDR technical documentation requirements split this category into surgical-grade certified products versus lower-regulation hygiene and general care items.
- Surgical Products:These encompass barrier meshes, hemostatic fabrics, and adhesion prevention membranes engineered from lactide-glycolide copolymers with controlled 30-90 day resorption profiles. Hospital value-analysis committees in Germany and France are consolidating procurement authority around pre-qualified suppliers with ISO 13485 quality systems and established notified body relationships.
- Medical Dressings:Primary and secondary wound coverings manufactured from oxidized regenerated cellulose or polyglycolic acid fibers, designed for fluid management and moist wound healing. Outpatient treatment expansion across the United States and United Kingdom is multiplying consumption volumes for single-use absorbent configurations.
- Absorbent Pads:Multi-layer composites combining hydrophilic cores with fluid-resistant backings for exudate management in post-operative and chronic wound protocols.
- Hygiene Products:Compostable wipes and personal care substrates facing EU Green Deal circular economy mandates for validated biodegradation pathways.
Established volume favors Surgical Products; emerging adoption favors Medical Dressings.
Material:
Feedstock availability and catalyst chemistry determine regional manufacturing footprints and compliance exposure under REACH substance restriction proposals.
- Polyglycolic Acid:Fastest-resorbing synthetic polymer degrading through hydrolysis within 4-6 weeks, prized for emergency trauma and military first-response applications. Military medical procurement in the United States and civilian emergency protocols in Japan are capturing premium positioning for rapid-integration grades.
- Polylactic Acid:Slower-degrading aliphatic polyester with 6-12 month resorption timelines suited for structural support in orthopedic and dental barrier applications. Precursor chemical supply concentration in China creates input cost volatility for Western nonwoven manufacturers dependent on lactide monomer imports.
- Polycaprolactone:Semi-crystalline polymer offering extended degradation windows and blend compatibility with other biodegradable matrices.
- Cellulose:Regenerated natural polymer from wood pulp or cotton linters, facing substitution pressure as European producers preempt REACH catalyst restrictions.
Polyglycolic Acid commands the steepest expansion trajectory in trauma segments; Polylactic Acid retains structural application dominance.
Application:
Clinical setting determines sterilization requirements, reimbursement coding, and competitive entry barriers.
- Wound Care:Acute and chronic wound management protocols spanning hospital, outpatient, and home-based treatment environments. Home care expansion in the United Kingdom and United States is displacing traditional gauze with advanced absorbent dressings.
- Surgical Procedures:Operating room applications requiring terminal sterilization compatibility and lot traceability under FDA quality system regulations.
- Personal Care:Consumer hygiene applications with lower biocompatibility testing burdens but intensifying sustainability certification requirements.
- Veterinary Use:Animal health applications following parallel but abbreviated regulatory pathways in major agricultural economies.
Wound Care is climbing the fastest in unit volume; Surgical Procedures maintains value concentration.
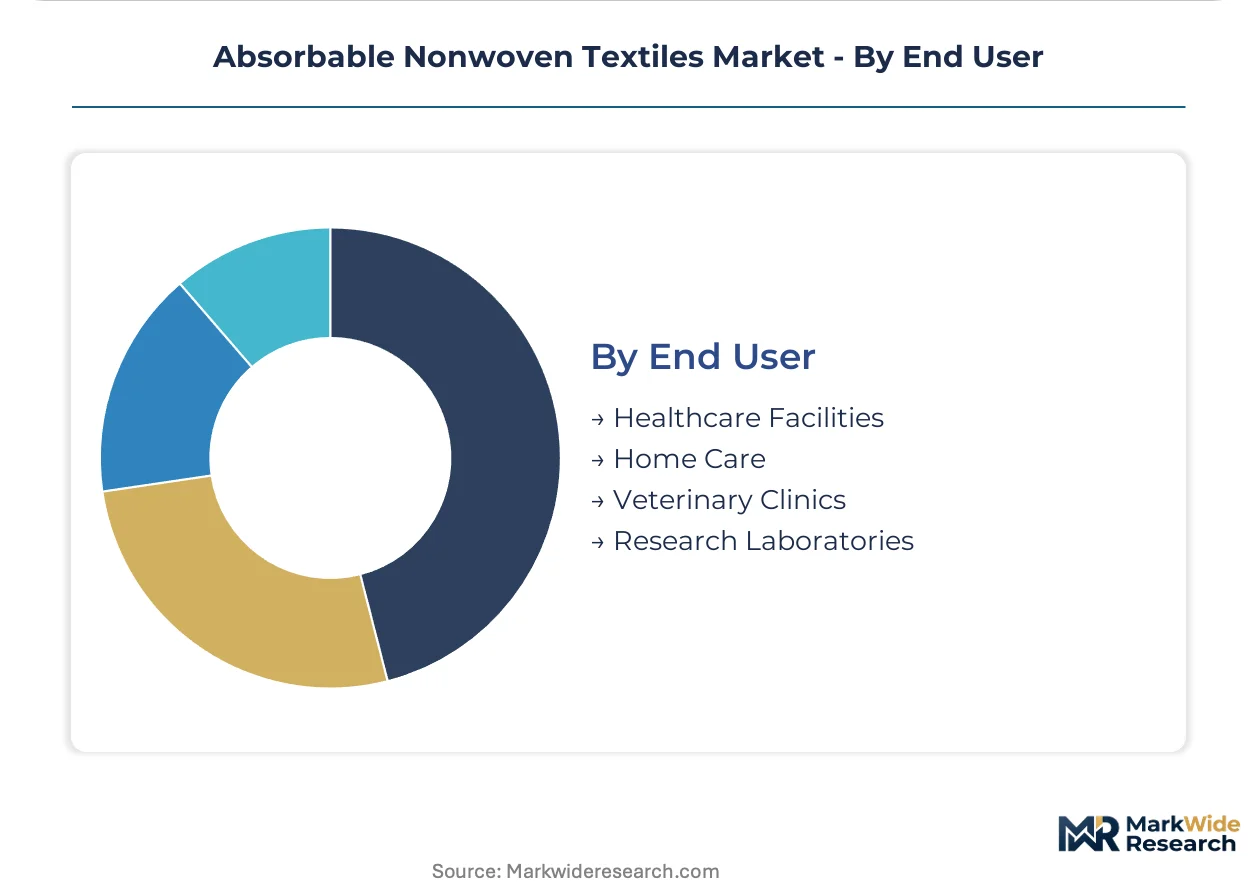
End User:
Procurement sophistication and technical specification authority vary dramatically across customer types.
- Healthcare Facilities:Tertiary hospitals and surgical centers with centralized purchasing, value-analysis committees, and direct manufacturer contracting. German hospital federations and United States integrated delivery networks are disintermediating specialty distributors.
- Home Care:Patients and informal caregivers purchasing through retail pharmacies and e-procurement platforms. United Kingdom National Health Service e-procurement infrastructure is enabling margin capture by specialized nonwoven producers.
- Veterinary Clinics:Companion and livestock animal practices with decentralized purchasing and price-sensitive procurement patterns.
- Research Laboratories:Academic and commercial R&D facilities requiring small-batch customization and flexible specification protocols.
Healthcare Facilities anchor contract value; Home Care is gaining share fastest in volume terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German hospitals consume absorbable nonwoven textiles primarily for advanced wound care protocols, while United States demand concentrates in emergency trauma and military medical applications. Japanese procurement favors rapid-resorption grades for surgical barriers. This consumption-mix differential shapes regional competitive positioning and regulatory compliance investments.
United States
Military medical procurement and civilian trauma centers drive preference for polyglycolic acid grades with 4-6 week resorption timelines. FDA ISO 10993 biocompatibility protocols filter smaller suppliers from surgical-grade segments. The Research Triangle Park cluster in North Carolina hosts polymer engineering talent pools serving defense and civilian hospital systems.
Germany
Hospital federations consolidate vendor lists around ISO 13485-certified producers with established notified body relationships. EU MDR enforcement compresses certification timelines, favoring vertically integrated converters. The Freudenberg Group anchors production in Weinheim, supplying surgical-grade nonwovens across European tertiary hospitals.
Japan
PMDA accelerated review pathways for breakthrough devices attract innovators with antimicrobial-impregnated absorbable mesh platforms. METI industrial policy supports domestic biomedical polymer engineering programs. The Kansai region around Osaka maintains concentration of textile-to-medical conversion facilities.
United Kingdom
NHS e-procurement infrastructure enables direct-to-hospital contracting, disintermediating traditional medical distributors. Home-based wound care expansion multiplies consumption volumes for single-use absorbent dressings. The Midlands corridor hosts contract manufacturers serving retail pharmacy and hospital supply chains.
China
Lactide and glycolide precursor chemical supply clusters create feedstock cost advantages for domestic nonwoven producers. NMPA quality system regulations govern market access for imported surgical-grade materials. The Yangtze River Delta concentration of polymer engineering capacity serves both domestic hygiene and export surgical segments.
Absorbable Nonwoven Textiles Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the absorbable nonwoven textiles sector. Freudenberg Group and Berry Global Inc. occupy positions with captive polymer conversion and meltblown-spunbond line control. Mid-scale specialists compete on formulation customization and regional regulatory dossier expertise. Dominant competitive moves include backward integration into lactide-glycolide copolymer feedstock and strategic partnerships with notified bodies for EU MDR certification acceleration.
Within the integrated leader tier, Freudenberg Group represents European R&D-centric positioning, while Berry Global Inc. anchors North American supply chain security. DuPont occupies a position defined by proprietary polymer platform differentiation. These three exemplify how material science depth and regulatory dossier bandwidth concentrate procurement authority among pre-qualified surgical-grade suppliers.
| Leading Market Players |
|---|
| Ahlstrom-Munksjo |
| Berry Global Inc. |
| Glatfelter Company |
| DuPont |
| Fitesa |
| Freudenberg Group |
| TWE Group |
| PFNonwovens |
| Lydall Inc. |
| Others |
Value Network & Pricing Analysis
FDA ISO 10993 biocompatibility certification and EU MDR technical documentation requirements simultaneously gate supply qualification and stratify price tiers, forcing surgical-grade producers to absorb compliance costs that commodity hygiene suppliers cannot shoulder while capturing premium positioning in hospital procurement channels.
Pricing Analysis
Long-term offtake contracts dominate hospital system procurement in Germany and the United States, with spot purchasing limited to emergency stockpiles and research laboratory orders. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified surgical meshes from oxidized regenerated cellulose dressings and unbranded hygiene substrates. Cost compression in economy-tier cellulose grades is intensifying because EU Green Deal compostability mandates require catalyst reformulation. Home care buyers exhibit highest price sensitivity, while military medical procurement shows lowest sensitivity due to performance-critical trauma protocols.
Supply Chain Analysis
Strategic stockpiling of lactide-glycolide copolymer precursors characterizes Western nonwoven manufacturers responding to Chinese feedstock concentration, while just-in-time inventory governs downstream hospital distribution. Manufacturing gravity centers on Germany, the United States, and China, with polymer engineering talent clusters in North Carolina and Weinheim anchoring R&D-intensive segments. Raw material dependencies include lactide monomer imports, glycolide precursor chemicals, and medical-grade cellulose pulp. Single-source vulnerability in Chinese precursor supply creates structural risk for European surgical mesh producers. Distribution runs through national procurement consortia and GPO contracts in hospital systems, bypassing traditional specialty distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through German hospital federation consolidation and United States integrated delivery network expansion, fragmenting vendor access for mid-scale nonwoven producers lacking direct manufacturer contracting capabilities.
For Market Incumbents: Consolidate notified body relationships and ISO 13485 certification bandwidth to defend against EU MDR compliance filtering, while securing captive lactide-glycolide copolymer supply through backward integration or long-term precursor offtake agreements with Chinese chemical producers. Capacity addition in Weinheim or Research Triangle Park reinforces proximity to polymer engineering talent pools. For New Entrants and Emerging Players: Post-operative home care service-layer gaps in the United Kingdom NHS e-procurement infrastructure expose white-space for specialized nonwoven producers with direct-to-hospital digital platforms. Antimicrobial-impregnated rapid-resorption meshes for Japan's PMDA breakthrough device pathway represent the most penetrable regulatory entry point. Go-to-market execution should leverage NHS digital procurement onboarding rather than distributor relationship building. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electrospun nanofiber surgical barrier segments, favoring acquisition targets with installed nanofiber line capacity and established sterilization validation protocols. The 5-10 year viability window rewards platforms with dual FDA-EU MDR dossier management capabilities. Watch for PMDA shonin approval velocity as inflection indicator for Japan-market revenue traction.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Acceleration | Notified body partnerships compress technical documentation timelines for surgical-grade producers. |
| Backward Integration into Copolymer Feedstock | Captive lactide-glycolide supply insulates margin structures from Chinese precursor volatility. |
| Electrospun Nanofiber Line Retrofit | High-porosity rapid-integration grades capture preference in cardiovascular and orthopedic surgery. |
| Antimicrobial-Eluting Mesh Development | Drug-device combination convergence opens pharmaceutical-tier reimbursement codes. |
| Direct-to-Hospital Digital Procurement | NHS e-procurement platforms disintermediate distributor networks for margin capture. |
Research Methodology
Initial hypotheses were tested against primary input from biomedical polymer engineers, hospital purchasing committee members, regulatory affairs directors at notified bodies, and GPO contracts managers, then refined against FDA 510(k) clearance databases, EU MDR technical documentation filings, hospital procurement contract registries, and customs trade data for lactide-glycolide precursor flows. Bottom-up volume modeling across polymer grades and care settings triangulated with top-down market sizing from surgical procedure volumes and dressing consumption protocols.
Variance decomposition across material chemistry, product configuration, end-user procurement sophistication, and geographic regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume elasticities to surgical procedure growth and wound care protocol shifts, with electrospun nanofiber adoption curves and EU MDR compliance cost pass-through rates serving as industry-specific forecast inputs.
Underlying assumptions cover surgical procedure volume trajectories, regulatory enforcement intensity, and precursor chemical supply continuity, with deviation risk concentrated in Chinese lactide export policy shifts and REACH substance restriction timing. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nonwoven Materials
Nonwoven Protective Clothing Market
Nonwoven Materials
Global Wet Laid Nonwovens Market
Nonwoven Materials
PP Nonwovens Market
Nonwoven Materials
Global Melt-Blown Nonwovens Market
Nonwoven Materials
Non Woven Converting Machine Market
Nonwoven Materials
Nonwoven Cleanroom Apparel Market
Nonwoven Materials
India Non-Woven Geotextiles Market
Nonwoven Materials
Asia-Pacific Non-Woven Fabric Market
Nonwoven Materials
Nonwoven Dust Cover Market
Nonwoven Materials
Global Automotive Nonwoven Fabrics Market
Nonwoven Materials
Staples PP Nonwovens Market
Nonwoven Materials
Nonwoven Flanging Market
Nonwoven Materials
Non Woven Fabric Making Machine Market
Nonwoven Materials
Nonwoven Fabric Production Line Market
Nonwoven Materials
Nonwoven Sponges Market
Nonwoven Materials
Barrier Nonwoven Fiber for Breathable Surgical Gowns Market