
 Global Non Woven Fabric Market | 2026-2036
Global Non Woven Fabric Market Size, Share, and Industry Trends Forecast 2026-2036
Global Non Woven Fabric Market Foresight
Polypropylene is recalibrating cost structures across hygiene and filtration grades as it displaces cotton and rayon in disposable medical textiles. Berry Global Inc. leverages vertical integration from resin to finished roll goods across North American and European plants. Freudenberg Group anchors its position through specialized spunlace systems for automotive interior and industrial wiping applications. DuPont de Nemours, Inc. differentiates via high-performance Sontara-engineered substrates targeting pharmaceutical cleanroom specifications.
Non woven fabric consists of sheet or web structures bonded by mechanical, thermal, or chemical means rather than interlaced yarns, typically manufactured from synthetic polymers like polypropylene, polyester, or viscose at basis weights ranging from 10 to 150 grams per square meter. These engineered materials provide barrier protection, absorbency, and filtration efficiency across hygiene, medical, and industrial end uses. Spunbond dominates volume production due to its speed and tensile uniformity in geotextile and packaging applications. Meltblown commands premium positioning within filtration segments where fiber diameters below 5 microns enable HEPA-grade performance. Spunlace competes aggressively in wet-wipe and cosmetic pad markets where soft hand-feel and flushability specifications drive material selection.
The U.S. EPA regulates industrial non woven emissions under Clean Air Act guidelines while the FDA governs medical-grade material biocompatibility and sterilization validation. REACH restrictions on phthalates and persistent organic pollutants constrain chemical binder formulations across European supply chains. China's GB standards and MEE environmental enforcement are tightening wastewater discharge limits for wet-laid and spunlace facilities. Stakeholders must monitor evolving extended producer responsibility frameworks and polymer recycling infrastructure buildouts to secure feedstock access and maintain market authorization across multiple jurisdictions.
Market Dynamics
Spunbond-meltblown-spunbond (SMS) composite lines are absorbing capital flows as manufacturers retool for medical-grade barrier fabrics, compressing lead times for surgical drape and N95 respirator substrates while displacing older carded thermal-bond capacity.
Growth Catalysts
- EU Single-Use Plastics Directive:Mandates for reduced plastic waste in packaging and hygiene products are redirecting R&D investment toward bio-based polypropylene and polylactic acid feedstocks for flushable wipe substrates.
- Spunlace hydroentanglement:Water-jet bonding technology is capturing share in cosmetic and personal care applications where cotton softness specifications previously blocked synthetic penetration.
- China's domestic filtration buildout:MEE environmental enforcement and GB standards compliance are accelerating meltblown line additions for industrial air and liquid filtration systems serving semiconductor and pharmaceutical cleanrooms.
Market Restraints
- Propylene monomer volatility:Naphtha-cracker feedstock costs swing with crude oil indices, compressing margins on commodity spunbond grades where producers lack resin backward integration.
- Meltblown diehead supply concentration:Precision melt-distribution equipment fabrication concentrates among German and Japanese tooling specialists, creating 12-18 month order backlogs for new filtration capacity.
- REACH chemical binder restrictions:ECHA classifications on formaldehyde-releasing resins and phthalate plasticizers are forcing reformulation of durable automotive and furniture nonwovens at elevated testing costs.
Strategic Opportunities
- India's hygiene penetration gap:Per-capita consumption of disposable diapers and feminine care products remains below Southeast Asian benchmarks, creating white space for spunbond backsheet and acquisition-distribution layer suppliers.
- Battery separator substrates:Ceramic-coated wet-laid nonwovens are converging with lithium-ion cell manufacturing, opening technical textile applications beyond traditional hygiene and medical end uses.
- Extended producer responsibility frameworks:France's Citeo eco-modulation fees and Italy's CONAI packaging taxes are creating preferential market access for producers with certified recyclable or compostable bonding chemistries.
Industry Challenges
- Electrospinning scale-up:Sub-micron fiber production for advanced filtration remains trapped between lab-scale demonstration and continuous roll-good manufacturing, constraining nanofiber membrane commercialization timelines.
- Multi-jurisdictional sterilization validation:FDA 510(k) pathways for medical nonwovens diverge from CE-MDR technical documentation requirements, forcing parallel compliance architectures that extend product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Non Woven Fabric Market |
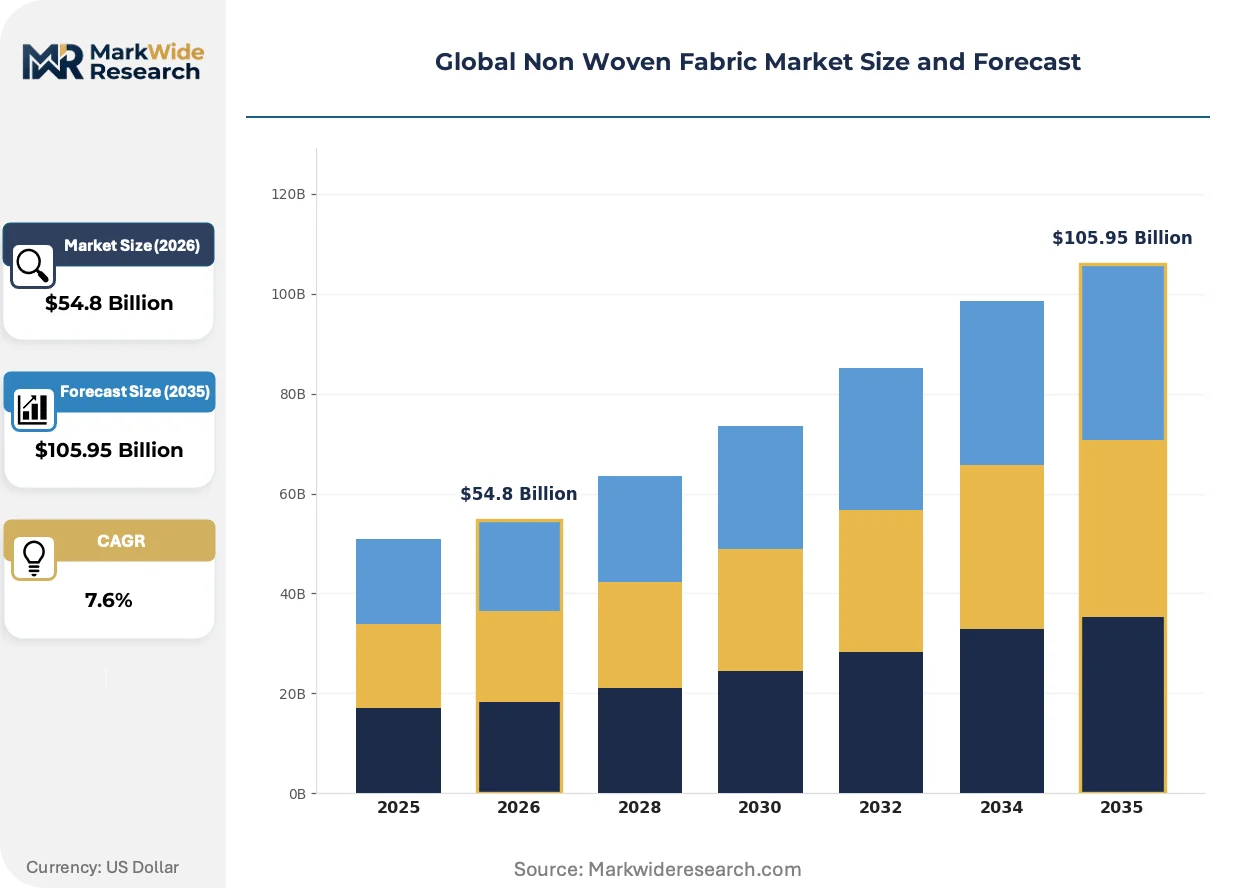
| Market Size in 2026 | $54.8 Billion |
| Market Size in 2035 | $105.95 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spunbond, Meltblown, Needle Punch, Airlaid, Spunlace Application: Hygiene Products, Filtration, Construction, Agriculture, Packaging End User Industry: Consumer Goods, Pharmaceuticals, Automotive Suppliers, Food Processing, Apparel Manufacturers Production Technology: Wet Laid, Dry Laid, Thermal Bonding, Chemical Bonding, Mechanical Bonding |
| Companies Covered | Berry Global Inc., Freudenberg Group, Ahlstrom-Munksjö, Kimberly-Clark Corporation, Fitesa S.A., DuPont de Nemours, Inc., Asahi Kasei Corporation, Toray Industries, Inc., Mitsui Chemicals, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Non Woven Fabric Market Shifts & Advancements
Bicomponent fiber spinning and sustainable bonding chemistries are compressing the performance gap between petroleum-based synthetics and bio-alternatives, reshaping material selection protocols across hygiene, medical, and industrial procurement functions.
Dual-core sheath-core polypropylene-polyethylene fibers are absorbing technical requirements previously served by homogeneous spunbond structures, enabling thermal calibration for soft-touch medical gowns without sacrificing tensile integrity. European hygiene converters are adopting these substrates at accelerating rates for premium diaper topsheet applications. The technology is absorbing margin pressure from cotton price volatility while opening down-gauging opportunities that reduce resin consumption per unit area.
REACH restrictions on per- and polyfluoroalkyl substances (PFAS) are forcing reformulation of oil-repellent nonwovens for food packaging and industrial protective apparel, eliminating long-chain fluorochemical treatments by 2025 enforcement deadlines. German automotive suppliers and French food-service material converters face the steepest compliance cliffs, pivoting toward silicone-based and paraffin wax alternatives that trade some performance for regulatory certainty. Spunbond producers with in-house fluoropolymer compounding capabilities are absorbing restructuring costs to maintain authorization.
Hospital procurement consortia are consolidating supplier panels and demanding consolidated roll-good deliveries with validated sterilization rather than separate substrate and contract-conversion sourcing. This behavioral shift concentrates volume among nonwoven producers with in-house finishing and gamma-irradiation capabilities, marginalizing merchant roll-good suppliers without downstream integration. The pattern is most visible in Germany's university hospital networks and U.S. integrated delivery networks negotiating multi-year surgical pack contracts.
Global Non Woven Fabric Market Segmentation
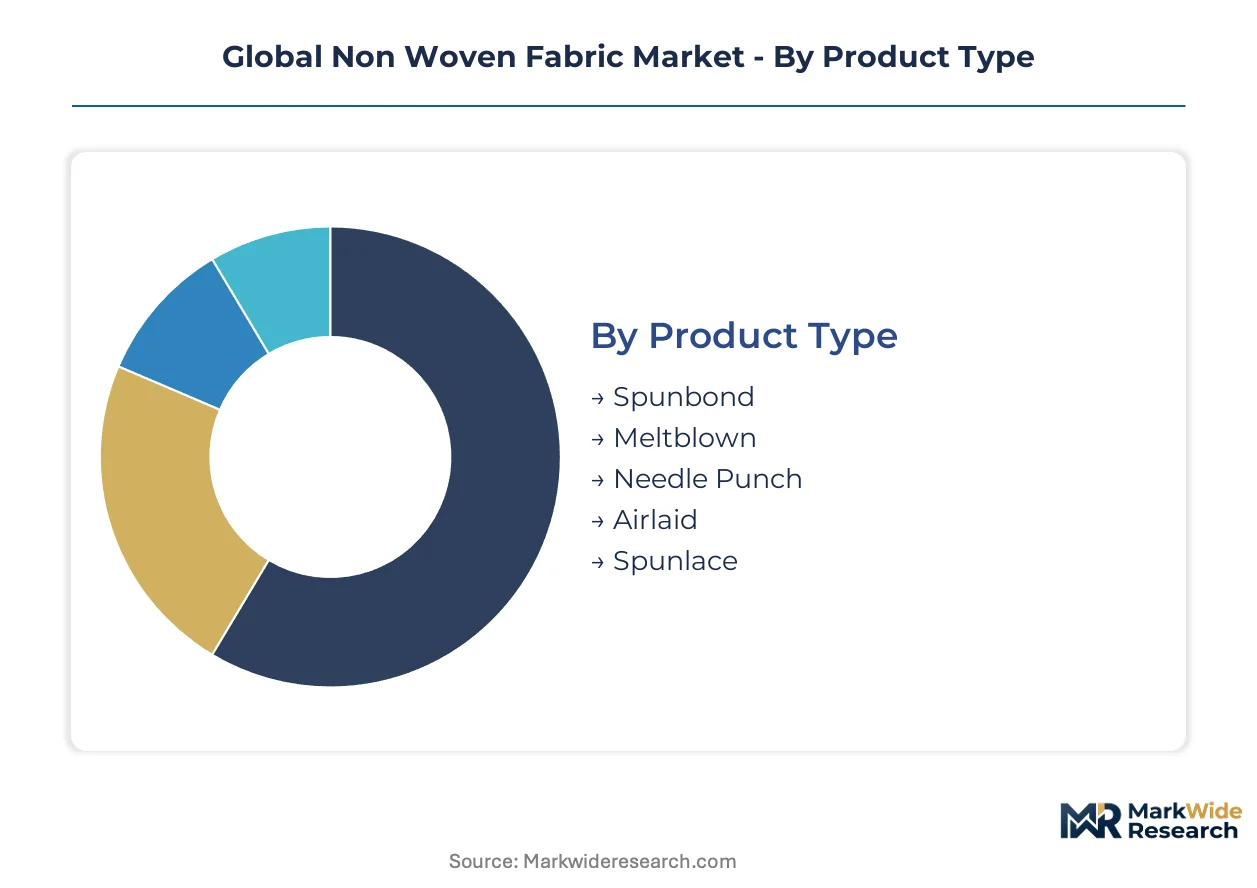
Non woven fabric segmentation reveals how manufacturing technology and end-use specifications create distinct margin tiers. Procurement managers select substrates based on filtration efficiency, tensile strength, and regulatory compliance requirements rather than commodity pricing alone.
Product Type:
Upgrade cycles in medical barrier fabrics and industrial filtration are redirecting capital toward composite manufacturing lines that combine multiple bonding technologies in single-pass operations.
- Spunbond:Continuous filament polypropylene webs deliver tensile uniformity at high production speeds, making them the default substrate for geotextile stabilization and hygiene backsheet applications. Chinese producers are expanding spunbond capacity for domestic diaper and medical drape markets as per-capita consumption rises.
- Meltblown:Microfiber structures with diameters below 5 microns achieve HEPA-grade filtration efficiency, commanding premium positioning in respirator media and semiconductor cleanroom systems. German and Japanese tooling specialists control precision diehead supply, creating order backlogs for new capacity.
- Needle Punch:Mechanical entanglement of staple fibers produces dimensional stability for automotive carpeting and geosynthetic drainage applications.
- Airlaid:Fluff pulp and synthetic fiber composites absorb liquid rapidly in feminine hygiene cores and incontinence products.
- Spunlace:Hydroentangled cellulosic and synthetic blends replicate cotton softness for cosmetic wipes and medical gauze substitutes.
Volume placements concentrate in Spunbond; the faster expansion belongs to Meltblown.
Application:
Cost tier differentiation separates specification-grade medical and filtration substrates from commodity construction and agricultural uses.
- Hygiene Products:Diaper acquisition-distribution layers and feminine care topsheets demand soft hand-feel combined with fluid management precision. Indian converters are expanding spunlace and airlaid purchasing as per-capita product usage climbs toward Southeast Asian benchmarks.
- Filtration:Industrial air and liquid separation systems require graduated density structures with validated efficiency ratings. China's MEE enforcement is accelerating meltblown line additions for pharmaceutical and semiconductor cleanroom supply.
- Construction:Geotextile separation and drainage layers utilize heavy-basis-weight needle punch for soil stabilization.
- Agriculture:Crop protection fleeces and greenhouse shading employ UV-stabilized spunbond for seasonal durability.
- Packaging:Single-use plastic directives in France and Italy are forcing reformulation toward bio-based and recyclable bonding chemistries for food-service applications.
Margin concentration sits with Filtration; the steepest volume climb is occurring in Hygiene Products.
End User Industry:
Customer type determines certification burden and contract duration, with pharmaceutical and automotive suppliers imposing the most stringent qualification protocols.
- Consumer Goods:Brand owners specify flushability and compostability credentials for wet-wipe substrates facing extended producer responsibility fees. European eco-modulation frameworks in France and Italy reward certified recyclable bonding chemistries with preferential market access.
- Pharmaceuticals:Cleanroom garment and sterilization wrap applications demand validated biocompatibility under FDA 510(k) and CE-MDR pathways. Hospital procurement consortia in Germany and the United States are consolidating supplier panels toward integrated roll-good and finishing capabilities.
- Automotive Suppliers:Interior trim and acoustic insulation specifications prioritize NVH performance and VOC emissions compliance.
- Food Processing:Oil-repellent nonwovens for packaging are reformulating away from PFAS treatments ahead of REACH deadlines.
- Apparel Manufacturers:Interlinings and protective garment substrates balance breathability with barrier properties.
Contract stability favors Pharmaceuticals; the broadest volume base rests with Consumer Goods.
Production Technology:
Supply concentration in bonding equipment fabrication shapes regional manufacturing footprints and technology adoption timelines.
- Wet Laid:Cellulosic fiber suspensions form uniform webs for battery separator substrates and technical filtration media. Ceramic-coated wet-laid nonwovens are converging with lithium-ion cell manufacturing beyond traditional hygiene applications.
- Dry Laid:Carded staple fiber processing remains cost-competitive for automotive and furniture applications where basis weights exceed 100 gsm.
- Thermal Bonding:Calender-activated bicomponent fibers enable soft-touch surfaces without chemical binders, capturing medical gown specifications previously served by spunlace.
- Chemical Bonding:REACH restrictions on formaldehyde-releasing resins are elevating reformulation costs for durable nonwovens in automotive and furniture end uses.
- Mechanical Bonding:Needle punch and stitch-bonded structures serve geotextile and carpet backing applications where dimensional stability outweighs surface softness.
Equipment availability concentrates in Thermal Bonding; the technology gaining share fastest is Wet Laid.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration for non woven fabric tilts toward healthcare hygiene and filtration end uses, with production capacity clustering in manufacturing hubs that combine polymer feedstock access, technical textile heritage, and regulatory proximity to major consumer markets.
China
Domestic filtration buildout and diaper consumption expansion drive meltblown and spunbond line additions across coastal provinces. MEE environmental enforcement tightens wastewater discharge limits for wet-laid and spunlace facilities under GB standards compliance programs. Yangtze River Delta manufacturers concentrate new capacity for semiconductor cleanroom and pharmaceutical barrier fabric exports.
Germany
Automotive interior specifications and medical device sterilization wrap demand anchor spunlace and thermal-bonded substrate consumption. REACH chemical binder restrictions on formaldehyde-releasing resins force reformulation of durable nonwovens for furniture and automotive end uses. Baden-Württemberg suppliers cluster around precision meltblown diehead fabrication and hospital procurement consortium headquarters.
United States
Integrated delivery networks and university hospital systems consolidate surgical pack supplier panels toward roll-good producers with in-house gamma-irradiation capabilities. FDA 510(k) pathways for medical-grade biocompatibility validation diverge from European CE-MDR requirements, extending product launch cycles. Southeast states absorb new spunbond-meltblown-spunbond composite line investments serving domestic hygiene and filtration markets.
India
Per-capita disposable diaper and feminine care product consumption remains below Southeast Asian benchmarks, creating white space for spunbond backsheet and acquisition-distribution layer suppliers. BIS standards implementation and PLI scheme incentives support technical textile manufacturing scale-up. Gujarat and Maharashtra industrial corridors attract hygiene converter investments seeking import substitution for currently sourced roll goods.
Japan
Semiconductor cleanroom garment and battery separator substrate specifications drive premium-grade meltblown and wet-laid nonwoven demand. METI industrial policy supports advanced fiber spinning technology development for sub-micron filtration applications. Kansai region producers concentrate ceramic-coated wet-laid capacity converging with lithium-ion cell manufacturing supply chains.
Global Non Woven Fabric Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated roll-good producers capturing hospital procurement consortium volume while merchant suppliers serve fragmented hygiene converter markets. The vendor base organizes around three archetypes: resin-backward-integrated multinationals, specialized bonding technology licensors, and regional hygiene-focused fabricators. Capacity expansion and strategic partnerships dominate competitive moves, with producers seeking diehead supply security and sterilization validation capabilities.
Within the premium-tier vector, DuPont de Nemours, Inc. and Asahi Kasei Corporation occupy positions emphasizing high-performance engineered substrates for pharmaceutical and industrial filtration specifications. Berry Global Inc. anchors the scale-driven segment through North American and European manufacturing footprints. These three entities exemplify divergent strategic postures: technology differentiation versus geographic coverage versus vertical integration from polymer to finished roll goods.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Freudenberg Group |
| Ahlstrom-Munksjö |
| Kimberly-Clark Corporation |
| Fitesa S.A. |
| DuPont de Nemours, Inc. |
| Asahi Kasei Corporation |
| Toray Industries, Inc. |
| Mitsui Chemicals, Inc. |
| Others |
Supply & Pricing Matrix
Precision meltblown diehead engineers concentrated in Baden-Württemberg and Osaka command wage premiums that propagate through filtration-grade substrate pricing, widening spreads between commodity spunbond and medical barrier fabric tiers. Labor-cost differentials between German tooling specialists and Chinese line operators compress margins on standardized hygiene backsheet production while sustaining premium capture in HEPA-grade respirator media.
Pricing Analysis
Volume placements concentrate in commodity spunbond where resin backward integration determines survival, while margin capture belongs to meltblown filtration substrates where German and Japanese diehead supply bottlenecks sustain premium positioning. Price differentiation rests on FDA 510(k) certification tier and gamma-irradiation validation capabilities, with hospital procurement consortia paying substantial premiums for consolidated roll-good and sterilization sourcing. Pricing pressure stems from propylene monomer volatility tied to naphtha-cracker feedstock swings, compressing returns on non-integrated commodity grades. Hygiene converters in India exhibit acute price sensitivity, whereas pharmaceutical cleanroom operators prioritize validated biocompatibility over unit cost.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Charleston anchor hub-and-spoke patterns for European, Asian, and North American hygiene converter markets respectively. Manufacturing concentrates in China, Germany, and the United States, with Chinese producers expanding meltblown lines for domestic filtration and export markets. Raw material dependencies center on polypropylene resin, precision melt-distribution equipment, and chemical binders constrained by REACH formaldehyde-releasing resin restrictions. Single-source vulnerability concentrates in German and Japanese diehead fabrication, creating 12-18 month order backlogs that throttle filtration capacity expansion. Distribution runs through merchant roll-good suppliers for fragmented hygiene converters and direct mill relationships for consolidated hospital procurement networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where REACH chemical binder restrictions and FDA 510(k) validation requirements erect barrier-to-entry moats favoring producers with in-house sterilization and regulatory documentation capabilities.
For Market Incumbents: To counter margin compression from propylene monomer volatility, prioritize backward integration into resin production or captive offtake agreements with crackers in the US Gulf Coast and Middle East. Defensive consolidation moves center on acquiring gamma-irradiation facilities to meet hospital procurement consortium demands for validated sterilization, and securing precision diehead supply relationships with German and Japanese tooling specialists to preempt competitor capacity additions. For New Entrants and Emerging Players: Launch via private-label supply to Indian hygiene converters seeking import substitution for spunbond backsheet and acquisition-distribution layer materials, where per-capita consumption gaps versus Southeast Asian benchmarks create penetrable white space. White-space targets include ceramic-coated wet-laid battery separator substrates converging with lithium-ion cell manufacturing, and bio-based polylactic acid feedstocks for flushable wipe substrates facing EU Single-Use Plastics Directive compliance deadlines. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap producers possessing FDA 510(k) and CE-MDR dual certification capabilities given hospital procurement consolidation toward integrated roll-good and finishing suppliers. Long-term viability over the coming decade favors entities with demonstrated sterilization validation architectures and REACH-compliant bonding chemistry portfolios. The signal to watch is extended producer responsibility fee implementation velocity across France, Italy, and Germany, which will accelerate preferential market access for certified recyclable and compostable substrate producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polypropylene Resin | Captive feedstock supply insulates margin compression from naphtha-cracker volatility indices. |
| Gamma-Irradiation Facility Acquisition | In-house sterilization validation captures hospital procurement consortium surgical pack consolidation. |
| Precision Diehead Supply Agreement | Secured German and Japanese tooling access preempts competitor filtration capacity expansion timelines. |
| Bio-Based PLA Feedstock Transition | EU Single-Use Plastics Directive compliance positions for eco-modulation fee avoidance in France and Italy. |
| Ceramic-Coated Wet-Laid Capacity Addition | Battery separator substrate convergence with lithium-ion cell manufacturing diversifies beyond hygiene end uses. |
Research Methodology
Document review covered trade customs data, SEC 10-K filings, and ECHA REACH restriction notifications, complemented by interviews with plant managers at spunbond and meltblown facilities, procurement leads at hygiene converters, distribution channel partners in medical textile supply chains, and technical R&D directors specializing in hydroentanglement bonding. Bottom-up and top-down triangulation validated volume estimates across manufacturing technology and end-use segments.
Cross-referencing historical capacity expansion patterns against panel input from equipment suppliers and resin producers anchored the analytical framework across the analysis window. Segmentation dimensions modeled include manufacturing technology, application tier, end-user industry certification requirements, and regional production hub clusters. CAGRs derived from trend extrapolation of line addition announcements, per-capita consumption penetration curves, and regulatory enforcement timelines, with specific inputs from MEE environmental compliance cost burdens and EU eco-modulation fee structures.
Propylene feedstock price shocks, REACH chemical binder reclassification events, and hospital procurement consortium consolidation velocity are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding resin backward integration rates and sterilization validation capability diffusion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nonwoven Materials
Nonwoven Cleanroom Apparel Market
Nonwoven Materials
Nonwoven Protective Clothing Market
Nonwoven Materials
Non-Woven Glass Fiber Prepreg Market
Nonwoven Materials
Nonwoven Floor Covers Market
Nonwoven Materials
Non-Wood Fiber Market
Nonwoven Materials
Global Spunbond Nonwovens Market
Nonwoven Materials
Nonwoven Cotton Market
Nonwoven Materials
Nonwoven Geotextiles Market
Nonwoven Materials
Global Automotive Nonwoven Fabrics Market
Nonwoven Materials
PP Nonwovens Market
Nonwoven Materials
Barrier Nonwoven Fiber for Breathable Surgical Gowns Market
Nonwoven Materials
Nonwoven Sponges Market
Nonwoven Materials
Non Woven Converting Machine Market
Nonwoven Materials
India Non-Woven Geotextiles Market
Nonwoven Materials
Global Polypropylene (PP) Nonwoven Fabrics Market
Nonwoven Materials
Asia-Pacific Non-Woven Fabric Market