
 Global Spunbond Nonwovens Market | 2026-2036
Global Spunbond Nonwovens Market Size, Share, and Industry Trends Forecast 2026-2036
Global Spunbond Nonwovens Market Foresight
Medical-grade spunbond specifications is collapsing the gap between commodity hygiene fabrics and barrier-performance surgical materials. Berry Global leverages its North American meltblown-spunbond composite lines to sustain supply contracts with major hospital purchasing groups. Freudenberg Group anchors European medical nonwoven demand through its specialization in hydrophobic spunbond layers for infection control apparel. Kimberly-Clark Corporation dominates consumer hygiene spunbond volumes in the Americas through captive diaper and wipe manufacturing.
Spunbond nonwovens are continuous-filament fabrics manufactured by extruding and drawing thermoplastic polymers—primarily polypropylene with melt indices between 25–40 g/10min—onto a conveyor belt where filaments bond thermally or mechanically into a unified web structure engineered for tensile strength, porosity, and liquid barrier control. Polypropylene spunbond commands the largest production share due to its cost efficiency and compatibility with high-speed diaper and geotextile manufacturing, while polyester spunbond captures premium margin pools in roofing membranes and automotive interior substrates where thermal dimensional stability is non-negotiable. Medical and hygiene applications lead volume consumption, though construction-grade geotextiles and agricultural crop covers represent faster-growth outlets as infrastructure and climate-adaptive farming investments intensify.
FDA device regulations for surgical drapes and EPA stormwater management standards for geotextile drainage systems shape product certification requirements and market access thresholds in the United States, while REACH chemical compliance and the EU Medical Device Regulation (MDR) enforce phthalate-free additives and biocompatibility testing protocols across European supply chains. China's NMPA and GB standards for disposable medical textiles impose additional filtration efficiency and cytotoxicity benchmarks on exporters. Stakeholders must monitor how evolving extended producer responsibility frameworks and single-use plastic restrictions in multiple jurisdictions recalibrate raw material selection and end-of-life recovery economics for spunbond products.
Market Dynamics
Medical-grade barrier specifications are collapsing the historical separation between commodity hygiene spunbond and surgical-grade performance materials, forcing capital reallocation toward composite meltblown-spunbond lines that satisfy both FDA device regulations and EPA stormwater filtration standards.
Growth Catalysts
- EU MDR biocompatibility mandates:The Medical Device Regulation's cytotoxicity and sensitization testing protocols are accelerating hospital procurement of certified spunbond surgical drapes and gowns across German and French healthcare systems.
- India's PLI scheme for technical textiles:Production-linked incentives for nonwoven manufacturing are attracting polypropylene resin processing investments to serve domestic diaper and sanitary product brands.
- Dual carbon goals in China:Beijing's carbon intensity reduction targets are pressuring spunbond producers to adopt energy-efficient extrusion and thermal bonding equipment.
Market Restraints
- Propylene feedstock volatility:Crude oil and naphtha price swings transmit directly into polypropylene pellet costs, compressing margins for commodity-grade spunbond producers in the Middle East.
- Technical limitation in fine-denier production:Achieving sub-1.5 denier filaments with consistent tensile strength remains constrained by spinneret design and quench air uniformity in high-speed lines.
- Substitution threat from spunlace:Hydroentangled cotton and viscose webs are capturing premium wipe and cosmetic pad applications where softness perception outweighs spunbond cost advantages.
Strategic Opportunities
- Underpenetrated Vietnam:Rising domestic diaper manufacturing and limited local spunbond capacity create import substitution potential for Thai and Indonesian producers.
- Agricultural crop cover expansion:Climate-adaptive farming investments in Spain and Italy are accelerating demand for UV-stabilized polypropylene row covers with 2-3 season durability.
- Technology convergence of spunbond-meltblown-spunbond:SMS composite lines capable of producing both surgical barrier fabrics and high-efficiency filtration media are opening dual-revenue streams.
Industry Challenges
- Certification timeline compression:FDA 510(k) clearance for new surgical drape materials now requires extensive biocompatibility documentation that extends product development cycles by 12-18 months.
- Capex intensity for multi-beam lines:Installing three-beam spunbond capacity with inline meltblown capability demands capital commitments exceeding 50 million euros, limiting entry for mid-scale regional players.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Spunbond Nonwovens Market |
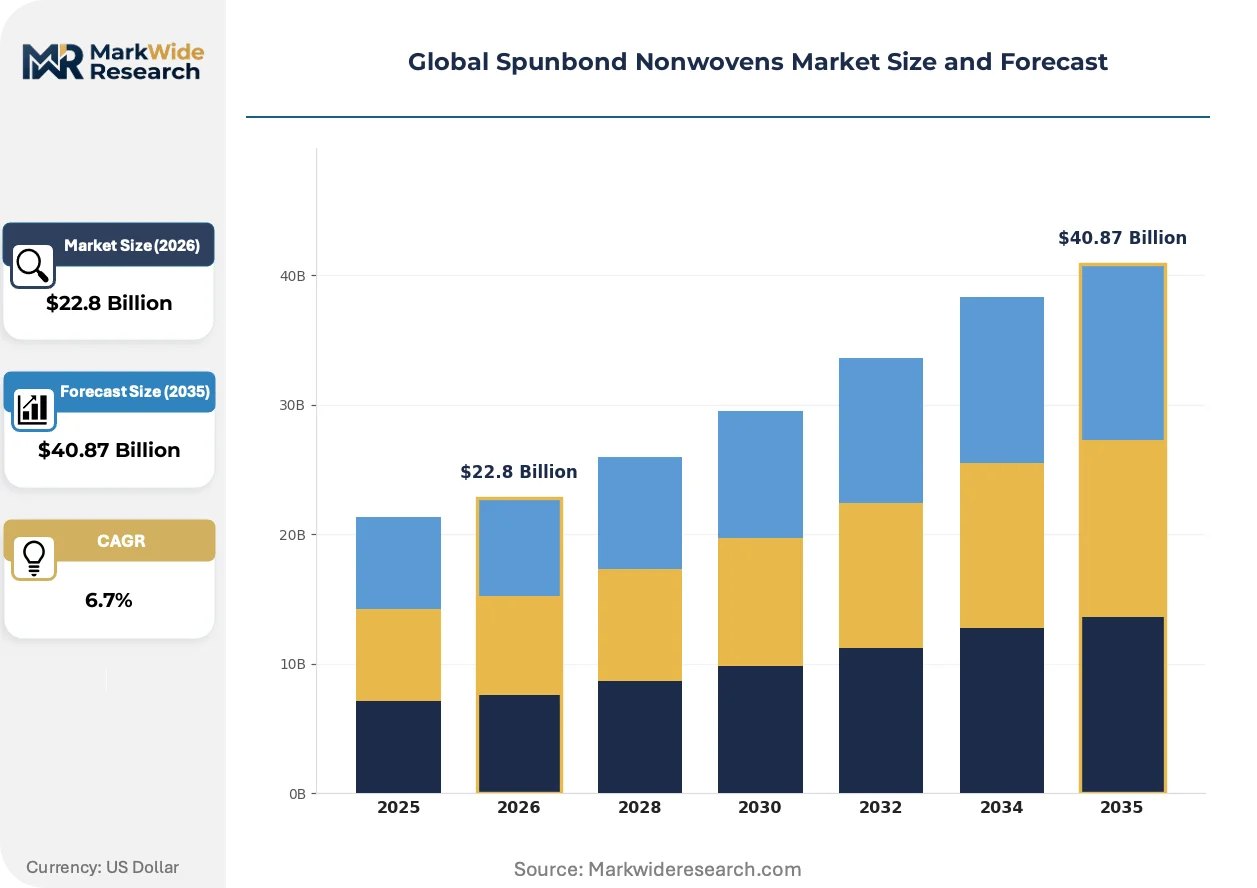
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $40.87 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Polyester, Nylon, Others Application: Consumer Products, Medical, Construction, Agriculture Technology: Hot Air Thru-air, Spinbond, Meltblown, Needle Punch End User: Healthcare, Automotive, Textile, Industrial |
| Companies Covered | DuPont, Pegas Nonwovens, Berry Global, Freudenberg Group, Kimberly-Clark Corporation, Asahi Kasei Corporation, Toray Industries, Fitesa, Avgol Nonwovens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Spunbond Nonwovens Market Shifts & Advancements
Bicomponent filament technology, recycled feedstock integration, and buyer consolidation in healthcare procurement are simultaneously reshaping product specifications, raw material sourcing, and commercial contracting structures across the spunbond value chain.
Bicomponent sheath-core spunbond filaments—combining polyethylene surface layers with polypropylene cores—are displacing monocomponent webs in premium diaper acquisition layers and medical topsheets where surface softness must coexist with core tensile strength. Japanese hygiene manufacturers are adopting these structures at scale for next-generation infant care products. The technology is displacing conventional spunbond in applications where liquid strike-through speed and rewet performance determine brand positioning.
REACH chemical compliance and the EU Green Deal's extended producer responsibility frameworks are mandating phthalate-free additive packages and documented recyclability pathways for single-use spunbond products sold into European healthcare and hygiene channels. German and French distributors now require mass-balance certification for recycled polymer content claims. Surgical gown manufacturers serving EU hospital purchasing groups are reformulating spin finishes and UV stabilizers to eliminate substances of very high concern.
Hospital buying consortiums in the United States are consolidating surgical pack procurement under national group purchasing organizations, compressing supplier rosters and demanding multi-year volume commitments with indexed polypropylene pricing. This concentration is displacing fragmented regional distributor networks that historically carried inventory for independent surgical centers. The shift is most visible in the southeastern states where health system mergers have reduced active spunbond gown suppliers from twelve to four contracted vendors.
Global Spunbond Nonwovens Market Segmentation
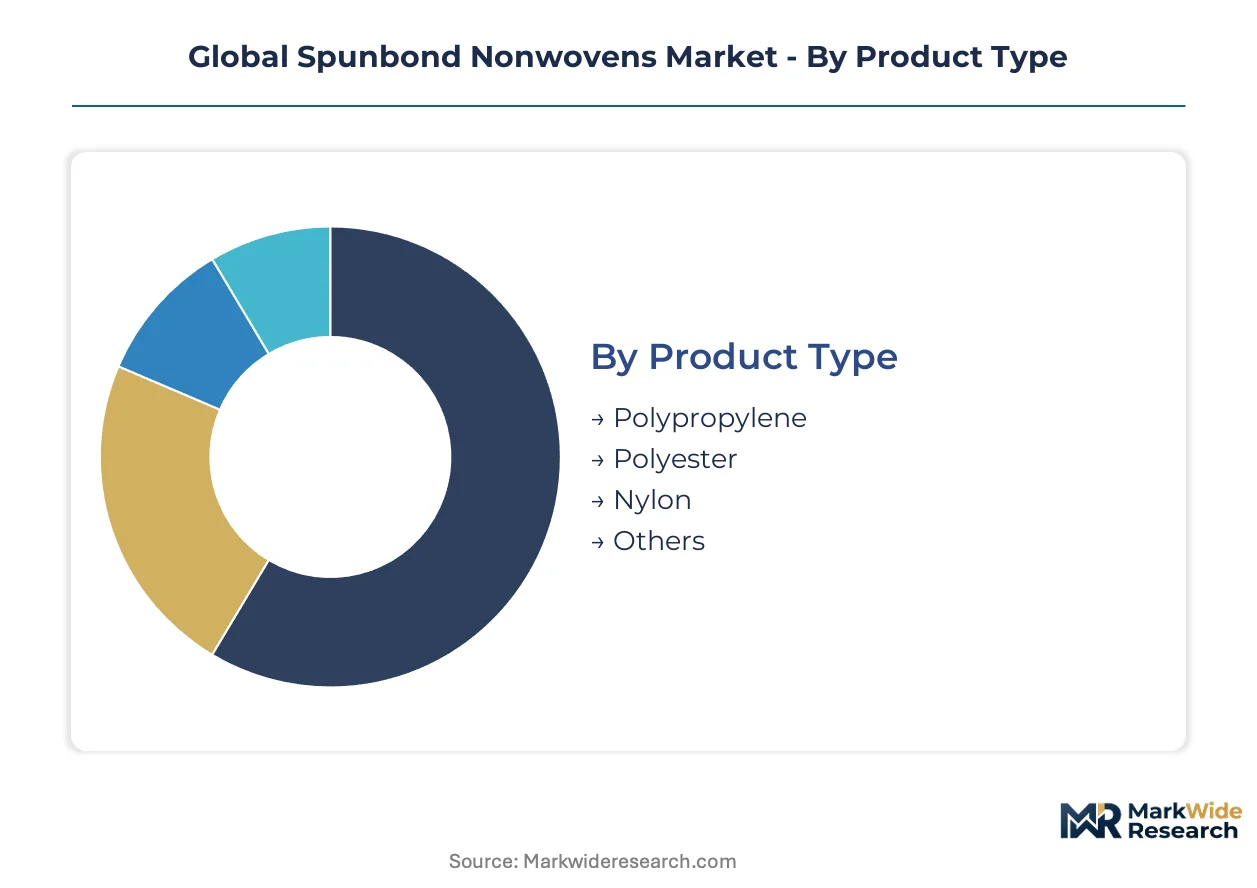
Segmentation in spunbond nonwovens separates commodity polypropylene hygiene fabrics from engineered barrier materials commanding divergent margin structures. Each dimension—polymer chemistry, end-use application, bonding technology, and customer vertical—carries distinct certification burdens and capital intensity requirements that reshape competitive positioning.
Product Type:
Domestic production concentrates on polypropylene for diaper and wipe manufacturers, while polyester and specialty grades serve export-oriented roofing and automotive Tier 1 suppliers.
- Polypropylene:Dominant thermoplastic resin with melt indices between 25–40 g/10min, thermally bonded into continuous-filament webs. Diaper manufacturers in India and China absorb regional capacity expansion as domestic hygiene brands displace imports.
- Polyester:Superior dimensional stability under thermal cycling makes this the default substrate for roofing membranes and automotive headliners. German automotive suppliers specify PET spunbond for interior trim applications requiring low fogging emissions.
- Nylon:High-tenacity filament structures serve abrasive industrial filtration and battery separator applications where chemical resistance outweighs cost sensitivity.
- Others:Bicomponent polyethylene-polypropylene sheath-core filaments and bio-based PLA variants address premium softness and compostability specifications in Japanese infant care markets.
Polypropylene commands the established base. The steepest expansion runs through bicomponent and bio-based alternatives.
Application:
Cost-tier stratification separates high-volume disposable hygiene from capital-intensive infrastructure and regulated medical segments.
- Consumer Products:Diaper acquisition layers, feminine hygiene topsheets, and household wipes constitute the volume anchor. Southeast Asian manufacturing clusters in Vietnam and Indonesia are absorbing new spunbond capacity as regional brands scale.
- Medical:Surgical drapes, gowns, and sterile barrier materials demand SMS composite structures meeting FDA 510(k) and EU MDR biocompatibility protocols. Hospital purchasing consolidation in the United States is compressing supplier rosters to four contracted vendors in several southeastern states.
- Construction:Geotextile drainage fabrics and roofing underlayments require UV-stabilized, high-tenacity constructions. Spanish and Italian infrastructure investments are accelerating demand for 2-3 season durable row covers and erosion control mats.
- Agriculture:Climate-adaptive farming investments are expanding polypropylene crop cover deployment for frost protection and moisture retention in Mediterranean growing regions.
Consumer products absorb the highest tonnage. Medical applications are climbing the fastest on regulatory upgrade cycles.
Technology:
Volume concentration favors high-speed spunbond lines, while premium filtration and barrier applications require composite meltblown integration.
- Hot Air Thru-air:Bulked, high-loft structures for absorbent hygiene products where softness and fluid acquisition speed determine brand positioning. Japanese manufacturers lead adoption for next-generation infant care.
- Spinbond:Core continuous-filament extrusion technology forming the backbone of commodity hygiene and geotextile production. China's dual carbon goals are pressuring producers to adopt energy-efficient thermal bonding equipment.
- Meltblown:Microfiber webs delivering filtration efficiency for surgical masks and liquid barrier layers. Composite SMS lines capable of inline meltblown deposition command capital commitments exceeding 50 million euros.
- Needle Punch:Mechanical entanglement for heavy-duty geotextiles and synthetic leather substrates where dimensional stability under load is critical.
Spunbond retains the volume foundation. Meltblown-spunbond composites are expanding most quickly on medical barrier demand.
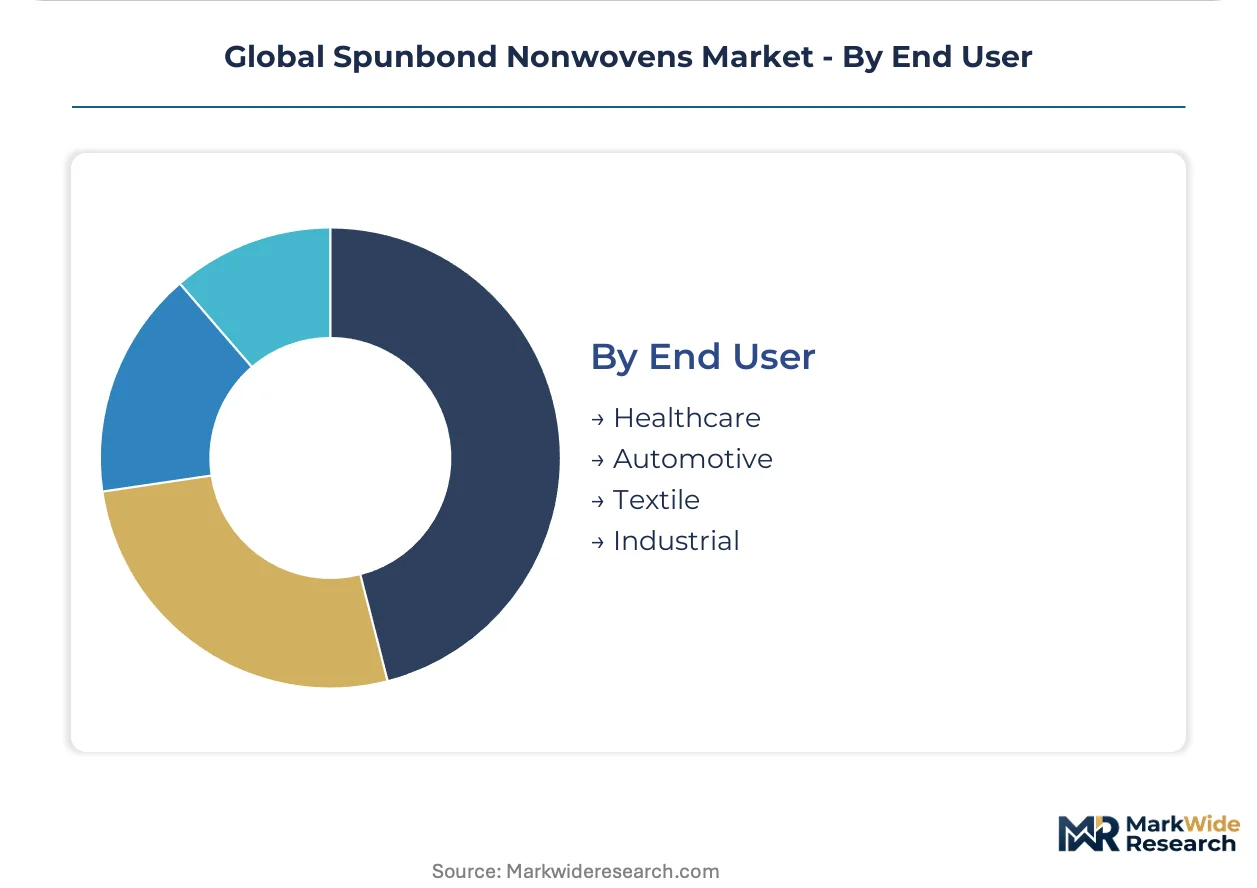
End User:
Customer-type fragmentation separates regulated institutional procurement from price-sensitive consumer goods manufacturing.
- Healthcare:Hospital systems and surgical centers demand certified barrier materials with documented biocompatibility testing. EU MDR cytotoxicity protocols are accelerating procurement upgrades across German and French healthcare networks.
- Automotive:Tier 1 interior trim suppliers specify polyester spunbond for headliners, door panels, and trunk liners requiring thermal dimensional stability and low VOC emissions.
- Textile:Apparel interlinings, synthetic leather substrates, and footwear components utilize needle-punched and thermal-bonded spunbond for structural reinforcement.
- Industrial:Filtration media, battery separators, and abrasive polishing pads exploit nylon and specialty polymer spunbond for chemical and mechanical durability.
Healthcare anchors premium pricing power. Automotive and industrial segments are gaining share fastest on electrification and infrastructure investment cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hygiene buyers in India and China exhibit extreme price elasticity, while German hospital purchasing groups absorb premium pricing for certified barrier materials without volume reduction.
United States
Hospital buying consortiums in the southeastern states have consolidated surgical pack procurement under national group purchasing organizations, reducing active spunbond gown suppliers from twelve to four contracted vendors. FDA 510(k) clearance timelines now extend product development cycles by 12-18 months due to expanded biocompatibility documentation requirements. Berry Global leverages its North American meltblown-spunbond composite lines to sustain supply contracts with major hospital purchasing groups.
Germany
Freudenberg Group anchors European medical nonwoven demand through its specialization in hydrophobic spunbond layers for infection control apparel. EU MDR cytotoxicity and sensitization testing protocols accelerate hospital procurement of certified surgical drapes and gowns across German healthcare systems. REACH chemical compliance mandates phthalate-free additive packages and documented recyclability pathways for single-use spunbond products sold into European healthcare channels.
China
Beijing's dual carbon goals pressure spunbond producers to adopt energy-efficient extrusion and thermal bonding equipment as domestic capacity scales to serve regional diaper and surgical gown manufacturers. NMPA and GB standards for disposable medical textiles impose additional filtration efficiency and cytotoxicity benchmarks on exporters. Yangtze River Delta manufacturing clusters absorb new polypropylene spunbond capacity as domestic hygiene brands displace imports.
India
Production-linked incentives for nonwoven manufacturing attract polypropylene resin processing investments to serve domestic diaper and sanitary product brands. BIS certification requirements and evolving technical textile standards reshape material specifications for hygiene applications. Gujarat and Maharashtra industrial corridors concentrate new spunbond line installations as regional manufacturers scale to capture import substitution opportunities.
Vietnam
Rising domestic diaper manufacturing and limited local spunbond capacity create import substitution potential for Thai and Indonesian producers. The country's national technical textile regulator imposes quality benchmarks that favor suppliers with established ASEAN supply chains. Ho Chi Minh City manufacturing zones attract hygiene product final assembly operations that drive upstream nonwoven demand.
Global Spunbond Nonwovens Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the spunbond nonwovens market. Integrated hygiene conglomerates with captive diaper and wipe manufacturing dominate volume consumption, while specialized medical barrier fabricators command premium pricing through certification depth. Three archetypes define competitive positioning: multinational hygiene integrators, regional technical textile specialists, and diversified chemical conglomerates with nonwoven divisions. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with multi-beam line investments exceeding 50 million euros limiting entry for mid-scale regional players.
Among North American-based multinationals, DuPont, Berry Global, and Kimberly-Clark Corporation exemplify distinct strategic positions. DuPont occupies a technology-specialist archetype rooted in material science heritage. Berry Global represents scale-driven composite manufacturing integration. Kimberly-Clark Corporation anchors consumer hygiene spunbond volumes through captive end-use manufacturing. These three entities illustrate how geographic origin and corporate structure shape competitive positioning without converging on identical capability profiles.
| Leading Market Players |
|---|
| DuPont |
| Pegas Nonwovens |
| Berry Global |
| Freudenberg Group |
| Kimberly-Clark Corporation |
| Asahi Kasei Corporation |
| Toray Industries |
| Fitesa |
| Avgol Nonwovens |
| Others |
Supply & Pricing Matrix
Bicomponent sheath-core filaments displacing monocomponent polypropylene webs in Japanese infant care markets simultaneously redraws raw material sourcing patterns toward specialized polyethylene suppliers and compresses margin structures for commodity-grade producers locked into single-resin contracts.
Pricing Analysis
After-sales technical service contracts and multi-year maintenance agreements on SMS composite lines drive lifetime value for equipment suppliers serving hospital purchasing groups. Pricing stratifies across premium, standard, and economy tiers based on FDA 510(k) certification depth and volume scale commitments. Cost compression in commodity-grade spunbond is intensifying because Indian and Chinese domestic capacity expansion feeds price elasticity among regional hygiene manufacturers. Consumer diaper producers exhibit extreme price sensitivity, while German hospital systems absorb premium pricing for EU MDR-certified barrier materials without volume reduction.
Supply Chain Analysis
Inventory buffers for polypropylene resin have compressed to 3-4 weeks across Southeast Asian converters as just-in-time procurement spreads from automotive into hygiene manufacturing. Supply concentrates in China, India, and Saudi Arabia for polypropylene resin extrusion, while Germany and Japan anchor specialized meltblown composite equipment production. Raw material flows draw from naphtha crackers, propane dehydrogenation units, and recycled post-industrial scrap streams. Single-source vulnerability runs through Middle Eastern propylene feedstock exposed to crude oil volatility. Distribution runs through regional distributor networks in fragmented markets and direct mill contracts under consolidated hospital purchasing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Spunbond Nonwovens Market sits at a post-pandemic normalization phase that tracks healthcare capital expenditure cycles and infrastructure investment waves.
For Market Incumbents: Secure multi-year volume commitments with indexed polypropylene pricing from consolidated US hospital purchasing groups before additional supplier roster compression. Anchor backward integration into bicomponent resin compounding to defend margin position against commodity-grade imports from scaling Chinese producers. Deepen certification investment in EU MDR biocompatibility protocols to sustain premium positioning as regulatory barriers rise. For New Entrants and Emerging Players: Anchor in Vietnam's underpenetrated diaper manufacturing corridor where limited local spunbond capacity creates import substitution openings for Thai and Indonesian producers with established ASEAN logistics. Target agricultural crop cover applications in Mediterranean climate zones where UV-stabilized specifications favor nimble regional players over hygiene-focused multinationals. Lead with sustainability-certified recycled content offerings to differentiate against incumbent virgin-resin positions. For Investors and Strategic Acquirers: The market sits at a mid-cycle consolidation phase that favors specialized medical barrier fabricators with certification depth over commodity hygiene volume players. Long-term viability rests on exposure to healthcare procurement consolidation and climate-adaptive agricultural investment cycles. Acquisition targets should demonstrate established FDA 510(k) or EU MDR technical files rather than pure capacity scale. Monitor hospital group purchasing organization contract renewal windows as inflection signals for supplier roster stability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bicomponent Resin Compounding | Captures margin pool from sheath-core filament demand in Japanese infant care markets. |
| EU MDR Certification Investment | Unlocks German and French hospital procurement channels with mandated cytotoxicity testing protocols. |
| Multi-Beam SMS Capacity Expansion | Serves dual surgical barrier and high-efficiency filtration revenue streams from single asset base. |
| Recycled Feedstock Mass-Balance Certification | Satisfies REACH chemical compliance and EU Green Deal extended producer responsibility mandates. |
| Long-Term Supply Agreement with Hospital GPOs | Defends volume position against roster compression in US southeastern health system mergers. |
Research Methodology
Cross-validation between primary interviews with plant managers at nonwoven manufacturing facilities and secondary validation through customs trade data and technical textile association reports anchors the qualitative findings. The research program combined structured discussions with procurement leads at diaper and surgical gown OEMs, distribution channel partners in ASEAN markets, and technical R&D directors at resin suppliers. Secondary sources included SEC 10-K filings of listed nonwoven producers, BIS and NMPA regulatory filings, and European technical textile federation capacity surveys. Bottom-up demand modeling triangulated against top-down polymer consumption estimates from regional chemical industry associations.
Sensitivity analysis around propylene feedstock price volatility and hospital procurement consolidation scenarios shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include polymer chemistry tier, end-use application vertical, bonding technology type, and geographic production cluster. CAGRs were derived from trend extrapolation of historical capacity utilization rates and forward-looking capital expenditure announcements. Industry-specific forecast inputs incorporated EU MDR implementation timelines and India's PLI scheme disbursement patterns for technical textiles.
Decision-makers should treat outputs as directional under assumptions of sustained healthcare infrastructure investment and moderate oil price environments; material deviation in either would warrant model refresh. Specific risk factors that could revise forecasts include accelerated single-use plastic restrictions, abrupt propylene feedstock price spikes, or faster-than-expected hospital purchasing consolidation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nonwoven Materials
Nonwoven Weed Control Fabric Market
Nonwoven Materials
Nonwoven Protective Clothing Market
Nonwoven Materials
Global Polypropylene (PP) Nonwoven Fabrics Market
Nonwoven Materials
Hygienic Non-Woven Fabrics Market
Nonwoven Materials
PP Nonwovens Market
Nonwoven Materials
Global Nonwoven Materials and Products Market
Nonwoven Materials
Staples PP Nonwovens Market
Nonwoven Materials
Nonwoven Decking Market
Nonwoven Materials
Non Woven Printing Machine Market
Nonwoven Materials
Nonwoven Polyester Fabric Market
Nonwoven Materials
Non-Woven Glass Fiber Prepreg Market
Nonwoven Materials
India Non-Woven Geotextiles Market
Nonwoven Materials
Global Melt-Blown Nonwovens Market
Nonwoven Materials
Non Woven Converting Machine Market
Nonwoven Materials
Global Non Woven Fabric Market
Nonwoven Materials
Nonwoven Flanging Market