
 Staples PP Nonwovens Market | 2026-2036
Staples PP Nonwovens Market Size, Share, and Industry Trends Forecast 2026-2036
Staples PP Nonwovens Market Intelligence
Demand from large-volume converters in the hygiene sector versus specialized industrial end users is bifurcating the market's customer base. Large integrated producers like ExxonMobil leverage their control over polypropylene resin supply. Meanwhile, dedicated nonwoven manufacturers such as Fitesa and PEGAS compete on production scale and material innovation for major hygiene applications. Kimberly Clark operates as a major captive consumer and buyer, influencing product development cycles.
Staples polypropylene (PP) nonwovens are engineered fabrics created from short, discrete polypropylene fibers bonded together through mechanical, thermal, or chemical processes. These materials are valued for their liquid repellency, strength-to-weight ratio, and cost-effectiveness, serving as critical components in disposable and durable goods. The hygiene segment is the largest volume driver, whereas geotextiles and filtration demand higher technical specifications. Spunbond technology dominates production, while the thermobond process gains in applications requiring softer textures.
Product safety and material standards are governed by bodies like the US FDA for medical and food contact applications and the EU's REACH regulation concerning chemical substances. In China, GB standards dictate performance criteria for nonwovens used in hygiene products, influencing market access for foreign and domestic producers. Stakeholder focus now turns to balancing performance requirements with the growing pressure for material circularity and end-of-life solutions.
Market Dynamics
The fundamental market dynamic is the bifurcation between high-volume, cost-sensitive hygiene applications and lower-volume, high-specification industrial uses. This split influences everything from production scale and technology choice to supply chain structure and customer relationships.
Growth Catalysts
- Material Innovation:Advances in thermobond and spunbond technologies are yielding softer, more absorbent materials, directly fueling consumption in the adult incontinence and feminine hygiene product sectors.
- Geographic Demand Concentration:China's vast and expanding healthcare system, coupled with its large-scale construction projects requiring geotextiles, provides a massive and centralized demand base for PP nonwovens.
- Hygiene Standard Elevation:Rising public health awareness and government initiatives in markets like India and Brazil are boosting demand for disposable hygiene products, creating new volume opportunities.
Market Restraints
- Input Cost Volatility:The market is highly sensitive to fluctuations in polypropylene resin prices, which are tied to volatile crude oil markets, impacting producer margins and pricing stability.
- Substitution Threats:In certain applications, particularly wipes and some durable goods, PP nonwovens face competition from materials like PET, viscose, and bio-based polymers like PLA.
- Regulatory Friction:The EU's REACH regulation imposes strict controls on chemical substances used in binders and additives, increasing compliance costs and complexity for producers selling into Europe.
Strategic Opportunities
- Advanced Filtration Media:Developing high-efficiency meltblown and composite PP nonwovens for HVAC systems, water purification, and medical-grade masks presents a high-margin growth avenue.
- Durable Goods Penetration:Untapped potential exists in durable applications like automotive interiors, furniture, and bedding, where PP nonwovens can replace heavier, more expensive textiles.
- Circular Economy Solutions:Developing chemically or mechanically recyclable PP nonwoven products, or those incorporating recycled content, offers a significant opportunity to meet sustainability mandates from brand owners.
Industry Challenges
- End-of-Life Management:A primary operational challenge is the lack of scalable collection and recycling infrastructure for post-consumer PP nonwoven products, particularly contaminated hygiene items.
- Standardization Gaps:Divergent performance criteria, such as China's GB standards for hygiene products versus US FDA requirements, create testing and compliance burdens for producers operating across multiple regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Staples PP Nonwovens Market |
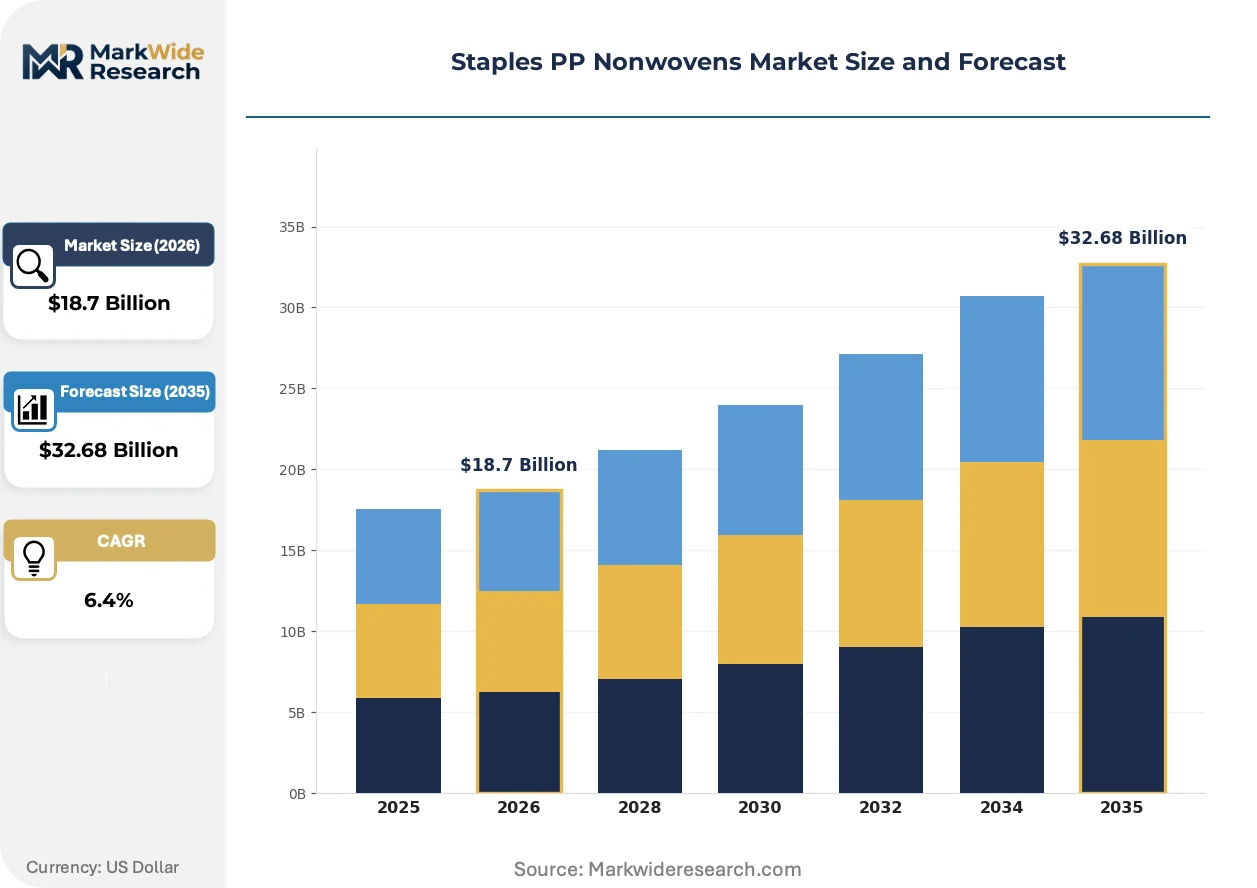
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spunbond, Meltblown, Needle Punch, Thermobond Application: Medical, Hygiene, Geotextiles, Filtration End User: Healthcare, Agriculture, Construction, Automotive Thickness: Lightweight, Medium Weight, Heavyweight, Ultra-Heavyweight |
| Companies Covered | Kimberly Clark, PEGAS, ExxonMobil, Fitesa, AVGOI, Mitsui, First Quality, Toray, SABIC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Staples PP Nonwovens Market Strategic Shifts & Innovations
Material science is advancing on two parallel tracks: enhancing functional performance for demanding applications and designing for circularity. This dual focus is driving innovation in polymer chemistry, fiber formation, and bonding technologies to meet new regulatory and consumer expectations.
Bi-Component Fiber Development
Bi-component fiber technology creates sophisticated core-sheath or side-by-side fiber structures, combining different polymer properties within a single filament. Hygiene product converters are rapidly adopting these materials to engineer superior softness, loft, and fluid management in premium diapers and sanitary pads. This technology is miniaturizing the effective fiber denier to achieve unparalleled tactile properties, compressing the performance gap between nonwovens and traditional textiles.
Single-Use Plastics Regulation
The European Union's Single-Use Plastics Directive imposes new obligations on products containing plastic, including many types of nonwoven wipes. This directive mandates specific on-pack marking to inform consumers about plastic content and proper disposal, while also establishing extended producer responsibility schemes. The personal care and industrial wipes segments are most affected, forcing an acceleration of research into both plastic-free alternative materials and viable end-of-life solutions for PP-based products.
Certification-Driven Procurement
A notable shift in buying behavior is the prioritization of materials with sustainability credentials, such as those certified by OEKO-TEX or those with verifiable life-cycle assessment data. This change disrupts procurement models based purely on price and technical performance, creating an advantage for suppliers who offer transparency and documented environmental footprints. This pattern is most pronounced in the European consumer goods sector and North American construction market, where eco-labels are becoming a critical purchasing factor.
Staples PP Nonwovens Market Segmentation
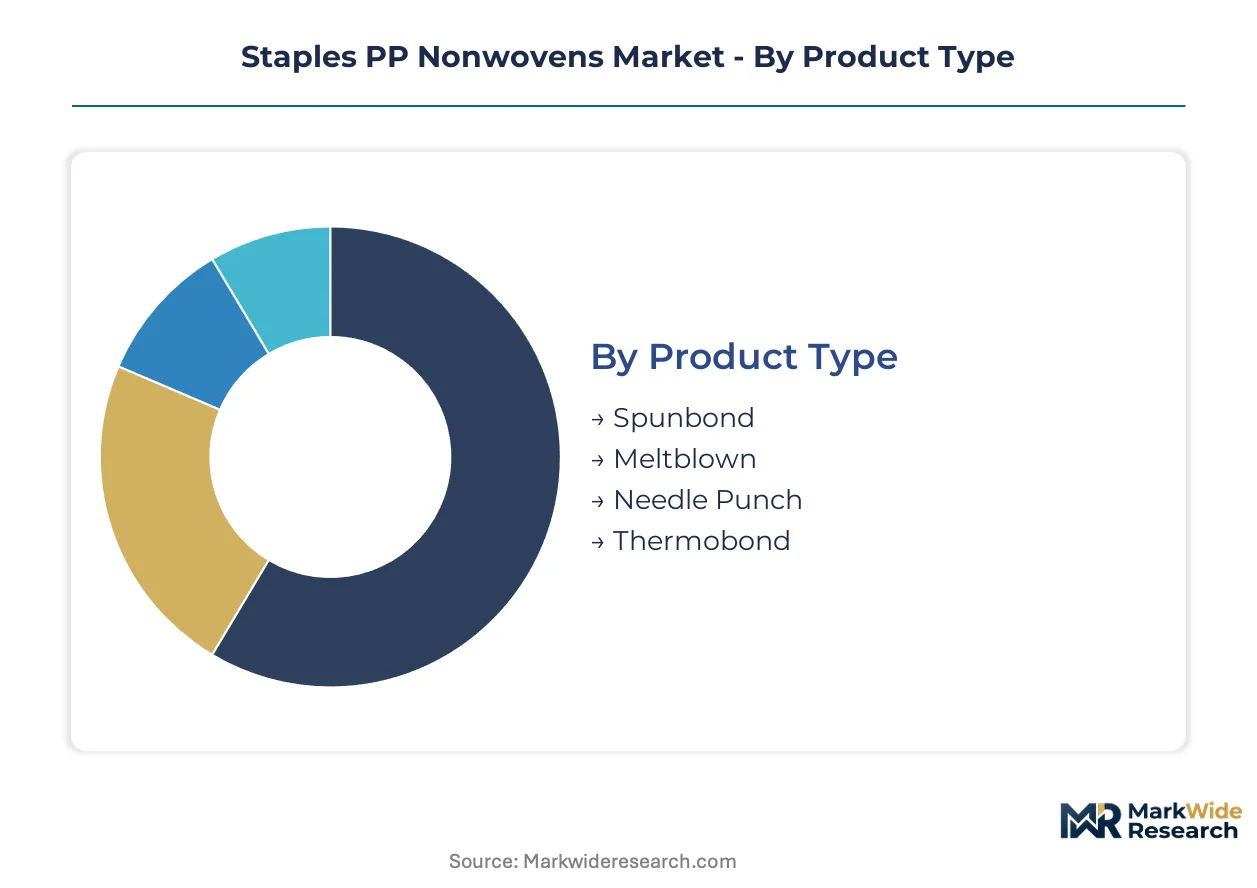
The Staples PP Nonwovens market is meticulously segmented to reflect the diverse material characteristics, processing technologies, and end-use applications driving demand. This granular breakdown clarifies where material innovation is most impactful, how different production methods cater to specific performance needs, and which end-user sectors represent the most significant volume drivers or growth opportunities for manufacturers.
Product Type:
Some PP nonwoven product types see concentrated production for domestic consumption, while others are optimized for global export to meet specialized requirements.
- Spunbond:This product type consists of continuous polypropylene filaments thermally bonded, offering high strength, excellent drape, and cost-effectiveness. Production is heavily concentrated in China, serving its vast domestic hygiene and construction industries due to efficient large-scale manufacturing.
- Thermobond:Thermally bonded fibers create a softer, bulkier fabric with enhanced comfort and fluid management properties, often incorporating bi-component fibers. Demand is significant in European and North American markets for premium adult incontinence and feminine care products, driven by consumer preference for tactile attributes.
- Meltblown:Characterized by extremely fine fibers and high surface area, meltblown nonwovens are critical for filtration media and medical masks.
- Needle Punch:Mechanically entangled fibers create durable, robust fabrics often used in geotextiles and automotive applications requiring high tensile strength.
Spunbond commands the established base. The steepest expansion runs through Thermobond.
Application:
The application landscape for PP nonwovens exhibits distinct cost structures, ranging from high-volume, price-sensitive uses to specialized, value-added functions.
- Hygiene:This segment includes disposable diapers, adult incontinence products, and feminine hygiene items, utilizing PP nonwovens for top sheets, back sheets, and acquisition layers due to their liquid repellency and softness. Demand is accelerating in markets like India and Brazil, driven by rising public health awareness and accessibility to affordable products.
- Filtration:PP nonwovens are engineered into high-efficiency air, liquid, and gas filtration media, leveraging their fine fiber structure and chemical resistance. Advanced filtration media for HVAC systems and water purification in European and North American industrial sectors represent a high-margin growth area.
- Medical:PP nonwovens form essential components of surgical drapes, gowns, sterilization wraps, and face masks, providing barrier protection against contaminants.
- Geotextiles:These durable fabrics are used in civil engineering for soil stabilization, erosion control, and drainage in large-scale infrastructure projects.
Hygiene applications drive significant volume, while filtration presents a high-margin growth avenue.
End User:
End-user segments for PP nonwovens range from large-scale industrial consumers to specialized niche manufacturers.
- Healthcare:This sector utilizes PP nonwovens extensively for disposable medical products, protective apparel, and wound care, emphasizing sterility and barrier properties. China's expanding healthcare infrastructure and aging population are major demand drivers for these materials.
- Construction:The construction industry consumes PP nonwovens primarily as geotextiles for road building, foundation stabilization, and erosion control. Large-scale infrastructure projects in China and other developing economies contribute substantially to this segment's volume.
- Agriculture:PP nonwovens are employed in crop covers, weed control fabrics, and protective nets to enhance agricultural yields and protect crops.
- Automotive:Used for interior components such as headliners, carpet backings, and insulation, PP nonwovens offer lightweighting and acoustic benefits.
The healthcare sector consumes high volumes, whereas automotive applications offer potential for durable goods penetration.
Thickness:
PP nonwoven thickness directly correlates with specific performance requirements and application areas.
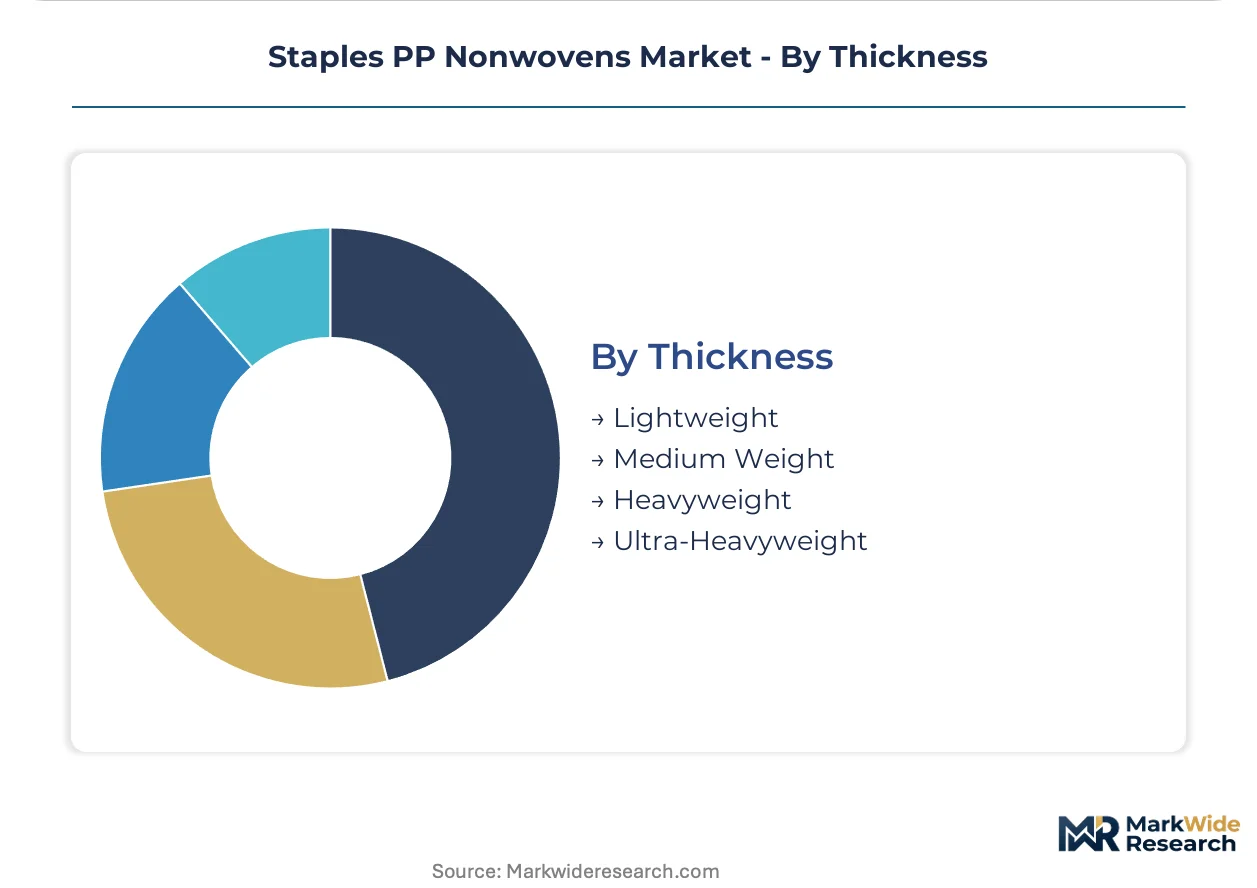
- Lightweight:Characterized by low grammage, these nonwovens offer high breathability, softness, and drape, making them ideal for skin-contact applications. They are critical in the manufacture of premium baby diapers and feminine hygiene products in developed markets, where comfort is a primary consumer consideration.
- Heavyweight:These nonwovens possess high grammage, providing enhanced strength, durability, and robust barrier properties. Demand is concentrated in industrial applications such as geotextiles for civil engineering projects and high-performance filtration media, where material integrity is paramount.
- Medium Weight:Offering a balance of strength and flexibility, medium-weight nonwovens are commonly used in general-purpose wipes, medical gowns, and protective apparel.
- Ultra-Heavyweight:Designed for extreme durability and load-bearing capacity, these specialized nonwovens find application in demanding civil engineering and industrial textile projects.
Lightweight nonwovens are critical for disposable hygiene, while heavyweight variants serve demanding industrial applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's large-scale production of spunbond PP nonwovens serves its extensive domestic hygiene and construction sectors. This output also flows into global markets, meeting demand for cost-effective materials. Meanwhile, European and North American markets prioritize thermobond for premium adult incontinence and feminine care products.
China
Demand for PP nonwovens in China is robust, driven by its vast domestic healthcare industry and extensive construction projects. GB standards dictate performance criteria for nonwovens in hygiene products, influencing market access. The Yangtze River Delta region, a major manufacturing hub, sees significant production and innovation in nonwoven materials.
United States
The United States market sees strong demand for PP nonwovens in medical and automotive applications. The US FDA regulates medical and food contact applications, ensuring material safety and compliance. Southern states, with their growing manufacturing base, are concentrating production of specialized nonwovens for durable goods.
Germany
Germany represents a significant market for high-specification PP nonwovens, particularly in filtration and advanced medical applications. The EU's REACH regulation imposes strict controls on chemical substances, impacting production processes. The Rhine-Ruhr region, a traditional industrial heartland, hosts numerous specialized nonwoven manufacturers focusing on technical textiles.
India
India's market for PP nonwovens is expanding rapidly, fueled by rising public health awareness and a growing hygiene sector. BIS standards provide quality benchmarks for various industrial and consumer products. Maharashtra, a key economic state, is experiencing increased investment in nonwoven production facilities to meet domestic demand.
Brazil
Brazil exhibits accelerating demand for disposable hygiene products, creating new volume opportunities for PP nonwovens. ANVISA, the national health surveillance agency, oversees product safety and quality in medical and hygiene sectors. The São Paulo state, a major industrial center, is a focal point for nonwoven conversion and distribution across Latin America.
Staples PP Nonwovens Market Key Industry Players
Player mix skews toward large integrated producers controlling raw material supply and specialized nonwoven manufacturers. The market exhibits a clear bifurcation between high-volume, cost-sensitive hygiene applications and lower-volume, high-specification industrial uses. Strategic archetypes include upstream resin suppliers, dedicated nonwoven converters, and major captive brand owners. Competitive moves involve significant capacity expansion, continuous material innovation, and strategic partnerships to secure raw material access.
Among the integrated material suppliers, ExxonMobil exemplifies control over polypropylene resin supply, leveraging its position to influence pricing dynamics across the value chain. Dedicated nonwoven manufacturers like Fitesa occupy a position focused on production scale and material innovation, particularly for major hygiene applications where specialized material properties are critical. This group competes on efficiency and advanced fiber engineering. Kimberly Clark represents a significant captive consumer and buyer, influencing product development cycles through its extensive internal demand for finished hygiene products and setting benchmarks for material performance.
| Leading Market Players |
|---|
| Kimberly Clark |
| PEGAS |
| ExxonMobil |
| Fitesa |
| AVGOI |
| Mitsui |
| First Quality |
| Toray |
| SABIC |
| Others |
Cost & Logistics Intelligence
Large-scale production economies in spunbond technology underpin the Staples PP nonwovens market, driving supply concentration in Asia and setting competitive price floors. This scale also influences material cost stability for high-volume hygiene applications.
Pricing Analysis
The pricing gap between commodity spunbond and advanced thermobond materials defines market value. Contract-based long-term offtake agreements dominate for high-volume hygiene applications. Price differentiation stems from material technical specifications, like softness for premium feminine care, and the certification level for medical-grade products. Pricing softness runs through basic spunbond nonwovens due to overcapacity in China; hygiene sector converters exhibit the highest price sensitivity, while specialized industrial end-users prioritize performance.
Supply Chain Analysis
Just-in-time inventory strategies are common for high-volume PP nonwovens, though strategic stockpiles are maintained for critical medical applications. Geographic supply concentration centers on China for spunbond materials, with Europe and North America producing specialized thermobond. The market relies on polypropylene resin as its primary input, making commodity price volatility a significant structural risk. Distribution runs through large-volume converters for hygiene products and specialized distributors for industrial and medical sectors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Staples PP nonwovens market is undergoing a platform-economics inflection, driven by the integration of material science with digital traceability solutions. This shift fosters a new ecosystem for circularity and sustainable product development.
For Market Incumbents: Consolidate existing production assets, particularly in cost-effective spunbond capacity, to counter pricing softness from Asian oversupply. Deepen backward integration into polypropylene resin production to mitigate input cost volatility. Invest in R&D for advanced thermobond technologies, enhancing material properties to defend against substitution threats from bio-based polymers. Leverage established customer relationships in hygiene to reinforce long-term supply contracts.
For New Entrants and Emerging Players: Certification fast-tracks for sustainable materials, such as OEKO-TEX or REACH compliance, provide a market entry point. Target the premium adult incontinence and feminine care segments in Europe and North America, where demand for softer, more absorbent materials is rising. Focus on developing bi-component fiber technologies for superior tactile properties. A go-to-market angle emphasizing verifiable life-cycle assessment data will attract brand owners seeking sustainability credentials.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialized nonwoven manufacturers with strong intellectual property in advanced materials. The long-term viability of this market hinges on sustainable innovation and circular economy solutions over the next decade. Target acquisition profiles include mid-sized firms with proprietary meltblown or bi-component fiber technologies. The signal to watch for inflection is the widespread adoption of chemically recyclable PP nonwovens by major hygiene brands.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Thermobond | Expands production of softer materials for premium hygiene products in European markets. |
| R&D for Bi-Component Fibers | Enhances fluid management and tactile properties, critical for advanced diaper and pad designs. |
| Circular Economy Partnership | Develops scalable collection and recycling infrastructure for post-consumer PP nonwoven products. |
| Geographic Market Penetration | Targets rising public health awareness and demand for hygiene products in India and Brazil. |
| Certification Investment (e.g., OEKO-TEX) | Meets sustainability mandates from brand owners and facilitates market access in Europe. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through primary interviews, validated with extensive secondary research. Stakeholder roles included nonwoven manufacturers, hygiene product converters, material science R&D directors, and procurement leads. Secondary data sources comprised industry association reports, government trade statistics, company financial filings, and technical journals. This approach ensured robust bottom-up and top-down triangulation for market sizing and forecasting.
The forecast horizon extends across the analysis window, utilizing a robust analytical framework. Segmentation dimensions included product type, application, end-user, thickness, and regional regulatory compliance. Compound annual growth rates were derived from historical trends and projected demand drivers. Key forecast inputs included polypropylene resin price forecasts and demographic shifts impacting hygiene product consumption.
Underlying assumptions cover stable geopolitical conditions and consistent regulatory enforcement, with deviation risk concentrated in crude oil price volatility. Forecasts reflect these foundational assumptions. Revision becomes warranted when significant shifts in trade policies or material science breakthroughs cross critical thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nonwoven Materials
Absorbable Nonwoven Textiles Market
Nonwoven Materials
India Non-Woven Geotextiles Market
Nonwoven Materials
Non Woven Fabric Making Machine Market
Nonwoven Materials
Global Melt-Blown Nonwovens Market
Nonwoven Materials
Nonwoven Weed Control Fabric Market
Nonwoven Materials
Nonwoven Protective Clothing Market
Nonwoven Materials
Asia-Pacific Non-Woven Fabric Market
Nonwoven Materials
Global Spunbond Nonwovens Market
Nonwoven Materials
Nonwoven Fabric Production Line Market
Nonwoven Materials
PP Nonwovens Market
Nonwoven Materials
Meltblown Fabrics Market
Nonwoven Materials
Non-Wood Fiber Market
Nonwoven Materials
Non Woven Printing Machine Market
Nonwoven Materials
Non-Woven Glass Fiber Prepreg Market
Nonwoven Materials
Global Wet Laid Nonwovens Market
Nonwoven Materials
Global Polypropylene (PP) Nonwoven Fabrics Market