
 Global Melt-Blown Nonwovens Market | 2026-2036
Global Melt-Blown Nonwovens Market Size, Share, and Industry Trends Forecast 2026-2036
Global Melt-Blown Nonwovens Market Foresight
Aftermarket filter replacement revenue is fragmenting across regional service networks as original equipment manufacturers lose captive aftermarket share to independent distributors. Freudenberg Performance Materials leverages its integrated media-to-module supply chain to retain installed-base loyalty. Berry Global Inc competes through high-volume polypropylene capacity positioned near North American hygiene converters. Toray Industries Inc anchors Asian filtration demand with precision-caliber melt-blown grades certified for cleanroom applications.
Melt-blown nonwovens are microfiber webs produced by extruding thermoplastic resin through fine die orifices and attenuating filaments with high-velocity hot air, yielding fiber diameters of 0.5–10 microns and basis weights from 10 to 300 gsm for barrier, filtration, and absorption functions. Polypropylene dominates current output due to its low melt viscosity and established spinneret infrastructure, though polyamide variants command premium positioning in liquid filtration where chemical resistance defines performance. Spunbond-meltblown-spunbond composites retain structural importance in medical drapes and surgical gowns, while standalone melt-blown layers are displacing glass microfiber in HVAC applications.
EPA National Emission Standards for Hazardous Air Pollutants constrain solvent-based bonding alternatives, indirectly strengthening thermal and hydroentanglement process demand for melt-blown substrates. REACH substance restrictions on persistent organic pollutants filter through to raw material qualification protocols, extending compliance timelines for European suppliers. ISO 16890 test methods for air filter performance are displacing older EN 779 ratings, forcing media producers to recalibrate fiber diameter distributions. Stakeholders must track polymer price volatility against filter end-user contract structures to protect margin pools.
Market Dynamics
Polymer feedstock volatility and circular economy mandates are compressing margin pools while forcing capital reallocation toward recycled-content extrusion lines and solvent-free bonding infrastructure.
Growth Catalysts
- HEPA-grade air filtration mandates:Industrial facilities in Germany and the United States are retrofitting HVAC systems to meet stricter particulate capture standards, pulling demand for sub-micron fiber grades.
- EU Green Deal circular economy requirements:Binding recycled content thresholds for single-use medical textiles are redirecting R&D budgets toward post-consumer polypropylene purification technologies.
- Cleanroom certification expansion:Semiconductor fabrication investments in Taiwan and South Korea are specifying ISO 14644-compliant melt-blown media for airborne molecular contamination control.
Market Restraints
- Propylene monomer price volatility:Naphtha-cracker output fluctuations in the Middle East Gulf are transmitting cost instability directly to converter margin structures.
- Spunbond capacity concentration:Three integrated producers control roughly two-thirds of European SMS composite substrate supply, limiting bargaining leverage for standalone melt-blown specialists.
- Glass microfiber residual performance:High-temperature liquid filtration above 120°C still favors borosilicate microfiber where thermal dimensional stability is non-negotiable.
Strategic Opportunities
- Battery separator membrane convergence:Ceramic-coating of ultra-fine melt-blown webs for lithium-ion cell applications is hybridizing two previously distinct supply chains in Japan.
- India medical textile localization:PLI scheme incentives for domestic nonwoven surgical gown production are creating first-mover advantages for extrusion equipment suppliers with local service presence.
- Direct-to-converter digital platforms:Specialty grade distributors in the Netherlands are bypassing traditional merchant resin channels to offer certified-batch traceability for pharmaceutical customers.
Industry Challenges
- Multilayer lamination expertise scarcity:Converters lack process engineers capable of calibrating ultrasonic bonding parameters for recycled-content webs with variable melt-flow indices.
- ISO 16890 recertification timelines:Filter media producers must retest entire product portfolios against new fractional efficiency protocols before EN 779 grandfathering expires.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Melt-Blown Nonwovens Market |
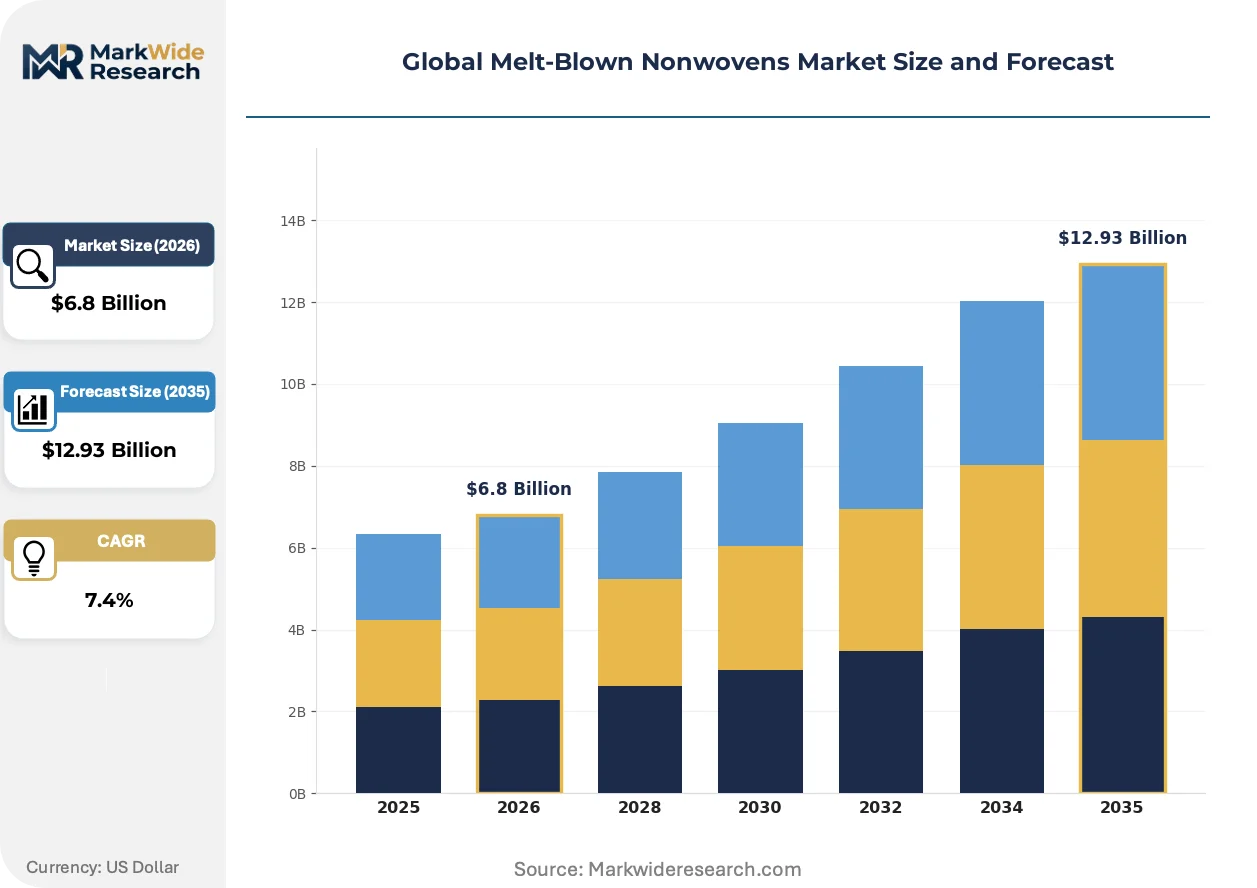
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.93 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Polyethylene, Polystyrene, Polyester, Polyamide, Polycarbonate End Use Industry: Personal Protection, Filtration Equipment, Medical Supplies, Hygiene Products, Automotive Components, Construction Materials Technology: Electrospinning, Spunbond, Thermal Bonding, Needle Punching, Hydroentanglement, Chemical Bonding Application: Face Masks, Air Filters, Oil Absorbents, Insulation, Water Filtration, Agricultural Covers |
| Companies Covered | Freudenberg Performance Materials, Kimberly-Clark Corporation, Berry Global Inc, Avgol Ltd, Toray Industries Inc, Fitesa, Mogul Nonwoven, PEGAS NONWOVENS, Japan Vilene Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Melt-Blown Nonwovens Market Shifts & Advancements
Electrostatic charging techniques and bio-based polymer alternatives are redefining performance benchmarks while regulatory test method harmonization is compressing product development cycles.
Bicomponent sheath-core filaments with differential shrinkage properties are enabling gradient density structures without mechanical layering. Automotive cabin air filter suppliers in Stuttgart and Detroit are qualifying these materials for combined particulate and molecular gas removal. The technology is hybridizing filtration and adsorption functions into single-substrate architectures that reduce module weight and assembly steps.
REACH substance restrictions on per- and polyfluoroalkyl substances are eliminating oil-repellent fluorochemical treatments from food-contact nonwovens. European converters are pivoting toward plasma-induced hydrophobic surface modification or bio-based wax coatings. Medical packaging applications face the steepest compliance timeline, with ECHA dossier submissions required before 2026 sunset dates.
Original equipment manufacturers are unbundling aftermarket filter replacement from capital equipment contracts, ceding installed-base revenue to independent service networks. North American industrial distributors are capturing this margin pool through private-label media sourcing and predictive maintenance software integration. The pattern is most pronounced in municipal water treatment, where municipal procurement offices prioritize unit cost over single-source loyalty.
Global Melt-Blown Nonwovens Market Segmentation
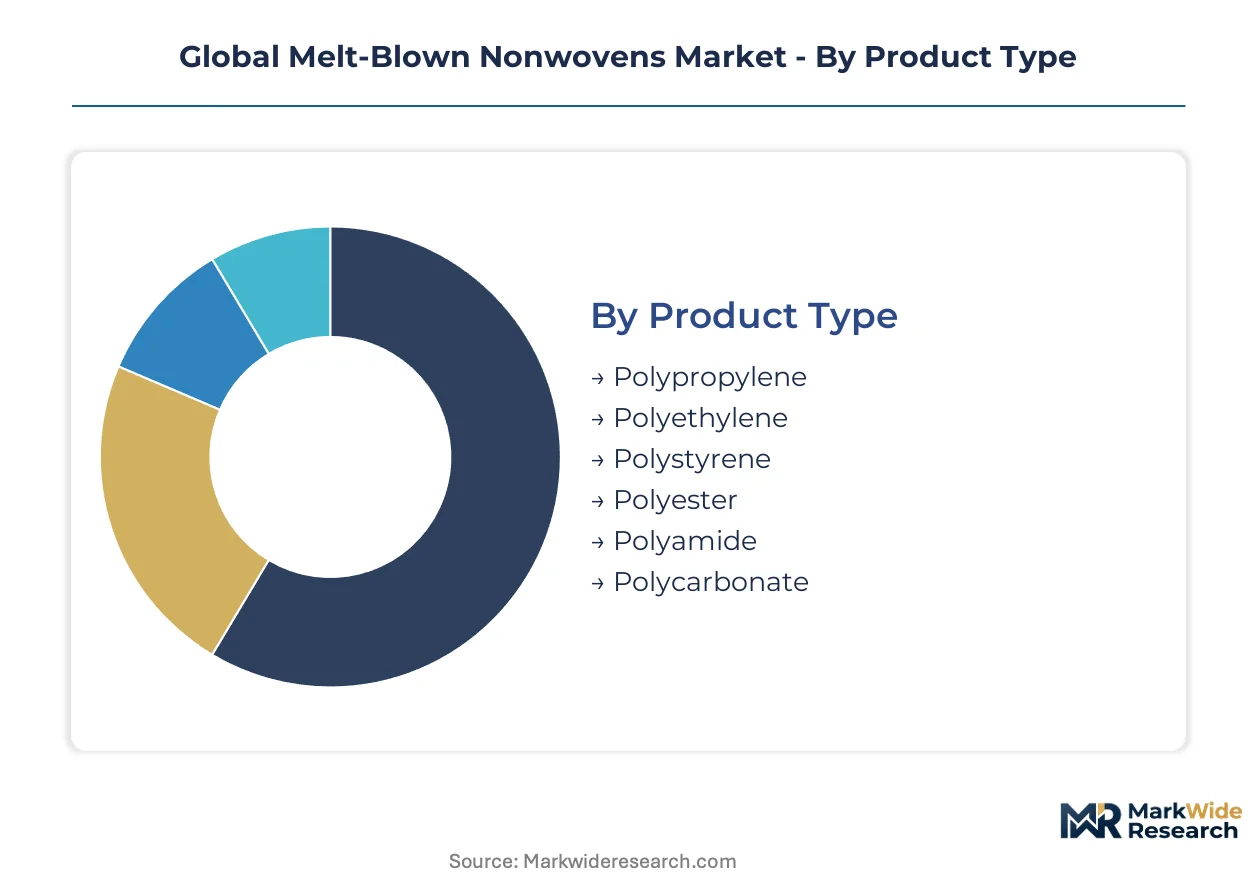
Melt-blown nonwovens serve divergent performance requirements across medical barrier, industrial filtration, and consumer hygiene applications. Segmentation reveals how polymer selection, bonding technology, and end-use specifications determine margin structures and aftermarket service intensity.
Product Type:
Aftermarket filter replacement cycles vary dramatically by polymer chemistry, with hydrophobic grades requiring more frequent technical service support than standard polypropylene.
- Polypropylene:Low melt viscosity enables fine fiber formation down to 0.5 microns with established spinneret infrastructure. German automotive cabin air filter manufacturers specify this grade for HEPA-equivalent particulate capture in Stuttgart supplier parks.
- Polyamide:Superior chemical resistance commands premium positioning in liquid filtration systems. Industrial water treatment facilities in the Netherlands specify polyamide webs for aggressive solvent exposure where thermal dimensional stability is mandatory.
- Polyethylene:Soft handfeel and lower processing temperatures suit single-use hygiene applications.
- Polystyrene:Rigid fiber structure supports acoustic insulation panels in construction.
- Polyester:Higher melting point enables thermal bonding compatibility with spunbond substrates.
- Polycarbonate:Optical clarity and impact resistance serve specialized medical device packaging.
Polypropylene holds the largest share; momentum sits with polyamide as chemical resistance specifications tighten.
End Use Industry:
Volume concentration and margin tiering diverge sharply between regulated medical applications and commodity hygiene markets.
- Filtration Equipment:HVAC retrofit mandates in Germany and the United States are pulling demand for sub-micron fiber grades certified to ISO 16890 protocols. Industrial air purification systems require HEPA-grade media with documented batch traceability.
- Medical Supplies:EU Green Deal circular economy requirements are redirecting R&D budgets toward post-consumer polypropylene purification for single-use surgical textiles. REACH substance restrictions on per- and polyfluoroalkyl substances eliminate oil-repellent fluorochemical treatments from food-contact nonwovens.
- Personal Protection:Face mask demand has normalized post-pandemic with procurement shifting to strategic stockpiling frameworks.
- Hygiene Products:High-volume converters prioritize unit cost over performance differentiation.
- Automotive Components:Cabin air filter specifications now combine particulate and molecular gas removal in single-substrate architectures.
- Construction Materials:Acoustic and thermal insulation applications favor bulk volume over fiber precision.
Filtration Equipment captures the steepest expansion trajectory; Medical Supplies retain the highest margin pool.
Technology:
Capital equipment depreciation schedules and energy intensity separate scalable commodity production from precision-caliber specialty output.
- Spunbond:High-throughput continuous filament production dominates SMS composite substrates for medical drapes and surgical gowns. Three integrated producers control roughly two-thirds of European supply, limiting bargaining leverage for standalone melt-blown specialists.
- Electrospinning:Produces nanofiber webs below 0.1 microns for battery separator membrane applications. Ceramic-coating of ultra-fine webs for lithium-ion cells is hybridizing previously distinct supply chains in Japan.
- Thermal Bonding:Solvent-free consolidation strengthens EPA-compliant alternatives to hazardous air pollutant-emitting processes.
- Hydroentanglement:Mechanical entanglement without chemical binders serves sustainable product positioning.
- Needle Punching:Structural integrity for geotextile and construction applications.
- Chemical Bonding:Declining share as REACH restrictions constrain solvent-based alternatives.
Spunbond maintains volume leadership; electrospinning is climbing the fastest on battery materials demand.
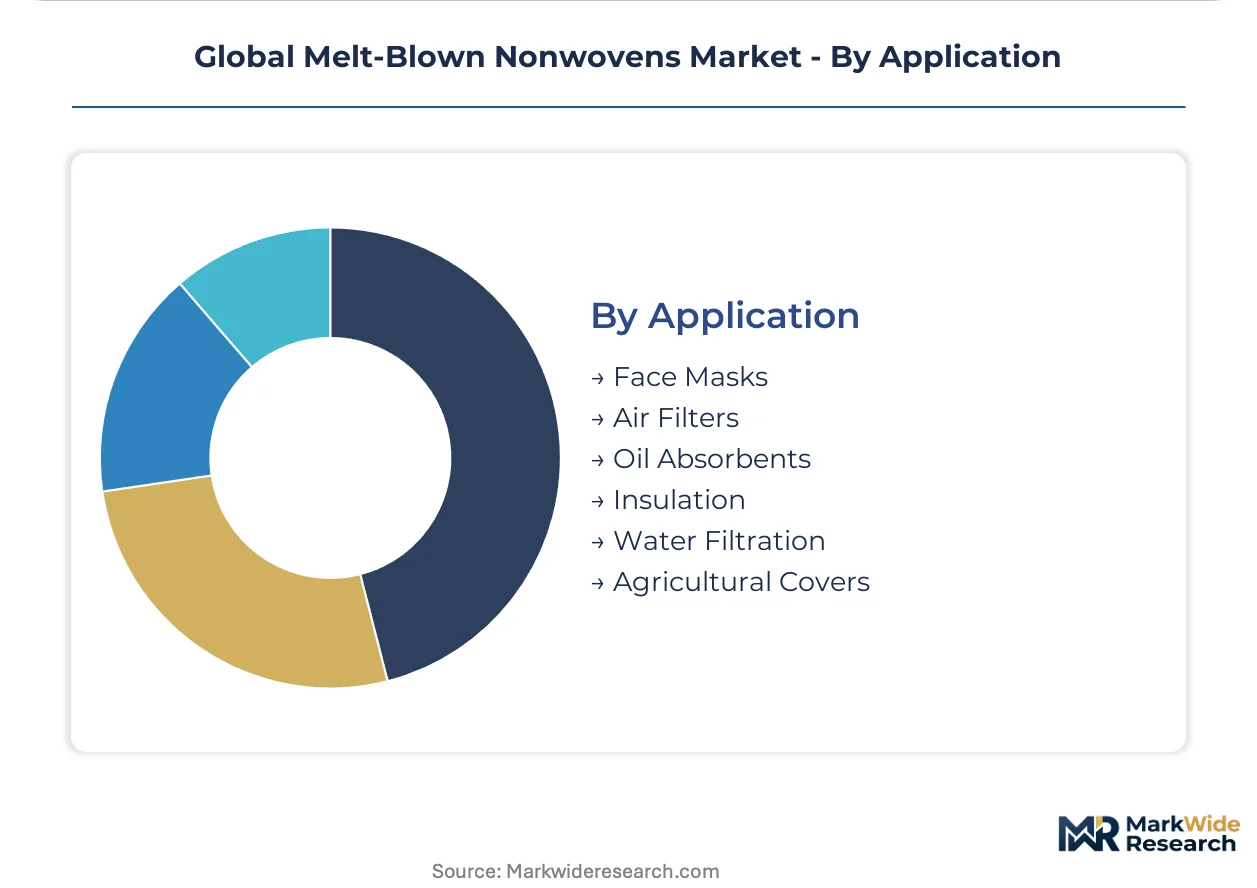
Application:
Regulatory certification requirements and replacement frequency determine aftermarket revenue capture for media producers.
- Air Filters:ISO 16890 test methods are displacing older EN 779 ratings, forcing media producers to recalibrate fiber diameter distributions. Semiconductor fabrication investments in Taiwan and South Korea specify ISO 14644-compliant media for airborne molecular contamination control.
- Face Masks:Bicomponent sheath-core filaments with differential shrinkage enable gradient density structures without mechanical layering. Stuttgart and Detroit automotive suppliers qualify these for combined particulate and gas removal.
- Water Filtration:Municipal procurement offices prioritize unit cost over single-source loyalty, fragmenting aftermarket revenue to independent distributors.
- Oil Absorbents:Industrial spill response applications favor bulk absorbency metrics.
- Insulation:Construction thermal and acoustic performance specifications.
- Agricultural Covers:Seasonal demand patterns with limited technical differentiation.
Air Filters command the largest installed base; Face Masks are gaining share fastest on bicomponent technology adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and Southeast Asia exhibit extreme price elasticity on commodity polypropylene grades, while German automotive and Taiwanese semiconductor purchasers absorb premiums for certified sub-micron fiber specifications. This demand-elasticity contrast shapes regional production strategies and margin capture potential.
Germany
Automotive cabin air filter manufacturers in Stuttgart supplier parks drive HEPA-equivalent particulate capture specifications. EU Green Deal circular economy requirements mandate recycled content thresholds for single-use medical textiles. The Baden-Württemberg automotive cluster sources specialized melt-blown grades locally from integrated media-to-module suppliers.
United States
EPA National Emission Standards for Hazardous Air Pollutants constrain solvent-based bonding alternatives, strengthening thermal and hydroentanglement process demand. Industrial facilities retrofit HVAC systems to meet stricter particulate capture standards. Midwest hygiene converters prioritize high-volume polypropylene capacity positioned near North American supply chains.
China
Dual carbon goals accelerate capital reallocation toward recycled-content extrusion lines and solvent-free bonding infrastructure. NMPA medical device regulations extend compliance timelines for raw material qualification protocols. Yangtze River Delta filtration equipment manufacturers scale production for domestic HVAC retrofit mandates.
Japan
METI industrial policy supports ceramic-coating of ultra-fine melt-blown webs for lithium-ion battery separator membrane applications. Semiconductor fabrication investments specify ISO 14644-compliant media for airborne molecular contamination control. Nagoya-based material suppliers hybridize previously distinct battery and filtration supply chains.
India
PLI scheme incentives for domestic nonwoven surgical gown production create first-mover advantages for extrusion equipment suppliers with local service presence. BIS standards compliance requirements extend product development cycles for imported media. Maharashtra medical textile clusters localize supply chains to capture government procurement preferences.
Global Melt-Blown Nonwovens Market Competitive Landscape
Capability concentration sits with integrated producers commanding spinneret infrastructure and certified cleanroom grades; scale advantage sits with high-volume polypropylene specialists positioned near hygiene converter clusters. Three integrated producers control roughly two-thirds of European SMS composite substrate supply. The competitive landscape segments into integrated media-to-module suppliers, high-volume commodity producers, and precision-caliber specialty fabricators. Dominant competitive moves include backward integration into polymer purification technologies and geographic expansion through local service presence in emerging medical textile markets.
Among integrated media-to-module suppliers, Freudenberg Performance Materials and Berry Global Inc represent archetypes of supply chain control strategies. Toray Industries Inc exemplifies the precision-caliber specialty tier anchoring Asian filtration demand with certified cleanroom applications. These three companies occupy positions across the capability-scale spectrum, with each representing distinct approaches to margin defense through either captive supply integration, regional volume positioning, or technical certification barriers.
| Leading Market Players |
|---|
| Freudenberg Performance Materials |
| Kimberly-Clark Corporation |
| Berry Global Inc |
| Avgol Ltd |
| Toray Industries Inc |
| Fitesa |
| Mogul Nonwoven |
| PEGAS NONWOVENS |
| Japan Vilene Company |
| Others |
Supply & Pricing Matrix
Propylene monomer price volatility transmitted from Middle East Gulf naphtha-cracker output determines both margin compression severity for converters and the geographic clustering of extrusion capacity near polymer purification hubs. This feedstock instability widens spreads between certified sub-micron grades and commodity polypropylene while forcing supply chain reconfiguration toward recycled-content feedstock security.
Pricing Analysis
Aftermarket filter replacement revenue drives lifetime value capture for media producers. Three-tier pricing structure across premium, standard, and economy levels separates ISO 14644-certified cleanroom grades from EN 779 legacy ratings and unbranded commodity rolls. Price differentiation rests on certification tier and batch traceability documentation. Cost compression in standard polypropylene intensifies because municipal procurement offices prioritize unit cost over single-source loyalty. Hygiene converters exhibit extreme price sensitivity; semiconductor fabricators in Taiwan absorb premiums for certified specifications.
Supply Chain Analysis
Freudenberg Performance Materials, Berry Global Inc, and Toray Industries Inc hold concentrated spinneret infrastructure and certified cleanroom capacity. Geographic supply concentrates in Germany, the United States, and Japan. Raw material dependencies draw from propylene monomer, post-consumer polypropylene feedstock, and ceramic coating precursors. Single-source vulnerability runs through Middle East Gulf naphtha-cracker output fluctuations. Distribution runs through integrated media-to-module suppliers, independent regional distributors, and direct-to-converter digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery separator membrane convergence hybridizes filtration and energy storage supply chains, creating platform economics where ceramic-coating expertise migrates across previously distinct end-use ecosystems.
For Market Incumbents: Harden installed-base loyalty through predictive maintenance software integration and captive polymer purification technologies. Defend margin pools from independent distributor encroachment by unbundling aftermarket filter replacement from capital equipment contracts. Deepen backward integration into post-consumer polypropylene feedstock security to meet EU Green Deal circular economy thresholds. For New Entrants and Emerging Players: India's Maharashtra medical textile clusters offer underpenetrated white-space for extrusion equipment suppliers with local service presence. Target PLI scheme procurement preferences by establishing BIS standards compliance capabilities. Penetrate through specialty grade digital platforms offering certified-batch traceability for pharmaceutical customers. For Investors and Strategic Acquirers: REACH substance restrictions on per- and polyfluoroalkyl substances reshape the acquisition landscape toward plasma-induced hydrophobic surface modification capabilities. Five-to-ten year viability favors precision-caliber specialty fabricators with ISO 16890 recertification completion. Target integrated producers commanding SMS composite substrate supply concentration. Monitor ECHA dossier submission timelines as inflection indicator for food-contact nonwoven compliance exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Purification | Captures EU Green Deal recycled content thresholds for medical textile certification. |
| Ceramic-Coating Capacity Expansion | Hybridizes filtration and battery separator supply chains for lithium-ion cell demand. |
| ISO 16890 Recertification Completion | Preserves EN 779 grandfathering expiration access for HEPA-grade HVAC retrofit mandates. |
| Direct-to-Converter Digital Platform Launch | Bypasses merchant resin channels with certified-batch traceability for pharmaceutical customers. |
| Local Service Presence in India | Captures PLI scheme surgical gown production incentives in Maharashtra clusters. |
Research Methodology
Cross-validation between primary interviews with extrusion equipment engineers, filtration media procurement managers, and polymer purification R&D directors and secondary validation through ECHA regulatory filings, EPA National Emission Standards documentation, and customs trade data anchors the qualitative findings. Bottom-up capacity assessments triangulate against top-down end-use demand modeling across medical barrier, industrial filtration, and consumer hygiene applications.
Calibration against historical polymer price volatility patterns and regulatory compliance timeline data shapes the analytical framework across the analysis window. Segmentation dimensions include polymer chemistry grade, end-use industry certification requirements, bonding technology energy intensity, and regional production hub regulatory cluster. CAGRs derive from fiber diameter distribution migration rates and HVAC retrofit mandate implementation curves.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by spunbond-integrated producers or accelerated REACH substance restriction timelines would shift outcomes. Quarterly review of propylene monomer futures curves and ECHA sunset date enforcement patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nonwoven Materials
Nonwoven Blanket Market
Nonwoven Materials
HDPE Nonwoven Market
Nonwoven Materials
Global Polypropylene (PP) Nonwoven Fabrics Market
Nonwoven Materials
Nonwoven Flanging Market
Nonwoven Materials
Nonwoven Geotextiles Market
Nonwoven Materials
Nonwoven Dust Cover Market
Nonwoven Materials
Hygienic Non-Woven Fabrics Market
Nonwoven Materials
PP Nonwovens Market
Nonwoven Materials
Nonwoven Decking Market
Nonwoven Materials
Nonwoven Fabric Production Line Market
Nonwoven Materials
Nonwoven Industrial Membrane Market
Nonwoven Materials
India Non-Woven Geotextiles Market
Nonwoven Materials
Global Automotive Nonwoven Fabrics Market
Nonwoven Materials
Global Wet Laid Nonwovens Market
Nonwoven Materials
Airlaid Textile Market
Nonwoven Materials
Polywoven Bags Market