
 Asia-Pacific Non-Woven Fabric Market | 2026-2036
Asia-Pacific Non-Woven Fabric Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Non-Woven Fabric Market Outlook
Technical service contracts for meltblown filtration calibration are pivoting how suppliers monetize output beyond commodity roll sales. TORAY INDUSTRIES, INC. leverages its polymer science heritage to anchor premium medical-grade supply chains across Japan and Southeast Asia. Berry Global Inc. competes through backward integration into resin compounding, sustaining margin control across multiple Asian production nodes.
Non-woven fabric comprises engineered sheet structures bonded by mechanical, thermal, or chemical means without weaving, typically ranging from 10 to 250 grams per square meter in basis weight, serving barrier, filtration, absorption, and reinforcement functions across industrial and consumer applications. Spunbond dominates volume throughput due to its speed and polypropylene cost structure, while meltblown commands premium positioning in medical and HEPA filtration segments where micron-scale fiber diameters determine performance. Airlaid occupies a narrower but defensible niche in absorbent hygiene cores where cellulose-polymer blends optimize fluid management.
China's SAMR enforces GB standards for disposable medical non-wovens, compelling domestic upgrades in bioburden control and tensile consistency. India's BIS certification requirements for geotextiles in national highway projects are redirecting technical textile investment toward infrastructure-grade needlepunched lines. Japan's METI circular economy guidelines for plastic-containing non-wovens are pressuring producers to validate recycled feedstock pathways. Stakeholders must weigh regulatory compliance costs against the pricing power that certified grades command in procurement tenders.
Market Dynamics
China's GB standards for medical non-wovens are compressing supply-side capacity while India's PLI scheme for technical textiles pulls investment toward infrastructure-grade needlepunched lines, creating divergent capability requirements across the region.
Growth Catalysts
- Medical-grade filtration mandates:China's SAMR enforces bioburden control standards for disposable surgical gowns, compelling domestic producers to upgrade meltblown calibration systems.
- India's PLI scheme:The technical textiles incentive redirects capital toward geotextile production for national highway projects, expanding needlepunched capacity in Gujarat and Tamil Nadu.
- Yangtze River Delta clustering:Spunbond capacity concentrates near downstream converters in Jiangsu and Zhejiang provinces, reducing logistics friction for hygiene and packaging applications.
Market Restraints
- Polypropylene feedstock volatility:Propylene price swings compress margins for spunbond producers dependent on naphtha-derived resin supply.
- Single-country meltblown concentration:Technical-grade filtration capacity clusters disproportionately in eastern China, exposing buyers to geographic supply risk.
- Cellulose substitution in absorbent cores:Airlaid non-wovens face displacement from superabsorbent polymer sheet alternatives in premium diaper segments.
Strategic Opportunities
- Vietnam's underpenetrated medical supply base:Hospital network expansion in Ho Chi Minh City and Hanoi creates demand for imported surgical drape materials.
- Recycled feedstock pathways:Japan's METI circular economy guidelines validate post-consumer polypropylene recovery for non-woven production.
- Technical service contracting:Meltblown filtration calibration contracts displace commodity roll sales, anchoring supplier-buyer relationships through performance guarantees.
Industry Challenges
- Polymer science talent scarcity:Formulation chemists with micron-scale fiber diameter expertise command premium compensation across Southeast Asian production nodes.
- Multi-standard certification timelines:Simultaneous compliance with China's GB standards, India's BIS requirements, and Japan's JIS specifications extends product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Non-Woven Fabric Market |
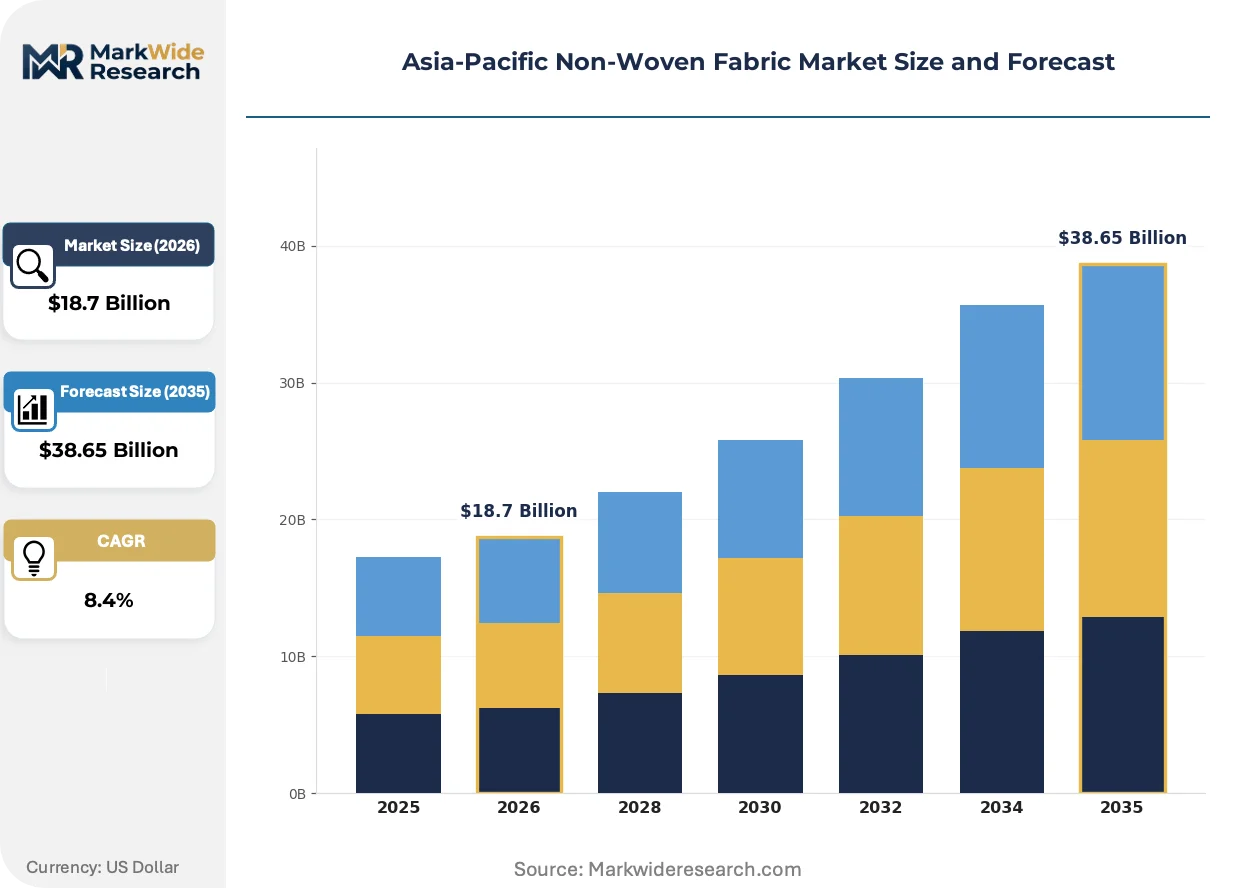
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spunbond, Meltblown, Needlepunched, Airlaid End User: Medical, Hygiene, Automotive, Construction Material: Polypropylene, Polyester, Cellulose, Viscose Application: Wipes, Filters, Geotextiles, Packaging |
| Companies Covered | Berry Global Inc., Autotech Nonwovens Pvt Ltd., TORAY INDUSTRIES, INC., Foshan Nanhai Beautiful Nonwoven Co., Ltd., Zhejiang Kingsafe Group Co., Ltd., Asahi Kasei, Ahlstrom, Oceancash, DuPont, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Non-Woven Fabric Market Strategic Shifts
Automation of quality assurance and the convergence of regulatory frameworks are compressing product development cycles while elevating performance thresholds for medical and filtration grades across Asia-Pacific production networks.
Smart inline inspection systems using machine vision are automating defect detection in spunbond lines, reducing manual sampling requirements. Medical textile converters in Japan and South Korea are adopting these systems fastest, compressing batch release timelines from days to hours. The technology is automating quality assurance labor out of high-throughput hygiene material production.
China's SAMR is tightening bioburden limits for disposable medical non-wovens under revised GB standards. Domestic producers must validate sterilization assurance levels through third-party testing, raising compliance costs. Surgical drape and gown manufacturers in Jiangsu and Zhejiang provinces are consolidating supplier lists to certified tier-1 meltblown sources.
Hospital procurement departments are consolidating vendor relationships around technical service capabilities rather than unit pricing. Large healthcare networks in Australia and Thailand now require filtration performance guarantees backed by calibration contracts. This pattern concentrates purchasing power among suppliers with in-house polymer science laboratories and regional technical service presence.
Asia-Pacific Non-Woven Fabric Market Segmentation
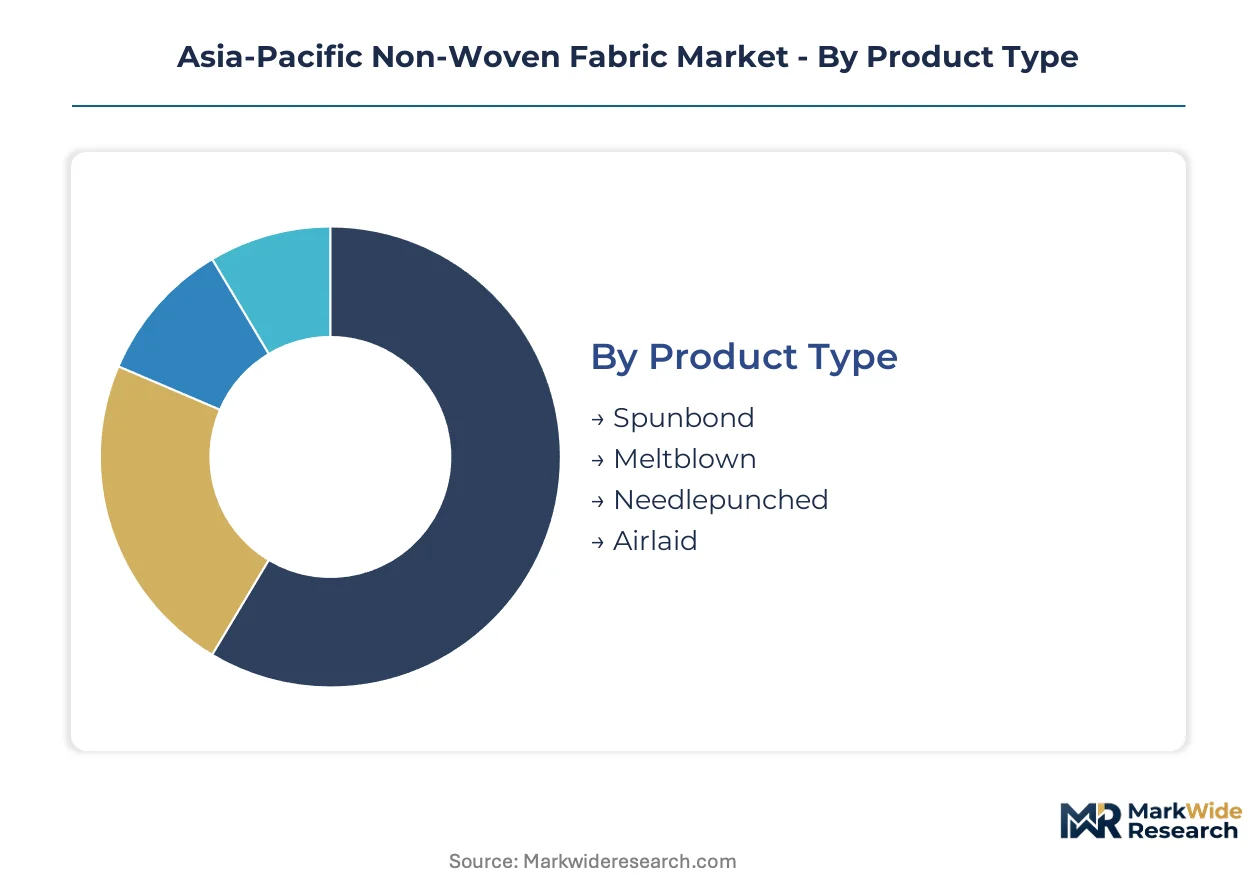
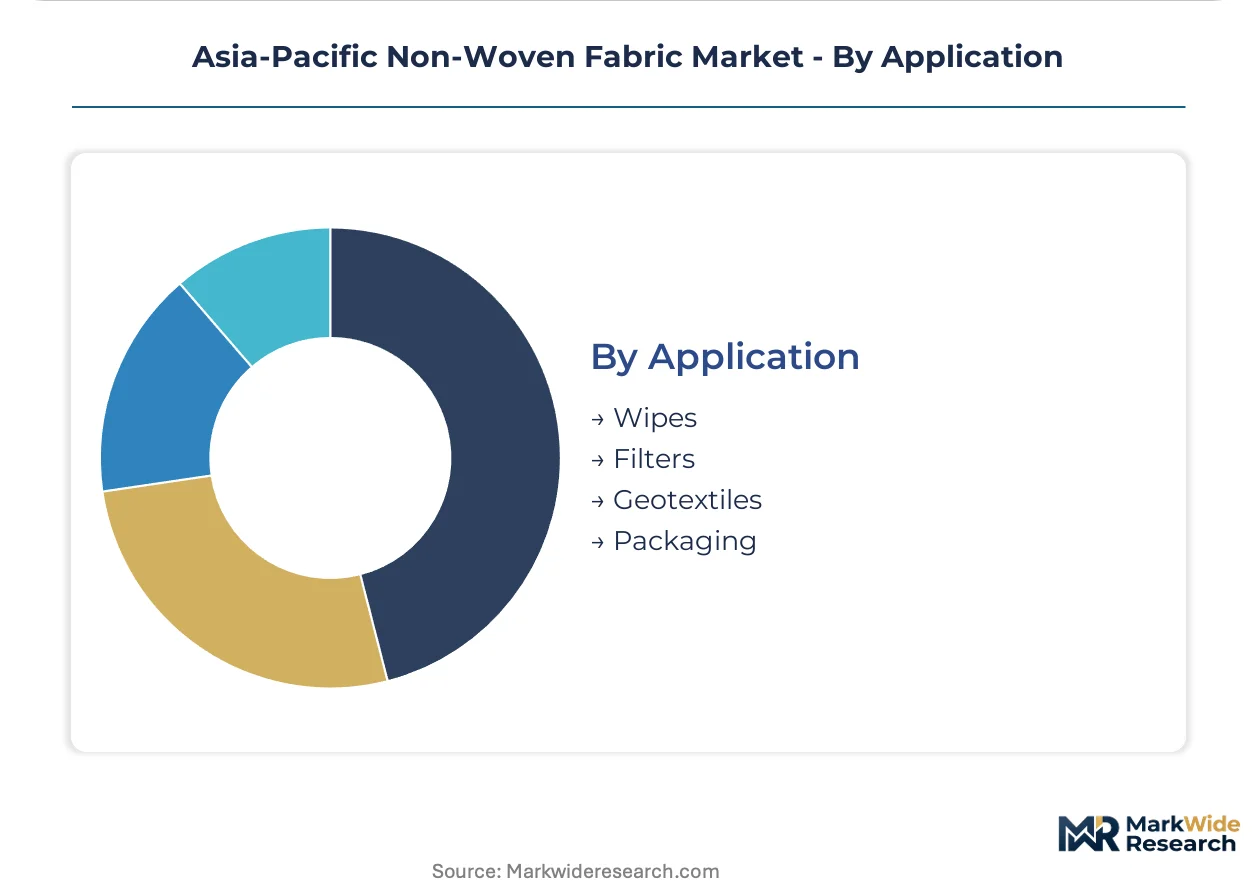
Segmentation in the Asia-Pacific non-woven fabric market reveals how production technology, regulatory requirements, and end-use specifications create distinct competitive arenas with divergent margin profiles and capability barriers.
Product Type:
Buyers select product types based on throughput speed versus filtration precision trade-offs, with polypropylene cost structures dominating volume decisions.
- Spunbond:Continuous filaments of polypropylene are thermally bonded into high-strength sheets, typically 10-150 gsm. Demand concentrates in China's Yangtze River Delta hygiene and packaging converters, where logistics proximity to Jiangsu and Zhejiang production clusters reduces freight costs.
- Meltblown:Micron-scale fibers (0.5-10 micrometers) create high-surface-area media for medical and HEPA filtration. Hospital procurement networks across Japan and Thailand now require technical service contracts with calibration guarantees, displacing commodity purchasing.
- Needlepunched:Mechanical interlocking of staple fibers produces durable geotextile-grade materials for infrastructure applications.
- Airlaid:Cellulose-polymer blends optimize fluid management in absorbent hygiene cores, facing substitution pressure from superabsorbent polymer sheet alternatives.
Spunbond leads on scale; meltblown leads on momentum.
End User:
Regulatory intensity varies sharply across end users, with medical and hygiene applications facing bioburden standards that automotive and construction segments escape.
- Medical:Surgical gowns, drapes, and sterilization wraps must meet China's SAMR GB standards for bioburden control and tensile consistency. Jiangsu and Zhejiang province manufacturers are consolidating supplier lists to certified tier-1 meltblown sources to comply with third-party sterilization validation requirements.
- Hygiene:Diaper and feminine care products drive spunbond and airlaid consumption across Southeast Asian manufacturing hubs. Indonesia and Vietnam hygiene converters are expanding capacity fastest, pulling in polypropylene supply from Singapore resin compounders.
- Automotive:Interior trim, insulation, and filtration applications favor needlepunched and spunbond materials with acoustic and thermal performance specifications.
- Construction:Geotextiles for soil stabilization and drainage command infrastructure-grade needlepunched output, particularly under India's BIS certification requirements for national highway projects.
Hygiene dominates volume throughput; medical commands the steepest expansion trajectory.
Material:
Feedstock selection locks producers into specific resin supply chains and recycling pathways, with polypropylene's cost advantage offset by circular economy pressures in Japan.
- Polypropylene:Dominates spunbond and meltblown production due to naphtha-derived cost structures and melt-flow characteristics suited to high-speed lines. Propylene price volatility remains the primary margin risk for producers dependent on Asian naphtha crackers.
- Polyester:PET staple fibers serve durable applications requiring dimensional stability and UV resistance, particularly in Australian geotextile specifications.
- Cellulose:Renewable feedstock for airlaid absorbent cores, constrained by pulp supply concentration in Indonesian and Malaysian fiber operations.
- Viscose:Regenerated cellulose offers premium softness in medical and hygiene wipes, with supply concentrated in Indian and Chinese dissolving pulp converters.
Polypropylene anchors volume; viscose is gaining share fastest in premium wipe segments.
Application:
Application selection determines the regulatory compliance burden and technical service intensity required to maintain supplier relationships.
- Wipes:Industrial, household, and personal care wipes consume spunlace and airlaid materials, with Vietnam and Philippines converters expanding wet-wipe production for ASEAN export markets.
- Filters:HVAC, automotive, and liquid filtration applications demand meltblown precision with micron-scale fiber diameter control. Australia's hospital networks now require filtration performance guarantees backed by calibration contracts rather than unit pricing.
- Geotextiles:Road construction, erosion control, and drainage systems utilize needlepunched polyester and polypropylene, with India's PLI scheme for technical textiles redirecting capital toward Gujarat and Tamil Nadu production lines.
- Packaging:Reusable shopping bags and protective wrapping employ spunbond polypropylene, competing against woven alternatives on cost and printability.
Filters lead on technical service revenue; geotextiles are climbing the fastest on infrastructure spending.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands meltblown filtration capacity while India redirects capital toward geotextile infrastructure, creating divergent capability requirements across Asia-Pacific production networks.
China
Medical-grade surgical gown demand from Jiangsu and Zhejiang hospital networks drives meltblown consumption. SAMR enforces revised GB standards for bioburden control, compelling sterilization validation through third-party testing. The Yangtze River Delta concentrates spunbond capacity near downstream hygiene converters in Suzhou and Ningbo.
India
National highway expansion pulls needlepunched geotextile demand into Gujarat and Tamil Nadu manufacturing corridors. BIS certification requirements for infrastructure-grade materials redirect technical textile investment under the PLI scheme. Ahmedabad and Coimbatore clusters are adding needlepunched lines to serve road construction tenders.
Japan
Hospital procurement networks in Tokyo and Osaka require filtration performance guarantees backed by technical service contracts. METI circular economy guidelines pressure producers to validate post-consumer polypropylene recovery pathways. Chubu region manufacturers are piloting recycled feedstock non-woven lines.
Vietnam
Hospital network expansion in Ho Chi Minh City and Hanoi creates demand for imported surgical drape materials. The country's national pharmaceutical regulator enforces medical device registration timelines that favor established suppliers. Dong Nai province converters are expanding wet-wipe production for ASEAN export markets.
Australia
Healthcare procurement consolidation around technical service capabilities elevates supplier selection criteria beyond unit pricing. TGA medical device standards align with filtration performance verification requirements. Melbourne and Sydney hospital networks now mandate calibration-backed supply contracts for surgical materials.
Asia-Pacific Non-Woven Fabric Market Competitive Environment
Top-tier vendors anchor premium medical-grade supply chains, while mid-scale regional fabricators compete on logistics proximity to hygiene converters. The market structure stratifies across polymer science capability, with backward integration into resin compounding separating margin-sustainable players from commodity roll suppliers. Two strategic archetypes dominate: diversified materials conglomerates with regional technical service presence, and specialized non-woven converters with captive meltblown calibration expertise. Competitive moves concentrate on capacity expansion in Vietnam and Indonesia, plus technical service contracting to displace commodity pricing relationships.
Within the diversified materials tier, Berry Global Inc. and TORAY INDUSTRIES, INC. exemplify contrasting geographic anchoring strategies. Berry Global Inc. represents North American-origin conglomerate positioning with Asian production node distribution. TORAY INDUSTRIES, INC. occupies a Japanese heritage position emphasizing polymer science laboratory capabilities. Among regional specialists, Foshan Nanhai Beautiful Nonwoven Co., Ltd. and Zhejiang Kingsafe Group Co., Ltd. sit within Chinese domestic supply chain configurations serving Yangtze River Delta converter demand.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Autotech Nonwovens Pvt Ltd. |
| TORAY INDUSTRIES, INC. |
| Foshan Nanhai Beautiful Nonwoven Co., Ltd. |
| Zhejiang Kingsafe Group Co., Ltd. |
| Asahi Kasei |
| Ahlstrom |
| Oceancash |
| DuPont |
| Others |
Value Chain & Pricing Dynamics
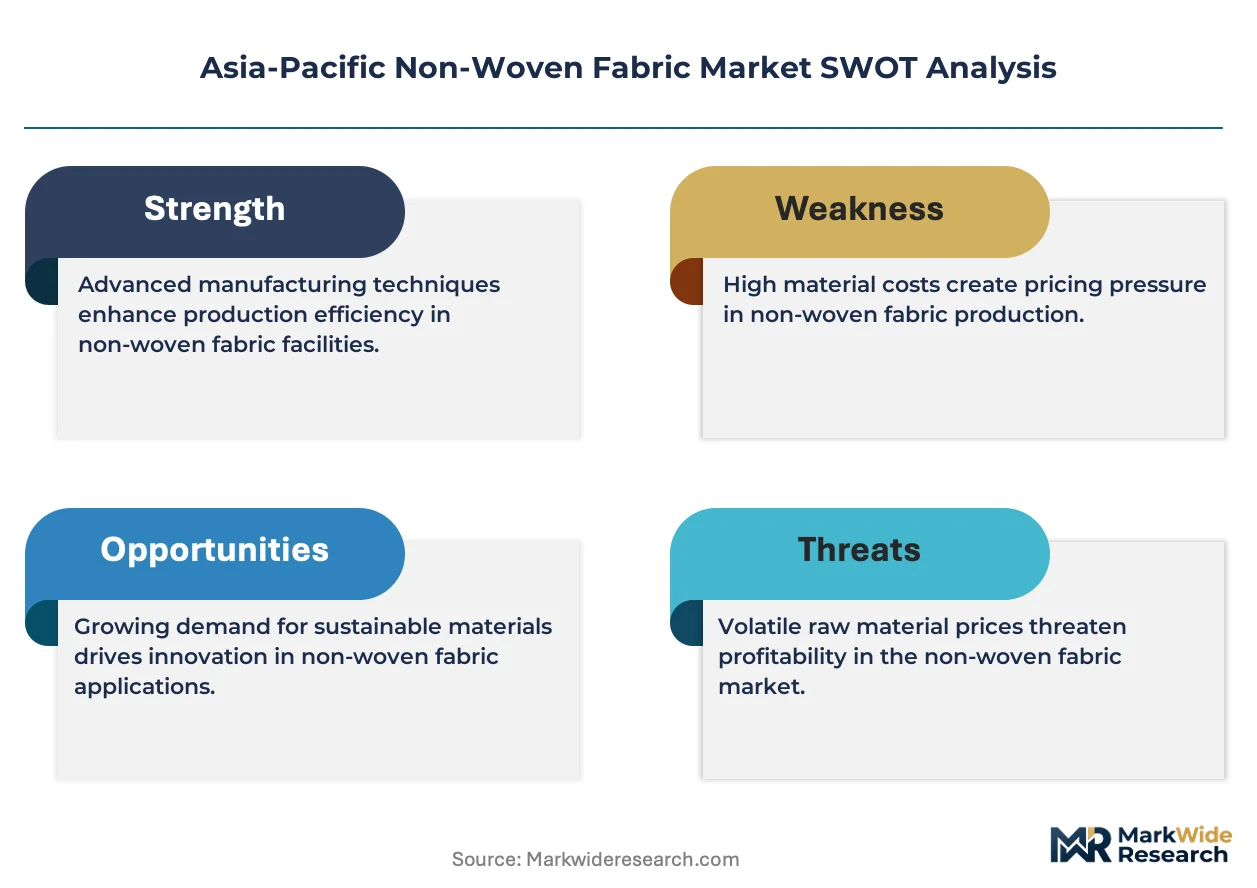
Polypropylene resin feedstock from Asian naphtha crackers flows through three distinct pricing tiers downstream, with meltblown calibration premiums separating certified medical-grade supply from commodity spunbond rolls in hospital procurement tenders.
Pricing Analysis
Capacity additions in Vietnam and Indonesia are reshaping price floors for standard-grade spunbond, compressing margins for producers without backward integration into resin compounding. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and technical service bundling, with China's SAMR-compliant meltblown commanding the widest spreads. Pricing pressure stems from propylene feedstock volatility and cellulose substitution in absorbent cores. Hygiene converters in Southeast Asia exhibit highest price sensitivity, while Australian hospital networks prioritize filtration guarantees over unit cost.
Supply Chain Analysis
Post-consumer polypropylene recovery pathways in Japan's Chubu region are piloting closed-loop feedstock flows, though scale remains insufficient for commercial non-woven production. Manufacturing concentrates in China, India, and Vietnam, with meltblown filtration capacity clustering disproportionately in Jiangsu and Zhejiang provinces. Raw material dependencies center on naphtha-derived propylene, dissolving pulp for viscose, and superabsorbent polymer alternatives threatening airlaid demand. Single-country concentration in eastern China exposes buyers to geographic supply risk. Distribution runs through converter-proximate logistics nodes in the Yangtze River Delta and Gujarat manufacturing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market hinges on technical service contracting displacing commodity roll sales, with calibration-backed performance guarantees capturing pricing power from cost-sensitive hygiene segments.
For Market Incumbents: Acquire meltblown calibration laboratories and regional technical service teams to anchor hospital procurement relationships against emerging Vietnamese converters. Consolidate supplier lists among Jiangsu and Zhejiang surgical drape manufacturers by embedding sterilization validation capabilities. Backward integration into resin compounding defends margin control against propylene price volatility from Asian naphtha crackers. For New Entrants and Emerging Players: Smart inline inspection systems using machine vision offer a technology-first wedge to compress batch release timelines for Japanese and South Korean medical textile converters. Target Vietnam's underpenetrated hospital network expansion in Ho Chi Minh City and Hanoi with imported surgical drape materials, leveraging Dong Nai province wet-wipe production clusters for ASEAN export market access. Lead with technical service capabilities rather than unit pricing to differentiate from established Yangtze River Delta suppliers. For Investors and Strategic Acquirers: Consolidation pressure builds where polymer science talent scarcity intersects with multi-standard certification timelines extending product launch cycles. Mid-scale regional fabricators with captive meltblown expertise and logistics proximity to hygiene converters represent viable acquisition targets over a long-term viability window. Monitor Japan's METI circular economy guideline enforcement as an inflection indicator for recycled feedstock pathway validation requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Technical Service Contracting | Meltblown calibration guarantees displace commodity pricing in Australian and Thai hospital procurement. |
| Backward Integration | Resin compounding capabilities insulate margins from naphtha-derived propylene volatility. |
| Capacity Expansion | Needlepunched lines in Gujarat and Tamil Nadu serve India's PLI-scheme highway infrastructure tenders. |
| Recycled Feedstock Validation | Post-consumer polypropylene recovery pathways align with Japan's METI circular economy guidelines. |
| Smart Quality Assurance | Machine vision inspection systems automate defect detection in high-throughput spunbond lines. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with polymer formulation chemists, hospital procurement managers, technical textile plant operators, and resin compounding specialists with secondary validation from customs trade data, GB standard enforcement disclosures, PLI scheme implementation reports, and SEC filings of diversified materials conglomerates. Bottom-up capacity assessments across China's Yangtze River Delta and India's Gujarat corridor were triangulated against top-down demand modeling from hygiene converter expansion plans.
Segment-weighting approaches distributed value and volume across product type, end user, material, and application dimensions throughout the forecast period. CAGRs were derived from elasticity-adjusted demand projections incorporating propylene price correlation coefficients and hospital network expansion rates. Industry-specific inputs included meltblown filtration performance tier migration, cellulose substitution elasticities in absorbent cores, and technical textile incentive scheme uptake trajectories.
The model holds under stable polypropylene feedstock pricing and sustained GB standard enforcement; deviation in propylene volatility spikes or regulatory relaxation would shift capacity investment timing. Practitioners should monitor China's SAMR bioburden limit revisions and India's BIS certification timeline extensions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nonwoven Materials
Absorbable Nonwoven Textiles Market
Nonwoven Materials
Staples PP Nonwovens Market
Nonwoven Materials
Nonwoven Furniture Construction Sheeting Market
Nonwoven Materials
Polywoven Bags Market
Nonwoven Materials
PET Spunbond Nonwoven Market
Nonwoven Materials
Nonwoven Blanket Market
Nonwoven Materials
Nonwoven Flanging Market
Nonwoven Materials
PP Nonwovens Market
Nonwoven Materials
Airlaid Textile Market
Nonwoven Materials
Global Spunbond Nonwovens Market
Nonwoven Materials
Nonwoven Sponges Market
Nonwoven Materials
Non Woven Converting Machine Market
Nonwoven Materials
Meltblown Fabrics Market
Nonwoven Materials
Global Wet Laid Nonwovens Market
Nonwoven Materials
Nonwoven Industrial Membrane Market
Nonwoven Materials
Global Non Woven Fabric Market