
 India Non-Woven Geotextiles Market | 2026-2036
India Non-Woven Geotextiles Market Size, Share, and Industry Trends Forecast 2026-2036
India Non-Woven Geotextiles Market Insights
Gujarat's petrochemical feedstock base is narrowing the raw-material cost gap for domestic non-woven geotextile output. Techfab India Industries Ltd. leverages its Surat manufacturing complex to serve western India road contracts. Garware Wall Ropes Ltd. anchors coastal supply chains for river bank protection schemes. Maccaferri Environmental Solutions Pvt. Ltd. specializes in erosion-control system integration, bundling geotextiles with gabion structures.
Non-woven geotextiles are permeable synthetic fabrics manufactured through needle-punching, thermal bonding, or meltblowing of polypropylene or polyester fibers, typically specified by mass per unit area ranging from 100 to 1200 gsm and engineered for separation, filtration, drainage, or reinforcement in civil earthworks. Needle-punched grades dominate volume shipments for road construction subgrade stabilization where puncture resistance governs specification. Spunbonded variants command margin premiums in rail infrastructure ballast separation layers due to uniform pore-size distribution and tensile consistency.
BIS geosynthetic standards, CEA dam safety guidelines, and MoRTH highway specifications collectively mandate certified material deployment for public infrastructure tenders, embedding compliance costs into contractor procurement workflows. The PLI scheme for technical textiles extends production-linked incentives to domestic non-woven geotextile capacity. Stakeholders must monitor alignment between state-level infrastructure auction pipelines and certified supplier base expansion to capture contract eligibility.
Market Dynamics
The India non-woven geotextiles market pivots on BIS certification mandates that embed compliance costs into public infrastructure procurement workflows, creating a bifurcation between certified domestic suppliers and import-dependent contractors.
Growth Catalysts
- MoRTH Highway Specifications:National highway expansion programs mandate geotextile deployment in subgrade stabilization, pulling certified material through state PWD tender pipelines.
- CEA Dam Safety Guidelines:Reservoir rehabilitation projects require filtration-grade non-wovens for embankment protection, opening utility-scale demand channels.
- Polypropylene Feedstock Proximity:Gujarat's petrochemical corridor supplies virgin PP granules at landed-cost parity, compressing raw material logistics for western India manufacturers.
Market Restraints
- Crude-Linked Input Volatility:Polypropylene resin prices track naphtha cracking margins, exposing converters to margin squeeze when oil benchmarks spike.
- Single-Source Needle-Punch Equipment:High-loft carding and needle-punch lines concentrate among European and Chinese machinery suppliers, creating capex delivery bottlenecks.
- Woven Geotextile Substitution:High-strength woven PP tapes retain cost advantage in reinforced soil wall applications, capping non-woven penetration in structural geotechnical works.
Strategic Opportunities
- PLI Scheme for Technical Textiles:Production-linked incentives cover non-woven geotextile capacity expansion, reimbursing eligible capital expenditure for domestic lines.
- Railway Ballast Separation:Dedicated freight corridors and track doubling projects specify spunbonded non-wovens for fouling prevention, a specification tier with margin premiums.
- E-Commerce Material Procurement:Infrastructure contractors pilot platform-based geosynthetic sourcing for standardized grades, disintermediating traditional distributor networks.
Industry Challenges
- BIS Certification Timelines:Laboratory testing and factory audit queues for IS 16391 compliance extend supplier qualification cycles, delaying contract eligibility.
- Geotechnical Engineer Scarcity:Design firms face shortages of specialists fluent in ISO 10319 tensile testing protocols and site-specific specification writing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Non-Woven Geotextiles Market |
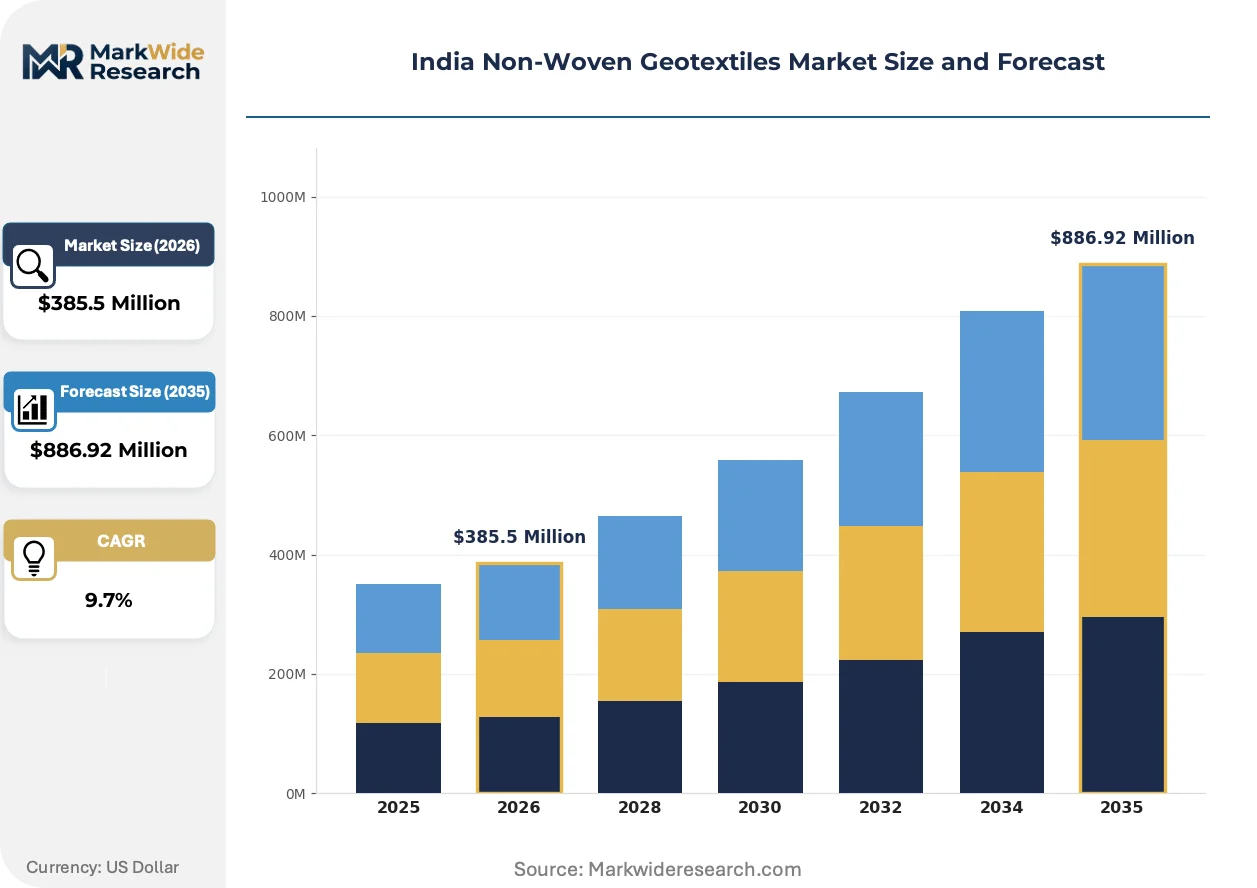
| Market Size in 2026 | $385.5 Million |
| Market Size in 2035 | $886.92 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Needle-Punched, Spunbonded, Heat-Bonded, Meltblown Application: Road Construction, Rail Infrastructure, Erosion Control, Landfills, River Bank Protection End User: Infrastructure Developers, Waste Management Companies, Construction Contractors, Environmental Agencies Distribution Channel: Wholesale Suppliers, Retail Outlets, Direct Sales, Online Marketplaces |
| Companies Covered | OCEAN GLOBAL, Garware Wall Ropes Ltd., Techfab India Industries Ltd., Terram Geosynthetics Pvt. Ltd., Maccaferri Environmental Solutions Pvt. Ltd., SKAPS Industries, Suntech Geotextile Pvt. Ltd., Jeevan Nonwoven, Gayatri Polymers & Geosynthetics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Non-Woven Geotextiles Market Trends and Innovations
Material science advances and procurement digitization are compressing specification cycles while elevating performance benchmarks across Indian civil earthworks.
Recycled polypropylene fiber feedstock is migrating from pilot-scale trials to commercial needle-punched production for non-structural separation layers. State road corporations in Maharashtra and Karnataka specify recycled-content geotextiles for rural connectivity projects with lower load-bearing requirements. This migration from virgin to post-industrial feedstock is compressing material cost curves while forcing equipment retrofits for fiber length consistency.
BIS IS 16391:2015 geosynthetic standards now incorporate UV resistance testing protocols that disqualify non-stabilized polypropylene grades from permanent works. The regulation forces converters to masterbatch antioxidant loading adjustments, raising technical barriers to tender participation. Road contractors in the Delhi-Mumbai Industrial Corridor corridor now pre-qualify suppliers based on certified UV degradation test reports, shifting procurement weight toward integrated manufacturers with in-house laboratory capabilities.
Buyers now unbundle geotextile supply from installation supervision, separating material procurement from civil works contracting. Large infrastructure developers maintain approved vendor lists for direct material purchase while engaging separate EPC firms for placement. This pattern concentrates most visibly in Gujarat and Tamil Nadu state highway projects, where developer entities source certified geotextiles independently of construction subcontractors to enforce specification compliance.
India Non-Woven Geotextiles Market Segmentation
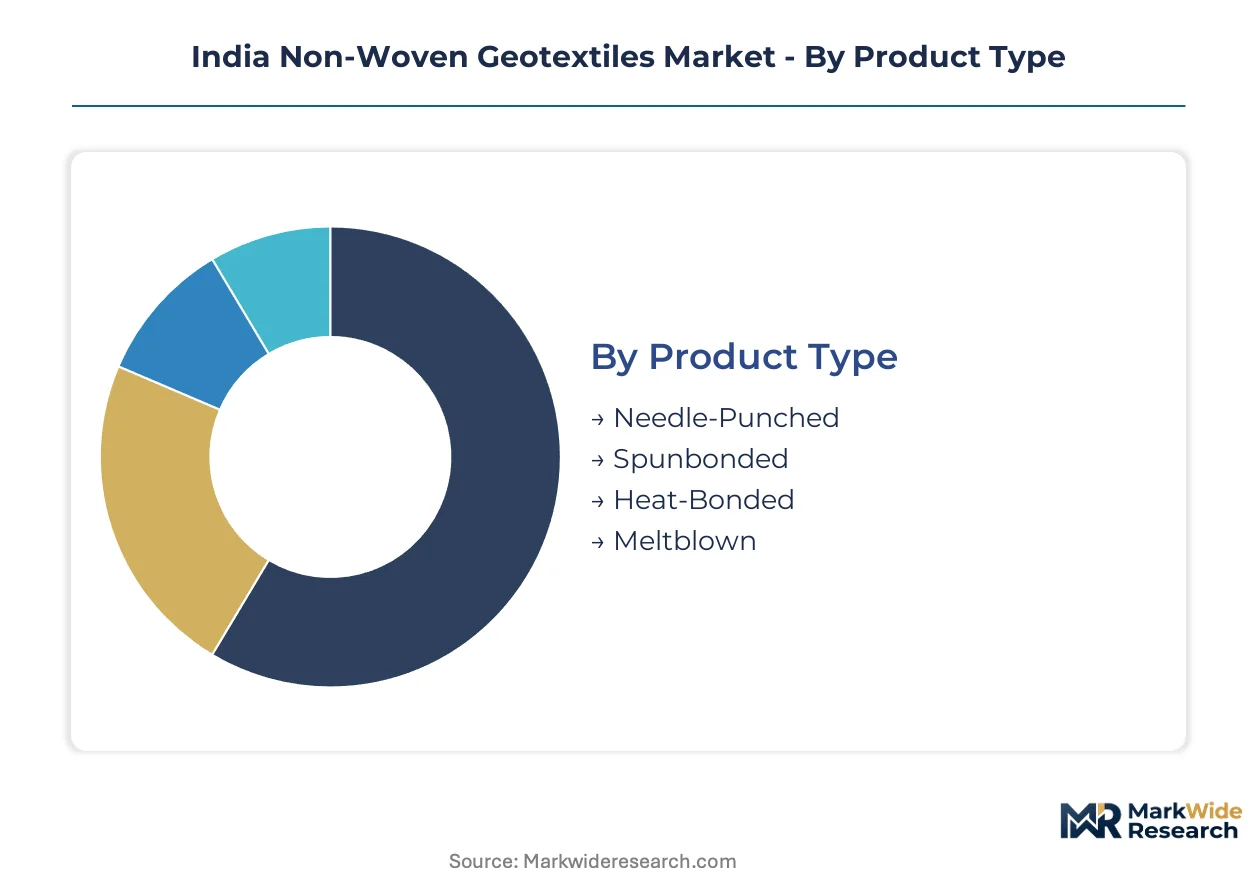
Non-woven geotextile procurement in India fragments across manufacturing technology, civil application, and channel structure. Each dimension carries distinct margin profiles and compliance requirements that shape supplier positioning.
Product Type:
Cost tier differentiation separates commodity-grade separation fabrics from performance-specified reinforcement materials.
- Needle-Punched:Fiber entanglement through barbed needles produces high-loft, puncture-resistant fabrics typically specified at 200-600 gsm for road subgrade stabilization. Maharashtra state highway contracts absorb the majority of domestic needle-punched volume, with BIS IS 16391 certification mandatory for tender eligibility.
- Spunbonded:Continuous filament extrusion and thermal bonding yield uniform pore-size distribution with tensile consistency critical for rail ballast separation. Dedicated freight corridor projects specify spunbonded grades for fouling prevention, commanding margin premiums over needle-punched alternatives.
- Heat-Bonded:Calendered thermal bonding creates stiff, dimensionally stable sheets preferred for landfill liner protection where puncture resistance is secondary to chemical compatibility.
- Meltblown:Microfiber webs from extrusion attenuation deliver fine filtration for drainage applications in dam rehabilitation works under CEA guidelines.
Needle-punched holds installed capacity. Spunbonded is rotating up the share rankings.
Application:
Geography of infrastructure investment concentrates demand around specific civil works categories.
- Road Construction:Subgrade separation and stabilization across national highway expansion and rural connectivity schemes. Gujarat and Maharashtra state PWDs specify certified non-wovens for flexible pavement layers, with MoRTH mandates embedding material into contractor workflows.
- Rail Infrastructure:Ballast separation and trackbed filtration for dedicated freight corridors and track doubling. Spunbonded specifications dominate this tier due to ISO 10319 tensile testing requirements and Indian Railways' emphasis on uniform hydraulic conductivity.
- Erosion Control:Slope stabilization and shoreline protection bundled with gabion structures. Coastal states deploy needle-punched fabrics beneath riprap for river bank protection schemes.
- Landfills:Leachate collection layers and capping systems. Waste management operators specify chemically resistant polypropylene grades for municipal solid waste facilities under environmental clearance conditions.
- River Bank Protection:Filtration and scour prevention in reservoir rehabilitation. CEA dam safety guidelines mandate certified geosynthetics for embankment protection, opening utility-scale channels.
Road construction anchors current volume. Rail infrastructure is climbing the fastest.
End User:
Customer type determines procurement sophistication and specification authority.
- Infrastructure Developers:Large developer entities maintain approved vendor lists for direct material purchase, unbundling geotextile supply from EPC contracts. Gujarat and Tamil Nadu state projects exhibit this pattern most visibly.
- Construction Contractors:Tier-2 and tier-3 civil works firms source through distributor networks, with BIS certification timelines delaying contract eligibility for uncertified suppliers.
- Waste Management Companies:Landfill operators specify chemically resistant grades for containment systems, with procurement tied to environmental compliance audits.
- Environmental Agencies:State pollution control boards and central ministries mandate certified deployment for public works, embedding compliance costs into tender documentation.
Infrastructure developers control specification authority. Construction contractors represent the broadest addressable base.
Distribution Channel:
Supply chain configuration shapes price realization and working capital intensity.
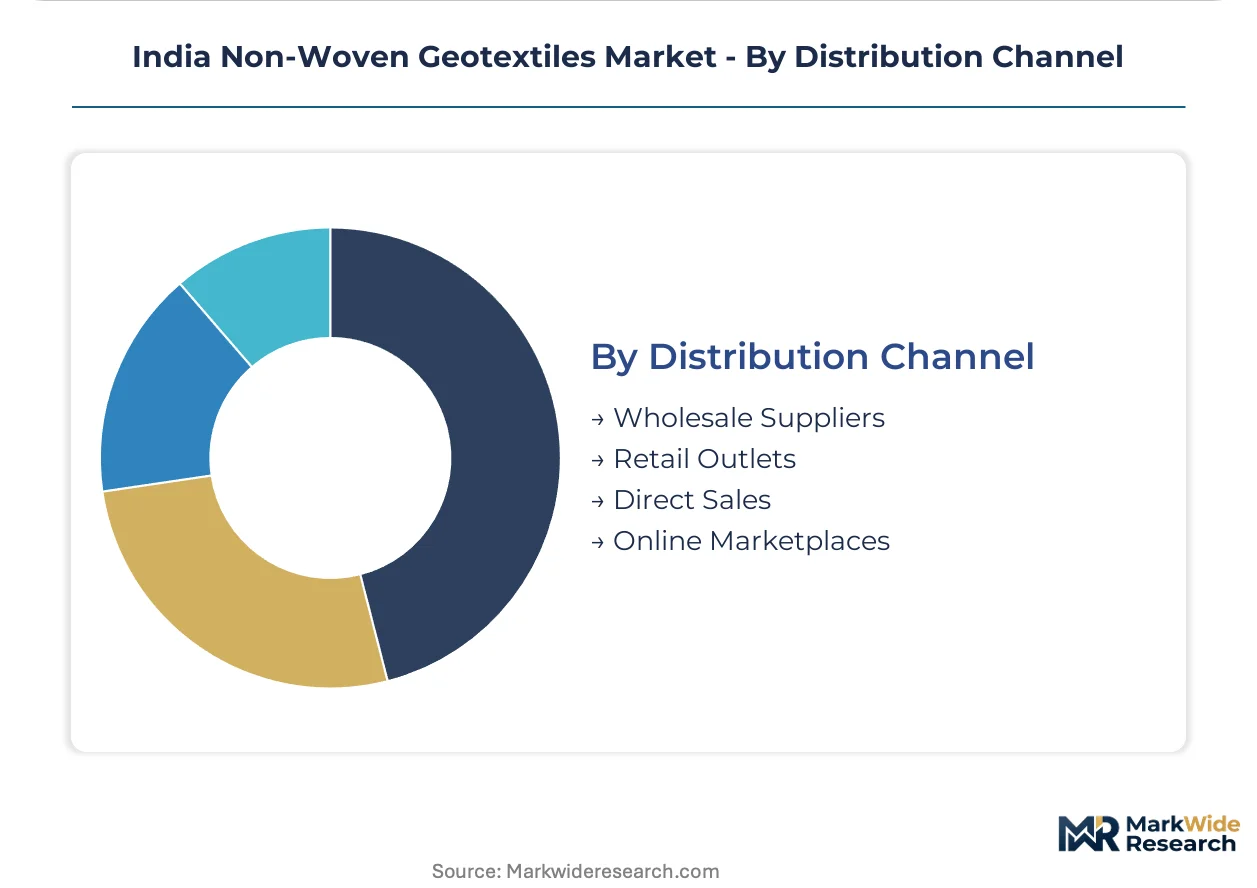
- Wholesale Suppliers:Regional distributors stock standard grades for contractor spot purchases, concentrating in Surat, Mumbai, and Chennai logistics hubs.
- Direct Sales:Integrated manufacturers serve large infrastructure developers through annual rate contracts, bypassing distributor margins.
- Online Marketplaces:Platform-based procurement pilots for standardized grades disintermediate traditional networks, with adoption concentrating among mid-tier contractors.
- Retail Outlets:Limited penetration for geosynthetics; hardware channels serve small-scale drainage and landscaping applications.
Wholesale suppliers dominate transaction volume. Direct sales is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic manufacturing clusters concentrate around western India's petrochemical corridor and southern textile belts. State-level infrastructure pipelines dictate regional demand intensity.
Maharashtra
National highway expansion and Mumbai-Pune expressway upgrades absorb certified needle-punched volumes. MoRTH specifications mandate BIS-compliant geotextiles for subgrade stabilization. Nagpur-based distributors serve Vidarbha road contracts.
Gujarat
Surat manufacturing complexes leverage proximate Reliance Industries PP feedstock for cost-competitive output. State PWD tenders specify spunbonded grades for coastal highway projects. Dahej petrochemical corridor supplies virgin resin at logistics parity.
Karnataka
Bengaluru-Chennai industrial corridor drives demand for rail ballast separation fabrics. State highway development corporations specify UV-stabilized grades for high-altitude western ghat roads. Mysuru textile clusters host conversion facilities.
Tamil Nadu
Port modernization and coastal road schemes deploy erosion-control systems. Infrastructure developers maintain direct vendor relationships bypassing distributor networks. Coimbatore industrial belt supplies needle-punched grades for southern markets.
Delhi-NCR
Delhi-Mumbai Industrial Corridor anchor projects concentrate specification authority. Central government procurement mandates embed BIS certification into contractor workflows. Faridabad and Ghaziabad logistics hubs stock standard grades for northern tenders.
India Non-Woven Geotextiles Market Competitive Landscape
Integrated manufacturers and specialized converters split the market along certification capability lines. Domestic capacity concentrates among western India petrochemical-adjacent producers and southern textile heritage clusters. Three archetypes dominate: BIS-certified integrated manufacturers with in-house testing laboratories, regional converters dependent on third-party certification, and multinational system integrators bundling geotextiles with civil works. Competitive moves center on PLI-linked capacity expansion and direct procurement relationships with infrastructure developers.
Among western India-based integrated manufacturers, Techfab India Industries Ltd. and Garware Wall Ropes Ltd. exemplify the certified-integrated archetype with Surat and Pune adjacent production footprints. Maccaferri Environmental Solutions Pvt. Ltd. occupies a position representing the multinational system-integrator model, bundling material supply with erosion-control engineering. These three anchors illustrate the bifurcation between domestic certification-heavy players and internationally positioned solution providers.
| Leading Market Players |
|---|
| OCEAN GLOBAL |
| Garware Wall Ropes Ltd. |
| Techfab India Industries Ltd. |
| Terram Geosynthetics Pvt. Ltd. |
| Maccaferri Environmental Solutions Pvt. Ltd. |
| SKAPS Industries |
| Suntech Geotextile Pvt. Ltd. |
| Jeevan Nonwoven |
| Gayatri Polymers & Geosynthetics |
| Others |
Pricing and Supply Chain Analysis
Surat's petrochemical-adjacent manufacturing cluster anchors domestic capacity and compresses logistics costs for western India converters, translating feedstock proximity into pricing power against import-dependent eastern competitors. BIS certification mandates embed compliance premiums into contractor procurement workflows, bifurcating the market between certified integrated manufacturers and uncertified regional traders.
Pricing Analysis
BIS IS 16391:2015 dictates the pricing tier structure by mandating laboratory testing and factory audit costs that certified manufacturers recover through grade premiums. Three-tier pricing structure across certified spunbonded, certified needle-punched, and uncertified commodity grades separates rail infrastructure specifications from rural road projects. Cost compression in standard needle-punched tiers is intensifying because recycled polypropylene feedstock trials are migrating to commercial scale. State PWD contractors exhibit highest price sensitivity, while dedicated freight corridor developers prioritize tensile consistency over unit economics.
Supply Chain Analysis
Domestic conversion capacity concentrates in Gujarat, Maharashtra, and Tamil Nadu, with Surat and Coimbatore industrial belts hosting the majority of needle-punch and spunbond lines. Virgin polypropylene resin draws from Reliance Industries' Dahej petrochemical corridor, while recycled fiber feedstock sources from post-industrial textile waste clusters in Tiruppur. Single-source vulnerability concentrates in European and Chinese needle-punch equipment suppliers, creating capex delivery bottlenecks for capacity expansion. Distribution runs through Surat, Mumbai, and Chennai logistics hubs serving state PWD tender pipelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Installation supervision and geotechnical design services are expanding faster than base material supply as infrastructure developers unbundle procurement from civil works contracting. This service-attach layer commands recurring revenue through annual rate contracts and site-specific specification support.
For Market Incumbents: Build certification moats by accelerating in-house ISO 10319 testing laboratory investments before BIS audit queues lengthen further. Expand direct sales relationships with Gujarat and Tamil Nadu infrastructure developers to bypass distributor margin erosion. Acquire distressed regional converters in Karnataka to consolidate western India supply positioning against spunbonded import competition. For New Entrants and Emerging Players: Mid-tier contractors in Maharashtra and Karnataka state highway projects represent the most penetrable entry point, as these buyers pilot platform-based procurement for standardized needle-punched grades. Target e-commerce material procurement channels disintermediating traditional Surat and Mumbai distributor networks. Lead with certified recycled-content offerings for rural connectivity schemes with lower load-bearing specifications. For Investors and Strategic Acquirers: Long-term, this sits as a compliance-infrastructure play because BIS mandates are embedding certified geosynthetics into irreversible public works procurement workflows. Acquisition targets should display integrated manufacturing with captive testing laboratories and established state PWD vendor list placement. Watch for PLI scheme disbursement acceleration as inflection signal for domestic capacity expansion viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Virgin PP Resin | Captive feedstock from Reliance Industries proximity defends margin against crude-linked volatility. |
| In-House ISO 10319 Testing Laboratory | Accelerates BIS IS 16391 certification timelines and qualifies suppliers for MoRTH highway tenders. |
| Recycled Fiber Feedstock Commercialization | Post-industrial textile waste from Tiruppur clusters compresses material cost curves for rural road specifications. |
| Direct Procurement Platform Development | Disintermediates Surat and Mumbai wholesale distributors for mid-tier contractor market share. |
| Rail Ballast Separation Specification Capture | Dedicated freight corridor spunbonded mandates command margin premiums over needle-punched alternatives. |
Research Methodology
Desk research of BIS certification records, MoRTH highway tender documentation, and CEA dam safety guidelines preceded structured interviews with geotechnical design engineers, state PWD procurement officers, integrated manufacturer plant managers, and distributor network heads. Primary fieldwork combined with secondary validation through customs trade data, petrochemical feedstock pricing indices, and infrastructure project development databases. Bottom-up capacity estimates triangulated against top-down infrastructure investment pipeline analysis.
Forecasts assume sustained MoRTH highway expansion, stable polypropylene feedstock availability from Gujarat's petrochemical corridor, and progressive BIS enforcement without regulatory rollback. Segmentation modeling spanned manufacturing technology, civil application category, and end-user procurement sophistication across the projection horizon. CAGRs derived from infrastructure auction pipeline velocity, certified supplier base expansion rates, and material substitution dynamics in reinforced soil applications.
Practitioners should monitor crude-linked polypropylene resin volatility, BIS certification queue lengths, and PLI scheme disbursement pacing for early signals of forecast revision. Quarterly review of state PWD tender award patterns and Reliance Industries feedstock pricing disclosures is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nonwoven Materials
Global Nonwoven Materials and Products Market
Nonwoven Materials
Nonwoven Cleanroom Apparel Market
Nonwoven Materials
Barrier Nonwoven Fiber for Breathable Surgical Gowns Market
Nonwoven Materials
Nonwoven Weed Control Fabric Market
Nonwoven Materials
Nonwoven Dust Cover Market
Nonwoven Materials
Global Wet Laid Nonwovens Market
Nonwoven Materials
Non-Wood Fiber Market
Nonwoven Materials
Nonwoven Cotton Market
Nonwoven Materials
Nonwoven Floor Covers Market
Nonwoven Materials
Non-Woven Glass Fiber Prepreg Market
Nonwoven Materials
PP Nonwovens Market
Nonwoven Materials
Nonwoven Furniture Construction Sheeting Market
Nonwoven Materials
Absorbable Nonwoven Textiles Market
Nonwoven Materials
Global Polypropylene (PP) Nonwoven Fabrics Market
Nonwoven Materials
United States Non-Woven Fabric Market
Nonwoven Materials
Nonwoven Polyester Fabric Market