
 Non-Woven Glass Fiber Prepreg Market | 2026-2036
Non-Woven Glass Fiber Prepreg Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Woven Glass Fiber Prepreg Market Analysis
The EU Green Deal is realigning material sourcing criteria across European aerospace and wind energy supply chains. Owens Corning leverages its integrated glass fiber operations to secure feedstock continuity for prepreg laminates. Hexcel Corporation anchors North American defense and commercial aviation programs with qualified non-woven prepregs. Toray Industries competes through carbon-glass hybrid portfolios that extend into adjacent composite segments.
Non-woven glass fiber prepreg consists of randomly oriented or chopped strand glass mat impregnated with thermoset resin, typically formulated with areal weights between 300 and 900 g/m² and cured under controlled temperature-pressure cycles to produce fiber-reinforced polymer components. The material serves primarily as a structural laminate in applications demanding high strength-to-weight ratios with conformable molding characteristics. Epoxy prepreg dominates aerospace qualification pathways due to established OEM certification databases and elevated service temperature performance. Wind Energy applications represent the fastest-expanding consumption vector as blade lengths exceed 100 meters and fabric-based layup cycles disperse stress concentrations more effectively than woven alternatives. Vacuum Bagging technology captures margin pools in prototype and repair environments where tooling flexibility outweighs throughput economics.
REACH registration requirements and CE marking under the EU Construction Products Regulation govern resin chemistry disclosures and fire performance classifications for glass fiber composites entering European infrastructure applications. The FAA maintains material qualification standards through its Composites Working Group, while China's GB standards and MIIT directives shape domestic content thresholds for wind turbine nacelle assemblies. Stakeholders must monitor evolving bio-based epoxy formulations and recycled glass fiber feedstock certifications as sustainability criteria penetrate procurement specifications without grandfathering existing material approvals.
Market Dynamics
EU Green Deal embodied carbon thresholds are forcing aerospace and wind OEMs to requalify entire laminate supply chains, compressing the window for legacy resin formulations and concentrating procurement among vertically integrated fiber suppliers.
Growth Catalysts
- Wind blade scaling:Turbine manufacturers above 100-meter blade lengths require conformable non-woven mats that disperse stress concentrations more effectively than woven fabrics.
- REACH compliance pathways:Established epoxy prepreg certification databases under ECHA registration requirements accelerate OEM qualification timelines versus novel bio-based alternatives.
- Germany's manufacturing corridor:Concentrated nacelle assembly capacity along the North Sea coast generates localized demand pull for just-in-time prepreg delivery.
Market Restraints
- Petrochemical feedstock volatility:Epoxy resin formulations depend on bisphenol-A and epichlorohydrin pricing, with energy-intensive refining concentrated in Rotterdam and Antwerp hubs.
- Single-source glass fiber concentration:Chopped strand mat production clusters in China's Shandong province, exposing European laminators to shipping rate fluctuations and tariff uncertainty.
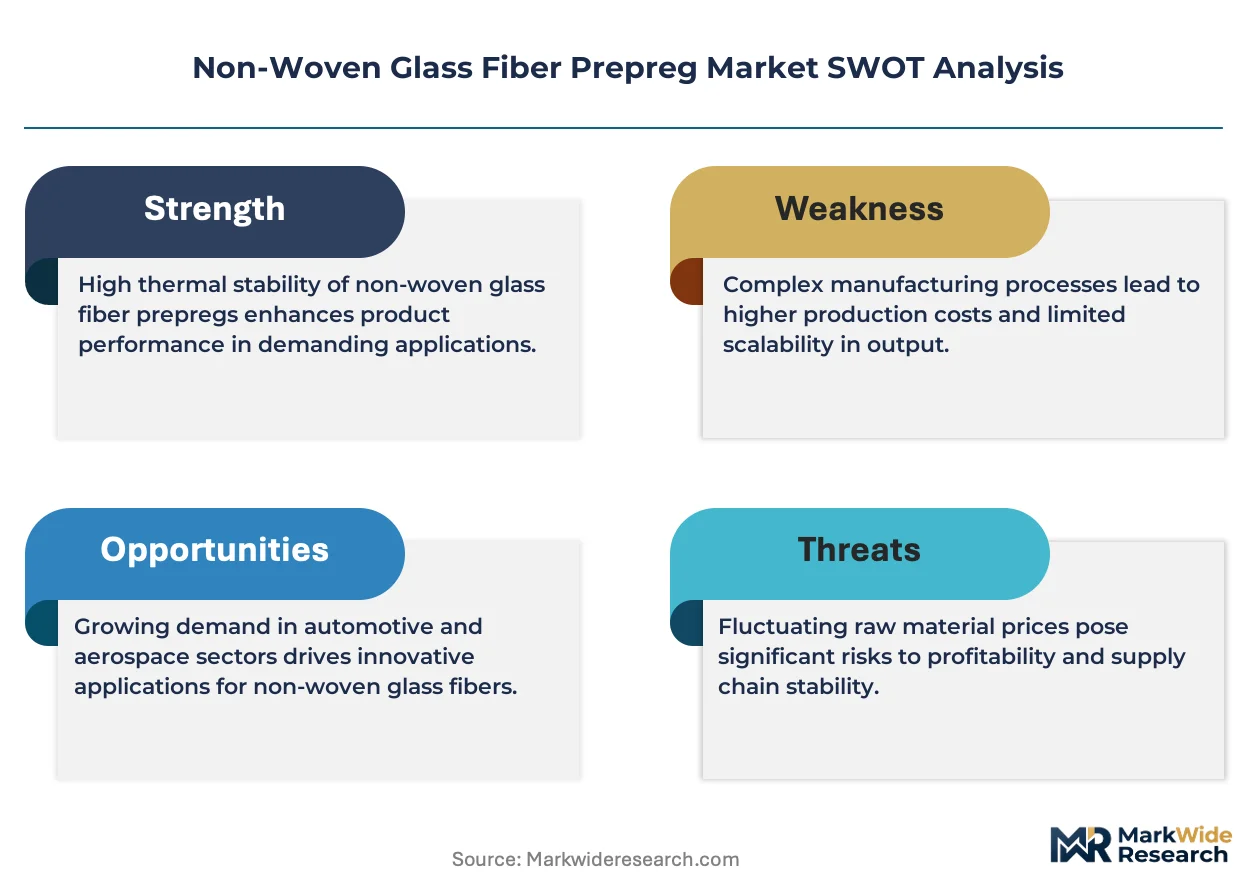
- Service temperature ceilings:Standard epoxy prepregs face substitution threat from BMI and cyanate ester systems in next-generation engine nacelles exceeding 180°C operational thresholds.
Strategic Opportunities
- Recycled fiber integration:Pyrolysis-derived glass fiber recovery from end-of-life wind blades offers feedstock cost arbitrage for secondary laminate applications.
- Vacuum infusion automation:Robot-guided preform placement in blade manufacturing reduces layup labor intensity and cycle time versus manual fabric cutting.
- MIIT domestic content mandates:China's wind turbine localization requirements create captive demand for non-woven prepreg producers establishing Jiangsu or Guangdong production.
Industry Challenges
- Autoclave capacity scarcity:Large-diameter aerospace component curing requires pressurized vessels exceeding 5-meter diameter, with qualified installation backlog extending 18-24 months.
- Cross-material certification:Hybrid carbon-glass laminates demand simultaneous qualification under both FAA Composites Working Group and OEM-specific damage tolerance protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Woven Glass Fiber Prepreg Market |
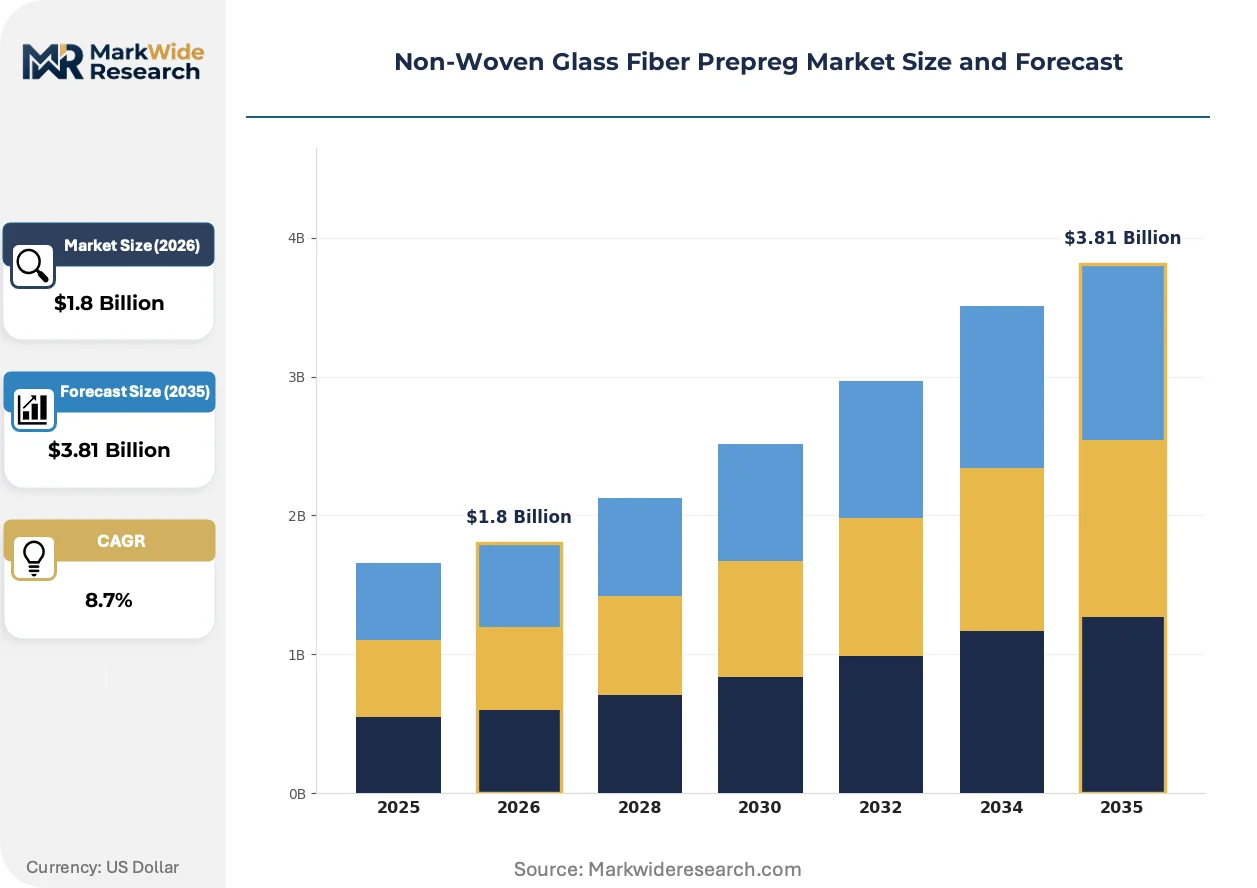
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy Prepreg, Polyurethane Prepreg, Phenolic Prepreg, Vinyl Ester Prepreg Application: Aerospace, Automotive, Wind Energy, Sporting Goods End User: OEMs, Tier-1 Suppliers, Manufacturers, Aftermarket Providers Technology: Spray Coating, Hot Pressing, Cold Pressing, Vacuum Bagging |
| Companies Covered | Owens Corning, Hexcel Corporation, Toray Industries, Saint-Gobain, Solvay, Jushi Group, SAERTEX GmbH & Co. KG, Gurit Holding AG, SGL Carbon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Woven Glass Fiber Prepreg Market Emerging Trajectories
Material science advances and regulatory compliance automation are compressing development cycles while fragmenting the qualified supplier base along sustainability and performance tier lines.
Thermoplastic-compatible glass mat architectures are absorbing development resources across European wind blade programs. Vestas and Siemens Gamesa pilot lines are validating polypropylene-impregnated non-woven prepregs for recyclable trailing edge components. This technology is absorbing margin pressure from thermoset disposal costs while requiring entirely new welding and consolidation equipment.
EU Green Deal carbon border adjustment mechanisms are reshaping import economics for Asian laminate producers. ECHA is expanding REACH disclosure requirements to cover Scope 3 emissions from glass fiber smelting and resin synthesis. German aerospace tier-1 suppliers are responding by dual-sourcing from Owens Corning's European integrated operations and qualifying domestic recycling streams.
Consolidated procurement through blade OEM direct contracts is displacing distributor-mediated spot purchasing. LM Wind Power and TPI Composites have centralized prepreg specification authority, compressing the qualified vendor list to three primary laminators per region. This concentration is most advanced in Denmark and Spain, where long-term offtake agreements now cover 70% of annual volume planning.
Non-Woven Glass Fiber Prepreg Market Segmentation
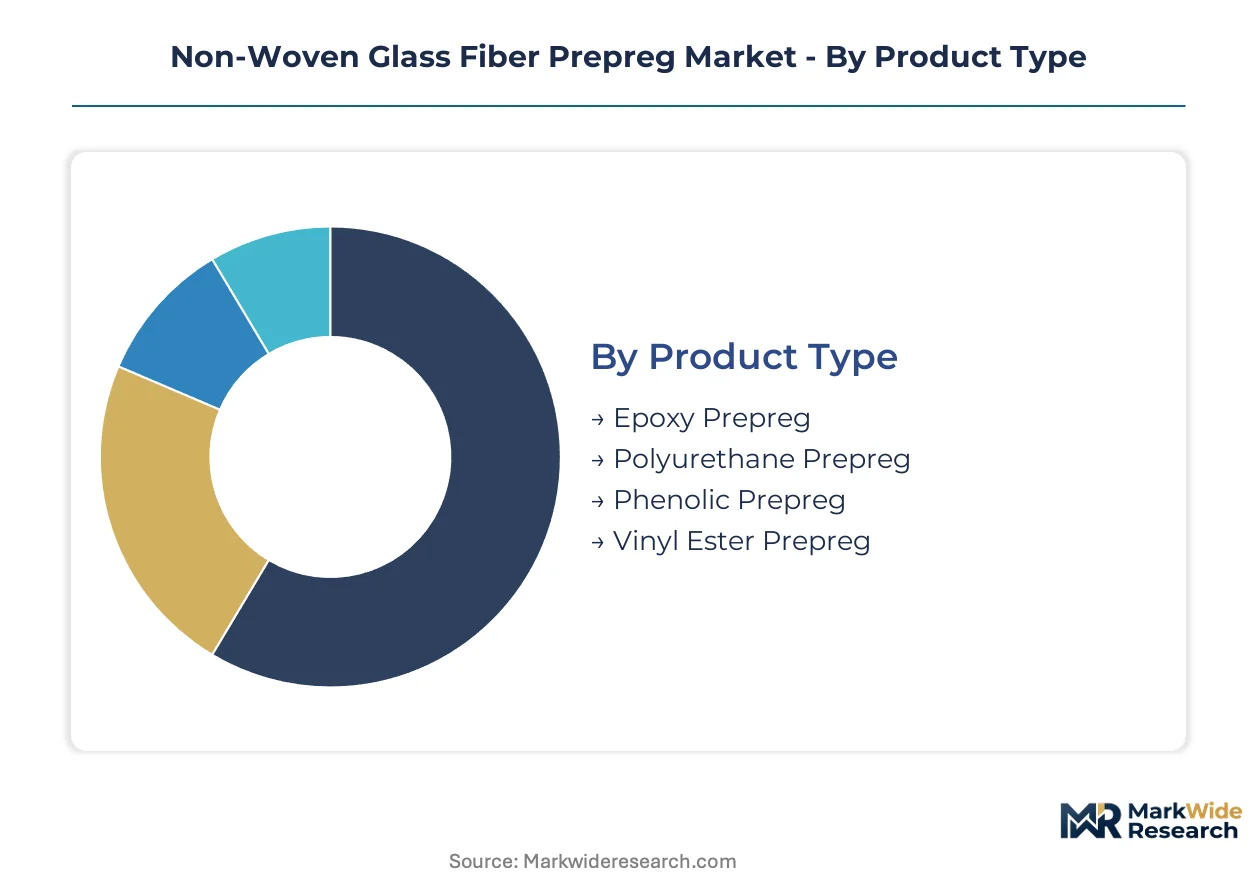
Non-woven glass fiber prepreg markets fragment along resin chemistry, curing methodology, and customer integration depth. Each segmentation axis carries distinct capital requirements, qualification timelines, and margin structures that shape supplier positioning.
Product Type:
Capital intensity peaks with aerospace-qualified epoxy systems requiring autoclave infrastructure and FAA certification databases, while industrial formulations run on lower-cost tooling.
- Epoxy Prepreg:Thermoset resin systems formulated with bisphenol-A and amine hardeners deliver service temperatures exceeding 120°C with established OEM qualification pathways. Aerospace laminators in Germany and the United States concentrate procurement here due to FAA and EASA damage tolerance protocols. REACH registration requirements under ECHA compress the qualified supplier base.
- Polyurethane Prepreg:Lower-viscosity resin chemistry enables rapid cure cycles at reduced temperatures, suiting automotive panel production where throughput economics dominate. Demand clusters in Germany's automotive manufacturing corridor around Stuttgart and Wolfsburg, with OEMs seeking to displace metal stampings in electric vehicle architectures.
- Phenolic Prepreg:Fire-resistant formulations serve rail and marine interior applications where smoke toxicity regulations apply.
- Vinyl Ester Prepreg:Corrosion-resistant systems penetrate chemical storage and infrastructure markets with moderate capital barriers.
Epoxy prepreg absorbs the bulk of installed capacity; polyurethane prepreg is expanding most quickly.
Application:
Volume concentration diverges sharply between qualification-heavy aerospace programs and scaling wind energy blade production.
- Wind Energy:Turbine manufacturers above 100-meter blade lengths specify conformable non-woven mats that disperse stress concentrations across composite spar caps. Vestas and Siemens Gamesa direct procurement through long-term offtake agreements covering 70% of annual volume in Denmark and Spain. Vacuum infusion automation is compressing layup labor intensity.
- Aerospace:OEMs including Boeing and Airbus mandate fiber-reinforced polymer laminates for secondary structures and engine nacelles, with qualification databases extending 18-24 months. Hexcel and Toray anchor supply through qualified prepregs meeting FAA Composites Working Group standards.
- Automotive:Lightweighting targets in electric vehicle platforms drive panel substitution, though cycle time constraints limit penetration.
- Sporting Goods:Bicycle frames and hockey sticks absorb specialty volumes with fragmented, distributor-mediated purchasing.
Wind Energy commands the steepest expansion trajectory; Aerospace retains the highest margin pool per kilogram.
End User:
Customer integration depth determines specification authority and contract structure across the value chain.
- OEMs:Airbus, Vestas, and BMW retain direct prepreg specification authority, compressing qualified vendor lists to three primary laminators per region. Long-term offtake agreements now cover 70% of annual volume planning in Denmark and Spain, displacing spot purchasing through distributors.
- Tier-1 Suppliers:GKN Aerospace and Spirit AeroSystems manage laminate fabrication under OEM-directed material approvals, absorbing qualification cost without specification control.
- Manufacturers:Independent composite fabricators serve prototype and repair markets with vacuum bagging flexibility.
- Aftermarket Providers:MRO operators for wind blades and aircraft components purchase through distributor channels with compressed lead times.
OEMs capture specification authority; Tier-1 Suppliers shoulder the capital burden without margin control.
Technology:
Process selection trades tooling investment against throughput and geometric complexity.
- Vacuum Bagging:Flexible tooling accommodates prototype geometries and repair environments where throughput economics yield to adaptability. LM Wind Power and TPI Composites deploy robot-guided preform placement to reduce cycle time in blade manufacturing.
- Hot Pressing:Matched metal dies deliver automotive panel volumes with sub-ten-minute cure cycles, requiring capital-intensive press installations.
- Spray Coating:Manual resin application serves low-volume custom fabrication with minimal fixed investment.
- Cold Pressing:Room-temperature curing systems penetrate infrastructure applications with reduced energy input.
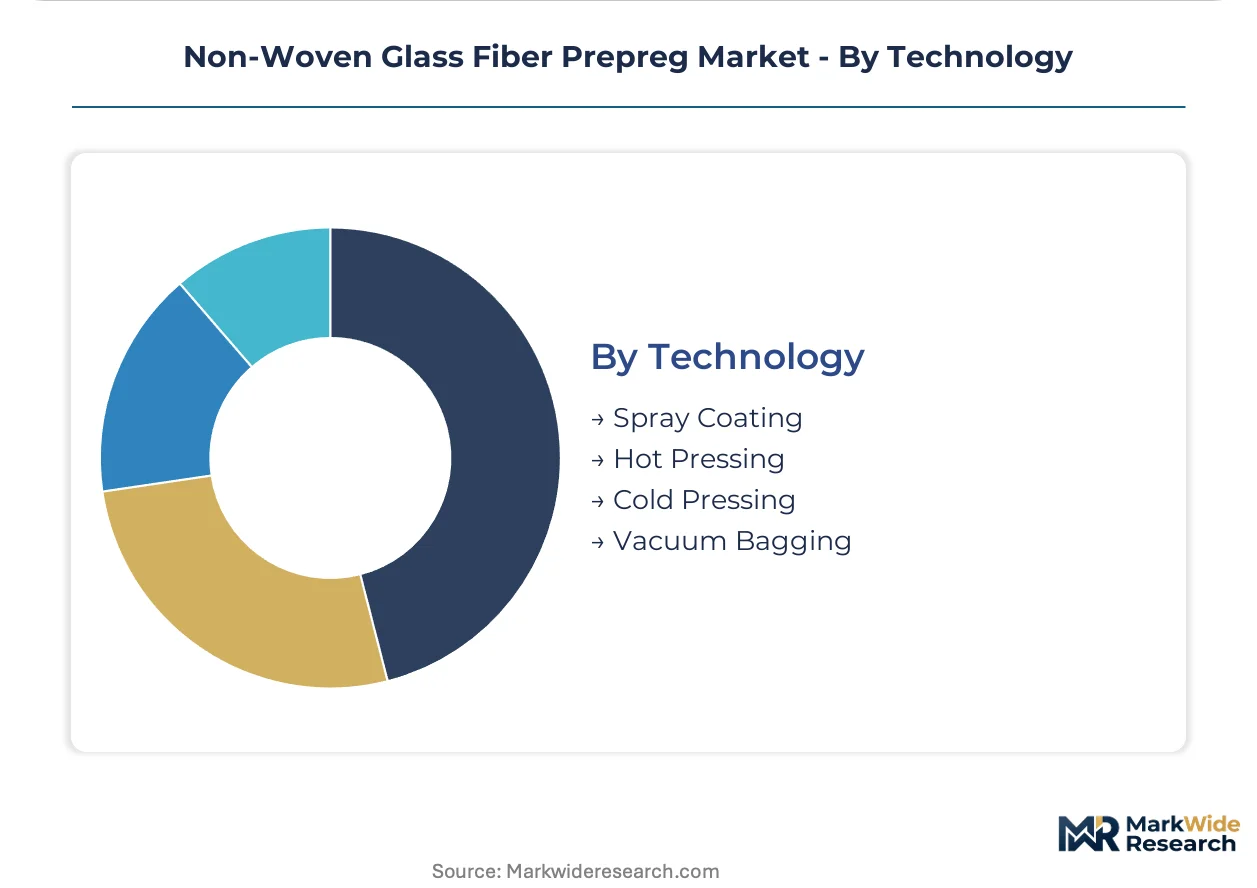
Hot Pressing locks up the most capital per line; Vacuum Bagging is gaining share fastest as blade automation advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's North Sea coast manufacturing corridor anchors European demand concentration for non-woven glass fiber prepreg. Blade assembly clusters around Bremerhaven and Cuxhaven pull just-in-time material flows from qualified laminators.
Germany
Wind turbine nacelle assembly along the North Sea coast drives concentrated procurement from Vestas and Siemens Gamesa operations. The EU Green Deal's embodied carbon thresholds force requalification of laminate supply chains under REACH registration requirements. The Bremerhaven-Cuxhaven corridor hosts integrated blade manufacturing facilities demanding conformable non-woven mat architectures.
United States
Boeing and defense contractors sustain aerospace-qualified prepreg consumption for secondary structures and engine nacelles. The FAA Composites Working Group maintains material qualification standards that compress the approved supplier base. Kansas and Washington state manufacturing clusters anchor Hexcel Corporation's qualified prepreg distribution to commercial aviation programs.
China
MIIT domestic content mandates for wind turbine assemblies generate captive demand for localized prepreg production. GB standards and provincial directives in Jiangsu and Guangdong shape nacelle localization requirements. The Shandong peninsula concentrates chopped strand mat production, exposing laminators to shipping rate volatility.
Japan
Toray Industries anchors carbon-glass hybrid portfolio development for adjacent composite segments. METI industrial policy supports advanced material qualification pathways for aerospace tier-1 suppliers. The Nagoya aerospace manufacturing cluster integrates non-woven prepreg laminates into regional supply chains.
Denmark
LM Wind Power centralizes prepreg specification authority through long-term offtake agreements covering seventy percent of annual volume. National renewable energy targets accelerate blade scaling beyond one hundred meters. The Esbjerg port complex facilitates integrated logistics for North Sea turbine installation campaigns.
Non-Woven Glass Fiber Prepreg Market Vendor Landscape
The competitive structure tilts toward integrated fiber-resin suppliers with established OEM qualification databases. Market concentration is pronounced in aerospace segments where FAA and EASA certification timelines extend eighteen to twenty-four months. Two strategic archetypes dominate: vertically integrated glass fiber producers with captive resin formulation capabilities, and specialized prepreg laminators focused on wind energy blade architectures. Capacity expansion and strategic partnerships represent the dominant competitive moves as OEMs compress qualified vendor lists to three primary laminators per region.
Among integrated fiber producers, Owens Corning anchors North American and European supply continuity through in-house glass fiber operations. Hexcel Corporation occupies the premium-tier aerospace position with qualified prepreg systems meeting FAA Composites Working Group standards. Toray Industries exemplifies the hybrid-material archetype, extending carbon-glass portfolio reach into adjacent composite applications. SAERTEX GmbH & Co. KG represents the European specialist laminator model with concentrated wind energy blade supply relationships.
| Leading Market Players |
|---|
| Owens Corning |
| Hexcel Corporation |
| Toray Industries |
| Saint-Gobain |
| Solvay |
| Jushi Group |
| SAERTEX GmbH & Co. KG |
| Gurit Holding AG |
| SGL Carbon |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap laminators in Germany's Bremerhaven-Cuxhaven corridor anchor regional supply continuity through in-house resin formulation capabilities, translating captive feedstock control into pricing discipline against volatile petrochemical benchmarks. Their ownership structure insulates long-term contract negotiations from quarterly earnings pressure, stabilizing multi-year offtake agreements with Vestas and Siemens Gamesa.
Pricing Analysis
Outcome-based pricing tied to blade manufacturing yield rates anchors aerospace-qualified epoxy tiers, separating FAA-certified laminates from industrial formulations. Price differentiation rests on REACH registration completeness and autoclave infrastructure access, with German tier-1 suppliers absorbing the steepest cost compression from embodied carbon compliance. Wind energy buyers exhibit highest price sensitivity due to consolidated procurement authority, while defense contractors tolerate premium tiers for qualified supply security.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale blade demand from LM Wind Power and TPI Composites, displacing distributor-mediated spot purchasing. Raw material flows draw from China's Shandong peninsula for chopped strand mat and Rotterdam-Antwerp refining hubs for bisphenol-A feedstock. Single-source concentration in Asian glass fiber smelting exposes European laminators to tariff volatility and shipping rate fluctuations. Distribution runs through long-term offtake agreements covering seventy percent of annual volume planning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The non-woven glass fiber prepreg sector is navigating a technology-transition phase as thermoplastic-compatible glass mat architectures displace thermoset epoxy in recyclable wind blade trailing edges. Vestas and Siemens Gamesa pilot lines validate polypropylene-impregnated systems, compressing qualification timelines for legacy resin portfolios.
For Market Incumbents: Deepen backward integration into pyrolysis-derived glass fiber recovery to capture feedstock cost arbitrage from end-of-life wind blades. Expand autoclave capacity in Kansas and Washington state manufacturing clusters to defend against BMI and cyanate ester substitution in engine nacelles exceeding 180°C thresholds. Lock in dual-source arrangements with Owens Corning's European operations to mitigate REACH disclosure expansion risks. For New Entrants and Emerging Players: Launch via vacuum infusion automation partnerships with blade OEMs seeking robot-guided preform placement to compress layup cycle times. Target aftermarket repair markets for aircraft components and wind turbine MRO, where distributor channels tolerate compressed lead times and lower qualification barriers. Pursue MIIT domestic content compliance in Jiangsu or Guangdong to access China's localized nacelle assembly demand. For Investors and Strategic Acquirers: Distressed-cycle entries favor European specialist laminators with concentrated wind energy relationships and incomplete REACH registration databases, positioned for rollup by integrated fiber producers. Monitor ECHA Scope 3 emission disclosure expansion as inflection indicator for carbon border adjustment mechanism impacts on Asian import economics. Five-to-ten year viability hinges on thermoplastic qualification velocity versus thermoset incumbency.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Fiber | Pyrolysis-derived glass fiber recovery captures feedstock cost arbitrage for secondary laminates. |
| Long-term Supply Agreement | Seventy percent volume coverage through offtake agreements stabilizes planning against spot volatility. |
| Green Manufacturing Transition | Thermoplastic-compatible mat architectures absorb margin pressure from thermoset disposal costs. |
| Capacity Expansion | Autoclave installations exceeding five-meter diameter address aerospace curing bottlenecks extending eighteen months. |
| Joint Venture | Localized production partnerships in Jiangsu satisfy MIIT domestic content mandates for turbine nacelles. |
Methodological Framework
Multi-period observation of blade scaling trajectories, REACH registration timelines, and OEM qualification databases anchored the trend analysis, supplemented by interviews with plant managers at European laminators, procurement leads at Vestas and Siemens Gamesa, distribution channel partners in the Bremerhaven-Cuxhaven corridor, and technical R&D directors at integrated fiber producers. Secondary validation drew from ECHA substance registrations, FAA Composites Working Group standards documentation, SEC 10-K filings from qualified prepreg suppliers, customs trade data for glass fiber mat flows, and MIIT domestic content directives. Bottom-up segment sizing triangulated against top-down aerospace and wind energy demand projections.
Input-output matrices modeled resin chemistry, curing methodology, and customer integration depth across the analysis window, with CAGRs derived from segment-level growth rate reconciliation. Segmentation dimensions included product type, application, end user, and technology, with industry-specific modeling of autoclave capacity utilization and vacuum infusion automation penetration. Forecast inputs incorporated embodied carbon threshold compliance costs and thermoplastic qualification velocity assumptions.
Petrochemical feedstock volatility, single-source glass fiber concentration, and regulatory disclosure expansion are the dominant revision risks for projection accuracy. Forecasts reflect documented assumptions regarding OEM procurement consolidation and sustainability criteria penetration without grandfathering provisions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nonwoven Materials
India Non-Woven Geotextiles Market
Nonwoven Materials
Hygienic Non-Woven Fabrics Market
Nonwoven Materials
Nonwoven Furniture Construction Sheeting Market
Nonwoven Materials
Nonwoven Blanket Market
Nonwoven Materials
Nonwoven Weed Control Fabric Market
Nonwoven Materials
Global Melt-Blown Nonwovens Market
Nonwoven Materials
Nonwoven Protective Clothing Market
Nonwoven Materials
Non Woven Printing Machine Market
Nonwoven Materials
PP Nonwovens Market
Nonwoven Materials
HDPE Nonwoven Market
Nonwoven Materials
Global Spunbond Nonwovens Market
Nonwoven Materials
Global Polypropylene (PP) Nonwoven Fabrics Market
Nonwoven Materials
Global Nonwoven Disposable Gloves Market
Nonwoven Materials
Nonwoven Floor Covers Market
Nonwoven Materials
Nonwoven Geotextiles Market
Nonwoven Materials
Polywoven Bags Market