
 Nonwoven Decking Market | 2026-2036
Nonwoven Decking Market Size, Share, and Industry Trends Forecast 2026-2036
Nonwoven Decking Market Intelligence
Enhanced durability nonwovens for high-traffic commercial applications is reorganizing the competitive landscape. This shift favors suppliers with advanced material science capabilities. Trex Company leverages its extensive distribution network to reach both contractors and homeowners. UPM Biocomposites specializes in natural fiber composites, differentiating on sustainability credentials and appealing to environmentally conscious designers.
Nonwoven decking refers to engineered fabrics, typically made from polypropylene or polyester fibers, bonded together chemically, thermally, or mechanically. These materials serve as reinforcement layers, surface protection, or drainage components within composite decking systems and outdoor flooring structures. Polypropylene remains the dominant material due to its moisture resistance and cost-effectiveness. Within applications, outdoor spaces for residential projects represent the largest segment, while geotextiles for commercial installations show significant growth potential.
Building codes in the United States, often referencing ASTM standards, dictate performance requirements for fire resistance and slip resistance. In Europe, CE marking and adherence to REACH regulations for chemical content govern market access for decking components. Suppliers must navigate these disparate regional standards while investing in material innovations that meet rising contractor demand for installation efficiency and longevity.
Market Dynamics
The central dynamic is the divergence between cost-driven demand for standard polypropylene nonwovens and a value-driven pull towards high-performance, sustainable composites. This creates distinct innovation paths for manufacturers targeting different construction segments.
Growth Catalysts
- Residential Outdoor Living:Expansion of outdoor entertainment spaces in residential projects, particularly in the United States, directly increases the volume of nonwoven materials used within decking systems.
- Sustainable Building Mandates:Policies aligned with Europe's green initiatives favor materials with recycled content or natural fibers, creating a regulatory pull for innovative nonwoven decking products.
- Advanced Bonding Technology:Improved thermal and chemical bonding processes enhance the delamination resistance of nonwoven layers, boosting contractor confidence in the longevity of composite decking.
Market Restraints
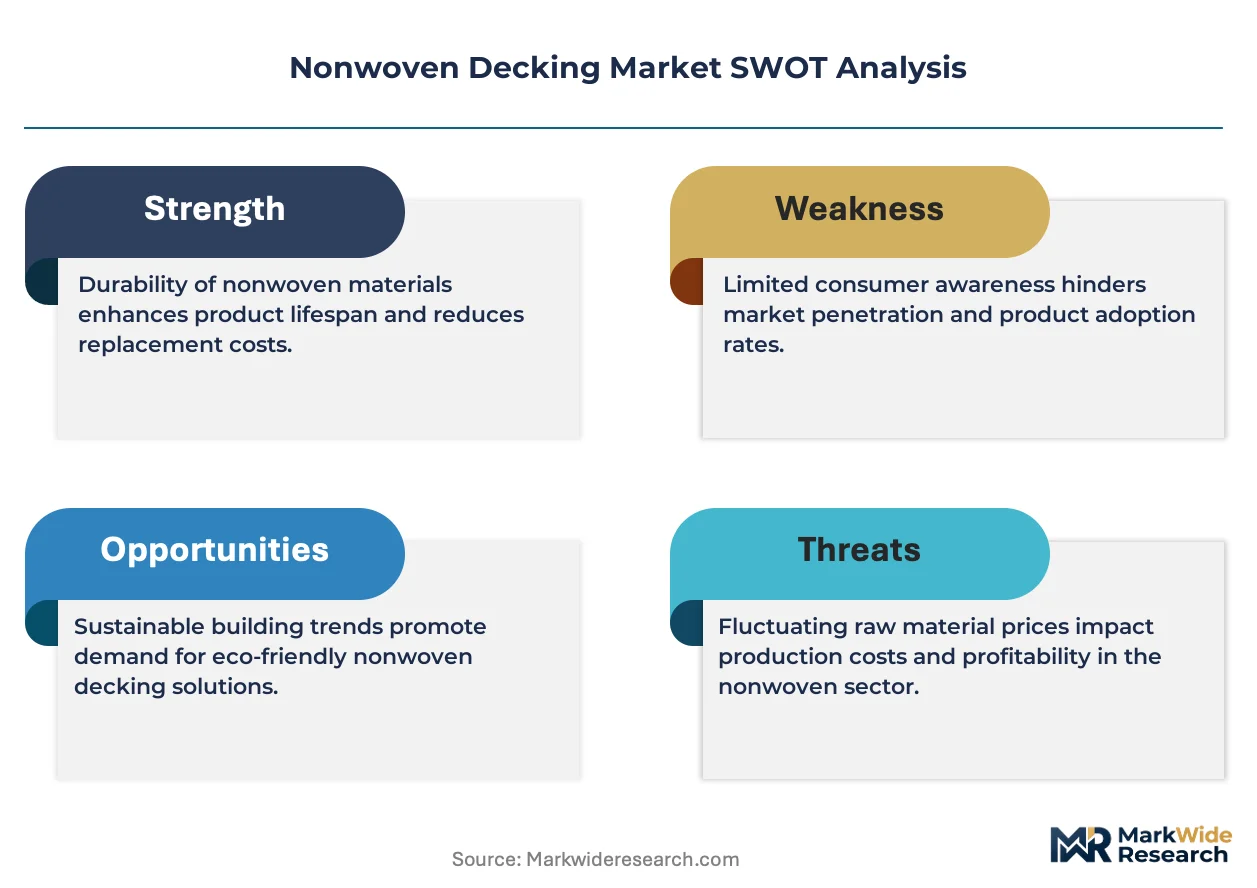
- Raw Material Volatility:Price fluctuations for polypropylene, a primary petrochemical-derived feedstock, create margin pressure and complicate cost forecasting for nonwoven manufacturers and their customers.
- Threat of Substitution:Fully synthetic PVC decking and modified wood products that do not require a nonwoven layer compete directly for market share, especially in premium segments.
- UV Degradation:Without expensive additives, standard nonwoven materials can exhibit poor UV stability, limiting their use in applications with direct, prolonged sun exposure.
Strategic Opportunities
- Geographic Expansion:Introducing cost-effective nonwoven decking solutions to growing construction markets in South America and Southeast Asia represents a significant volume opportunity.
- New Product Categories:Developing specialized nonwovens for adjacent outdoor applications, such as vertical cladding, fencing, or acoustic barriers, opens new revenue streams beyond horizontal surfaces.
- Bio-Composite Development:Investing in R&D for nonwovens made from agricultural waste fibers, like hemp or flax, can create a new class of premium, circular-economy products.
Industry Challenges
- Regulatory Navigation:The cost and complexity of achieving compliance with disparate regional standards, such as ASTM fire resistance codes in the US and REACH chemical regulations in Europe, act as a barrier to entry.
- Supply Chain Adaptation:Establishing reliable, scaled supply chains for emerging natural fibers requires significant investment in sourcing, quality control, and processing capabilities distinct from traditional polymers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nonwoven Decking Market |
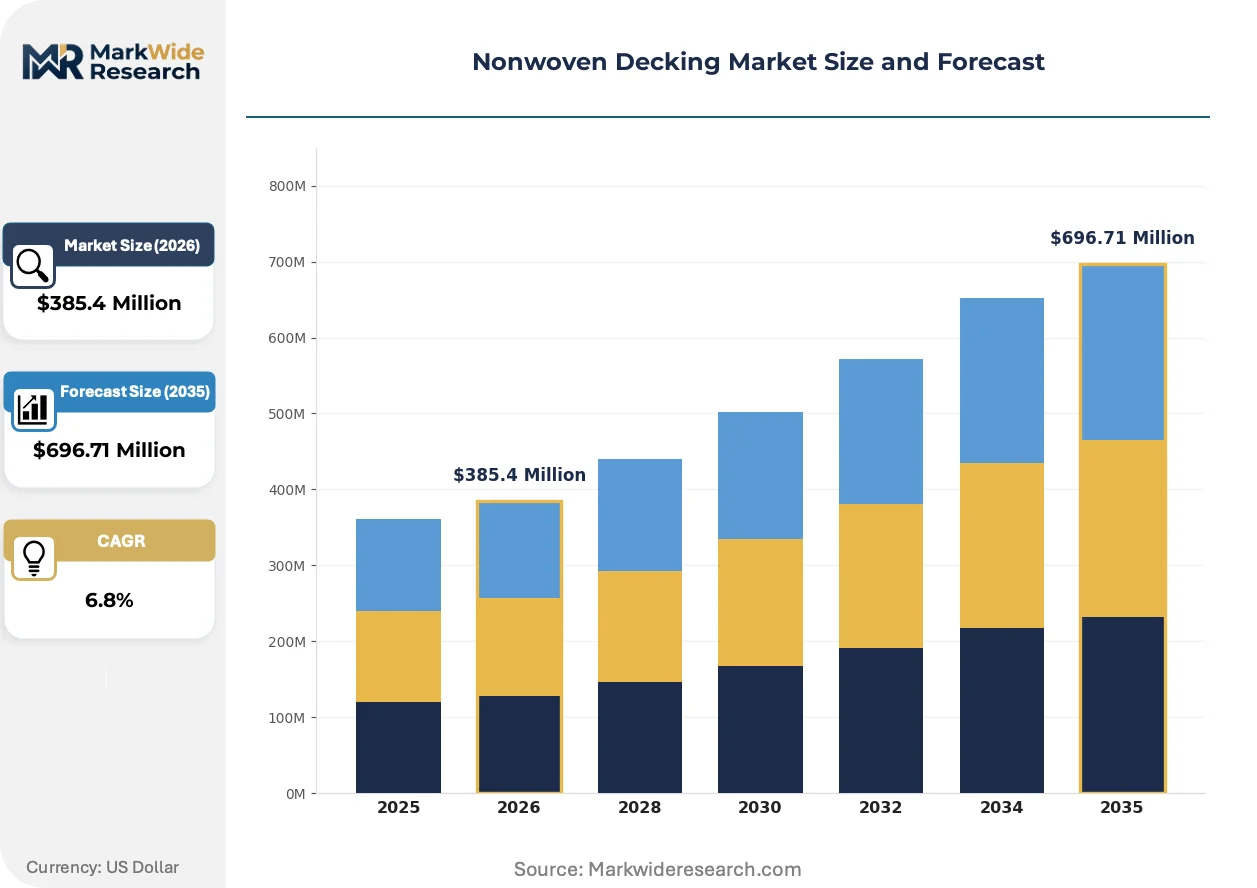
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Geotextiles, Carpet Tiles, Wall Coverings, Padding Application: Outdoor Spaces, Commercial Flooring, Residential Flooring, Industrial Usage Material: Polypropylene, Polyester, Natural Fibers, Biodegradable Options End User: Contractors, Designers, Homeowners, Manufacturers |
| Companies Covered | Trex Company, TimberTech, TAMKO Building Products, UPM Biocomposites, Green Bay Decking LLC, DuraLife Decking and Railing Systems, Cardinal Building Products, Fiberon LLC, Azek Building Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nonwoven Decking Market Strategic Shifts & Innovations
Material science advancements are driving a fundamental split in product strategy. Innovations are simultaneously pushing the boundaries of sustainability with bio-composites while also optimizing the cost-performance ratio of conventional polypropylene-based materials for mass-market applications.
Natural fiber composites serve as a sustainable reinforcement alternative to synthetic fibers. Environmentally-focused architects and homeowners in developed markets are specifying these materials for high-end residential and light commercial projects. This adoption is bifurcating the market into a premium, eco-branded segment and a volume-driven, traditional polypropylene segment.
Europe's Corporate Sustainability Reporting Directive (CSRD) is a significant regulatory driver. The directive compels large construction firms and material producers to disclose the environmental footprint of their supply chains, including decking components. This affects nonwoven suppliers by forcing them to provide lifecycle assessment data and prioritize recycled or bio-based feedstocks to remain competitive.
Contractor preference is shifting towards integrated decking systems that prioritize installation speed over individual component cost. This disrupts the standalone sale of nonwoven rolls, favoring manufacturers who offer pre-bonded composite boards or complete installation kits. The shift is most visible within the professional residential remodeling channel in the United States.
Nonwoven Decking Market Segmentation
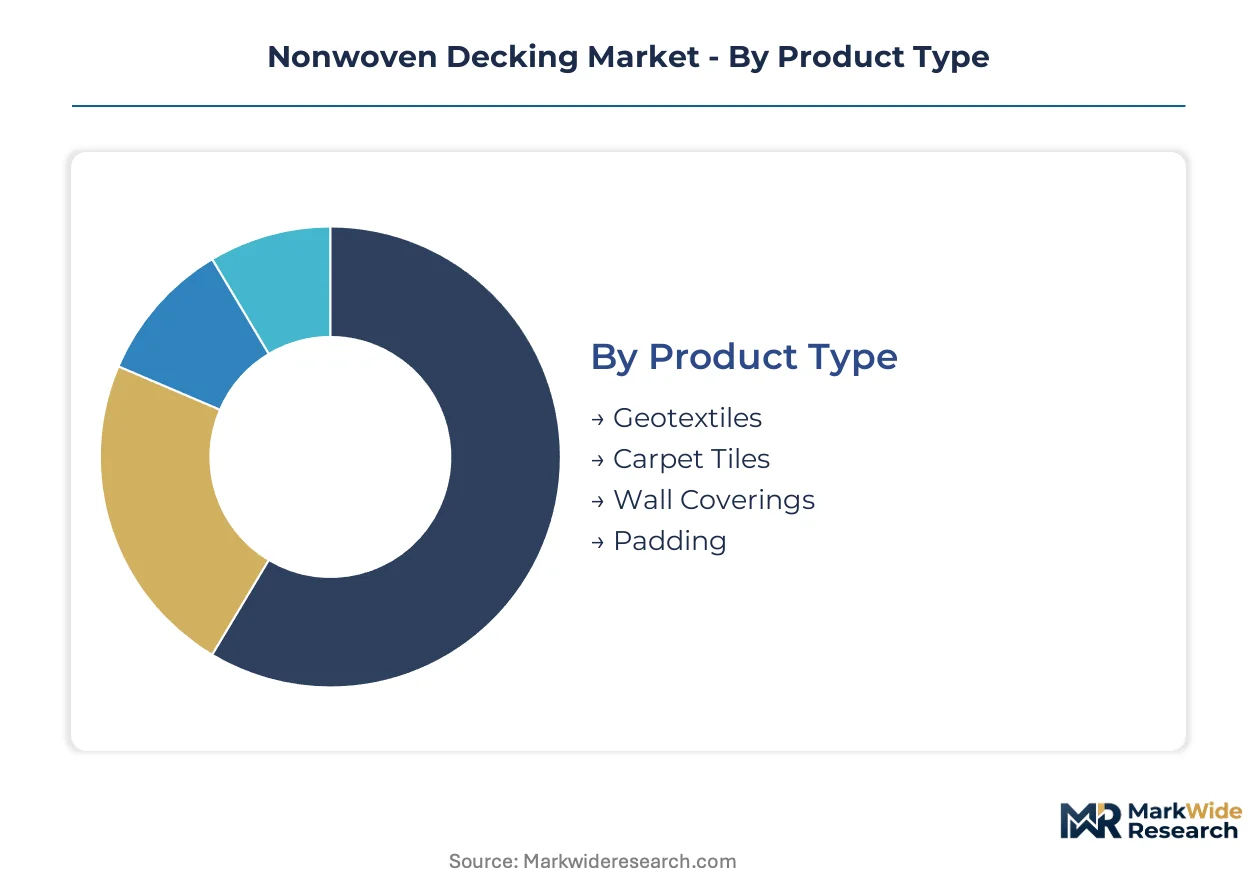
Understanding the Nonwoven Decking Market through segmentation reveals how diverse product forms, applications, materials, and end-user preferences shape demand. This detailed breakdown highlights areas of concentrated value and opportunities for specialized product development. It also clarifies the distinct pathways for market entry and competitive differentiation.
Product Type:
The channel mix for nonwoven decking components reflects varying distribution strategies, from direct supply to manufacturers for integration into finished products to retail channels for installers and end-users.
- Geotextiles:These engineered fabrics, typically made from polypropylene or polyester, provide reinforcement, filtration, and drainage within composite decking substructures. Demand concentrates in large-scale commercial installations, driven by requirements for ground stabilization and moisture management in outdoor spaces.
- Carpet Tiles:Nonwoven carpet tiles often feature a robust nonwoven backing that enhances dimensional stability and durability for outdoor and commercial flooring. Their modular design appeals to commercial contractors seeking efficient installation and easy replacement in high-traffic areas.
- Wall Coverings:Nonwoven wall coverings serve as a protective or decorative layer, providing enhanced durability and moisture resistance in certain outdoor or semi-outdoor applications.
- Padding:Nonwoven padding offers cushioning and sound absorption properties, primarily used as an underlayment in some composite decking systems to improve comfort and reduce impact noise.
By volume, Geotextiles leads the product type segment due to widespread infrastructure applications. By growth pace, Carpet Tiles is ahead, driven by commercial renovation cycles.
Application:
Application segments are often distinguished by the value proposition they offer, ranging from cost-effective solutions for general use to high-performance systems for specialized environments requiring enhanced durability or aesthetic appeal.
- Outdoor Spaces:This segment includes nonwovens used in composite decking, patios, and other external structures, primarily to provide reinforcement, drainage, or weed suppression. Demand is strong in the United States for residential renovation projects and new home construction.
- Commercial Flooring:Nonwoven materials serve as backing or reinforcement layers in heavy-duty commercial floor coverings, offering stability and moisture resistance in environments like offices, retail, and hospitality. European regulations, such as CE marking, influence material selection for these installations.
- Residential Flooring:Nonwovens in residential flooring applications typically enhance the durability and comfort of indoor and outdoor composite floor systems for homeowners.
- Industrial Usage:This category encompasses nonwovens employed in specialized industrial settings for specific structural, protective, or drainage functions within flooring or platform systems.
The expansion of outdoor entertainment spaces drives the Outdoor Spaces segment. Building codes dictating performance requirements constrain material choices within Commercial Flooring.
Material:
Material choices reflect the availability of raw feedstocks and the complexity of processing, influencing supply chain concentration and the strategic sourcing decisions of nonwoven manufacturers.
- Polypropylene:This synthetic polymer is the dominant material for nonwoven decking components due to its inherent moisture resistance, chemical stability, and cost-effectiveness. Price volatility for petrochemical feedstocks impacts manufacturing margins for polypropylene-based products.
- Natural Fibers:Nonwovens made from natural fibers, such as hemp or flax, offer sustainable alternatives, appealing to environmentally conscious designers and builders. Investment in R&D for agricultural waste fibers creates new premium, circular-economy products.
- Polyester:Polyester nonwovens provide good tensile strength and dimensional stability, often used where higher performance or specific mechanical properties are required in decking systems.
- Biodegradable Options:These materials are engineered to decompose naturally, representing an emerging category driven by sustainable building mandates and consumer demand for eco-friendly construction components.
Polypropylene materials command significant market share due to their cost-performance ratio. Natural Fibers are gaining share fastest, driven by sustainability mandates.
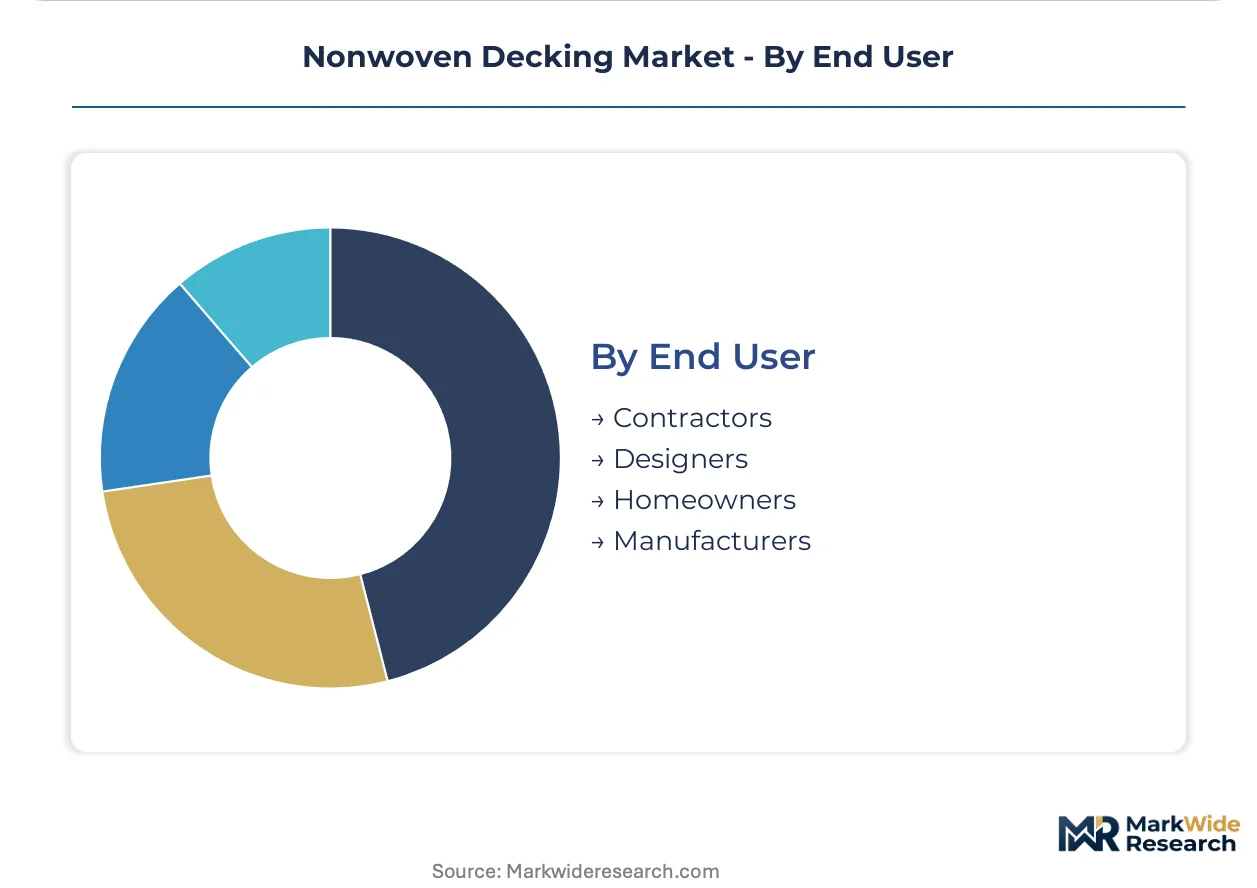
End User:
End-user segments exhibit distinct purchasing behaviors and product requirements, ranging from bulk procurement by professional contractors to individual selections made by homeowners for renovation projects.
- Contractors:These professional installers and builders prioritize nonwoven decking components that offer ease of installation, consistent quality, and long-term durability to meet project specifications and client expectations. Their demand often focuses on efficiency and reliability.
- Homeowners:Individual homeowners purchase nonwoven decking materials, often through retail channels, for personal renovation or DIY projects. Their decisions are influenced by aesthetic appeal, ease of maintenance, and perceived value, especially for outdoor living spaces.
- Designers:Designers specify nonwoven decking materials based on aesthetic requirements, performance characteristics, and sustainability credentials, influencing material choices for high-end residential and commercial projects.
- Manufacturers:Manufacturers of composite decking systems integrate nonwoven layers as components, requiring consistent supply, specific technical properties, and competitive pricing for their finished products.
Contractors represent a high-volume segment, driven by project scale. Homeowners exert significant influence over material selection in residential renovation channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Concentration sits with established construction markets that drive demand for outdoor living solutions. North America and Europe exhibit mature preferences for composite decking, while Asia's emerging economies present volume opportunities. Regulatory frameworks across these regions influence material specification and market access.
United States
United States demand for nonwoven decking stems from robust residential renovation and new construction activity. Building codes, referencing ASTM standards, dictate performance requirements for fire and slip resistance. The Southeast's expanding outdoor living market, particularly in Florida, drives significant volume for composite decking systems.
Germany
European green initiatives influence Germany's nonwoven decking market, emphasizing sustainable materials. CE marking and REACH regulations strictly control chemical content and product safety for building materials. Manufacturers in the Rhine-Ruhr region concentrate on advanced nonwoven production for both residential and commercial projects.
China
China's rapid urbanization and infrastructure development fuel demand for nonwoven decking in commercial and residential projects. GB standards for building materials ensure product quality and safety across the construction sector. Manufacturing clusters in the Pearl River Delta supply both domestic and export markets with diverse nonwoven decking components.
India
India's burgeoning construction sector, particularly in residential and commercial infrastructure, requires durable nonwoven decking solutions. BIS standards for construction materials guide product specifications and quality control across the country. The industrial hubs of Karnataka are witnessing significant growth in the manufacturing of composite building materials.
Nonwoven Decking Market Key Industry Players
Concentration sits with established nonwoven manufacturers leveraging material science expertise. The market exhibits a tiered structure, with a distinct split between high-performance, sustainable composite specialists and volume-driven polypropylene producers. These specialists often target value-driven segments with advanced material solutions. Strategic partnerships for distribution and targeted R&D investments in biodegradable options are common competitive moves. Geographic expansion into emerging construction markets also represents a key strategy for volume growth.
Within the established composite decking sector, Trex Company anchors a strong market position through extensive distribution networks for both contractors and homeowners across North America. UPM Biocomposites, a Finland-based entity, exemplifies specialization in natural fiber composites, appealing to environmentally conscious designers and sustainable building mandates. Azek Building Products, known for its premium decking solutions, also sits within the segment of companies offering advanced material science capabilities for durable outdoor applications. These entities collectively shape the competitive dynamics through continuous product innovation, material advancements, and broad market reach.
| Leading Market Players |
|---|
| Trex Company |
| TimberTech |
| TAMKO Building Products |
| UPM Biocomposites |
| Green Bay Decking LLC |
| DuraLife Decking and Railing Systems |
| Cardinal Building Products |
| Fiberon LLC |
| Azek Building Products |
| Others |
Cost & Logistics Intelligence
Large-scale manufacturing of polypropylene nonwovens creates significant economies of scale, concentrating supply among a few major producers. This scale directly influences competitive price floors for mass-market decking components.
Pricing Analysis
CE marking in Europe dictates the pricing tier structure for nonwoven decking components, influencing market access and material specifications. Pricing stratifies across premium bio-composite options and volume-driven polypropylene materials, with sustainability credentials and performance certifications driving differentiation. Raw material volatility for polypropylene creates margin pressure across the standard segment. Contractors sourcing high-volume polypropylene nonwovens exhibit the most price sensitivity, while designers specifying natural fiber composites for premium projects are less sensitive.
Supply Chain Analysis
China's Pearl River Delta and Germany's Rhine-Ruhr region anchor significant nonwoven decking component production, supplying diverse markets. The supply chain sources from polypropylene, polyester, and emerging natural fibers like hemp or flax. Raw material volatility for petrochemical-derived polypropylene represents a significant structural risk for manufacturers. Distribution runs through extensive networks, reaching composite decking manufacturers, contractors, and increasingly, homeowners via retail channels for integrated systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nonwoven decking market presents a significant service-attach opportunity, particularly around installation and maintenance. Integrated decking system sales, which bundle components and installation support, are expanding faster than individual material sales.
For Market Incumbents: Secure leadership by investing heavily in advanced material science for enhanced durability and UV stability, countering the threat of substitution from PVC decking. Deepen vertical integration into bio-composite development to meet sustainable building mandates. Expand distribution networks, particularly in emerging markets, to maintain volume against new entrants. Prioritize R&D in improved thermal and chemical bonding to boost contractor confidence in composite decking longevity.
For New Entrants and Emerging Players: CE marking compliance for bio-based materials offers a certification fast-track into European markets, appealing to environmentally conscious designers. Target specialized nonwovens for adjacent outdoor applications like vertical cladding or acoustic barriers, expanding beyond horizontal surfaces. Introduce cost-effective, sustainable decking solutions to residential outdoor living projects in South America, a highly penetrable segment. Differentiate through transparent lifecycle assessment data, aligning with regulatory drivers like CSRD.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialists in natural fiber composites and advanced bonding technologies, aligning with long-term sustainability trends. The market's viability over the next decade depends on the continued push for eco-friendly construction materials and integrated decking systems. Target acquisition profiles include agile firms with proprietary agricultural waste fiber processing or unique thermal bonding expertise. The signal to watch is the increasing adoption of bio-composite nonwovens in major commercial infrastructure projects.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Bio-Composite R&D | Develops new premium products from agricultural waste fibers, appealing to environmentally conscious designers. |
| Expand Distribution Network | Reaches more contractors and homeowners, countering market share erosion from substitute products. |
| Certify Products to ASTM/CE Standards | Ensures market access and meets performance requirements for fire and slip resistance in the US and Europe. |
| Develop Integrated Decking Systems | Prioritizes installation speed for contractors, capturing value beyond individual nonwoven component sales. |
| Geographic Expansion into Southeast Asia | Introduces cost-effective nonwoven decking solutions to growing construction markets, unlocking significant volume. |
Research Approach
Cross-validation between primary interviews and secondary market reports anchors the qualitative findings for nonwoven decking. Industry stakeholders, including nonwoven manufacturers, composite decking producers, and contractors, provided critical insights. Secondary validation utilized ASTM standards, CE marking guidelines, and construction industry reports. This approach employed both bottom-up market sizing and top-down validation against overall construction spend for comprehensive triangulation.
Sensitivity analysis evaluated market projections against variations in raw material prices and regulatory shifts. The analytical framework integrated segmentation across product type, application, material, and end-user, alongside regional compliance levels. Compound Annual Growth Rates were derived from historical data and projected construction activity. Key forecast inputs included polypropylene price volatility and residential renovation spending in the United States over the projection horizon.
Underlying assumptions cover current economic conditions and established building codes, with deviation risk concentrated in raw material price fluctuations. Forecasts reflect these assumptions, acknowledging potential impacts from unforeseen regulatory changes or material science breakthroughs. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nonwoven Materials
Nonwoven Geotextiles Market
Nonwoven Materials
India Non-Woven Geotextiles Market
Nonwoven Materials
Nonwoven Fabric Production Line Market
Nonwoven Materials
United States Non-Woven Fabric Market
Nonwoven Materials
Polywoven Bags Market
Nonwoven Materials
Global Nonwoven Disposable Gloves Market
Nonwoven Materials
Nonwoven Cleanroom Apparel Market
Nonwoven Materials
Staples PP Nonwovens Market
Nonwoven Materials
Asia-Pacific Non-Woven Fabric Market
Nonwoven Materials
Global Non Woven Fabric Market
Nonwoven Materials
Nonwoven Cotton Market
Nonwoven Materials
Nonwoven Sponges Market
Nonwoven Materials
Nonwoven Flanging Market
Nonwoven Materials
Nonwoven Polyester Fabric Market
Nonwoven Materials
Nonwoven Protective Clothing Market
Nonwoven Materials
Global Melt-Blown Nonwovens Market