
 Nonwoven Furniture Construction Sheeting Market | 2026-2036
Nonwoven Furniture Construction Sheeting Market Size, Share, and Industry Trends Forecast 2026-2036
Nonwoven Furniture Construction Sheeting Market Intelligence
Modular furniture kit packaging is realigning how nonwoven sheeting is specified and purchased. Freudenberg Performance Materials leverages its European manufacturing footprint to supply standardized roll formats for flat-pack assemblers. Berry Global Inc. anchors North American demand through direct mill partnerships with large upholstery producers. Fitesa competes on meltblown specialization for acoustic and protective furniture layers.
Nonwoven furniture construction sheeting comprises engineered fibrous webs bonded through thermal, chemical, or mechanical means, typically weighing 15–150 gsm and serving as interlining, padding, or barrier layers beneath visible upholstery surfaces. Spunbond grades dominate volume due to their tensile strength and cost efficiency in high-throughput furniture lines. Needle-punched segments capture margin pools in premium seating where dimensional stability and loft retention command specification premiums. Meltblown applications in sound absorption are gaining traction in office furniture as open-plan acoustic standards tighten.
The US Consumer Product Safety Commission flammability framework and California's Bureau of Electronic and Appliance Repair, Home Furnishings and Thermal Insulation regulate ignition resistance requirements that directly determine fiber and additive selection. REACH restrictions in Europe limit certain chemical binders and flame retardants, pushing suppliers toward thermoplastic bonding alternatives. Stakeholders must monitor how pending state-level chemical disclosure laws in the US and evolving EU Ecodesign criteria reshape specification roadmaps and qualification timelines for nonwoven furniture components.
Market Dynamics
Modular furniture kit packaging is compressing specification cycles and forcing nonwoven suppliers to standardize roll formats for flat-pack assemblers, while California TB 117-2013 and EU REACH simultaneously rewrite fiber and binder selection criteria.
Growth Catalysts
- Residential upholstery expansion:Furniture manufacturers in Guangdong and Zhejiang provinces are scaling spunbond procurement for cushioning layers in export-grade seating.
- REACH chemical restrictions:European ECHA limitations on halogenated flame retardants are accelerating thermoplastic bonding adoption across continental supply chains.
- Acoustic standards tightening:Open-plan office furniture specifications in North America are pulling meltblown grades for sound absorption layers.
Market Restraints
- Petrochemical input volatility:Polypropylene and polyester staple fiber costs fluctuate with crude oil indices, squeezing margin pools on commodity-grade spunbond.
- China supply concentration:Bulk needle-punched capacity clusters in Zhejiang province, creating single-point vulnerability for European flat-pack assemblers.
- Technical loft degradation:High-recycled-content fibers exhibit compressive set failures in premium seating applications above 80,000 cycle testing.
Strategic Opportunities
- India furniture manufacturing:PLI scheme incentives for domestic upholstery production are opening bulk procurement channels for mid-weight spunbond grades.
- Bio-based binder convergence:Polylactic acid fiber webs combined with bio-ureaformaldehyde resins address EU Ecodesign criteria for circular material content.
- Direct mill procurement platforms:Digital B2B marketplaces are disintermediating regional distributors for standardized 15-50 gsm interlining specifications.
Industry Challenges
- Flammability certification timelines:California Bureau of Electronic and Appliance Repair testing queues extend qualification cycles for new fiber blends by 4-6 months.
- Needle-punch skill scarcity:Loft engineering expertise concentrates in aging European technician pools, constraining quality replication in Southeast Asian greenfield plants.
- Legacy ERP integration:Furniture assemblers' MRP systems require custom EDI mapping for nonwoven roll traceability data, delaying supplier onboarding.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nonwoven Furniture Construction Sheeting Market |
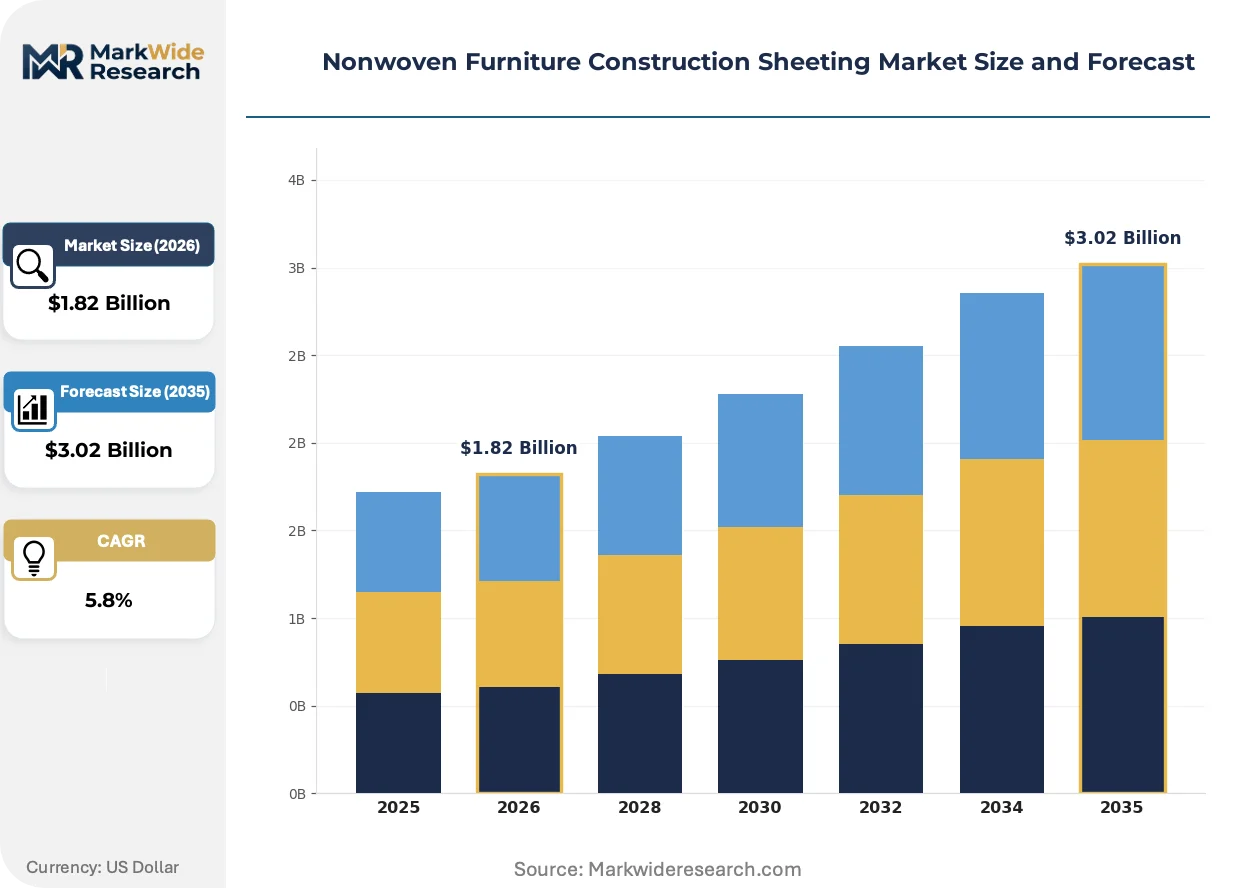
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $3.02 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spunbond, Meltblown, Needle-Punched, Airlaid End User: Residential Furniture, Office Furniture, Medical Furniture, Outdoor Furniture Application: Cushioning, Upholstery, Protection, Sound Absorption Distribution Channel: Online Retail, Specialty Stores, Wholesale Distributors, Direct Sales |
| Companies Covered | Kimberly-Clark Corporation, Freudenberg Performance Materials, Berry Global Inc., Fitesa, Toray Industries, Mitsui Chemicals, PFNonwovens, Johns Manville, Glatfelter Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nonwoven Furniture Construction Sheeting Market Strategic Shifts & Innovations
Material science advances and regulatory chemistry restrictions are converging to redefine how nonwoven layers perform beneath visible upholstery surfaces, with sustainability credentials now filtering specification decisions.
Hybrid spunbond-meltblown-spunbond (SMS) laminates are unifying barrier and cushioning functions in single-pass furniture constructions. Premium seating manufacturers in Italy and Germany are specifying these composites for stain-resistant bottom layers. This unifying architecture is compressing the traditional multi-supplier interlining stack into consolidated single-source contracts.
REACH Annex XVII restrictions on organophosphorus flame retardants are forcing reformulation of chemical binders across European furniture supply chains. Thermoplastic bonding via calendering is displacing urea-formaldehyde saturation in residential upholstery bound for EU markets. Italian and Polish converters are qualifying polypropylene-based thermal bond webs to maintain CE marking compliance.
Flat-pack furniture assemblers are consolidating vendor bases around suppliers capable of just-in-time roll slitting and custom width formatting. Direct partnerships with nonwoven mills are replacing layered distributor networks for large upholstery producers in Germany and the United States. This concentration is most visible in North American contract furniture, where mill-direct procurement now covers 60% of standardized interlining volume.
Nonwoven Furniture Construction Sheeting Market Segmentation
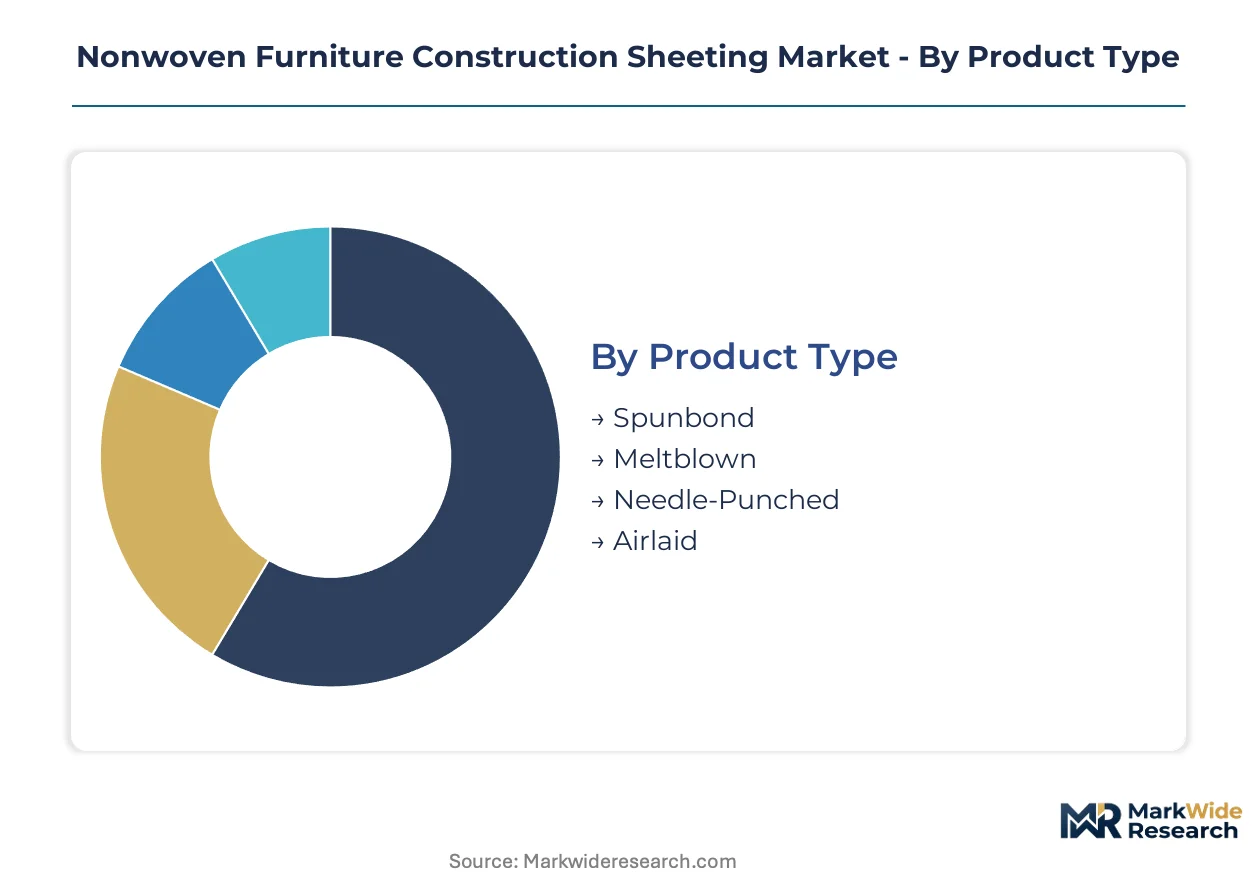
Nonwoven furniture construction sheeting serves distinct functional roles across manufacturing tiers, with product specifications varying sharply between high-volume cushioning applications and specialized acoustic or protective layers. Understanding how these segments concentrate supply and command margin premiums clarifies procurement strategy for furniture assemblers.
Product Type:
Supply concentration for nonwoven furniture sheeting clusters around thermal and mechanical bonding technologies, with distinct regional advantages shaping competitive positioning.
- Spunbond:Continuous filament polypropylene webs deliver tensile strength above 20 N/5cm in the machine direction, suiting high-throughput furniture lines. Guangdong and Zhejiang province manufacturers absorb the majority of Asian spunbond volume for export-grade seating production, driven by cost efficiency in automated cushioning lines.
- Needle-Punched:Mechanical entanglement of staple fibers creates dimensional stability and loft retention critical for premium seating above 80,000 cycle durability testing. Italian and German upholstery specialists specify these grades for contract furniture, where REACH-compliant thermoplastic bonding displaces legacy chemical saturation.
- Meltblown:Microfiber webs excel in acoustic absorption layers for open-plan office furniture, with fiber diameters below 5 microns enabling sound dampening in thin-profile constructions.
- Airlaid:Cellulose-synthetic blends offer absorbent padding for medical furniture applications, with fluff pulp cores providing fluid management in healthcare seating.
Spunbond absorbs the bulk of installed capacity; meltblown is expanding most quickly on acoustic specification tightening in North American contract furniture.
End User:
Cost tier differentiation separates commodity cushioning procurement from specification-driven medical and outdoor segments, with certification requirements determining supplier qualification timelines.
- Residential Furniture:Mass-market upholstery and bedding manufacturers drive volume procurement of 15-50 gsm interlining grades. Flat-pack assemblers in Germany and the United States are consolidating mill-direct relationships, compressing distributor margins on standardized roll formats.
- Office Furniture:Acoustic performance standards and fire resistance certifications dominate specification criteria. North American open-plan furniture producers are pulling SMS laminates for unified barrier-cushioning functions in seating and panel systems.
- Medical Furniture:Antimicrobial and fluid-resistant properties command premium positioning, with healthcare seating requiring compliance to institutional cleaning protocols.
- Outdoor Furniture:UV stabilization and moisture resistance specifications limit viable fiber and binder chemistries, constraining supplier pools for patio and marine seating applications.
Residential furniture absorbs the bulk of installed capacity; medical furniture is climbing the fastest on healthcare infrastructure expansion and infection control specification tightening.
Application:
Volume concentration in cushioning contrasts with margin capture in specialized protection and acoustic functions, where technical performance thresholds filter supplier participation.
- Cushioning:Bulk padding layers beneath visible upholstery surfaces constitute the largest application by tonnage, with spunbond and needle-punched grades competing on loft retention and compressive set performance.
- Upholstery:Interlining and backing layers require seam strength and dimensional stability, with thermal-bonded webs displacing woven scrims in cost-sensitive residential production.
- Protection:Dust and moisture barrier functions in storage and transit packaging favor SMS composite constructions, unifying multiple performance attributes in single-source supply contracts.
- Sound Absorption:Meltblown and high-loft needle-punched grades address open-plan acoustic standards, with office furniture specifications in North America and Europe driving qualification of specialized fiber blends.
Cushioning absorbs the bulk of installed capacity; sound absorption is gaining share fastest on workplace acoustic regulation convergence across multiple geographies.
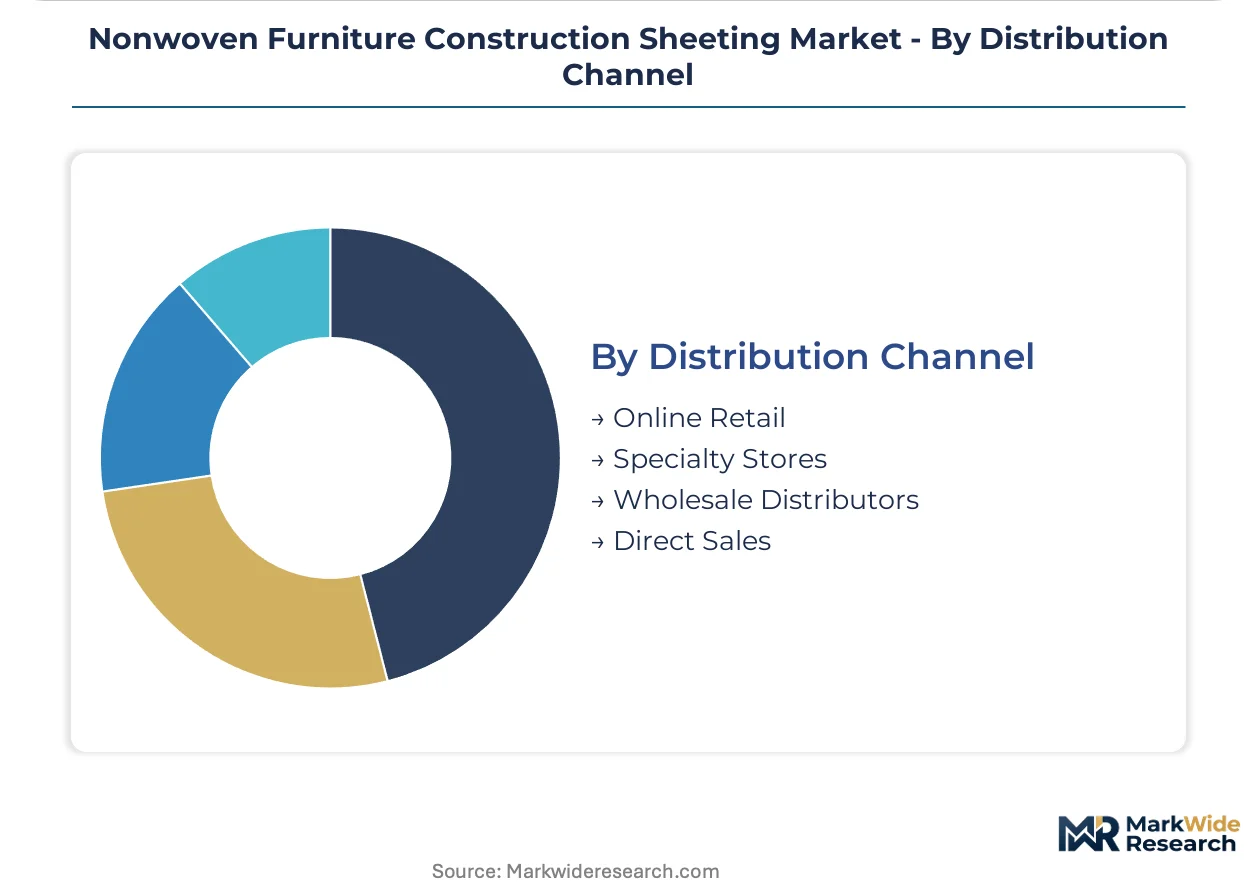
Distribution Channel:
Customer type and procurement scale determine channel selection, with large upholstery producers bypassing traditional distributor networks for direct mill relationships.
- Direct Sales:Mill-direct procurement now dominates standardized interlining for large furniture manufacturers in Germany and the United States, with custom width slitting and just-in-time delivery replacing inventory-heavy distributor relationships.
- Wholesale Distributors:Regional stockholding retains relevance for mid-tier assemblers requiring smaller lot sizes and technical support, particularly in Southeast Asian manufacturing clusters.
- Online Retail:Digital B2B marketplaces are emerging for standardized 15-50 gsm specifications, disintermediating regional distributors on price-transparent commodity grades.
- Specialty Stores:Technical nonwoven retailers serve prototype and custom furniture shops requiring rapid sampling and small-batch fulfillment.
Direct sales absorbs the bulk of installed capacity; online retail is expanding most quickly on procurement platform digitization and standardized specification commoditization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production clusters in coastal China supply the bulk of export-grade furniture sheeting, while consumption concentrates in North American and European assembly operations where flat-pack furniture manufacturers drive specification standards.
United States
Contract furniture manufacturers in North Carolina and Michigan specify SMS laminates for unified barrier-cushioning functions. The Consumer Product Safety Commission flammability framework and California's Bureau of Electronic and Appliance Repair testing queues extend qualification cycles for new fiber blends. Mill-direct procurement now dominates standardized interlining procurement for large upholstery producers.
Germany
Flat-pack assemblers in North Rhine-Westphalia consolidate vendor bases around suppliers capable of just-in-time roll slitting. REACH Annex XVII restrictions on organophosphorus flame retardants force reformulation of chemical binders across continental supply chains. Italian and Polish converters qualify polypropylene-based thermal bond webs to maintain CE marking compliance for German-bound production.
China
Furniture export manufacturing clusters in Guangdong and Zhejiang provinces drive bulk procurement of spunbond and needle-punched grades. The country's dual carbon goals and evolving GB standards reshape material specifications for domestic and export production. Spunbond volume concentrates in automated cushioning lines serving mass-market residential seating.
India
PLI scheme incentives for domestic upholstery production open bulk procurement channels for mid-weight spunbond grades. The Bureau of Indian Standards and DGFT frameworks govern import substitution and local content requirements for furniture components. Manufacturing investments concentrate in Gujarat and Maharashtra for regional supply to Southeast Asian export markets.
Italy
Premium seating manufacturers specify needle-punched grades for contract furniture above 80,000 cycle durability testing. ECHA limitations on halogenated flame retardants accelerate thermoplastic bonding adoption across Italian converter networks. Lombardy and Veneto host specialized upholstery clusters where REACH-compliant material qualification determines supplier selection.
Nonwoven Furniture Construction Sheeting Market Key Industry Players
The competitive structure tilts toward diversified material conglomerates with cross-sector nonwoven portfolios. Three tiers define participation: multinational chemical-fiber conglomerates with furniture-dedicated divisions, regional specialists in thermal or mechanical bonding technologies, and integrated textile converters with captive nonwoven capacity. Dominant competitive moves include geographic expansion through greenfield needle-punch capacity and strategic partnerships with flat-pack furniture assemblers for just-in-time supply contracts.
Within the multinational tier, Kimberly-Clark Corporation and Berry Global Inc. occupy positions anchored by broad hygiene and industrial nonwoven portfolios that extend into furniture applications. Freudenberg Performance Materials exemplifies the European manufacturing footprint archetype, supplying standardized roll formats from continental production bases. Toray Industries and Mitsui Chemicals represent the Asia-Pacific chemical conglomerate model, leveraging integrated fiber-to-fabric capabilities for regional furniture export supply chains.
| Leading Market Players |
|---|
| Kimberly-Clark Corporation |
| Freudenberg Performance Materials |
| Berry Global Inc. |
| Fitesa |
| Toray Industries |
| Mitsui Chemicals |
| PFNonwovens |
| Johns Manville |
| Glatfelter Corporation |
| Others |
Cost & Logistics Intelligence
Flat-pack furniture assemblers in Germany and the United States are consolidating mill-direct procurement relationships, forcing nonwoven suppliers to absorb distributor margin compression and standardize roll formats for just-in-time delivery.
Pricing Analysis
Cost-down pressure on commodity spunbond grades accelerates as petrochemical input volatility squeezes margin pools. Three-tier pricing structure across premium needle-punched, standard thermal-bond, and economy spunbond levels reflects certification grade and volume scale differentiation. Price erosion runs through residential upholstery segments where bulk procurement concentrates purchasing power. Medical furniture buyers exhibit lowest price sensitivity due to antimicrobial specification premiums and institutional compliance requirements.
Supply Chain Analysis
California Bureau of Electronic and Appliance Repair flammability certification queues gate supplier qualification timelines by 4-6 months. Manufacturing capacity clusters in China, Germany, and the United States, with raw material dependencies on polypropylene resin, polyester staple fiber, and bio-based binder chemistries. Single-point vulnerability concentrates in Zhejiang province needle-punch capacity for European flat-pack assemblers. Distribution runs through direct mill partnerships for large upholstery producers, with wholesale distributors retaining relevance for mid-tier assemblers requiring technical support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive positioning in nonwoven furniture sheeting is becoming a vertical-integration race as players pursue captive fiber production and direct mill relationships to defend margin pools against petrochemical volatility.
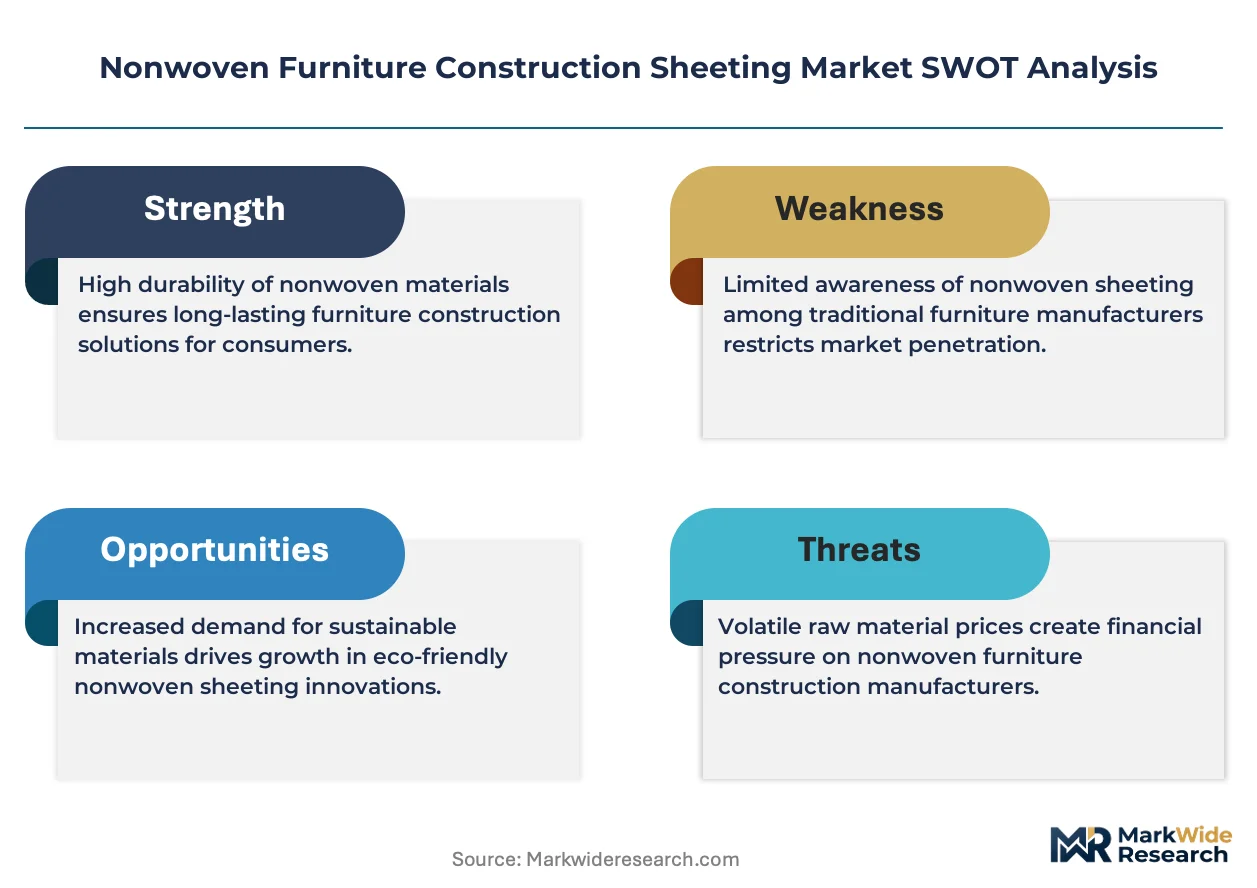
For Market Incumbents: To counter distributor disintermediation by digital B2B procurement platforms, backward integration into polypropylene fiber production secures input cost stability. Incumbents should anchor North American and European manufacturing footprints with just-in-time slitting capabilities for flat-pack assemblers, while accelerating REACH-compliant thermoplastic bonding qualification to maintain CE marking access. For New Entrants and Emerging Players: Launch via digital B2B marketplaces targeting standardized 15-50 gsm interlining specifications where price transparency commoditizes procurement. India presents the most penetrable geography given PLI scheme incentives for domestic upholstery production. Mid-weight spunbond grades for regional Southeast Asian export supply chains offer white-space entry with lower certification barriers than EU or US markets. For Investors and Strategic Acquirers: The window for entry favors specialized needle-punch operators with loft engineering expertise in aging European technician pools. Long-term viability hinges on bio-based binder convergence addressing EU Ecodesign circular material criteria. Watch pending state-level chemical disclosure laws in the US as an inflection indicator for thermoplastic bonding adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Production | Captive polypropylene supply insulates margin pools from crude oil index volatility. |
| REACH-Compliant Binder Reformulation | Thermoplastic bonding adoption maintains CE marking access for EU-bound production. |
| Just-in-Time Roll Slitting Capacity | Custom width formatting secures direct mill partnerships with flat-pack assemblers. |
| Digital B2B Marketplace Participation | Price-transparent platforms disintermediate regional distributors on commodity grades. |
| Bio-Based Material Qualification | Polylactic acid fiber webs address EU Ecodesign circular content requirements. |
Research Approach
Document review covered trade customs data, SEC 10-K filings, and ECHA regulatory submissions, complemented by interviews with nonwoven plant managers, furniture procurement leads at large upholstery producers, distribution channel partners, and technical R&D directors. Primary fieldwork across Guangdong, Zhejiang, North Rhine-Westphalia, and North Carolina manufacturing clusters was validated against secondary sources including GB standards documentation and Bureau of Indian Standards frameworks. Bottom-up volume modeling and top-down value triangulation anchored forecast construction.
Cross-referencing historical capacity expansion patterns against panel input from industry stakeholders shaped the analytical framework across the analysis window. Segmentation dimensions modeled include bonding technology, end-use furniture category, functional application layer, and procurement channel structure. CAGRs were derived from elasticity-adjusted demand projections incorporating petrochemical input cost trajectories and regulatory qualification timeline assumptions.
Petrochemical price volatility, REACH Annex XVII expansion scope, and China dual carbon policy implementation pace are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions on fiber substitution elasticities and flat-pack furniture growth trajectories. A model refresh is warranted upon material change in California flammability testing queue durations or EU Ecodesign circular content threshold adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nonwoven Materials
Non-Woven Glass Fiber Prepreg Market
Nonwoven Materials
Nonwoven Flanging Market
Nonwoven Materials
Airlaid Textile Market
Nonwoven Materials
Nonwoven Cleanroom Apparel Market
Nonwoven Materials
Non Woven Converting Machine Market
Nonwoven Materials
Global Non Woven Fabric Market
Nonwoven Materials
India Non-Woven Geotextiles Market
Nonwoven Materials
Global Melt-Blown Nonwovens Market
Nonwoven Materials
Nonwoven Blanket Market
Nonwoven Materials
Nonwoven Floor Covers Market
Nonwoven Materials
Nonwoven Sponges Market
Nonwoven Materials
HDPE Nonwoven Market
Nonwoven Materials
Staples PP Nonwovens Market
Nonwoven Materials
Barrier Nonwoven Fiber for Breathable Surgical Gowns Market
Nonwoven Materials
Global Wet Laid Nonwovens Market
Nonwoven Materials
Non Woven Printing Machine Market