
 Tape Stretching Line Market | 2026-2036
Tape Stretching Line Market Size, Share, and Industry Trends Forecast 2026-2036
Tape Stretching Line Market Analytics
China is reconfiguring regional supply dynamics as domestic converters expand film and tape capacity across the Yangtze River Delta. Reifenhäuser Group leverages its extrusion technology heritage to sustain premium positioning in high-speed biaxial lines. Windmöller & Hölscher Group anchors European demand through engineering-intensive mechanical stretching platforms. Lohia Group competes on cost-optimized monoaxial systems for emerging market packaging converters.
A tape stretching line is an industrial extrusion and orientation system that draws polymer films or tapes in one or more axial directions to enhance tensile strength, dimensional stability, and optical clarity, typically achieving draw ratios between four and ten times original gauge. The equipment serves primarily to manufacture substrate materials for pressure-sensitive adhesives, strapping tapes, and protective films used in logistics, electronics, and construction. Bi-axial stretching configurations command the dominant share of capital expenditure as converters prioritize balanced mechanical properties for heavy-duty packaging applications. Thermal stretching technology leads installed capacity due to its compatibility with polypropylene and polyester feedstocks, though mechanical stretching gains traction where energy recovery systems offset operating costs. Specialty tape applications attract the fastest-growing specification requirements as electronics manufacturers demand ultra-thin, low-shrinkback films for precision component mounting.
EMA and REACH frameworks in Europe enforce phthalate restrictions and substance-of-very-high-concern disclosures that shape raw material qualification timelines for tape substrate producers. FDA regulations in the United States govern indirect food-contact adhesives, creating compliance thresholds that determine market access for packaging-grade output. China's SAMR oversees national GB standards for plastic film mechanical performance, influencing domestic equipment specification sheets and export certification requirements. Stakeholders must monitor evolving dual carbon goals in China and EU Green Deal implementation timelines to calibrate capital deployment between thermal efficiency upgrades and feedstock transition pathways.
Market Dynamics
REACH compliance in Europe is tightening material purity requirements for adhesive tape substrates, forcing converters to requalify feedstock suppliers and stretching line configurations simultaneously. This regulatory compression is accelerating capital rotation toward equipment with integrated contamination detection and closed-loop thermal recovery systems.
Growth Catalysts
- Bi-axial stretching adoption:Heavy-duty packaging converters prioritize balanced mechanical properties for strapping tapes and protective films, driving specification upgrades from monoaxial legacy systems.
- China's dual carbon goals:Domestic machinery makers scale energy-efficient thermal stretching platforms to meet MEE emissions benchmarks while capturing regional flexible packaging demand.
- Electronics substrate specifications:Ultra-thin, low-shrinkback films for precision component mounting create pull for specialty tape applications with draw ratio precision above 8:1.
Market Restraints
- Feedstock volatility:Polypropylene and polyester resin price swings compress converter margins and delay stretching line procurement cycles in emerging markets.
- European supply concentration:REACH substance-of-very-high-concern disclosures extend raw material qualification timelines by 12-18 months for non-EU equipment suppliers.
- Mechanical stretching energy costs:High electricity intensity limits adoption in regions with grid instability or carbon-intensive power generation.
Strategic Opportunities
- India packaging expansion:BIS certification alignment and PLI scheme incentives attract capital deployment for cost-optimized monoaxial systems serving domestic e-commerce logistics.
- EU Green Deal thermal retrofits:Existing installed base replacement creates demand for heat recovery modules and electrification upgrades in Germany, Italy, and Poland.
- Digital twin integration:Convergence of extrusion process simulation with real-time draw ratio control enables predictive maintenance contracts and unbundled service revenue streams.
Industry Challenges
- Process control engineering scarcity:Specialized expertise in simultaneous biaxial orientation mechanics commands premium compensation and extends commissioning timelines.
- Legacy system integration:Retrofitting contamination detection and automated gauge control into 1990s-era thermal lines requires custom mechanical interfacing and voids OEM warranties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tape Stretching Line Market |
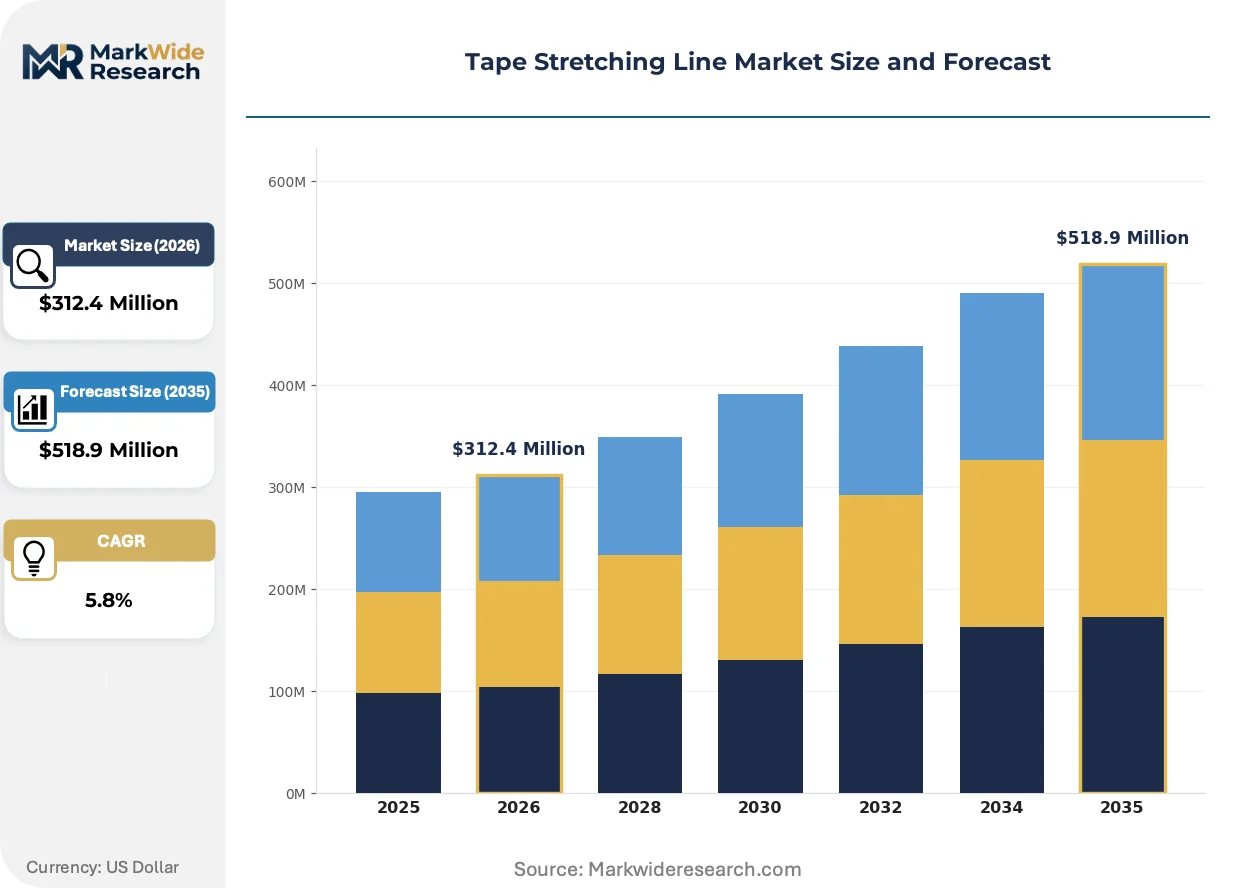
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoaxial Stretching, Bi-axial Stretching, Multiaxial Stretching, Hot Stretching Technology: Thermal Stretching, Mechanical Stretching, Chemical Stretching, Optical Stretching End User: Packaging Industry, Automotive Sector, Textile Industry, Electrical Industry Application: Pressure Sensitive Tapes, Adhesive Tapes, Protective Films, Specialty Tapes |
| Companies Covered | Reifenhäuser Group, Windmöller & Hölscher Group, Lohia Group, Yongming Machinery, Polystar Machinery, Cemach Machineries, Starlinger, Hao Yu Precision Machinery Industry, Heaven Extrusions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tape Stretching Line Market Evolving Landscape
Equipment architecture is fragmenting along energy recovery and precision control axes as converters face divergent regulatory and feedstock cost pressures across geographies. Three distinct trajectories are crystallizing in product development and procurement patterns.
Electrified thermal management is hybridizing conventional gas-fired stretching ovens with induction heating zones and exhaust-to-feedstock heat exchangers. German packaging converters operating high-output biaxial systems are piloting these configurations to satisfy EU Green Deal implementation timelines. The technology is compressing operating cost differentials between European and Asian production bases while extending equipment depreciation schedules.
REACH phthalate restrictions and SVHC disclosure mandates are forcing substrate producers to maintain blockchain-traceable feedstock documentation from resin pellet to finished tape. European adhesive tape manufacturers are absorbing compliance overhead through dedicated regulatory affairs functions and pre-qualified supplier panels. Electronics-grade output faces the tightest qualification windows as OEMs demand full material genealogy for precision component mounting films.
Converter procurement is consolidating around lifecycle cost models that unbundle capital expenditure from energy performance guarantees and aftermarket service contracts. Chinese flexible packaging specialists are negotiating throughput-based pricing with domestic machinery makers, shifting risk to equipment suppliers. This restructuring is most visible in the Yangtze River Delta where regional banks have developed specialized asset-backed lending products for stretching line acquisitions.
Tape Stretching Line Market Segmentation
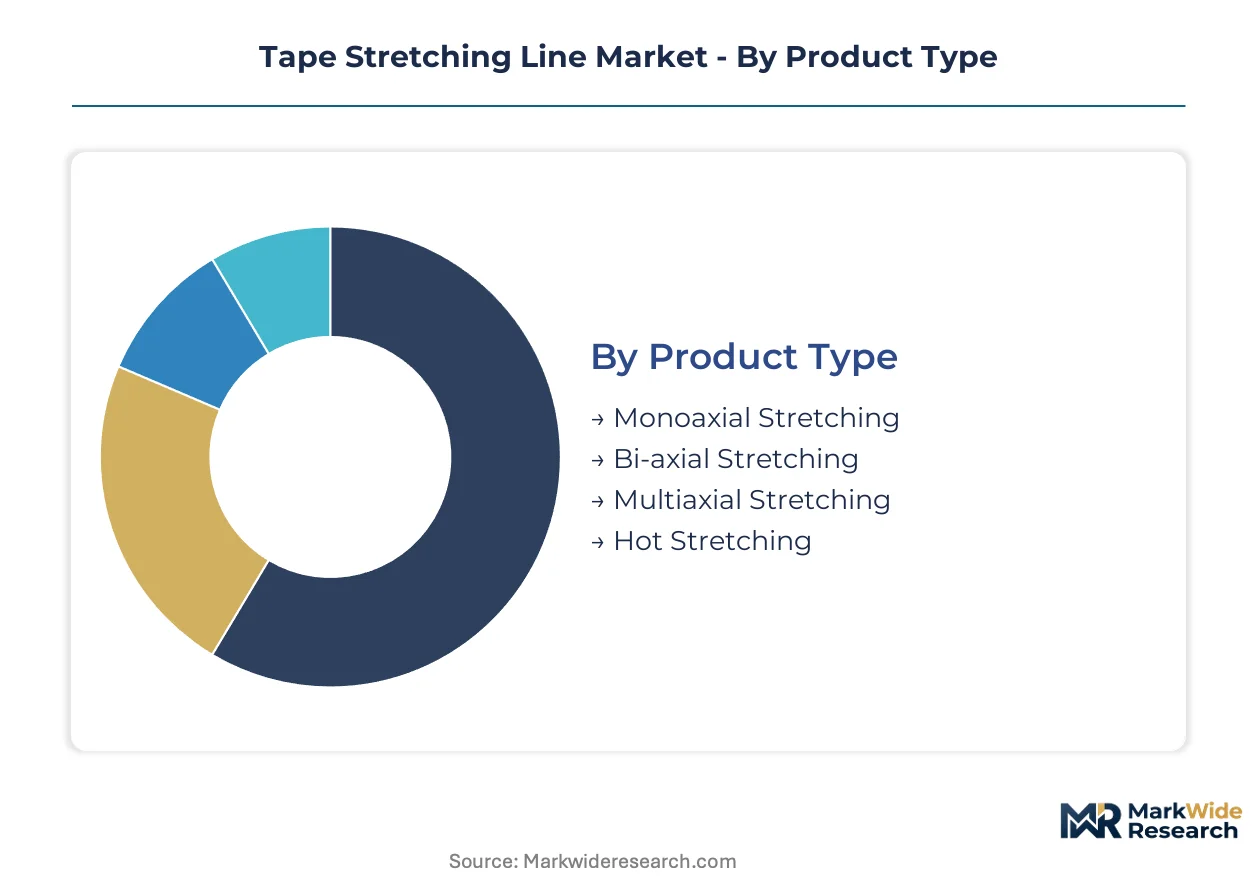
Stretching line procurement cycles vary dramatically by configuration complexity, with bi-axial systems requiring 18-24 month qualification timelines versus 6-9 months for monoaxial units. Understanding segment turnover velocity enables equipment suppliers to calibrate inventory, service deployment, and financing structures against converter capital planning rhythms.
Product Type:
Bi-axial systems command the longest sales cycles due to simultaneous orientation mechanics and precision gauge control requirements, while hot stretching platforms turn over fastest among thermal-dependent configurations.
- Bi-axial Stretching:Simultaneous machine-direction and transverse-direction orientation achieves balanced tensile properties through draw ratios exceeding 8:1. Heavy-duty packaging converters in Germany specify these systems for strapping tape substrates requiring isotropic strength distribution under pallet load stress.
- Monoaxial Stretching:Single-axis orientation draws polymer films in either machine or transverse direction, yielding asymmetric mechanical properties suited to linear stress applications. Emerging market converters in India prioritize these cost-optimized systems for e-commerce logistics tape volumes where unidirectional strength suffices.
- Multiaxial Stretching:Complex orientation in three or more axes serves aerospace composite prepregs and medical device substrates requiring isotropic performance.
- Hot Stretching:Elevated-temperature drawing above glass transition temperature enables high crystallinity in polypropylene strapping tapes.
Monoaxial systems dominate installed base across cost-sensitive packaging converters. Bi-axial configurations are where expansion concentrates for electronics-grade precision films.
Technology:
Capital deployment splits between energy-intensive thermal platforms with proven polypropylene compatibility and emerging mechanical systems where electricity costs and carbon intensity determine feasibility.
- Thermal Stretching:Gas-fired or electric radiant ovens heat polymer films above orientation temperature before controlled draw. Chinese flexible packaging converters in the Yangtze River Delta specify these systems to satisfy MEE emissions benchmarks while processing commodity polypropylene feedstocks.
- Mechanical Stretching:Direct roller friction generates orientation stress without external heating, enabling energy recovery through regenerative braking systems. German automotive tape suppliers pilot these configurations to align with EU Green Deal thermal efficiency mandates.
- Chemical Stretching:Solvent-induced plasticization reduces orientation temperature for heat-sensitive polymer blends.
- Optical Stretching:Laser-based localized heating enables micro-zone orientation control for display component films.
Thermal stretching retains dominant installed capacity across legacy packaging infrastructure. Mechanical platforms are expanding most quickly where grid decarbonization and energy cost hedging motivate converter investment.
End User:
Packaging converters drive replacement demand through 7-10 year depreciation cycles, while automotive qualification timelines extend to 15 years for adhesive tape substrate approvals.
- Packaging Industry:Flexible packaging and corrugated box sealing applications consume oriented polypropylene and polyester tapes at volumes scaling with e-commerce throughput. Regional converters across China's Yangtze River Delta are expanding capacity to capture domestic logistics demand.
- Electrical Industry:Insulation tapes, capacitor films, and battery separator substrates require ultra-thin gauge control with low shrinkback specifications. Japanese electronics OEMs impose material genealogy requirements that extend equipment qualification timelines.
- Automotive Sector:Wire harness wrapping and exterior protection films demand UV-stable oriented substrates.
- Textile Industry:Synthetic fiber precursor tapes and geotextile strips utilize lower-precision orientation systems.
Packaging Industry dominates installed base across commodity tape volumes. Electrical Industry applications are gaining share fastest as battery and display component specifications tighten.
Application:
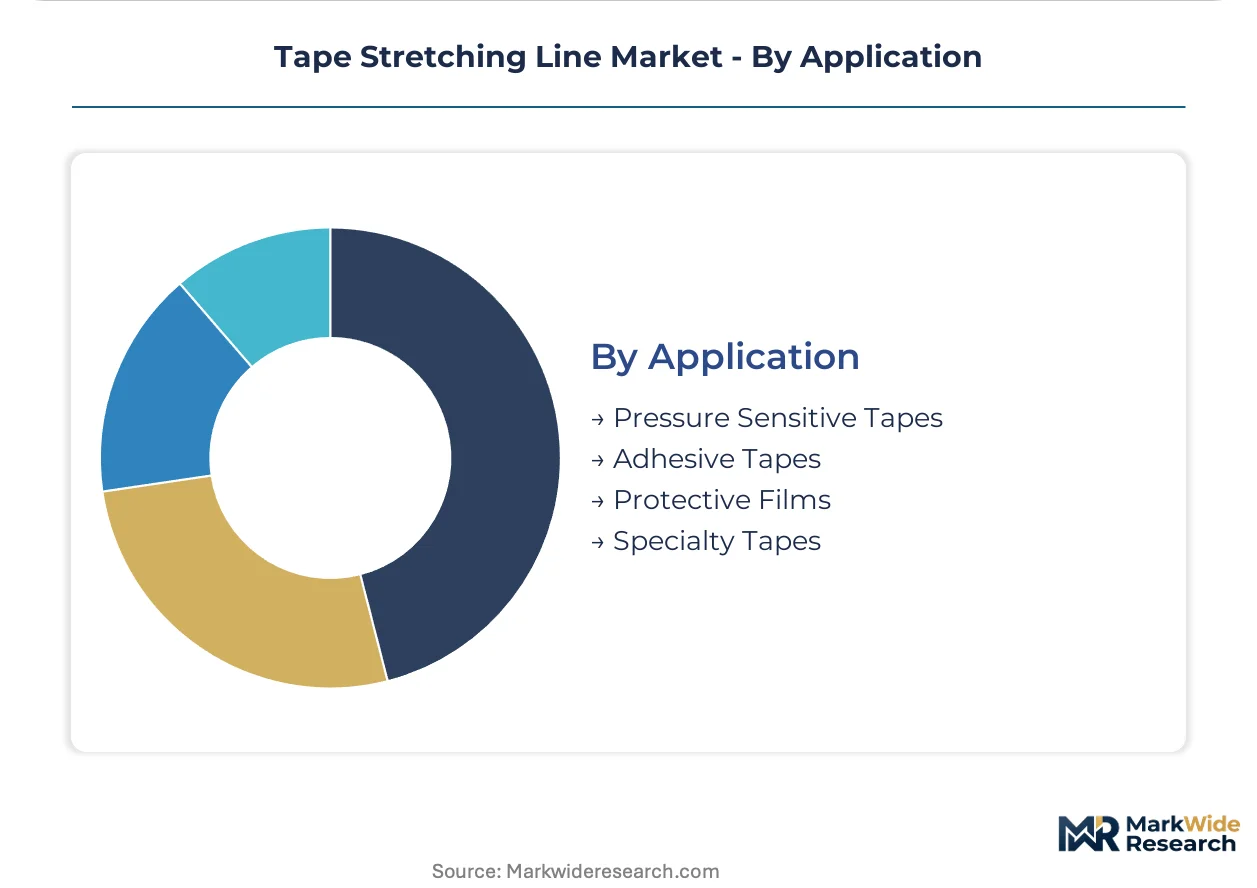
Adhesive tape substrates turn over on commodity resin cost cycles, while specialty tape applications require extended qualification for electronics and medical device integration.
- Adhesive Tapes:Pressure-sensitive adhesive substrates for carton sealing and industrial bonding represent standardized output with specification tolerance bands accommodating feedstock variation. Indian packaging converters under PLI scheme incentives are scaling monoaxial capacity for domestic e-commerce logistics.
- Specialty Tapes:Ultra-thin, low-shrinkback films for semiconductor component mounting and medical device fixation demand draw ratio precision above 8:1 with real-time gauge feedback. FDA indirect food-contact and EMA medical device regulations impose material purity thresholds that filter equipment supplier pools.
- Pressure Sensitive Tapes:Commodity office and consumer adhesive products with standardized release liner configurations.
- Protective Films:Temporary surface protection for electronics, automotive, and construction applications.
Adhesive Tapes dominate installed base across price-sensitive volume applications. Specialty Tapes represent the steepest expansion trajectory as precision component mounting specifications proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR's GB standards for plastic film mechanical performance shape equipment specification sheets across China's Yangtze River Delta. German converters under ECHA's REACH phthalate restrictions are requalifying feedstock suppliers and stretching line configurations simultaneously.
China
Domestic machinery makers scale capacity for regional flexible packaging converters expanding film and tape production across the Yangtze River Delta. MEE emissions benchmarks under dual carbon goals accelerate energy-efficient thermal stretching platform deployment. Regional banks in Shanghai and Jiangsu province have developed specialized asset-backed lending products for stretching line acquisitions.
Germany
Packaging Industry buyers are expanding orders for high-output biaxial systems serving strapping tape substrates under pallet load stress. ECHA's substance-of-very-high-concern disclosure mandates extend raw material qualification timelines for non-EU equipment suppliers. Industrial clusters in North Rhine-Westphalia pilot electrified thermal management configurations with induction heating zones to satisfy EU Green Deal implementation timelines.
India
E-commerce logistics volumes drive demand for cost-optimized monoaxial systems among domestic packaging converters. BIS certification alignment and PLI scheme incentives attract capital deployment for regional machinery acquisitions. Gujarat-based flexible packaging specialists negotiate throughput-based pricing with equipment suppliers, shifting operational risk to manufacturers.
United States
FDA regulations governing indirect food-contact adhesives create compliance thresholds determining market access for packaging-grade tape substrate output. Electronics manufacturers in California and Texas demand ultra-thin, low-shrinkback films for precision component mounting with full material genealogy documentation. Midwest automotive tape suppliers face extended qualification timelines stretching to fifteen years for substrate approvals.
Japan
Electronics OEMs impose material genealogy requirements that extend equipment qualification timelines for battery separator and capacitor film substrates. METI oversight of industrial efficiency standards influences thermal stretching platform specifications for polypropylene compatibility. Kansai region precision component manufacturers specify draw ratio precision above 8:1 with real-time gauge feedback systems.
Tape Stretching Line Market Competitive Landscape
Capability concentration sits with engineering-intensive mechanical stretching specialists; scale advantage sits with cost-optimized monoaxial fabricators serving emerging market volumes. The vendor base organizes around three strategic archetypes: European heritage extrusion technology houses, Asian domestic champions capturing regional flexible packaging demand, and mid-scale specialists competing on commissioning speed and aftermarket service density. Competitive moves center on geographic expansion through localized assembly partnerships and technology licensing arrangements that bypass capital-intensive greenfield establishment.
Among European heritage extrusion technology houses, Reifenhäuser Group GmbH and Windmöller & Hölscher Group occupy positions anchored by decades of mechanical stretching platform engineering. Lohia Group sits within the cost-optimized systems tier, exemplifying the Asian domestic champion archetype competing on monoaxial specification accessibility for emerging market converters.
| Leading Market Players |
|---|
| Reifenhäuser Group |
| Windmöller & Hölscher Group |
| Lohia Group |
| Yongming Machinery |
| Polystar Machinery |
| Cemach Machineries |
| Starlinger |
| Hao Yu Precision Machinery Industry |
| Heaven Extrusions |
| Others |
Value Network & Pricing Analysis
REACH substance-of-very-high-concern disclosure mandates compress pricing tier spreads between European and Asian equipment suppliers while simultaneously forcing feedstock requalification investments that reshape supply chain geography toward pre-certified supplier panels. Polypropylene resin price volatility transmits directly into converter procurement delays, amplifying the cost differential between thermal and mechanical stretching platforms across regional production bases.
Pricing Analysis
Equipment pricing spreads widest between German-engineered biaxial systems and Chinese monoaxial platforms, with premium-mid-economy pricing differentiation anchored by certification grade and after-sales service bundling. Price compression in the standard tier intensifies as domestic machinery makers in the Yangtze River Delta absorb margin pressure through throughput-based contract structures. Emerging market packaging converters exhibit highest price sensitivity, while electronics-grade specialty tape producers prioritize draw ratio precision over capital expenditure minimization.
Supply Chain Analysis
Contract manufacturing concentration for precision gauge control systems sits with German and Japanese automation specialists, while thermal oven fabrication centers on Chinese and Italian metalworking clusters. Polypropylene resin supply draws from Saudi Arabian and South Korean petrochemical complexes, with polyester feedstock anchored in China and Taiwan. Single-source vulnerability for high-precision orientation rollers threatens equipment delivery timelines. Distribution runs through regional machinery dealers with localized commissioning capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from feedstock cost cyclicality as polypropylene resin prices stabilize and converter capital planning resumes normal depreciation-driven replacement cadence.
For Market Incumbents: Entrench position through backward integration into precision roller manufacturing and captive heat exchanger production, countering emerging Chinese suppliers' cost advantages. Accelerate EU Green Deal-aligned thermal retrofit service contracts to lock in installed base replacement demand across German and Polish packaging clusters. For New Entrants and Emerging Players: India's Gujarat and Maharashtra industrial corridors represent the most penetrable entry point, where PLI scheme incentives and BIS certification gaps create procurement openness absent in saturated European markets. Pursue throughput-based pricing partnerships with regional banks' asset-backed lending programs to overcome converter capital constraints. For Investors and Strategic Acquirers: Engineering-intensive mechanical stretching specialists with proprietary draw ratio control algorithms offer the strongest long-term viability through the next capital equipment cycle. Monitor MEE emissions benchmark tightening as the signal to watch for accelerated thermal platform replacement demand in China's Yangtze River Delta.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Components | Captive roller manufacturing secures delivery timelines against German-Japanese supply bottlenecks. |
| EU Green Deal Thermal Retrofit Programs | Heat recovery module upgrades extend equipment depreciation schedules for German packaging converters. |
| Throughput-Based Pricing Contracts | Chinese machinery makers shift operational risk while capturing regional flexible packaging demand. |
| Digital Twin Integration | Real-time draw ratio control enables predictive maintenance revenue streams for aftermarket service. |
| Blockchain-Traceable Feedstock Documentation | REACH SVHC compliance creates supplier qualification barriers favoring integrated resin-tape producers. |
Research Methodology
Operator-level perspectives from extrusion line engineers, packaging converter procurement directors, aftermarket service technicians, and thermal systems R&D managers anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation against SAMR GB standard filings, ECHA REACH substance databases, MEE emissions disclosures, and customs trade records for polypropylene and polyester resin flows. Bottom-up equipment shipment tallies triangulated against top-down converter capacity expansion announcements.
Scenario-bracketing framed volume and value outputs across the analysis window, with segmentation modeling spanning stretching configuration type, technology platform, end-use industry vertical, and regional regulatory cluster. CAGRs derived from equipment replacement cycle analysis and feedstock cost elasticity modeling incorporated polypropylene price volatility indices and dual carbon policy implementation trajectories as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in resin commodity prices, euro-yuan exchange rates, or EU carbon border adjustment timelines would shift the trajectory. Quarterly review of MEE emissions enforcement intensity, ECHA SVHC candidate list updates, and Indian PLI scheme disbursement rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Pre-Printed Tape Market
Tapes
Release Tape Market
Tapes
Carton Sealing Tape Market
Tapes
Foil Tapes Market
Tapes
United States End-Of-Line Packaging Tape Market
Tapes
Double Sided Tape Market
Tapes
Paper Masking Tapes Market
Tapes
Reflective Tape Market
Tapes
Strapping Tapes Market
Tapes
Sterilization Indicator Tape Market
Tapes
Global Non Woven Tape Market
Tapes
Tape Dispenser Market
Tapes
Carry Handle Tape Market
Tapes
Seam Tapes Market
Tapes
Industrial Tapes Market
Tapes
Thermal Transfer Tapes Market