
 Memory Interface Chip Market | 2026-2036
Memory Interface Chip Market Size, Share, and Industry Trends Forecast 2026-2036
Memory Interface Chip Market Foresight
REACH compliance is hardening material sourcing requirements for memory interface chip vendors serving European OEMs. Montage Technology leverages its captive design capabilities across DDR and HBM controller portfolios. Rambus anchors its position through serial interface IP licensing that extends into data center interconnect standards. Samsung Electronics dominates advanced packaging roadmaps by integrating interface logic with its own DRAM fabrication.
A memory interface chip manages electrical signaling and protocol translation between memory devices and host processors, operating at speeds exceeding 6.4 GT/s in current DDR5 implementations while compensating for signal degradation across dense PCB layouts. The HBM product category commands premium positioning as AI training clusters require 8192-bit parallel interfaces with stacked die configurations. Serial technology segments attract R&D concentration from networking equipment vendors seeking pin-efficient solutions, while synchronous architectures remain the volume foundation across consumer computing applications.
The EPA governs hazardous substance thresholds in US-based semiconductor fabrication, while China's MIIT enforces GB standards on electromagnetic compatibility for domestically deployed server components. The EU AI Act's risk-classification framework for high-performance computing systems directly shapes memory interface certification requirements for European cloud provider procurement. Stakeholders must monitor how dual carbon goals in China and the EU Green Deal's embodied carbon tracking reshape foundry location decisions and interface chip sourcing strategies.
Market Dynamics
High-bandwidth memory interface architectures are compressing design cycles across AI accelerator platforms, forcing vendors to synchronize roadmaps with foundry process transitions and heterogeneous integration requirements.
Growth Catalysts
- AI Training Cluster Expansion:Hyperscale data centers in the United States are deploying HBM3E configurations that demand 8192-bit parallel interface controllers.
- REACH Compliance Hardening:European OEM procurement specifications now mandate full material disclosure for memory interface components entering data center infrastructure.
- Advanced Packaging Ecosystem Maturation:South Korea's concentration of 2.5D/3D interposer capacity is pulling interface logic design activity toward Seoul and Pyeongtaek clusters.
Market Restraints
- Advanced Substrate Cost Volatility:ABF substrate pricing fluctuations constrain margin expansion for high-layer-count memory interface packages.
- Foundry Concentration Risk:Leading-edge logic production for DDR5 PHYs concentrates at TSMC facilities in Taiwan, creating single-source exposure.
- Signal Integrity Limitations:PCB trace losses above 6.4 GT/s restrict channel reach without expensive retimer insertion.
Strategic Opportunities
- Automotive Edge AI Deployment:Germany's tier-one suppliers are qualifying GDDR6 interface chips for autonomous driving compute modules.
- EU AI Act Certification Services:Risk-classification frameworks for high-performance computing systems create advisory revenue streams around memory subsystem compliance.
- Chiplet Interoperability Standards:UCIe and BoW protocol convergence enables modular interface IP licensing across fabless design houses.
Industry Challenges
- SerDes Architecture Talent Scarcity:Mixed-signal design expertise for 112G PAM4 interfaces remains concentrated among a limited pool of specialists in Silicon Valley and Hsinchu.
- Multi-Die Thermal Management:Stacked HBM configurations generate localized hotspots that degrade interface timing margins and require iterative physical design iteration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Memory Interface Chip Market |
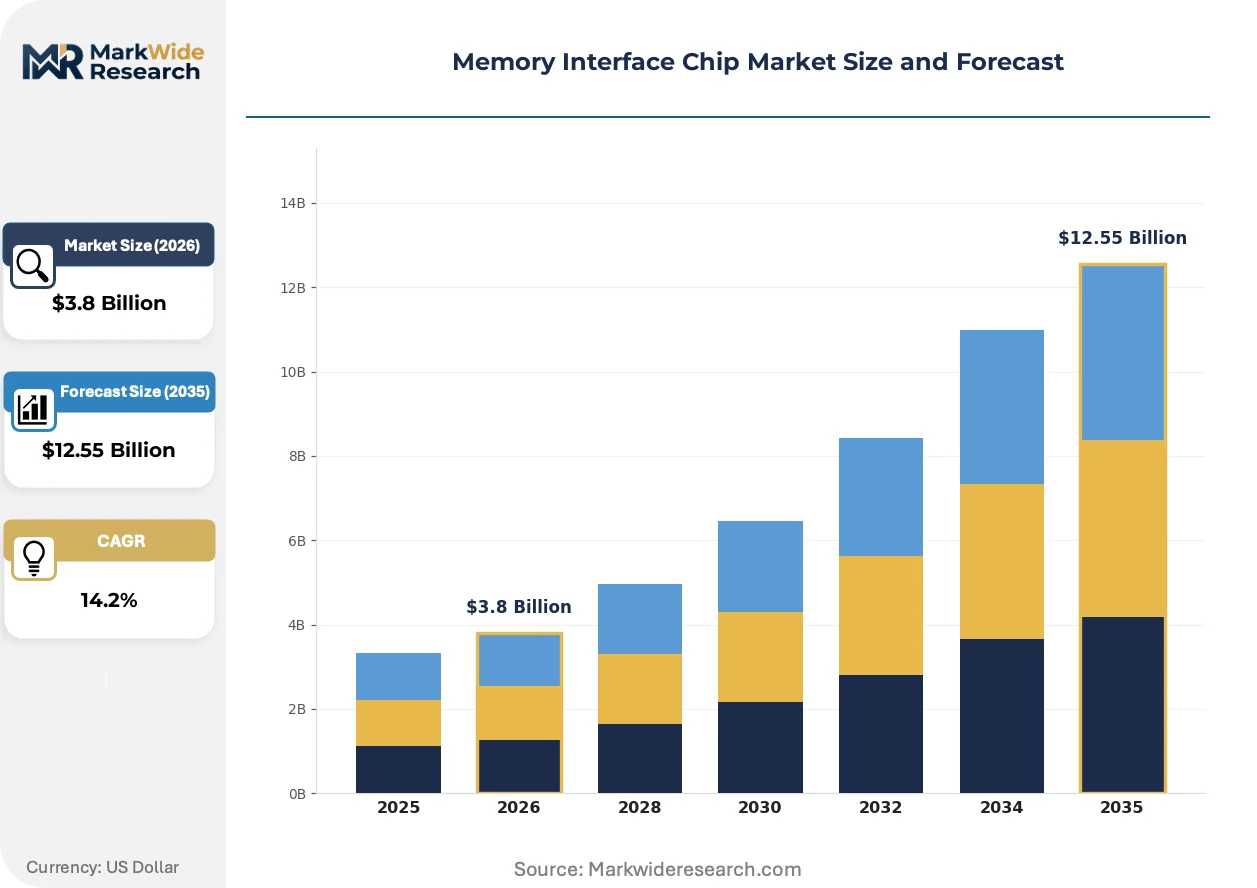
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DDR, GDDR, LPDDR, HBM Technology: Synchronous, Asynchronous, Serial, Parallel Application: Computing, Gaming, Networking, Consumer Electronics End User: OEMs, Data Centers, Cloud Providers, Telecommunication |
| Companies Covered | Montage Technology, Renesas Electronics, Rambus, Synopsys, SK hynix, Samsung Electronics, Micron Technology, Intel Corporation, Broadcom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Memory Interface Chip Market Shifts & Advancements
Serial interface architectures are compressing pin count requirements while protocol standardization accelerates interoperability testing across multi-vendor ecosystems.
HBM3E memory interface technology is overtaking GDDR-based solutions in AI training workloads. Cloud providers in the United States are transitioning accelerator card designs within 18-month procurement cycles. This shift is overtaking legacy discrete GPU memory architectures and consolidating purchasing power around vertically integrated HBM suppliers.
REACH substance restrictions are hardening material sourcing requirements for European-bound memory interface components. ECHA's candidate list expansion is forcing substrate laminate reformulation and flux chemistry substitution. Memory module assemblers in Germany and the Netherlands are now requiring full supply chain material declarations from interface chip vendors.
Specification-driven procurement is displacing incumbent supplier relationships in hyperscale data center memory subsystem sourcing. Cloud operators are mandating OCP-compliant DDR5 PMIC and interface component interoperability before volume qualification. This pattern is most visible in United States-based hyperscale buildouts, where procurement teams now prioritize open standards over proprietary controller IP.
Memory Interface Chip Market Segmentation
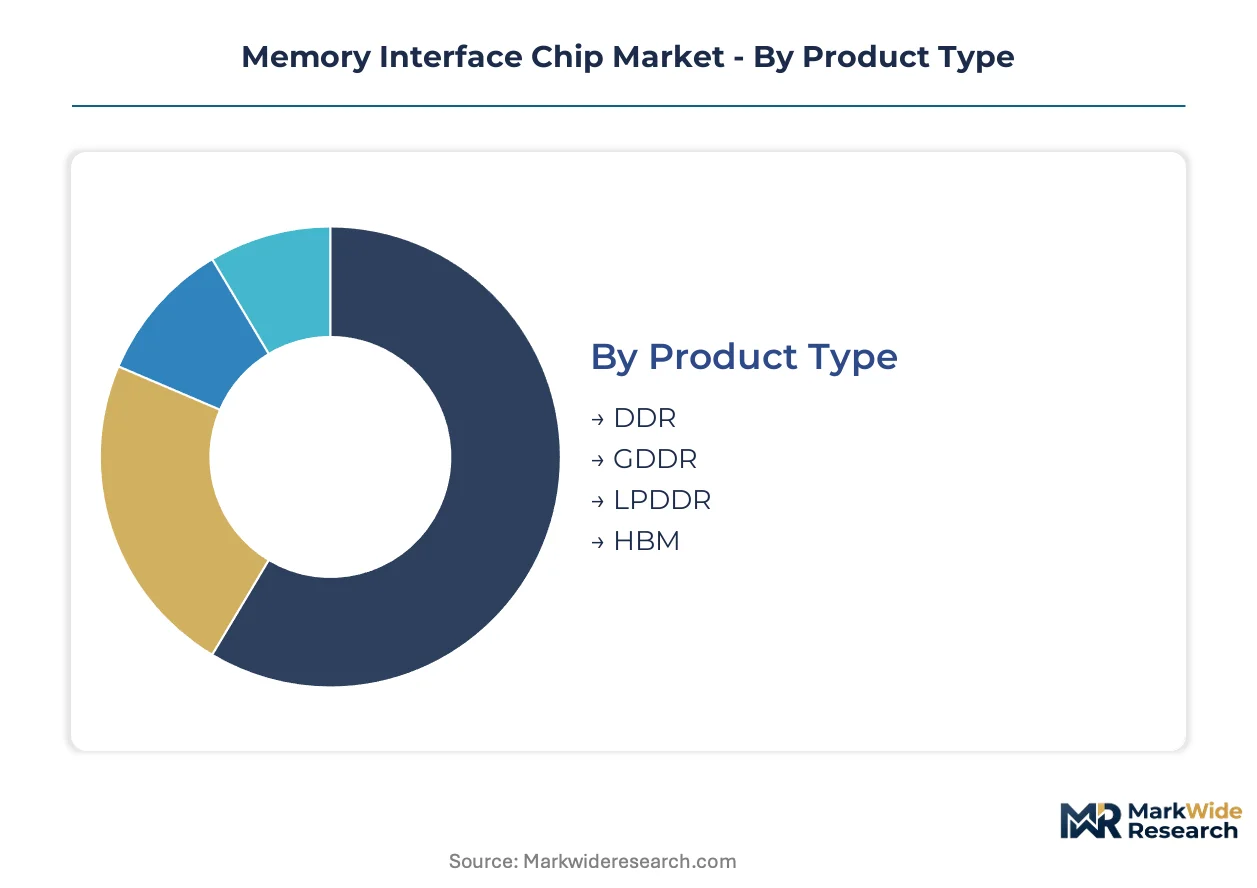
Memory interface chip segmentation reveals how supply-side specialization fragments across protocol standards, thermal constraints, and customer procurement power. Each dimension carries distinct margin profiles and qualification barriers that shape vendor positioning strategies.
Product Type:
Supply concentration for high-performance categories anchors in South Korean packaging ecosystems, while commodity segments distribute across Taiwanese and Chinese assembly networks.
- HBM:Stacked die configurations integrate 8192-bit parallel interfaces with through-silicon vias for AI training clusters. United States hyperscale data centers drive qualification timelines as cloud providers compress accelerator card refresh cycles to 18 months.
- DDR:Synchronous architectures operate at 6.4 GT/s in DDR5 implementations with signal compensation for dense PCB layouts. Computing OEMs in Taiwan and China constitute the volume foundation, though margin pressure intensifies from PMIC integration trends.
- GDDR:Graphics-oriented protocols target discrete GPU and automotive edge AI modules with higher per-pin bandwidth than DDR equivalents. Germany's tier-one suppliers are qualifying GDDR6 for autonomous driving compute.
- LPDDR:Low-power variants sacrifice peak bandwidth for thermal efficiency in mobile and thin-client form factors. Smartphone OEM procurement concentrates in Shenzhen and Seoul design centers.
HBM absorbs the bulk of installed capacity at leading-edge packaging facilities; LPDDR is expanding most quickly in automotive edge applications.
Technology:
Cost tier differentiation separates premium mixed-signal designs from standard digital implementations, with R&D intensity scaling directly with SerDes complexity.
- Serial:Pin-efficient architectures employ 112G PAM4 signaling for data center interconnect standards. Networking equipment vendors in San Jose and Hsinchu concentrate R&D investment as channel reach requirements extend beyond PCB trace limitations.
- Parallel:Wide-bus configurations dominate HBM and DDR implementations where latency tolerance is minimal. AI accelerator platforms in the United States and China pull interface logic toward 2.5D interposer integration.
- Synchronous:Clock-aligned protocols retain volume dominance across consumer computing with mature IP licensing ecosystems. PC motherboard vendors in Dongguan and Taoyuan constitute the procurement core.
- Asynchronous:Self-timed circuits address metastability risks in multi-clock-domain systems with reduced power overhead. Niche adoption concentrates in aerospace and industrial control applications with extended qualification horizons.
Parallel interfaces command the highest wafer allocation at advanced foundry nodes; serial architectures are climbing the fastest in networking equipment attach rates.
Application:
Volume concentration in computing creates procurement scale advantages, while emerging segments impose divergent thermal and reliability specifications.
- Computing:Server and workstation platforms integrate DDR5 PHYs with retimer chains for signal integrity extension. United States enterprise OEMs mandate OCP-compliant interoperability before volume qualification.
- Networking:Switch and router designs prioritize pin efficiency through serial interface adoption with 56G and 112G lane rates. Cisco and Arista procurement specifications influence PHY IP roadmap prioritization.
- Gaming:Discrete GPU configurations leverage GDDR6X and emerging GDDR7 for texture bandwidth expansion. Add-in-board assemblers in Suzhou and Taipei manage qualification cycles tied to NVIDIA and AMD launch cadences.
- Consumer Electronics:Set-top boxes and smart displays employ LPDDR derivatives with aggressive cost targets. White-label manufacturers in Shenzhen drive consolidation around integrated PMIC-interface combo solutions.
Computing applications anchor foundry capacity allocation; networking is gaining share fastest in 112G SerDes qualification pipelines.
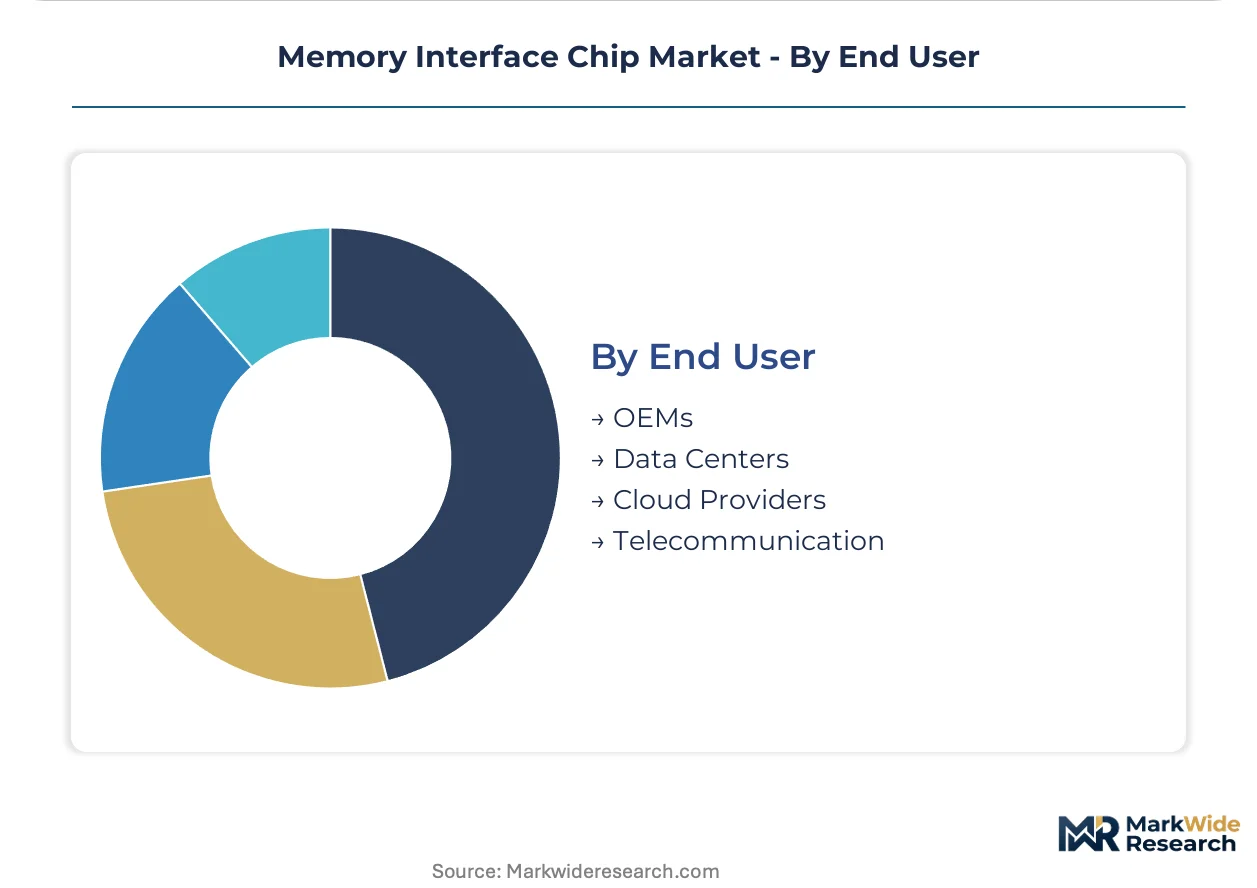
End User:
Customer type determines pricing leverage, with cloud provider consolidation shifting procurement power toward specification-driven sourcing.
- Cloud Providers:Hyperscale operators in the United States mandate open standards compliance and direct foundry relationships for HBM3E configurations. AWS, Google, and Microsoft procurement teams now prioritize OCP-aligned component interoperability over proprietary controller IP.
- Data Centers:Enterprise colocation and edge facilities balance performance requirements with extended depreciation schedules. European operators face EU AI Act risk-classification mandates that lengthen memory subsystem certification timelines.
- OEMs:Branded server and PC manufacturers manage multi-source strategies across DDR5 PHY suppliers. Taiwanese ODMs in Taoyuan and Kunshan intermediate between chip vendors and downstream system assembly.
- Telecommunication:5G baseband and fronthaul equipment require extended temperature grade interfaces with supply continuity guarantees. Huawei and Ericsson qualification programs in Shenzhen and Stockholm impose multi-year roadmap visibility requirements.
Cloud providers command the dominant share of HBM wafer starts; telecommunication infrastructure is expanding most quickly in extended-temperature grade demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pyongtaek's semiconductor cluster anchors advanced packaging capacity, drawing interface logic design toward South Korean tax-incentive zones. Seoul's concentration of 2.5D/3D interposer foundries reshapes foundry location decisions. San Jose and Hsinchu retain SerDes talent pools for 112G PAM4 development.
United States
Hyperscale data centers in Virginia and Oregon compress accelerator card refresh cycles to 18 months. EPA hazardous substance thresholds govern fabrication facility permitting in Arizona and Texas. Cloud provider procurement teams in Seattle and San Francisco mandate OCP-compliant interoperability before volume qualification.
South Korea
Samsung Electronics and SK hynix anchor HBM3E demand through vertically integrated DRAM fabrication. The Ministry of Trade, Industry and Energy channels R&D tax credits toward advanced packaging research consortia. Pyongtaek and Yongin clusters concentrate 2.5D interposer capacity for AI training cluster supply.
China
Domestic server OEMs in Shenzhen and Beijing accelerate DDR5 PHY localization under dual carbon goals. MIIT enforces GB electromagnetic compatibility standards on data center component deployments. Yangtze Memory Technologies and domestic foundries in Shanghai and Hefei expand captive interface controller production.
Germany
Tier-one automotive suppliers in Stuttgart and Munich qualify GDDR6 interface chips for autonomous driving compute modules. ECHA REACH substance restrictions harden material disclosure requirements for memory subsystem vendors. Dresden's silicon cluster attracts packaging investment for European-bound HBM configurations.
Taiwan
TSMC facilities in Hsinchu and Tainan concentrate leading-edge logic production for DDR5 PHYs, creating single-source exposure. The National Development Council subsidizes advanced packaging research through the Taiwan Chip-based Industrial Innovation Program. Taoyuan ODMs intermediate between interface chip vendors and downstream system assembly.
Memory Interface Chip Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across protocol standard and application boundaries. Market structure concentrates around vertically integrated memory fabricators, fabless IP licensors, and captive design houses serving modular ecosystems. Three archetypes dominate: IDMs controlling advanced packaging roadmaps, IP licensing specialists monetizing serial interface standards, and fabless controller vendors synchronizing with foundry process transitions. Competitive moves center on heterogeneous integration partnerships and open-standards compliance certification.
Among vertically integrated fabricators, Samsung Electronics and SK hynix exemplify the IDM archetype through captive DRAM and interface logic production. Montage Technology occupies a position within the fabless specialist tier, leveraging design capabilities across DDR and HBM controller portfolios. Rambus anchors the IP licensing vector, extending serial interface positions into data center interconnect standards.
| Leading Market Players |
|---|
| Montage Technology |
| Renesas Electronics |
| Rambus |
| Synopsys |
| SK hynix |
| Samsung Electronics |
| Micron Technology |
| Intel Corporation |
| Broadcom |
| Others |
Supply & Pricing Matrix
HBM3E process transitions to 2.5D interposer integration are compressing cost structures while concentrating wafer allocation at Pyeongtaek packaging facilities, simultaneously reshaping supplier economics and procurement leverage for United States hyperscale operators.
Pricing Analysis
Lead-time-driven pricing stratification rewards expedited delivery with substantial premiums while spot inventory liquidations clear excess ABF substrate capacity at discounted levels. Contract-based long-term offtake agreements dominate HBM configurations, with price differentiation hinging on OCP certification tier and volume scale commitments. Cost compression in DDR5 PHY segments is intensifying because PMIC integration trends eliminate discrete controller sockets. White-label manufacturers in Shenzhen exhibit the highest price sensitivity, whereas cloud providers in Seattle and San Francisco prioritize specification compliance over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with TSMC's Hsinchu and Tainan foundries for leading-edge DDR5 PHY logic production. Geographic supply concentration spans Taiwan, South Korea, and the United States, with raw material dependencies centering on ABF substrate laminates, high-purity copper foils, and advanced flux chemistries. Tariff exposure on semiconductor fabrication equipment imported into China threatens expansion timelines for domestic packaging facilities. Distribution runs through Taiwanese ODMs in Taoyuan and Kunshan, which intermediate between fabless interface chip vendors and downstream server assembly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
HBM3E architectures are displacing GDDR-based memory subsystems in AI training clusters, compressing technology transition windows and forcing synchronized roadmap decisions across the vendor ecosystem.
For Market Incumbents: To counter specification-driven procurement by United States hyperscale operators, Samsung Electronics and SK hynix should deepen backward integration into captive 2.5D interposer capacity at Pyeongtaek, while Rambus must accelerate UCIe protocol certification investments to defend serial interface licensing positions against open-standard alternatives. For New Entrants and Emerging Players: European automotive tier-one suppliers in Stuttgart and Munich represent an underserved buyer archetype seeking GDDR6 interface chips qualified for autonomous driving compute modules. New entrants should target Germany's REACH-compliant component procurement specifications as a differentiated entry pathway, leveraging advisory services around EU AI Act risk-classification compliance to bypass incumbent relationships. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by vertically integrated memory fabricators seeking to fill controller IP gaps. Long-term viability favors fabless specialists with validated HBM3E PHY designs and established foundry relationships at TSMC. Investors should monitor OCP-compliant interoperability certification timelines as the critical inflection signal for procurement power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| HBM3E PHY IP Licensing Expansion | Rambus and Synopsys monetize serial interface positions into data center interconnect standards. |
| 2.5D Interposer Capacity Buildout | Samsung Electronics anchors advanced packaging roadmaps through captive DRAM fabrication integration. |
| EU AI Act Certification Services | Montage Technology captures advisory revenue streams around memory subsystem compliance mandates. |
| Automotive Edge AI Qualification | German tier-one suppliers drive GDDR6 interface chip adoption for autonomous driving compute modules. |
| UCIe Protocol Convergence Investment | Chiplet interoperability standards enable modular interface IP licensing across fabless design houses. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with semiconductor packaging engineers, hyperscale procurement officers, foundry account managers, and automotive platform architects combined with secondary validation from SEC 10-K disclosures, MIIT GB standard publications, and ECHA REACH candidate list updates. Bottom-up wafer start estimates and top-down memory subsystem attach rate projections were triangulated to cross-verify volume assumptions.
Segment-level modeling operated at protocol standard, thermal constraint, and customer procurement power granularity across the projection horizon. Analytical frameworks incorporated technology transition curves for HBM3E adoption, foundry process node migration timelines, and heterogeneous integration partnership formations. CAGRs were derived from installed capacity trajectories at Pyeongtaek packaging facilities and hyperscaler accelerator card refresh cycle compression patterns.
Revisions become necessary when EPA hazardous substance thresholds tighten, EU AI Act risk-classification frameworks expand, or TSMC foundry allocation priorities shift toward alternative logic categories. Forecasts reflect documented assumptions regarding interposer yield rates, substrate laminate availability, and SerDes architecture talent pool constraints. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Memory Chips
Japan DRAM Market
Memory Chips
In-Memory Grid Market
Memory Chips
Smartphone Memory Chip Market
Memory Chips
Static RAM Market
Memory Chips
Automotive DRAM Market
Memory Chips
Memory Market
Memory Chips
ECC Memory Market
Memory Chips
Static Random-Access Memory (SRAM) Market
Memory Chips
Nano RAM Market
Memory Chips
In-Memory Computing Market
Memory Chips
Memristor Market
Memory Chips
Magneto Resistive RAM (MRAM) Market
Memory Chips
Global Dynamic Random Access Memory (DRAM) Market
Memory Chips
Graphics DDR SDRAM Market
Memory Chips
Memory Module Market
Memory Chips
MRAM Market