
 Global Bleaching Agents Market | 2026-2036
Global Bleaching Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bleaching Agents Market Foresight
Buyer concentration among water treatment facilities is expanding as municipal utilities consolidate procurement across regional networks. Kemira leverages its integrated chlorine dioxide supply chain to serve these consolidated buyers directly. Solvay anchors European hydrogen peroxide capacity through its Antwerp manufacturing complex. Nouryon competes on peracetic acid formulations tailored to food-contact sanitation standards.
Bleaching agents are oxidizing chemicals formulated to remove color, whiten substrates, or sterilize surfaces through electron-transfer reactions with chromophores; hydrogen peroxide decomposes to water and oxygen at concentrations between 3% and 70% by weight, making it the workhorse for textile and pulp delignification. Sodium hypochlorite dominates household and municipal water treatment applications due to its low cost and broad microbial efficacy, though peracetic acid gains share in food and beverage processing where chlorine residuals are restricted. Powder and granular forms command premium positioning in industrial laundries and textile manufacturing where precise dosing and transport stability reduce operational waste.
The EPA regulates disinfectant efficacy claims under FIFRA while the EU ECHA enforces REACH registration for active substances exceeding one tonne per year, forcing reformulation of legacy chlorine-based products. China's MEE implements discharge standards for adsorbable organic halogens in pulp mill effluent, redirecting capital toward peroxide bleaching sequences. Stakeholders must monitor regulatory divergence between peracetic acid approvals in North America and chlorine dioxide restrictions in European surface water catchments.
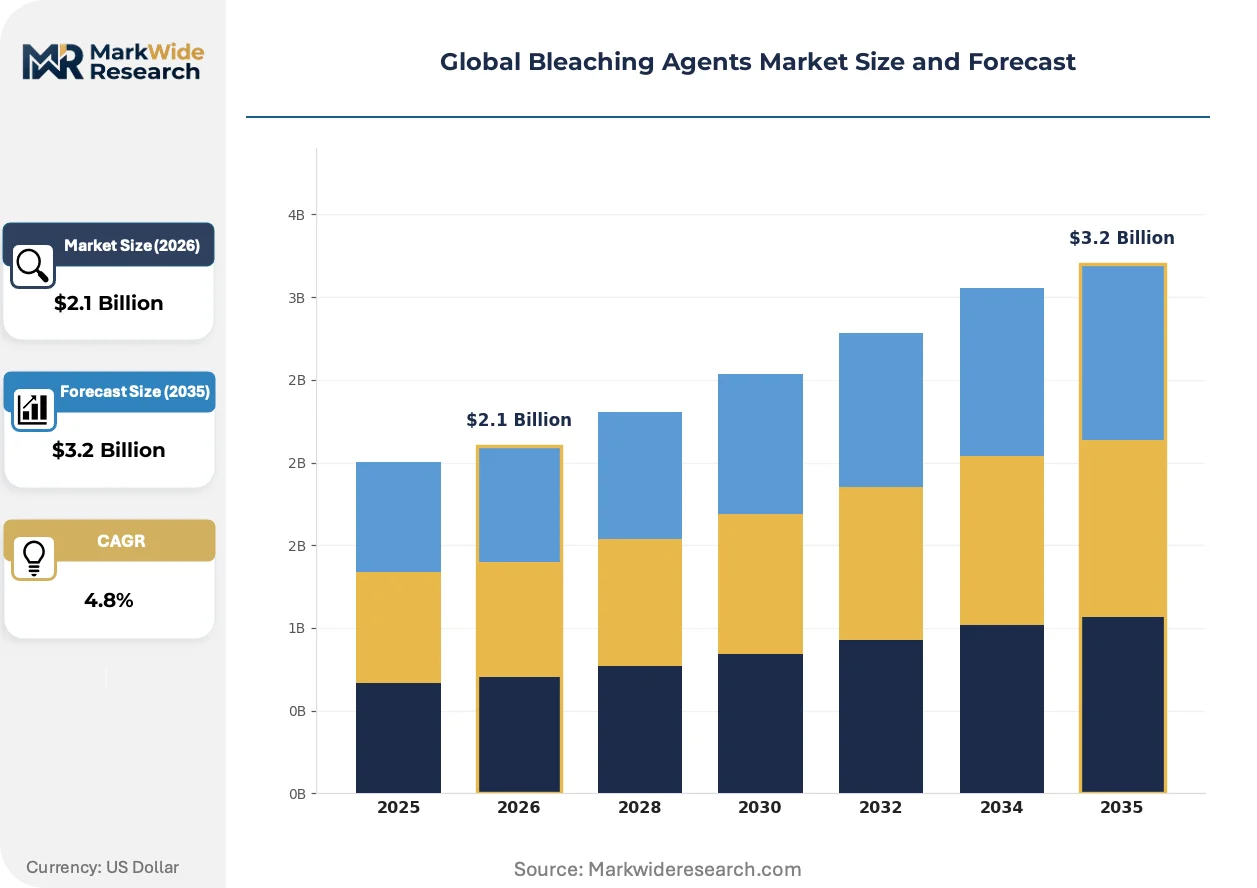
Market Dynamics
EU F-Gas Regulation phase-down schedules are compressing chlorine dioxide availability across European pulp mills, forcing accelerated migration toward peroxide-based bleaching sequences and rewiring supplier-customer contracting structures.
Growth Catalysts
- Pulp mill effluent mandates:China's MEE discharge standards for adsorbable organic halogens redirect capital spending toward peroxide bleaching in Shandong and Jiangsu provinces.
- Food-contact sanitation rules:Peracetic acid gains substitution share where chlorine residuals face restriction in beverage bottling and dairy processing lines.
- Textile processing scale-up:Capacity expansion across Vietnam and Bangladesh dye houses sustains hydrogen peroxide offtake for cotton preparation and denim finishing.
Market Restraints
- Anthracite coke input volatility:Sodium chlorate production costs fluctuate with energy-intensive electrochemical processing feedstock pricing.
- Antwerp supply concentration:European hydrogen peroxide capacity clusters at a single coastal complex, exposing buyers to port logistics disruption.
- AOX formation limits:Chlorine dioxide faces technical ceiling in elemental-chlorine-free bleaching sequences for premium paper grades.
Strategic Opportunities
- Indonesian pulp greenfield projects:New mill construction in Sumatra and Kalimantan creates demand for closed-loop peroxide systems without legacy chlorine infrastructure.
- EU Green Deal industrial decarbonization:Carbon border adjustment mechanisms incentivize low-emission bleaching agent selection in export-oriented mills.
- Precision dosing hardware convergence:Integration of solid percarbonate tablets with IoT-enabled dispensing equipment opens industrial laundry service contracts.
Industry Challenges
- Process safety certification timelines:Hazardous chemical handling permits for concentrated peroxide storage delay facility commissioning by 8-14 months in regulated jurisdictions.
- Legacy chlor-alkali integration:Chlorine dioxide producers face stranded asset risk as paper mills accelerate multi-year conversion timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bleaching Agents Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.2 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Hypochlorite, Hydrogen Peroxide, Calcium Hypochlorite, Chlorine Dioxide, Peracetic Acid, Others Form: Liquid, Powder, Granular, Gel, Tablet Application: Textile, Paper & Pulp, Water Treatment, Household, Personal Care End User: Laundry Services, Water Treatment Facilities, Textile Manufacturers, Cleaning Companies |
| Companies Covered | Kemira, AkzoNobel, Evonik Industries, Christeyns, Arkema, Solvay, Nouryon, Mitsubishi Gas Chemical Company, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bleaching Agents Market Shifts & Advancements
Active chemistry substitution, regulatory chemistry restrictions, and procurement consolidation are compressing traditional supply arrangements while opening white space for formulation specialists and integrated service providers.
Enzymatic pre-treatment technology is modularizing bleaching sequences by enabling partial lignin removal prior to chemical oxidation stages. Scandinavian pulp mills deploy cellulase and xylanase systems to reduce peroxide consumption by 15-25% in hardwood kraft lines. This biological-chemical hybrid approach is modularizing capital deployment and allowing tier-two producers to match brightness specifications without full sequence rebuilds.
REACH registration requirements for active substances exceeding one tonne annually are tightening documentation burdens on chlorine-based legacy formulations. ECHA enforcement has triggered reformulation costs exceeding EUR 500,000 per substance for mid-sized suppliers. Specialty paper segments in Germany and Finland are responding by qualifying peracetic acid alternatives ahead of authorization sunset dates.
Water treatment utilities are consolidating procurement across regional networks and unbundling chemical supply from equipment service contracts. Municipal buyers in the US Great Lakes region now issue multi-year framework agreements covering sodium hypochlorite, dosing systems, and residual monitoring as separate lots. This purchasing model shift is most visible in Ohio and Michigan, where regional water authority mergers have reduced supplier counts by 40% since 2022.
Global Bleaching Agents Market Segmentation
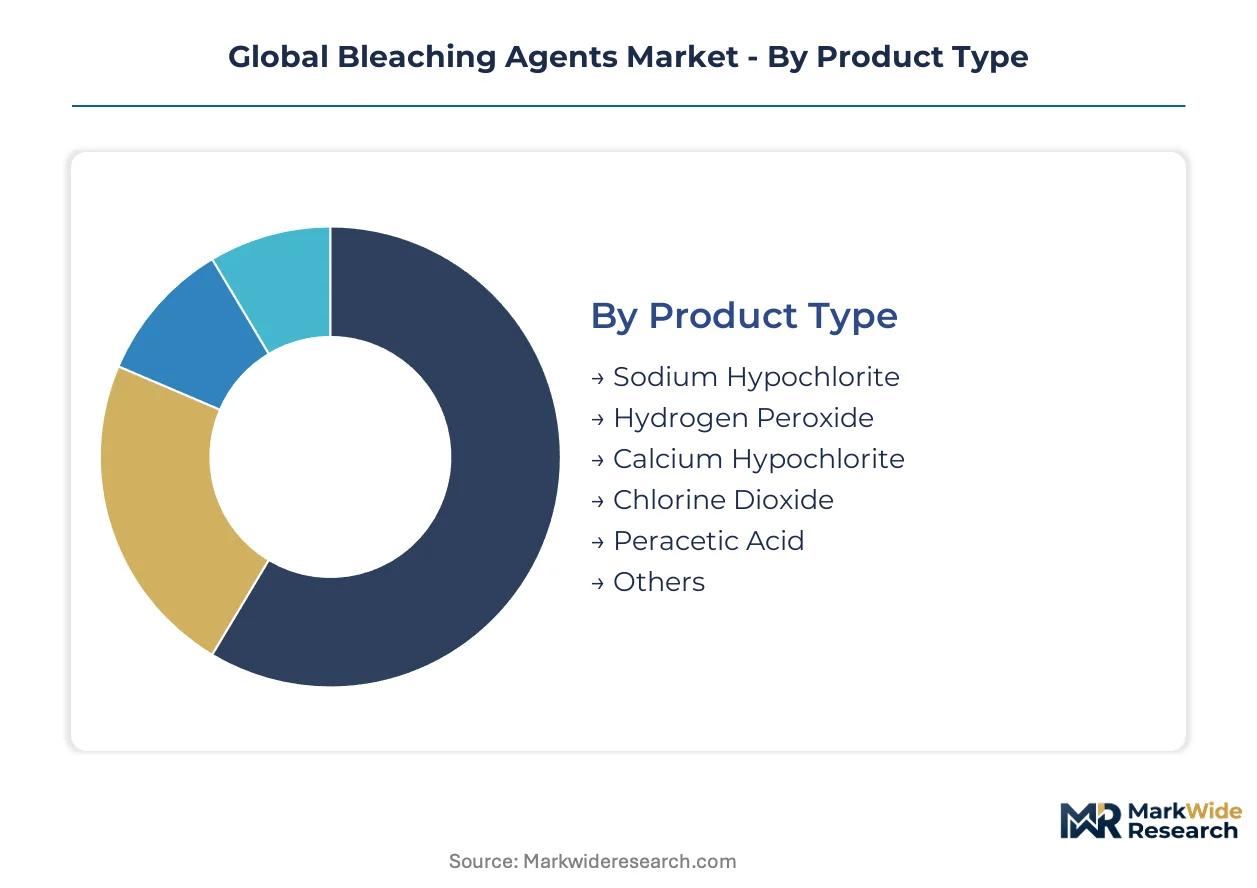
Bleaching agent procurement hinges on oxidation strength, substrate compatibility, and discharge compliance rather than price alone. Buyers sequence formulations across multi-stage processes where substitution costs cascade through downstream operations. Segmentation reveals how technical specifications fragment demand across industrial, municipal, and consumer channels.
Product Type:
Buyers select oxidizers based on redox potential, decomposition byproducts, and regulatory authorization for specific discharge environments.
- Hydrogen Peroxide:Decomposes to water and oxygen without chlorinated residuals, making it the default for elemental-chlorine-free pulp bleaching sequences in Shandong province mills. China's MEE adsorbable organic halogen limits are redirecting capital spending toward peroxide systems in hardwood kraft lines.
- Sodium Hypochlorite:Manufactured on-site via chlor-alkali electrolysis or delivered as bulk solution for municipal water disinfection. Consolidated procurement across Ohio and Michigan regional water authorities favors long-term hypochlorite framework agreements bundled with dosing infrastructure.
- Chlorine Dioxide:Generated via sodium chlorate reduction for lignin-selective delignification without carbohydrate degradation. EU F-Gas Regulation phase-down schedules are compressing availability across European pulp mills.
- Peracetic Acid:Equilibrium mixture of acetic acid and hydrogen peroxide approved for food-contact surfaces where chlorine residuals face restriction. German and Finnish specialty paper producers are qualifying formulations ahead of REACH authorization sunsets.
- Calcium Hypochlorite:Solid form with higher available chlorine concentration than sodium variants, suited to remote water treatment facilities lacking bulk liquid logistics.
- Others:Sodium percarbonate and perborate compounds serving consumer laundry applications and institutional cleaning where powder stability simplifies transport.
Hydrogen peroxide leads on scale; peracetic acid leads on momentum.
Form:
Physical state determines transport economics, dosing precision, and storage safety requirements across buyer segments.
- Liquid:Dominates industrial consumption where continuous flow systems enable automated injection into pulp stock and textile processing lines. Bulk tanker delivery minimizes packaging waste for high-volume consumers.
- Powder:Percarbonate and perborate formulations command premium positioning in industrial laundries where precise dosing reduces operational waste.
- Granular:Calcium hypochlorite granules serve remote municipal water treatment facilities with intermittent demand patterns and limited chemical handling infrastructure.
- Gel:Thickened formulations cling to vertical surfaces in food processing sanitation protocols, extending contact time for biofilm removal.
- Tablet:Solid percarbonate tablets integrated with IoT-enabled dispensing equipment are opening industrial laundry service contracts through usage-based pricing models.
Liquid forms dominate volume throughput; tablet formats are gaining share fastest in service-contract channels.
Application:
End-use specifications for brightness, sterility, or residual limits dictate formulation selection and sequence design.
- Paper & Pulp:Kraft mills deploy multi-stage bleaching sequences combining oxygen delignification, ozone, and peroxide stages to meet brightness targets without elemental chlorine. Scandinavian producers deploy enzymatic pre-treatment to reduce peroxide consumption by 15-25%.
- Textile:Cotton preparation and denim finishing in Vietnam and Bangladesh dye houses sustain hydrogen peroxide offtake for scouring and bleaching operations.
- Water Treatment:Municipal utilities consolidate procurement across regional networks, unbundling chemical supply from equipment service contracts in the US Great Lakes region.
- Household:Consumer laundry and surface disinfection applications favor sodium hypochlorite and percarbonate formulations with established retail distribution.
- Personal Care:Tooth whitening and hair bleaching applications require cosmetic-grade hydrogen peroxide with heavy metal limits below industrial specifications.
Paper and pulp represents the largest volume sink; textile processing in Southeast Asia shows the steepest expansion trajectory.
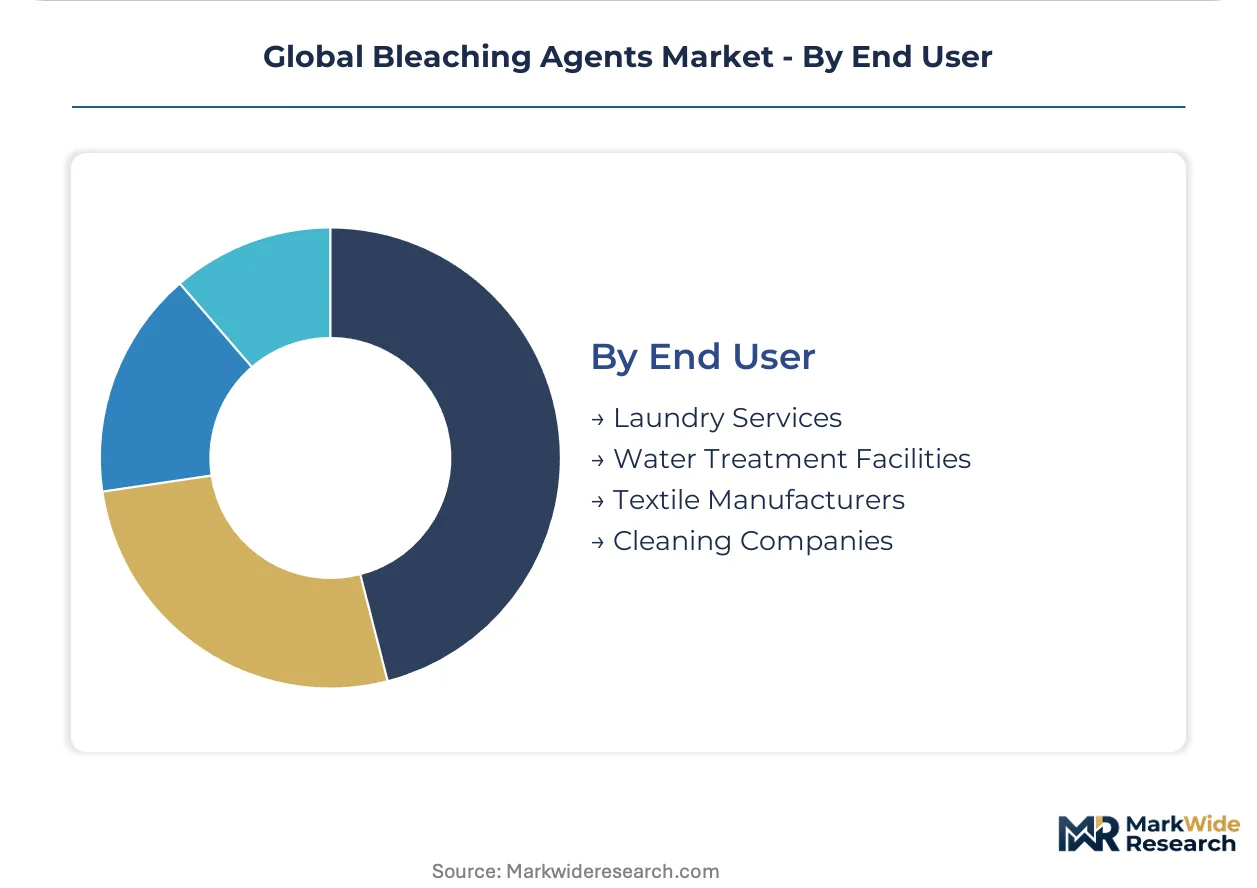
End User:
Operational scale and regulatory exposure differentiate procurement behavior across buyer categories.
- Water Treatment Facilities:Regional utility mergers in Ohio and Michigan have reduced supplier counts by 40% since 2022, favoring multi-year framework agreements.
- Textile Manufacturers:Capacity expansion across Vietnam and Bangladesh sustains oxidizer demand for cotton preparation and finishing operations.
- Laundry Services:Industrial and institutional laundries favor powder and tablet forms for transport stability and precise dosing control.
- Cleaning Companies:Contract sanitation providers select peracetic acid where food-contact approvals outweigh chlorine cost advantages.
Water treatment facilities concentrate procurement volume; textile manufacturers in Southeast Asia are expanding capacity most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's pulp mill capacity expansion outpaces European regulatory contraction, while Southeast Asian textile processing clusters absorb peroxide volumes redirected from mature markets.
China
Shandong and Jiangsu province mills drive hydrogen peroxide consumption as MEE discharge standards for adsorbable organic halogens mandate elemental-chlorine-free bleaching sequences. The Ministry of Ecology and Environment enforces AOX limits that redirect capital spending toward peroxide systems. Qingdao and Nantong industrial zones host hardwood kraft lines completing multi-year conversion timelines.
United States
Regional water authority mergers in Ohio and Michigan consolidate sodium hypochlorite procurement across municipal networks. EPA FIFRA regulations govern disinfectant efficacy claims while permitting frameworks for concentrated peroxide storage delay facility commissioning. Great Lakes utilities now unbundle chemical supply from equipment service contracts, reducing supplier counts by 40 percent since 2022.
Germany
Specialty paper producers in Bavaria and North Rhine-Westphalia qualify peracetic acid alternatives ahead of REACH authorization sunsets for legacy chlorine-based formulations. ECHA enforcement triggers reformulation costs exceeding EUR 500,000 per substance. The Antwerp-Rotterdam chemical cluster anchors European hydrogen peroxide capacity, exposing buyers to port logistics concentration risk.
Indonesia
Greenfield pulp mill construction in Sumatra and Kalimantan creates demand for closed-loop peroxide systems without legacy chlorine infrastructure. The Ministry of Environment and Forestry implements industrial discharge standards that favor peroxide bleaching in new mill designs. Medan and Pontianak processing zones attract capital avoiding stranded asset risk from chlor-alkali integration.
Vietnam
Textile dye house capacity expansion in Binh Duong and Dong Nai provinces sustains hydrogen peroxide offtake for cotton preparation and denim finishing. The Ministry of Natural Resources and Environment tightens effluent standards for textile processing zones. Ho Chi Minh City industrial parks host finishing operations scaling oxidizer consumption for export-oriented garment manufacturing.
Global Bleaching Agents Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation, equipment integration, and regional service density vectors. The vendor base organizes into three tiers: integrated chemical-electrochemical producers controlling chlorate and peroxide supply chains; formulation specialists tailoring peracetic acid and percarbonate blends for food-contact and textile applications; and equipment-chemical bundled service providers capturing municipal water treatment consolidation. Dominant competitive moves include backward integration into sodium chlorate electrochemical processing and geographic expansion through regional distribution joint ventures.
Among European chemical conglomerates, Solvay anchors hydrogen peroxide capacity through its coastal manufacturing position, while Nouryon occupies the specialty formulation tier with peracetic acid expertise. Kemira represents the integrated service model, leveraging chlorine dioxide supply chain control to serve consolidated municipal buyers directly. These three exemplify how competitive positioning fragments across upstream chemical production, midstream formulation customization, and downstream equipment-chemical bundling.
| Leading Market Players |
|---|
| Kemira |
| AkzoNobel |
| Evonik Industries |
| Christeyns |
| Arkema |
| Solvay |
| Nouryon |
| Mitsubishi Gas Chemical Company |
| BASF SE |
| Others |
Supply & Pricing Matrix
Anthracite coke input costs cascade through sodium chlorate electrochemical processing into chlorine dioxide price floors, while hydrogen peroxide contract structures in Antwerp-Rotterdam cluster buyers into long-term offtake agreements that buffer spot volatility.
Pricing Analysis
Capacity additions in China's Shandong province are reshaping price floors for industrial-grade hydrogen peroxide, compressing regional premiums that European suppliers commanded under legacy chlorine dioxide dependencies. Three-tier pricing structure across food-contact certified, industrial standard, and economy bulk grades separates pharmaceutical-grade peroxide from textile processing variants. Cost compression in European chlorine dioxide runs through EU F-Gas Regulation phase-down schedules, which constrain supply availability. Municipal water treatment facilities in Ohio and Michigan exhibit highest price sensitivity due to consolidated procurement frameworks, while specialty paper mills in Germany show lowest sensitivity where REACH compliance costs dominate substitution decisions.
Supply Chain Analysis
Empty peroxide tanker returns from Vietnamese textile dye houses to Chinese production hubs create backhaul optimization opportunities that reduce effective logistics costs for circular routing. Supply concentrates in Belgium, China, and the United States, with the Antwerp complex anchoring European hydrogen peroxide capacity. Sodium chlorate electrochemical processing draws from anthracite coke and electricity inputs, while peracetic acid formulations rest on acetic acid and hydrogen peroxide feedstocks. Single-source vulnerability concentrates at the Antwerp coastal complex, where port disruption would cascade through European pulp mill supply. Distribution runs through bulk tanker delivery for industrial consumers, with packaged formats serving remote municipal facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in bleaching agents hinges on enzymatic pre-treatment adoption that reduces peroxide consumption by 15-25%, allowing suppliers to capture value from chemical savings rather than volume tonnage.
For Market Incumbents: Lock in multi-year framework agreements with consolidated Great Lakes municipal utilities before regional procurement unbundling completes. Secure captive sodium chlorate capacity through backward integration into electrochemical processing, defending against stranded asset risk as paper mills accelerate chlorine dioxide conversion timelines. Prioritize REACH registration completion for peracetic acid formulations ahead of authorization sunsets. For New Entrants and Emerging Players: Begin with Indonesian greenfield pulp projects in Sumatra and Kalimantan, where absence of legacy chlorine infrastructure creates demand for closed-loop peroxide systems without incumbent equipment lock-in. Target precision dosing hardware convergence for industrial laundry service contracts, where IoT-enabled percarbonate tablet dispensing opens usage-based pricing models unavailable to bulk chemical suppliers. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-sized European formulation specialists face EUR 500,000-plus REACH registration burdens without scale economies to absorb compliance costs. Five-to-ten year viability favors suppliers with integrated chlorate-peroxide supply chains and regional service density in Southeast Asian textile processing clusters. Monitor EU carbon border adjustment mechanism implementation as inflection indicator for low-emission bleaching agent premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sodium Chlorate | Captive electrochemical capacity insulates chlorine dioxide producers from anthracite coke volatility. |
| Enzymatic Pre-treatment Partnerships | Cellulase and xylanase alliances with Scandinavian pulp mills reduce peroxide consumption and deepen supplier relationships. |
| Precision Dosing Hardware Convergence | IoT-enabled percarbonate tablet systems capture industrial laundry service contracts through usage-based pricing. |
| Indonesian Greenfield Mill Supply Agreements | Closed-loop peroxide system contracts in Sumatra avoid stranded asset risk from chlor-alkali legacy infrastructure. |
| REACH Registration Acceleration | Early peracetic acid qualification ahead of authorization sunsets secures German and Finnish specialty paper demand. |
Research Methodology
Coverage spans China, the United States, Germany, Indonesia, and Vietnam, with primary inputs from each market through structured interviews with pulp mill operations managers, municipal water procurement leads, textile dye house technical directors, and chemical distribution channel partners. Secondary validation draws from MEE discharge standard filings, EU ECHA REACH registration databases, US EPA FIFRA efficacy submissions, and pulp industry trade association capacity reports. Bottom-up demand modeling triangulates against top-down chemical production capacity assessments.
Granularity-level modeling disaggregates volume and value across product type, physical form, application segment, and end-user category throughout the projection horizon. Hydrogen peroxide, sodium hypochlorite, chlorine dioxide, peracetic acid, and calcium hypochlorite chemistries were modeled separately with grade-tier differentiation. CAGRs derive from regression analysis against pulp and paper capacity expansion, textile processing growth, and municipal water treatment consolidation patterns. Forecast inputs include enzymatic pre-treatment adoption curves and regulatory phase-down schedules.
Several conditions sit outside the modeled scope, including sudden feedstock price shocks, unanticipated regulatory acceleration, and breakthrough non-oxidative bleaching technologies. Forecasts reflect documented assumptions about technology substitution rates and regional enforcement consistency. Practitioners should monitor EU F-Gas Regulation implementation pace and Chinese MEE AOX limit expansion for early signals of demand redirection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Cold Phosphating Chemicals Market
Chemicals
Methoprene Market
Chemicals
Chemical Distribution Market
Chemicals
Neopentyl Polyhydric Alcohol Market
Chemicals
Calcium Borate Market
Chemicals
Dimethylaminopropylamine (DMAPA) Market
Chemicals
Hexamine Market
Chemicals
Hydrogen Chloride Market
Chemicals
Calcium Hydride Market
Chemicals
Fluorine Derivatives Market
Chemicals
Guaiazulene Market
Chemicals
Europe Biguanide Market
Chemicals
Isooctyl Alcohol Market
Chemicals
Global Butanediol Market
Chemicals
1, 4 Butanediol Market
Chemicals
Mercuric Chloride Market