
 Catenary Maintenance Vehicle Market | 2026-2036
Catenary Maintenance Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Catenary Maintenance Vehicle Market Outlook
The catenary maintenance vehicle market is decoupling between premium electrified platforms and legacy diesel-based units as railroad operators prioritize uptime reliability. CRCC High-Tech Equipment dominates Asia-Pacific rail infrastructure contracts through in-house production of integrated inspection systems. New Sorema Ferroviaria leverages Italian engineering heritage to anchor European demand for multi-function overhead line repair vehicles. Hilton Kommunal GmbH competes in German-speaking markets with specialized utility configurations for municipal tram networks.
Catenary maintenance vehicles are self-propelled or towed rail-mounted machines engineered to inspect, repair, and replace overhead contact systems at working heights exceeding seven meters, utilizing insulated telescopic booms and pantograph-compatible diagnostic arrays. The primary purpose is ensuring continuous electrical contact between locomotive pantographs and overhead catenary wires across electrified rail corridors. Power Source segmentation shows battery-operated configurations capturing margin pools as operators face escalating diesel emissions restrictions, while Vehicle Type demand tilts toward integrated power maintenance vehicles that combine inspection and repair functions. Application segmentation reveals overhead line work generating the fastest growth as aging copper-silver contact wire networks require proactive replacement cycles.
EU railway interoperability standards under ERA mandate standardized catenary geometry tolerances, compelling fleet upgrades among maintenance contractors seeking cross-border certification. China's NMPA and MIIT jointly enforce GB standards for rail-mounted electrical equipment, shaping product design requirements for manufacturers targeting domestic high-speed networks. Stakeholders must monitor evolving battery-electric platform endurance specifications as operators weigh total cost of ownership against overnight charging infrastructure investments.
Market Dynamics
Railway electrification mandates across Europe and Asia are forcing operators to retire diesel-based maintenance fleets faster than replacement supply can scale, creating a structural capacity gap that battery-electric platform manufacturers are racing to fill.
Growth Catalysts
- EU Railway Safety Directives:Mandated overhead line inspection frequencies under ERA interoperability standards compel maintenance contractors to expand electrified fleet capacity.
- China's High-Speed Rail Corridors:NMPA and MIIT joint enforcement of GB standards for rail-mounted electrical equipment drives domestic procurement volume for integrated inspection systems.
- Copper-Silver Contact Wire Replacement Cycles:Aging overhead line networks across Germany's urban rail transit systems generate sustained demand for proactive maintenance scheduling.
Market Restraints
- Lithium-Ion Battery Cost Volatility:Raw material price swings for cathode minerals constrain total cost of ownership calculations for battery-electric platform operators.
- Specialized Component Supply Concentration:Insulated telescopic boom manufacturing clusters in Central Europe create single-source vulnerability for pantograph-compatible diagnostic arrays.
- Overnight Charging Infrastructure Gaps:Depot electrification timelines lag vehicle procurement cycles, limiting operational deployment flexibility for maintenance contractors.
Strategic Opportunities
- India's Dedicated Freight Corridors:Electrification of 2,843 route kilometers under the Ministry of Railways creates untapped demand for self-propelled overhead line repair vehicles.
- Modular Battery Swapping Architectures:Convergence of standardized battery form factors with automated exchange systems enables continuous operation without depot charging delays.
- EU Green Deal Procurement Incentives:Carbon footprint scoring in public tender evaluations advantages zero-emission maintenance platforms over legacy diesel units.
Industry Challenges
- High-Voltage Certification Bottlenecks:ERA cross-border competency requirements for technicians working above 25kV extend workforce deployment timelines.
- Legacy Fleet Integration Complexity:Pantograph diagnostic arrays from third-party suppliers require custom software bridging to existing maintenance management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Catenary Maintenance Vehicle Market |
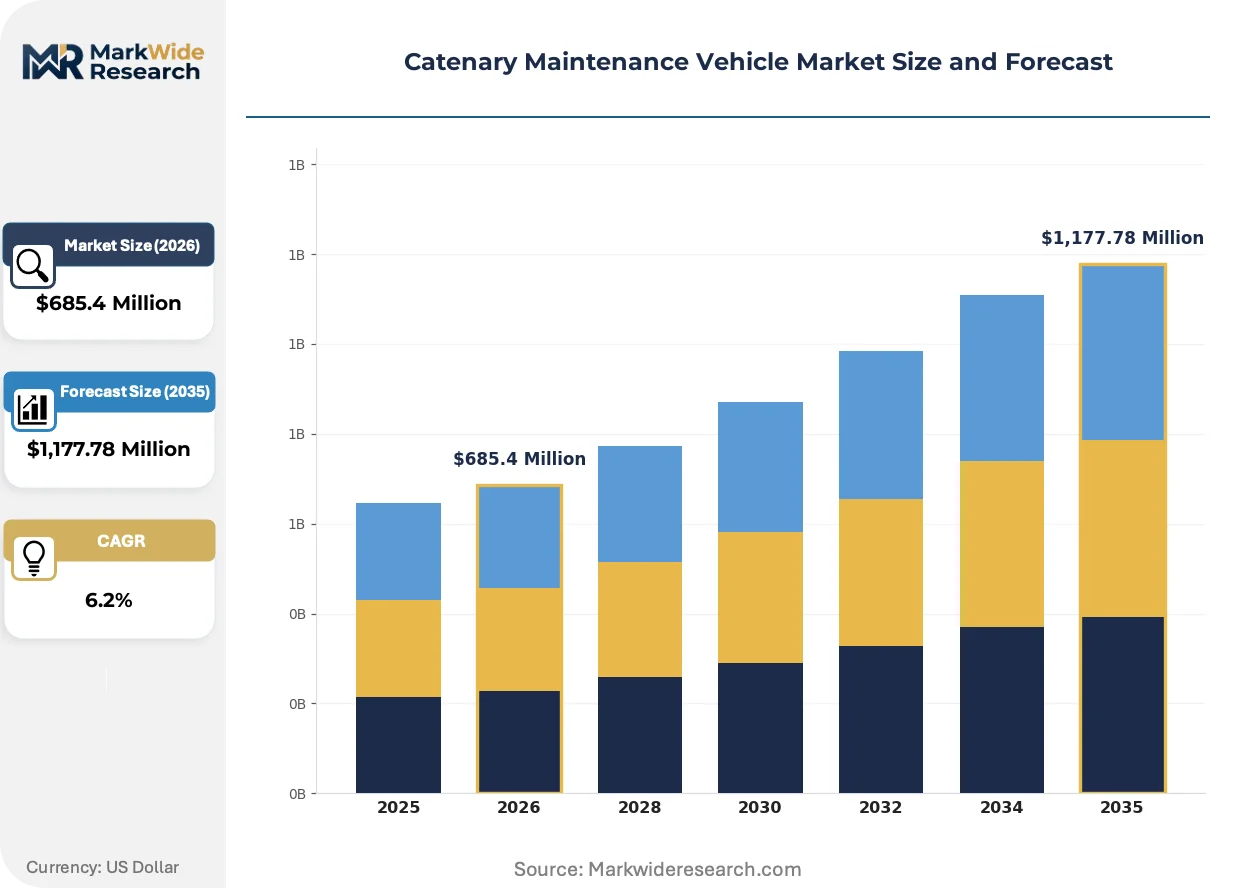
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,177.78 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Track Inspection Vehicle, Power Maintenance Vehicle, Repair Vehicle, Utility Vehicle Power Source: Diesel, Electric, Hybrid, Battery-operated Application: Rail Infrastructure, Overhead Lines, Electric Utility, Signal Systems End User: Government Agencies, Railroad Operators, Maintenance Contractors, Public Utilities |
| Companies Covered | New Sorema Ferroviaria, ZWEIWEG, TMCP V.V. Vorovsky, Aveng Manufacturing, Hilton Kommunal GmbH, Ferrovías Astur, Zwiehoff GmbH, Socofer France, CRCC High-Tech Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Catenary Maintenance Vehicle Market Strategic Shifts
Autonomous inspection technologies and predictive maintenance algorithms are compressing the traditional reactive repair cycle into continuous condition-based intervention models across electrified rail networks.
Lidar-based catenary geometry measurement systems are automating the detection of wire wear, stagger deviation, and contact point anomalies at track speeds up to 80 km/h. Deutsche Bahn maintenance divisions are deploying these platforms across Rhine-Ruhr corridor operations to eliminate manual boom inspections. This automation is compressing inspection cycle intervals from quarterly to weekly frequencies without proportional labor cost expansion.
REACH restrictions on perfluorinated compounds are phasing out legacy insulating materials in telescopic boom construction, compelling manufacturers to qualify ceramic-polymer composite alternatives. The industrial consequence is extended type-approval timelines for new vehicle configurations. Multi-function overhead line repair vehicles face the tightest certification delays as they integrate multiple high-voltage subsystems under revised material safety thresholds.
Performance-based maintenance contracting is displacing time-and-material service agreements among European infrastructure managers. Contractors now assume availability risk for specified catenary segments, incentivizing predictive investment in diagnostic capabilities. This shift concentrates most visibly in Germany's regional rail concessions, where DB Netz and private operators negotiate ten-year availability guarantees with penalty clauses for unplanned contact wire failures.
Catenary Maintenance Vehicle Market Segmentation
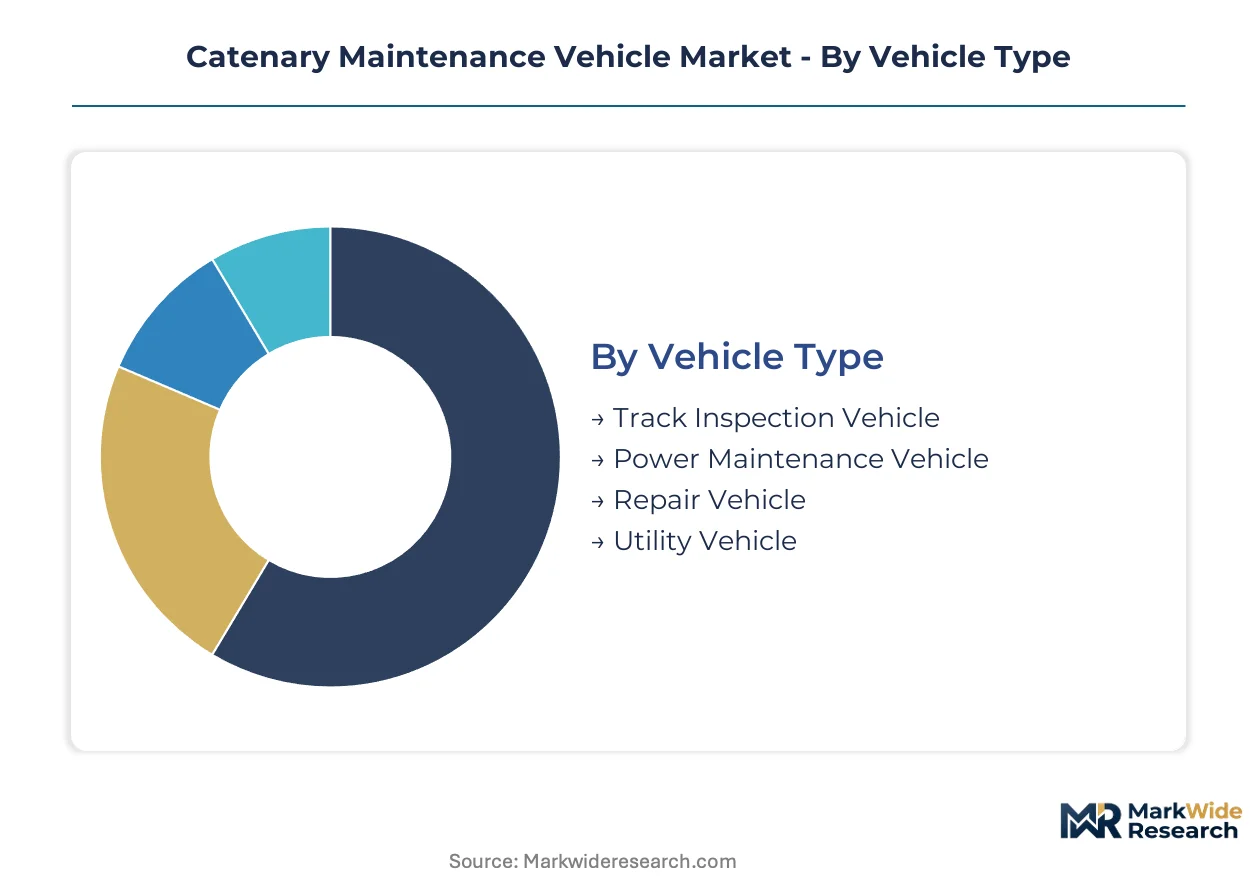
Segmentation in the catenary maintenance vehicle market reveals how certification burdens, operational requirements, and procurement authority shape equipment specifications across electrified rail networks. Understanding these divisions exposes where margin pools concentrate and which technical configurations face the steepest compliance escalation.
Vehicle Type:
ERA interoperability certification under EU Directive 2016/798 imposes divergent type-approval timelines across vehicle categories, with multi-function platforms facing the most complex high-voltage subsystem integration requirements.
- Track Inspection Vehicle:Self-propelled units equipped with lidar-based catenary geometry measurement systems and pantograph-compatible diagnostic arrays. Deutsche Bahn maintenance divisions across the Rhine-Ruhr corridor deploy these platforms to compress inspection cycles from quarterly to weekly frequencies without proportional labor expansion.
- Power Maintenance Vehicle:Integrated platforms combining inspection and repair functions with insulated telescopic booms reaching working heights exceeding seven meters. China's high-speed rail corridor maintenance operations concentrate procurement volume here as NMPA and MIIT joint enforcement of GB standards drives domestic fleet standardization.
- Repair Vehicle:Specialized units for contact wire replacement and tensioning operations.
- Utility Vehicle:Municipal tram network configurations with compact boom geometries for tight urban clearances.
Power Maintenance Vehicle sits at the top of the volume ranking, with Track Inspection Vehicle climbing the fastest as predictive maintenance models displace reactive repair cycles.
Power Source:
Cost tier stratification separates premium battery-electric platforms from legacy diesel units, with total cost of ownership calculations increasingly dominated by charging infrastructure investment rather than upfront capital expenditure.
- Battery-operated:Lithium-ion configurations capturing margin pools as EU Green Deal procurement incentives introduce carbon footprint scoring into public tender evaluations. Overnight charging infrastructure gaps at German and Austrian maintenance depots currently constrain operational deployment flexibility for contractors.
- Electric:Catenary-powered units drawing traction current from the overhead lines they maintain. Italian and Swiss alpine rail networks favor these configurations for continuous corridor operations where battery endurance specifications remain unproven.
- Diesel:Legacy platforms facing accelerated retirement timelines under escalating emissions restrictions.
- Hybrid:Dual-mode systems bridging electrified and non-electrified track sections.
Battery-operated configurations command the steepest expansion trajectory, while Electric maintains installed base dominance in mountainous topography.
Application:
Application segmentation tracks where aging copper-silver contact wire networks generate replacement demand versus where new electrification projects create greenfield procurement.
- Overhead Lines:Proactive maintenance scheduling for aging copper-silver contact wire networks across Germany's urban rail transit systems. REACH restrictions on perfluorinated compounds in telescopic boom insulation materials extend type-approval timelines for new vehicle configurations in this segment.
- Rail Infrastructure:Trackbed and civil works maintenance requiring lower working heights.
- Electric Utility:Third-rail and substation maintenance applications.
- Signal Systems:Communication and control equipment access platforms.
Overhead Lines generates the fastest volume gain, with Rail Infrastructure holding the largest installed equipment base.
End User:
Procurement authority concentration determines specification complexity, with infrastructure managers negotiating performance-based availability guarantees while maintenance contractors prioritize fleet flexibility.
- Railroad Operators:Deutsche Bahn and comparable integrated infrastructure managers negotiating ten-year catenary availability guarantees with penalty clauses for unplanned contact wire failures. These stakeholders drive demand for predictive diagnostic capabilities and autonomous inspection technologies.
- Maintenance Contractors:Third-party service providers assuming availability risk under performance-based contracting models. German regional rail concessions concentrate procurement here as DB Netz and private operators externalize maintenance execution.
- Government Agencies:National rail authorities overseeing electrification program standards.
- Public Utilities:Municipal tram network operators with specialized urban clearance requirements.
Railroad Operators anchor procurement volume, with Maintenance Contractors gaining share fastest as performance-based contracting displaces time-and-material agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized rail maintenance technicians concentrate in Germany's Rhine-Ruhr industrial corridor, anchoring Europe's largest pool of high-voltage catenary certification expertise. China's high-speed rail engineering workforce clusters in Beijing and Shanghai, driving procurement scale for integrated inspection platforms. Swiss alpine rail specialists maintain unique competency in catenary-powered continuous operation systems.
Germany
Deutsche Bahn maintenance divisions across the Rhine-Ruhr corridor deploy lidar-based catenary geometry measurement systems to compress inspection cycles from quarterly to weekly frequencies. ERA interoperability standards under EU Directive 2016/798 mandate standardized catenary geometry tolerances, compelling fleet upgrades among maintenance contractors. Munich-based engineering clusters specialize in insulated telescopic boom manufacturing for pantograph-compatible diagnostic arrays.
China
NMPA and MIIT joint enforcement of GB standards for rail-mounted electrical equipment drives domestic procurement volume for integrated inspection systems. The country's national rail authority oversees electrification program standards across 40,000 kilometers of high-speed corridor infrastructure. Beijing-Tianjin-Hebei engineering centers anchor production of self-propelled overhead line repair vehicles for domestic deployment.
Switzerland
Swiss Federal Railways maintenance operations favor catenary-powered units for continuous corridor operations where battery endurance specifications remain unproven. The country's national rail safety regulator enforces stringent high-voltage certification requirements for alpine network maintenance. Zurich-based technical clusters develop ceramic-polymer composite insulation alternatives under revised REACH material safety thresholds.
Italy
New Sorema Ferroviaria leverages Italian engineering heritage to anchor European demand for multi-function overhead line repair vehicles. The country's national rail infrastructure manager negotiates performance-based availability guarantees with penalty clauses for unplanned contact wire failures. Milan-Turin industrial corridors concentrate specialized manufacturing of pantograph diagnostic array subsystems.
India
Electrification of 2,843 route kilometers under the Ministry of Railways creates untapped demand for self-propelled overhead line repair vehicles. The country's national standards body shapes product design requirements through BIS certification protocols for rail-mounted electrical equipment. Delhi-Mumbai dedicated freight corridor operations concentrate procurement authority for integrated power maintenance vehicle fleets.
Catenary Maintenance Vehicle Market Competitive Environment
Top-tier vendors anchor integrated platform supply, while regional specialists occupy utility and repair niches. The vendor base stratifies between full-capability infrastructure managers and component-focused maintenance contractors. Two strategic archetypes dominate: state-affiliated rail equipment conglomerates with captive domestic markets, and European engineering heritage firms with ERA certification expertise. Competitive moves concentrate on modular battery swapping architectures and performance-based contracting partnerships with infrastructure managers.
Within the European engineering heritage tier, New Sorema Ferroviaria and Hilton Kommunal GmbH exemplify specialized competency in multi-function overhead line repair vehicles. CRCC High-Tech Equipment occupies a position representing state-affiliated scale advantage in Asia-Pacific rail infrastructure contracts. These three anchors illustrate how certification geography and procurement authority concentration shape competitive positioning across electrified network maintenance markets.
| Leading Market Players |
|---|
| New Sorema Ferroviaria |
| ZWEIWEG |
| TMCP V.V. Vorovsky |
| Aveng Manufacturing |
| Hilton Kommunal GmbH |
| Ferrovías Astur |
| Zwiehoff GmbH |
| Socofer France |
| CRCC High-Tech Equipment |
| Others |
Value Chain & Pricing Dynamics
Integrated infrastructure managers like Deutsche Bahn anchor procurement volume through performance-based availability guarantees, forcing tiered pricing structures that separate premium diagnostic-integrated platforms from economy repair-only configurations. This buyer concentration compresses margins for maintenance contractors while elevating price premiums for ERA-certified multi-function vehicles.
Pricing Analysis
Bundled service contracts combining vehicle lease with predictive maintenance software command premium positioning against unbundled equipment-only transactions. Price differentiation rests on ERA certification tier and battery-electric endurance specifications, with carbon footprint scoring under EU Green Deal procurement incentives intensifying cost compression in legacy diesel tiers. State-affiliated rail authorities exhibit lowest price sensitivity, while third-party maintenance contractors face acute margin pressure from overnight charging infrastructure gaps.
Supply Chain Analysis
Single-source vulnerability sits with insulated telescopic boom manufacturing clusters in Germany, Italy, and Switzerland. Lithium-ion cathode minerals draw from Chile, Australia, and Indonesia, while ceramic-polymer composite insulation alternatives hinge on REACH regulatory timelines. Tariff exposure on battery cell imports compounds supply risk. Distribution runs through OEM-direct contracts for integrated platforms and regional dealer networks for utility configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory demand through EU Directive 2016/798 mandating standardized catenary geometry tolerances, which forces fleet upgrade cycles regardless of economic conditions.
For Market Incumbents: To counter battery-electric platform entrants from state-affiliated Asian manufacturers, deepen in-house production of pantograph-compatible diagnostic arrays and secure ERA cross-border certification for technician training programs. Capacity addition in India's dedicated freight corridor zones captures emerging procurement authority before localization requirements harden. For New Entrants and Emerging Players: Launch via modular battery swapping architectures targeting maintenance contractors in Germany and Austria where overnight charging infrastructure gaps constrain incumbent deployment flexibility. India's Ministry of Railways electrification program represents the most penetrable geography, with performance-based contracting partnerships offering the clearest go-to-market angle against established OEM relationships. For Investors and Strategic Acquirers: State-affiliated rail equipment conglomerates are the most active acquirer in this space, seeking ERA certification expertise to unlock European infrastructure manager contracts. Five-to-ten year viability favors targets with captive diagnostic software development. The signal to watch is BIS certification protocol adoption in India's dedicated freight corridors as an inflection indicator for procurement standardization.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Battery Swapping Architecture | Automated exchange systems bypass depot charging delays for Deutsche Bahn maintenance divisions. |
| ERA Cross-Border Certification Investment | Type-approval for multi-function platforms unlocks DB Netz ten-year availability guarantee contracts. |
| Ceramic-Polymer Composite Qualification | REACH-compliant insulation materials extend boom manufacturing capacity under revised safety thresholds. |
| Predictive Maintenance Software Integration | Lidar-based geometry measurement compresses inspection cycles from quarterly to weekly frequencies. |
| India Localization Partnership | BIS certification alignment with Ministry of Railways electrification protocols secures corridor maintenance contracts. |
Study Parameters
Multiple input streams — maintenance director interviews, infrastructure manager procurement data, and OEM technical documentation — were reconciled against regulatory filing databases. Primary discussions with catenary system engineers, fleet operations managers, and ERA certification specialists were validated through secondary sources including EU railway safety directive archives, NMPA equipment registration records, and national rail authority electrification program disclosures. Bottom-up vehicle deployment estimates and top-down infrastructure investment flows were triangulated to anchor volume assumptions.
Historical fleet replacement patterns were cross-referenced against expert panel assessments of battery-electric platform adoption curves across the projection horizon. Segmentation dimensions modeled include vehicle type, power source architecture, application work height requirements, and end-user procurement authority concentration. CAGRs were derived from logistic diffusion curves fitted to electrification mandate compliance deadlines, with GB standard enforcement timelines and copper-silver contact wire replacement cycles serving as industry-specific forecast anchors.
Forecast precision tightens around the base case; tail outcomes carry wider variance under lithium-ion mineral price volatility and REACH material restriction acceleration. Forecasts reflect documented assumptions regarding depot electrification investment pacing and technician certification throughput capacity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Maintenance & Aftermarket
E-Commerce Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
US Maintenance Repair and Operations (MRO) Market
Vehicle Maintenance & Aftermarket
Road Maintenance Service Market
Vehicle Maintenance & Aftermarket
Asia-Pacific Car Cleaning Products Market
Vehicle Maintenance & Aftermarket
Vehicle Health Monitoring Market
Vehicle Maintenance & Aftermarket
Car Duster Market
Vehicle Maintenance & Aftermarket
Silicone in Car Care Products Market
Vehicle Maintenance & Aftermarket
Global Automotive Lubricants Aftermarket Market
Vehicle Maintenance & Aftermarket
Asia-Pacific Car Wash Market
Vehicle Maintenance & Aftermarket
Asia Pacific Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Car Polisher Market
Vehicle Maintenance & Aftermarket
Middle East and Africa Automotive Aftermarket Glass Market
Vehicle Maintenance & Aftermarket
Electric Vehicle Aftermarket Market
Vehicle Maintenance & Aftermarket
Car Glass Cleaner Market
Vehicle Maintenance & Aftermarket
Global Integrated Vehicle Health Management Market
Vehicle Maintenance & Aftermarket
Car Recycling Market