
 Lining Market | 2026-2036
Lining Market Size, Share, and Industry Trends Forecast 2026-2036
Lining Market Outlook
Advanced polymer compounding is reconfiguring how protective linings achieve chemical resistance and mechanical durability in hostile environments. The Jotun Group leverages its marine coatings heritage to anchor specialized lining solutions for ship hulls and offshore structures. Hempel A/S competes through R&D intensity in epoxy and polyurethane formulations for industrial tank protection. DuPont sustains technology leadership in high-performance fluoropolymer barriers for extreme-temperature applications.
Lining refers to a protective layer applied to the interior surface of vessels, pipelines, structures, or garments to prevent corrosion, abrasion, leakage, or thermal transfer, typically manufactured through calendering, extrusion, spray deposition, or adhesive bonding processes depending on base material and substrate geometry. Its primary commercial purpose spans containment integrity in chemical processing, waterproofing in civil engineering, and functional enhancement in apparel and automotive interiors. Polyester and fiberglass dominate the material dimension due to established supply chains and cost-performance ratios in construction and marine end uses, while silicone linings command premium positioning in aerospace thermal protection where outgassing resistance and temperature stability define specification thresholds. Plastic linings capture volume leadership across water infrastructure and mining heap-leach pads, whereas rubber formulations retain defensible positions in abrasion-heavy bulk material handling.
REACH in Europe mandates disclosure of Substances of Very High Concern in lining chemistries, redirecting formulation investment toward bio-based and low-VOC alternatives. China's SAMR enforces GB standards for construction material safety, compelling domestic manufacturers to upgrade testing protocols for geomembrane and tank lining products. EPA leachate prevention rules in the United States shape landfill and containment design specifications, directly influencing liner thickness and permeability requirements. Stakeholders must monitor regulatory divergence between jurisdictions to avoid compliance-driven cost fragmentation in cross-border project bidding.
Market Dynamics
Corrosion-resistant geomembrane systems are capturing capital allocation as water treatment infrastructure projects across Asia-Pacific accelerate specification upgrades for containment integrity. Polymer compounding advances and tightening chemical disclosure mandates are compressing formulation cycles while expanding addressable applications.
Growth Catalysts
- REACH compliance mandates:ECHA disclosure requirements for Substances of Very High Concern redirect European formulation investment toward bio-based and low-VOC alternatives, expanding qualified supplier pools.
- China's GB standards enforcement:SAMR construction material safety protocols compel domestic manufacturers to upgrade testing procedures for geomembrane and tank lining products.
- Heap-leach pad construction:Mining operations in copper and lithium extraction deploy high-density polyethylene linings for acid containment, driving specification intensity in resource extraction.
Market Restraints
- Petrochemical feedstock volatility:Ethylene and propylene price swings compress margin predictability for polyethylene and polypropylene lining manufacturers.
- Fluoropolymer supply concentration:PTFE and PVDF resin production clusters in China and the United States create geographic concentration risk for extreme-temperature applications.
- Cementitious coating substitution:Spray-applied concrete and epoxy-mortar systems compete for secondary containment in cost-sensitive municipal wastewater projects.
Strategic Opportunities
- India's irrigation canal rehabilitation:National programs targeting water loss reduction create specification openings for geomembrane lining in agricultural infrastructure.
- Dual carbon policy alignment:China's MEE enforcement of carbon intensity targets rewards low-emission lining production with preferential project access.
- Digital thickness monitoring:IoT-enabled liner integrity systems converge with geomembrane installation to create recurring revenue streams in landfill and mining containment.
Industry Challenges
- Welding technician certification:Geomembrane seam integrity depends on certified hot-wedge and extrusion welders, creating bottlenecks in project ramp schedules.
- Legacy substrate compatibility:Retrofit lining applications require surface preparation protocols that extend installation timelines and complicate warranty terms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lining Market |
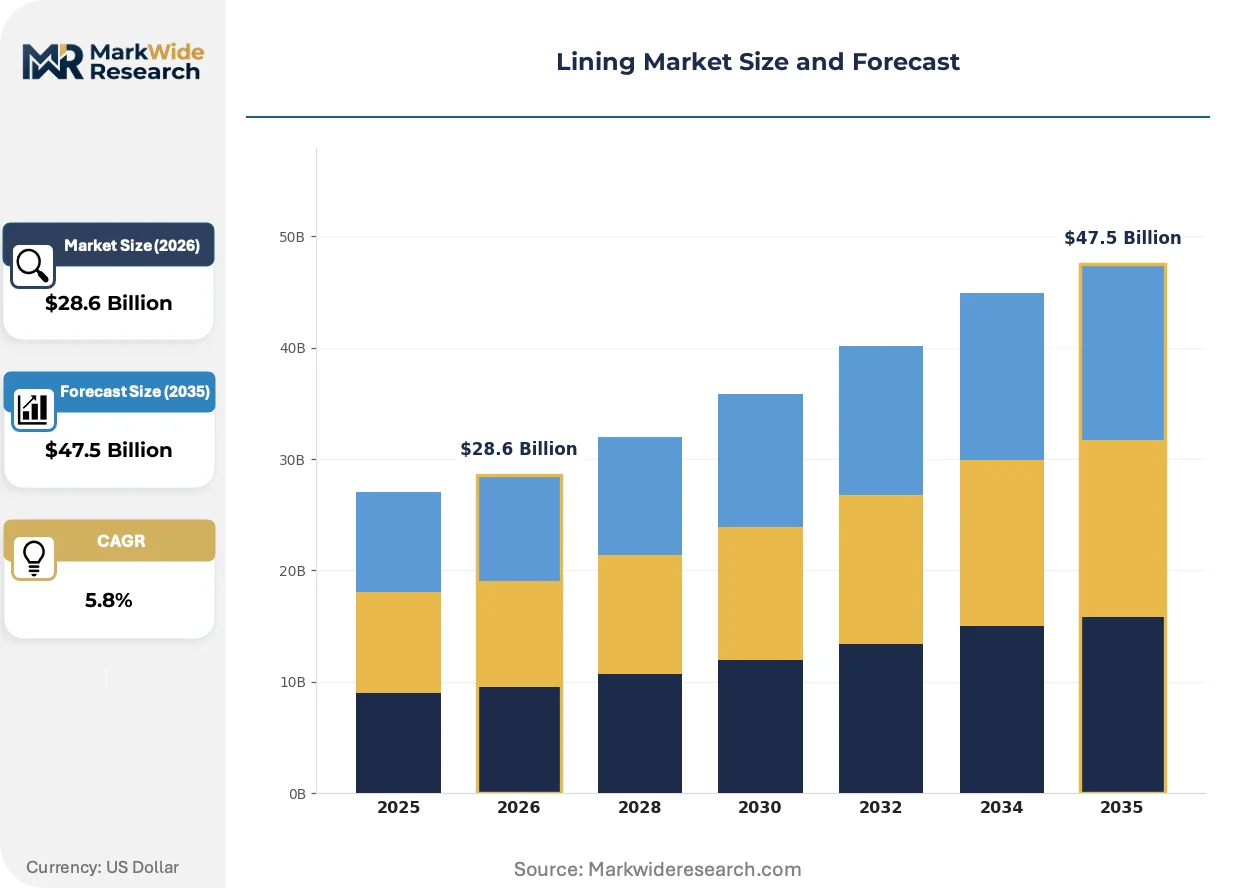
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
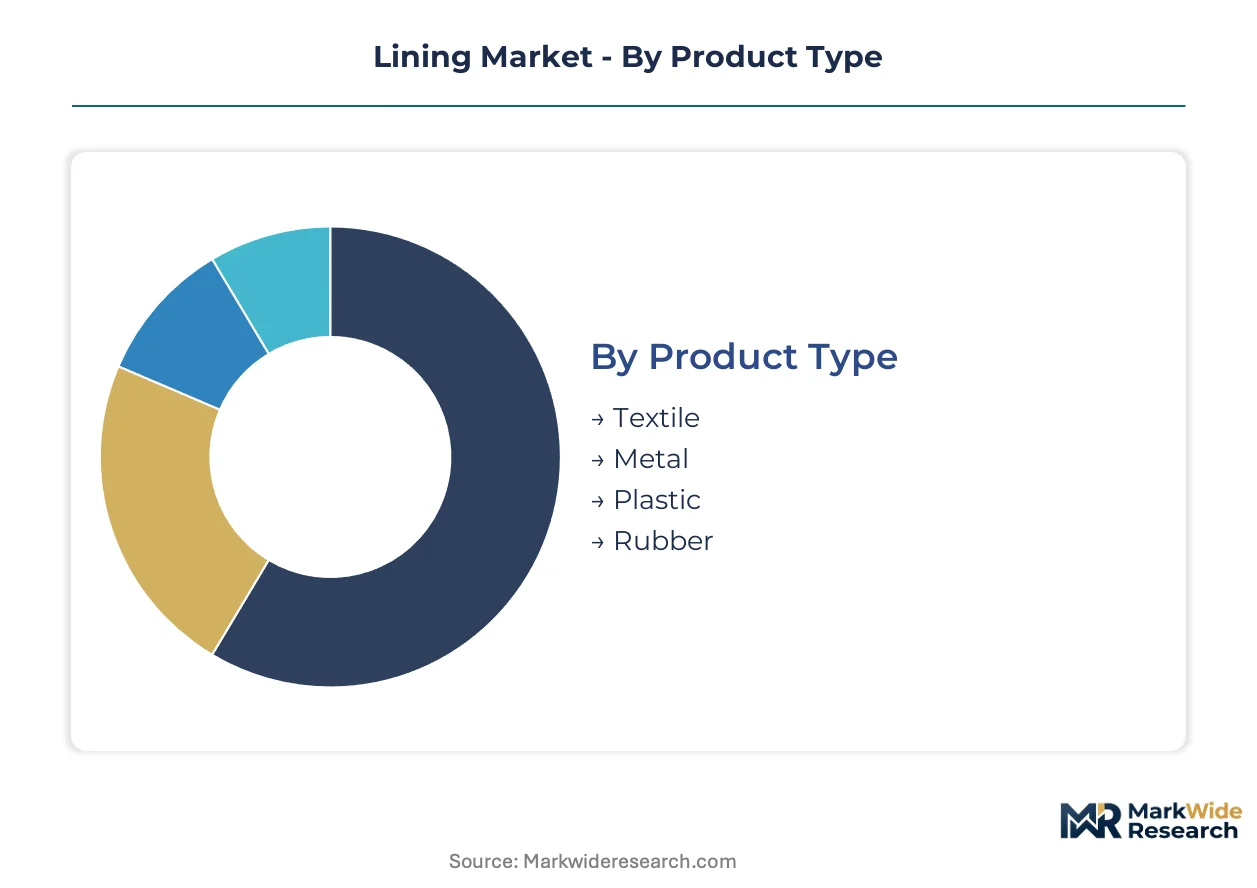
| Segmentation | Product Type: Textile, Metal, Plastic, Rubber End User: Automotive, Aerospace, Construction, Marine Application: Insulation, Protection, Aesthetics, Soundproofing Material: Polyester, Silicone, PVC, Fiberglass |
| Companies Covered | The Jotun Group, The Sherwin Williams Company, Hempel A/S, Akzo Nobel N.V., PPG Industries, Inc., Chargeurs PCC, Huzhou Meishida Textiles, Toray Industries, Inc., DuPont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lining Market Strategic Shifts
Advanced polymer architectures and automated installation methods are compressing project timelines while elevating performance thresholds for chemical resistance and mechanical durability.
Thermoplastic polyurethane liners are collapsing the performance gap between commodity geomembranes and fluoropolymer barriers in aggressive chemical environments. Chemical processing facilities and battery recycling plants specify these materials for acid containment at thicknesses below traditional HDPE alternatives. The technology is collapsing capital cost structures for secondary containment in mid-tier corrosion applications.
REACH authorization procedures for persistent organic pollutants tighten substitution timelines for chlorinated lining chemistries across European industrial tank protection. ECHA sunset dates for specific phthalate plasticizers force reformulation investments in PVC-based systems. German chemical manufacturers accelerate bio-based plasticizer trials to maintain product registrations.
Asset owner engineering teams now specify performance warranties rather than material certificates for lining installations in critical containment. This behavior shift displaces distributor-led specification with direct manufacturer accountability in mining and energy sector procurement. The pattern concentrates most visibly in Australian and Canadian resource extraction projects where operator liability frameworks emphasize lifecycle integrity guarantees.
Lining Market Segmentation
Lining specifications diverge sharply across end-use contexts, with material selection driven by chemical exposure severity, thermal cycling demands, and substrate compatibility requirements. Procurement patterns in this market track project lifecycle velocity rather than replacement frequency alone.
Product Type:
Replacement cycles stretch from months in abrasion-heavy rubber applications to decades in structural metal systems, creating distinct inventory and service revenue profiles.
- Plastic:High-density polyethylene and polypropylene formulations dominate geomembrane installations for water containment and mining heap-leach operations. China's municipal wastewater infrastructure and India's canal rehabilitation programs concentrate demand for welded seam systems with 30-50 year design life.
- Rubber:Natural and synthetic elastomer compounds absorb impact and vibration in bulk material handling equipment. Mining conveyors and aggregate processing in Australia and South Africa specify these linings for wear resistance against sharp particulate loads.
- Textile:Woven and non-woven fabric layers provide permeable separation and filtration functions in geosynthetic applications.
- Metal:Corrosion-resistant alloy cladding protects process vessels and exhaust systems in high-temperature industrial environments.
Plastic linings dominate installed base volume. Rubber is where expansion concentrates in resource extraction applications.
End User:
Margin structures correlate with certification burden and liability exposure rather than raw material cost alone.
- Construction:Geomembrane and tank lining specifications for containment integrity in water infrastructure, landfills, and chemical processing facilities. China's SAMR enforcement of GB standards and EPA leachate rules in the United States shape thickness and permeability requirements.
- Marine:Protective coatings and hull linings combat biofouling and saltwater corrosion in commercial shipping and offshore structures. IMO antifouling conventions and port state control inspections in Singapore and Rotterdam drive specification upgrades.
- Automotive:Interior trim and underbody coatings for noise reduction and corrosion protection.
- Aerospace:Thermal protection systems and insulation barriers for extreme-temperature engine and airframe applications.
Construction anchors volume demand. Marine is climbing the fastest on regulatory compliance investment.
Application:
Performance specifications escalate with the cost of containment failure, creating tiered qualification barriers for suppliers.
- Protection:Chemical-resistant barriers prevent substrate degradation in tanks, pipelines, and process equipment. Battery recycling plants and semiconductor fabrication facilities in Germany and South Korea specify fluoropolymer and thermoplastic polyurethane systems for acid containment.
- Insulation:Thermal barriers reduce heat transfer in industrial equipment and building envelopes. Data center cooling infrastructure in Ireland and Singapore drives demand for high-performance foam and reflective lining systems.
- Soundproofing:Acoustic damping layers for transportation and industrial noise control.
- Aesthetics:Decorative surface finishes for interior architectural and consumer product applications.
Protection commands specification intensity. Insulation is gaining share fastest on energy efficiency mandates.
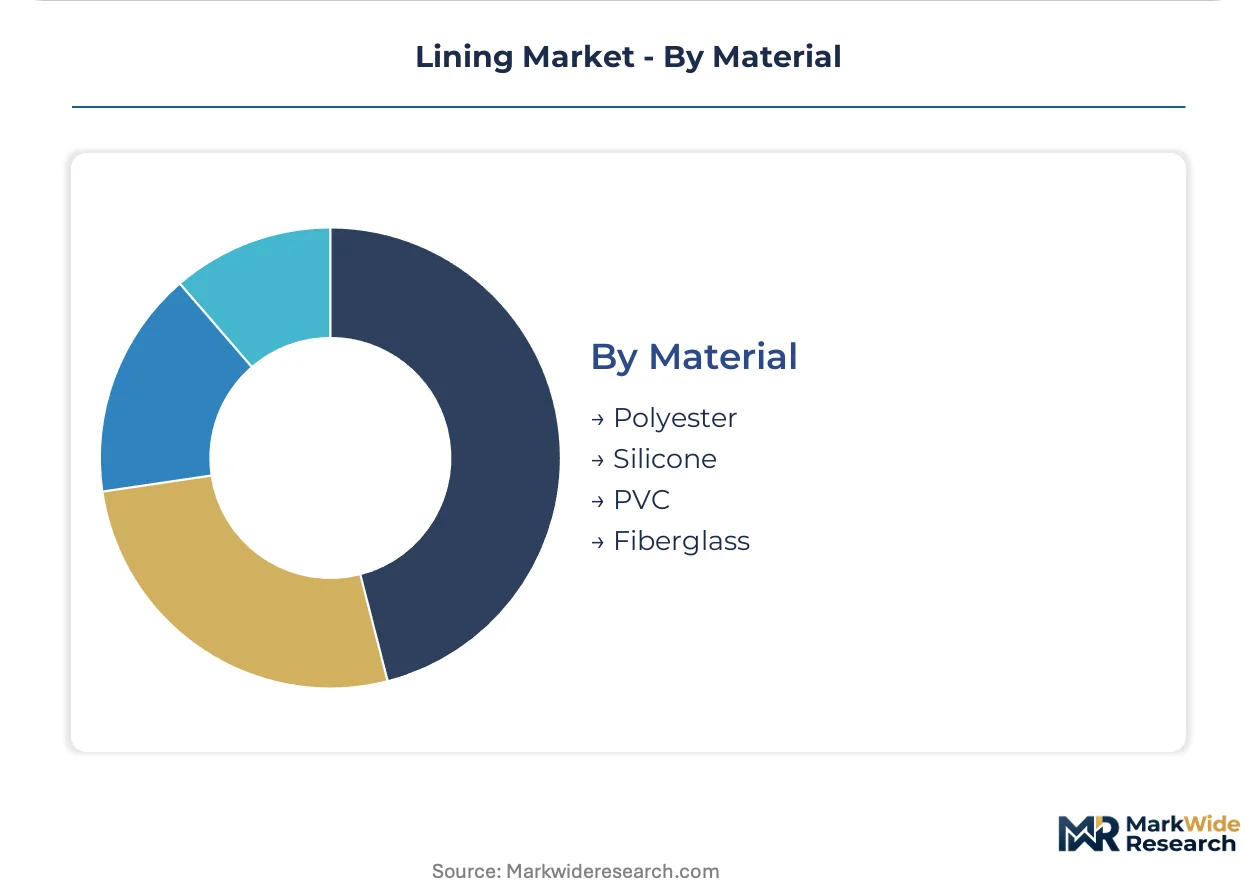
Material:
Supply chain concentration for fluoropolymer resins creates geographic dependency risks for extreme-performance applications.
- Polyester:Woven and non-woven geotextile substrates provide dimensional stability and cost efficiency in civil engineering. Road construction and erosion control projects in Brazil and Indonesia specify these materials for drainage and separation functions.
- Silicone:Elastomer formulations deliver temperature stability and outgassing resistance for aerospace and medical applications. Satellite thermal control systems and cleanroom equipment in California and Toulouse require low-volatile silicone barriers.
- PVC:Flexible membrane systems for roofing, tunnel waterproofing, and secondary containment. REACH authorization timelines for phthalate plasticizers force European manufacturers toward bio-based alternatives.
- Fiberglass:Reinforced composite linings for chemical resistance and structural reinforcement in corrosive environments.
Polyester dominates tonnage throughput. Silicone shows the steepest expansion trajectory on aerospace and electronics demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German lining manufacturers export corrosion-resistant geomembrane systems to water infrastructure projects across Asia-Pacific, while Chinese producers supply high-density polyethylene liners to mining operations in Australia and Chile.
China
Municipal wastewater treatment plants in Jiangsu and Zhejiang provinces drive specification upgrades for welded seam geomembranes with 30-50 year design life. SAMR enforcement of GB standards compels domestic manufacturers to upgrade testing protocols for construction material safety. The Yangtze River Delta cluster anchors production capacity for polyethylene and polypropylene lining systems serving domestic and export markets.
United States
EPA leachate prevention rules directly influence liner thickness and permeability requirements for landfill and containment design specifications. Mining heap-leach operations in Nevada and Arizona deploy high-density polyethylene linings for acid containment in copper and lithium extraction. The Permian Basin and Appalachian shale regions concentrate demand for tank lining systems in chemical processing infrastructure.
Germany
Battery recycling plants and semiconductor fabrication facilities in Saxony and Bavaria specify fluoropolymer and thermoplastic polyurethane systems for aggressive acid containment. ECHA REACH authorization timelines force reformulation investments away from chlorinated chemistries and phthalate plasticizers. The Ruhr industrial corridor and Munich metropolitan area host engineering teams demanding performance warranties rather than material certificates for critical containment installations.
India
National irrigation canal rehabilitation programs targeting water loss reduction create specification openings for geomembrane lining in agricultural infrastructure. BIS construction material standards tighten performance requirements for synthetic lining products in civil engineering applications. The Gujarat and Maharashtra industrial corridors concentrate procurement activity for water infrastructure and chemical processing containment systems.
Australia
Mining conveyors and aggregate processing operations in Western Australia and Queensland specify rubber linings for wear resistance against sharp particulate loads. Operator liability frameworks emphasize lifecycle integrity guarantees, concentrating procurement around direct manufacturer accountability. The Pilbara iron ore region and Bowen Basin coal fields drive replacement cycles for abrasion-heavy bulk material handling equipment.
Lining Market Competitive Environment
Channel-controlling players compete with product-specialist players across distinct specification tiers. The vendor base organizes around three structural positions: diversified coatings conglomerates with marine and industrial heritage, polymer technology specialists with fluoropolymer and polyurethane expertise, and regional fabricators serving geographically concentrated infrastructure projects. Competitive moves center on formulation licensing for REACH-compliant chemistries and capacity expansion in Asia-Pacific geomembrane welding services.
Within the diversified coatings tier, The Jotun Group and Hempel A/S occupy positions anchored by marine coatings heritage extending into specialized lining solutions. DuPont exemplifies the polymer technology archetype through high-performance fluoropolymer barriers for extreme-temperature applications. The Sherwin Williams Company and PPG Industries represent North American channel scale, while Akzo Nobel anchors European industrial coating specification networks. Toray Industries occupies a position in textile-based lining substrates, with Chargeurs PCC and Huzhou Meishida Textiles sitting within the fabric and technical textile specialization tier.
| Leading Market Players |
|---|
| The Jotun Group |
| The Sherwin Williams Company |
| Hempel A/S |
| Akzo Nobel N.V. |
| PPG Industries, Inc. |
| Chargeurs PCC |
| Huzhou Meishida Textiles |
| Toray Industries, Inc. |
| DuPont |
| Others |
Value Chain & Pricing Dynamics
PTFE and PVDF resin production clusters in China and the United States concentrate upstream supply for extreme-temperature lining applications, anchoring margin pools with polymer compounders and certified installation contractors rather than commodity geomembrane fabricators. This concentration pattern shapes pricing power downstream, where specification-grade fluoropolymer barriers command substantial premiums over standard polyethylene alternatives.
Pricing Analysis
Current-generation thermoplastic polyurethane liners, prior-generation high-density polyethylene geomembranes, and next-generation bio-based alternatives stratify across distinct price-performance tiers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and design life differentiation, with REACH-compliant formulations carrying explicit premiums over conventional chemistries. Cost compression in commodity HDPE segments is intensifying because cementitious coating substitution pressures municipal wastewater procurement. Municipal infrastructure buyers exhibit highest price sensitivity, while semiconductor fabrication facilities demonstrate lowest sensitivity due to containment failure costs.
Supply Chain Analysis
Export-control regimes limiting fluoropolymer resin flows between the United States and China reshape sourcing strategies for extreme-performance applications. Supply concentrates in China for high-density polyethylene geomembranes, Germany for epoxy and polyurethane formulations, and the United States for PTFE barriers. Raw material dependencies span ethylene and propylene feedstocks, specialty plasticizers, and corrosion-resistant alloy substrates. Single-source vulnerability in certified welding technician pools creates project ramp bottlenecks. Distribution runs through regional fabricators with geomembrane welding capabilities and direct manufacturer channels for specification-grade industrial tank protection.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lining market sits in early-cycle expansion as water infrastructure rehabilitation programs across Asia-Pacific accelerate specification upgrades for containment integrity. Battery recycling and semiconductor fabrication investments in Germany and South Korea extend addressable demand beyond traditional construction applications.
For Market Incumbents:Insulate formulation portfolios from REACH authorization timelines by accelerating bio-based plasticizer trials and securing ECHA pre-registrations for alternative chemistries. Deepen captive supply of polyethylene resin through backward integration into petrochemical feedstock arrangements, or acquire regional geomembrane welding service providers to control installation quality and warranty exposure.
For New Entrants and Emerging Players:India's irrigation canal rehabilitation programs represent the most penetrable entry point for geomembrane specialists lacking established municipal wastewater track records. Mid-tier chemical processing facilities in Southeast Asia seeking acid containment solutions below fluoropolymer cost thresholds offer secondary expansion terrain. Partner with state-level water resource departments on pilot installations to build specification credibility before national program scale-up.
For Investors and Strategic Acquirers:Capital is best deployed toward polymer technology specialists with demonstrated REACH-compliant formulation pipelines and existing aerospace or semiconductor customer qualifications. Long-term viability hinges on regulatory chemistry substitution capabilities rather than commodity geomembrane fabrication scale. Monitor ECHA sunset date announcements for persistent organic pollutants as the critical inflection signal for consolidation timing in European coating and lining markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive polyethylene supply secures margin stability against ethylene price volatility for geomembrane manufacturers. |
| REACH-Compliant Formulation Licensing | Technology transfer agreements enable European market access for Asia-Pacific compounders facing ECHA authorization barriers. |
| Geomembrane Welding Service Expansion | Certified technician networks in Australia and Chile reduce project ramp bottlenecks for mining containment contracts. |
| IoT-Enabled Liner Integrity Systems | Digital thickness monitoring creates recurring revenue streams beyond installation in landfill and heap-leach applications. |
| Bio-Based Plasticizer Development | Alternative chemistry pipelines maintain PVC lining registrations as ECHA phthalate sunset dates approach. |
Study Parameters
A standing panel of geomembrane installation contractors, chemical processing plant engineers, municipal procurement officers, and polymer R&D directors provided ongoing calibration across primary fieldwork and secondary validation. This practitioner input combined with customs trade data, ECHA substance registration databases, EPA landfill design filings, and SAMR construction material safety notifications. Bottom-up project pipeline analysis and top-down polymer consumption estimates were triangulated to anchor volume and value outputs.
Scenario-bracketing around regulatory acceleration and feedstock price volatility shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include material chemistry, application severity tier, end-use industry, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles and new project specification intensity. Forecast inputs incorporated heap-leach pad construction timelines and irrigation canal rehabilitation program pacing.
Practitioners should monitor ECHA authorization timelines, ethylene price volatility, and welding technician certification backlogs for early signals of forecast deviation. Forecasts reflect assumptions about regulatory enforcement consistency and infrastructure program funding continuity. Material shifts in REACH sunset date acceleration or national water infrastructure budget reallocations would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Breathable Lidding Film Packaging Market
Packaging Barrier Films
Heat Transfer Films Market
Packaging Barrier Films
Sterile Barrier Packaging Market
Packaging Barrier Films
Thailand Plastic Packaging Films Market
Packaging Barrier Films
Barrier Films Market
Packaging Barrier Films
Biobased Anti-Blocking Agents for Flexible Packaging Films Market
Packaging Barrier Films
Meat Packaging Films Market
Packaging Barrier Films
Child-Resistant Foil Packaging Market
Packaging Barrier Films
Dual Ovenable Lidding Films Market
Packaging Barrier Films
Water Resistant Packaging Market
Packaging Barrier Films
Global Silicone Release Liner Market
Packaging Barrier Films
Cryogenic Insulation Films Market
Packaging Barrier Films
Stretch Films Packaging Market
Packaging Barrier Films
Metalized Barrier Film Packaging Market
Packaging Barrier Films
Barrier Shrink Films Market
Packaging Barrier Films
PET Release Liner Market