
 Global Hazardous Location Thermostats Market | 2026-2036
Global Hazardous Location Thermostats Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hazardous Location Thermostats Market Foresight
Explosion-proof and flameproof certification tiers is reorganizing procurement patterns across hazardous location thermostat supply chains. Honeywell International Inc. leverages its distributed control system integration to anchor thermostat sales within bundled safety instrumented systems. Emerson Electric Co. competes through its Rosemount thermal management portfolio, which extends temperature control capabilities into SIL-rated process loops. R. Stahl Inc. specializes in European ATEX-certified enclosures, occupying a defensible position in chemical processing installations where German engineering standards dominate specification sheets.
Hazardous location thermostats are electromechanical or digital temperature control devices engineered with sealed housings, flame paths, and energy-limiting circuits to operate safely in atmospheres containing flammable gases, vapors, or combustible dusts. These instruments typically maintain setpoint accuracy within one to two degrees Celsius while containing internal arc energies below ignition thresholds of classified gas groups. Digital and programmable thermostat architectures are capturing margin pools as facilities replace aging bimetallic and capillary tube electromechanical units with devices offering remote diagnostics and HART communication protocols. Thermistor and resistance temperature detector sensing technologies are leading technology transitions, while mining and marine operations represent faster-growing application segments as those industries automate climate control in confined hazardous workspaces.
IECEx equipment certification schemes, ATEX Directive 2014/34/EU, and OSHA 29 CFR 1910.307 hazardous location electrical standards collectively define product compliance pathways and market access conditions across manufacturing and end-use jurisdictions. NEMA 7 and 9 enclosure classifications in the United States, alongside IEC 60079 series construction standards, create divergent testing burdens that shape regional manufacturing footprints and certification cost structures. Stakeholders must monitor evolving hydrogen economy infrastructure codes, as emerging H2-specific ignition energy thresholds promise to recast thermostat design specifications for refinery and power-to-gas applications.
Market Dynamics
IECEx and ATEX certification upgrades are forcing manufacturers to abandon legacy electromechanical architectures in favor of digital and programmable thermostat designs with integrated diagnostics capabilities.
Growth Catalysts
- Upstream oil and gas expansion:Offshore platform operators across the United States Gulf Coast are accelerating thermostat replacement programs to meet tightened safety audit schedules.
- ATEX Directive 2014/34/EU:European chemical processing installations must upgrade flameproof enclosures, creating sustained demand for certified temperature control devices.
- HART communication protocols:Digital thermostat architectures with remote diagnostic capabilities are displacing bimetallic and capillary tube units in refinery modernization projects.
Market Restraints
- Certification cost concentration:IEC 60079 series testing burdens fall heavily on smaller manufacturers, compressing margins for non-integrated suppliers.
- Copper and aluminum price volatility:Enclosure fabrication costs fluctuate with commodity markets, destabilizing thermostat pricing structures.
- Electromechanical substitute persistence:Mining operations in developing economies continue specifying capillary tube units due to lower upfront capital requirements.
Strategic Opportunities
- Hydrogen economy infrastructure codes:Emerging H2-specific ignition energy thresholds will recast thermostat specifications for power-to-gas applications in Germany and the Netherlands.
- Marine vessel automation:Confined hazardous workspaces on LNG carriers and tankers present underpenetrated demand for SIL-rated thermal management systems.
- Convergence of thermistor sensing with wireless mesh networks:Integration enables predictive maintenance contracts that unbundle hardware from recurring service revenue streams.
Industry Challenges
- IECEx certification timeline compression:Laboratory backlogs extend product launch schedules by six to nine months, delaying revenue recognition for new digital architectures.
- SIL-rated loop integration complexity:Process engineers face steep learning curves embedding programmable thermostats into existing safety instrumented systems without triggering spurious trip events.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hazardous Location Thermostats Market |
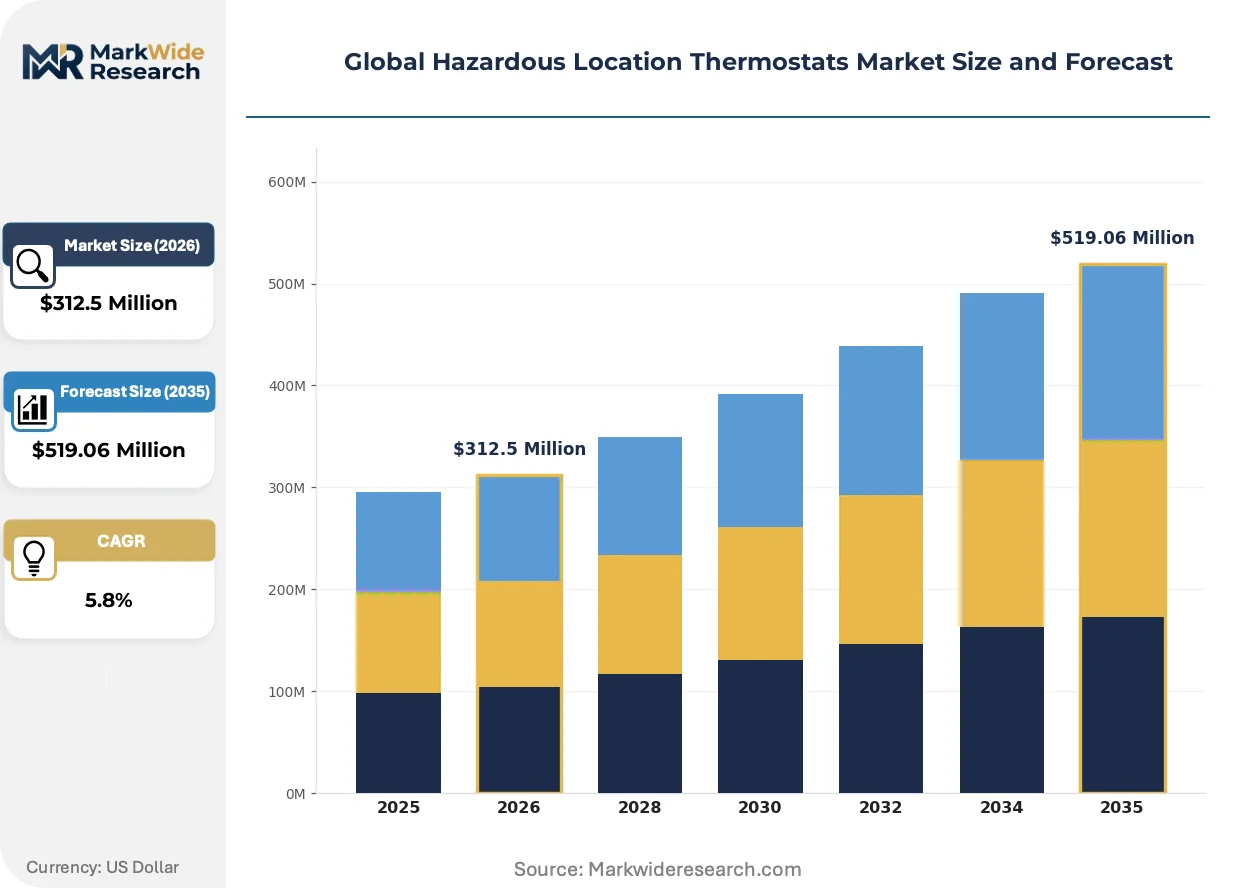
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $519.06 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromechanical, Digital, Programmable, Adjustable, Fixed Setpoint Technology: Thermistor, Bimetallic, Semiconductor, Capillary Tube, Resistance Temperature Detector Application: Oil & Gas, Chemical Processing, Power Generation, Mining, Marine Operations End User: Process Control Facilities, Energy Producers, Mineral Extraction Firms, Shipyards, Petrochemical Plants |
| Companies Covered | Pentair Ltd, Johnson Controls Inc., R. Stahl Inc., Honeywell International Inc., Emerson Electric Co., Schneider Electric SE, Watlow Electric Manufacturing Company, Thermon Group Holdings Inc., OMEGA Engineering Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hazardous Location Thermostats Market Shifts & Advancements
Digital thermostat architectures are actively fragmenting competitive advantage away from mechanical precision toward software-enabled diagnostics and protocol interoperability.
Thermistor and resistance temperature detector sensing technologies is bifurcating the installed base between legacy electromechanical users and facilities demanding HART-enabled remote monitoring. United States petrochemical corridor operators are adopting these sensors at accelerated pace to support predictive maintenance programs. The technology shift is compressing margins for manufacturers lacking firmware development capabilities while expanding service revenue pools for integrated control system vendors.
OSHA 29 CFR 1910.307 enforcement intensification is compelling Gulf Coast refineries to document explosion-proof enclosure integrity through digital audit trails. Industrial consequence includes mandatory replacement of undocumented legacy thermostats during scheduled turnarounds. Offshore platform operators in Texas and Louisiana are responding by specifying programmable units with built-in calibration logging.
Buyer preference is consolidating around bundled safety instrumented system procurement rather than standalone thermostat purchasing. Engineering procurement contractors are displacing direct manufacturer relationships by specifying integrated thermal management within larger automation packages. This concentration is most visible in United States Gulf Coast greenfield petrochemical investments where single-source accountability reduces project risk.
Global Hazardous Location Thermostats Market Segmentation
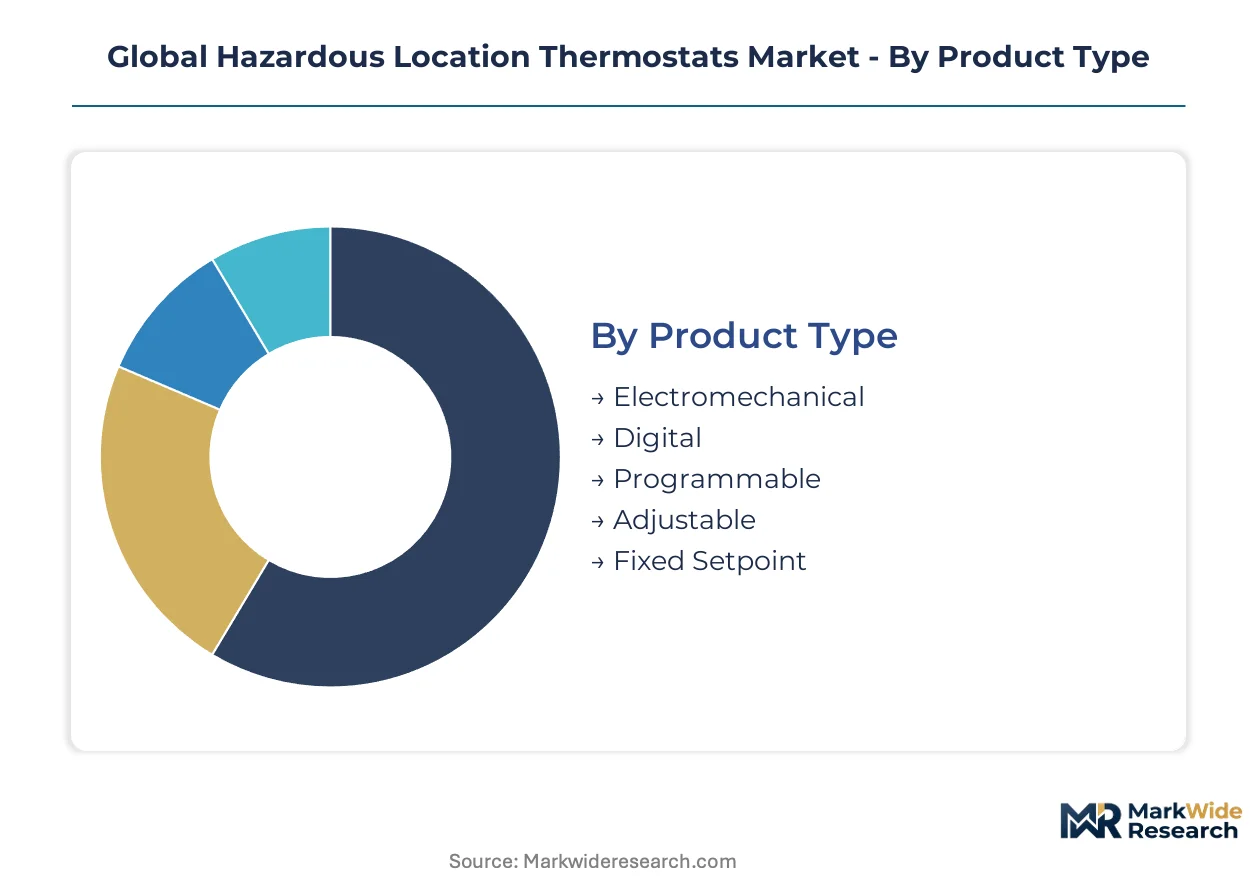
Segmentation in hazardous location thermostats reveals how certification requirements and sensing technologies split procurement budgets across facility types. Product architecture choices determine whether suppliers capture recurring service revenue or one-time hardware sales.
Product Type:
Margin pools concentrate in programmable architectures that bundle firmware licensing with hardware sales, while electromechanical units compete on replacement volume.
- Electromechanical:Bimetallic strip and capillary tube mechanisms deliver setpoint control without external power. Gulf Coast refineries specify these for non-critical heating circuits where SIL ratings are unnecessary.
- Digital:Microprocessor-based units with LCD interfaces and HART protocol support command premium positioning. Offshore platform operators in Texas and Louisiana prioritize these for remote diagnostics capability.
- Programmable:Multi-setpoint devices with integrated data logging serve safety instrumented system loops. German chemical processors specify these for ATEX Zone 1 installations requiring audit trails.
- Adjustable:Field-configurable setpoint mechanisms suit maintenance departments with limited calibration equipment. Mining operations in South Africa favor these for underground climate control.
- Fixed Setpoint:Factory-sealed units eliminate tampering risk in unattended installations. Pipeline compressor stations across the United States specify these for cost-sensitive heating applications.
Electromechanical holds installed capacity. Digital is rotating up the share rankings.
Technology:
Volume leadership sits with legacy sensing methods, though semiconductor and RTD architectures are climbing the specification ladder in process-critical loops.
- Thermistor:Temperature-sensitive resistors offer rapid response times for freeze protection circuits. Petrochemical plants along the Rotterdam-Antwerp-Ghent corridor specify these for outdoor tank heating.
- Bimetallic:Two-metal thermal expansion strips provide mechanical simplicity and intrinsic safety. Aging refineries in Louisiana continue specifying these for blower and pump motor protection.
- Semiconductor:Integrated circuit sensors enable linear output signals for PLC integration. Japanese LNG terminal operators specify these for vaporization skid temperature monitoring.
- Capillary Tube:Remote bulb-and-capillary systems separate sensing elements from hazardous enclosures. Underground coal operations in Poland rely on these for long-distance temperature transmission.
- Resistance Temperature Detector:Platinum wire elements deliver accuracy within fractions of a degree. Power-to-gas pilot facilities in the Netherlands specify these for hydrogen compressor cooling loops.
Bimetallic dominates replacement demand. RTD is climbing specification priority lists in energy transition projects.
Application:
Customer concentration varies sharply: oil and gas commands the largest individual contracts, while marine operations fragment across shipyard procurement schedules.
- Oil & Gas:Upstream, midstream, and downstream operations require Zone-rated thermostats for wellhead heating, pipeline tracing, and vessel climate control. United States shale producers specify SIL-rated units for well pad automation.
- Chemical Processing:Reactor temperature control and solvent storage heating demand ATEX-certified architectures. BASF and Dow facilities in Germany and Texas drive specification standardization.
- Power Generation:Turbine bearing temperature monitoring and switchgear heating require explosion-proof enclosures. Combined cycle plants in Saudi Arabia specify these for gas turbine compartment ventilation.
- Mining:Underground ventilation and equipment heating in coal and metal operations demand dust-ignition protection. South African platinum belt operations specify these for refuge chamber climate control.
- Marine Operations:Engine rooms, cargo tanks, and hazardous material storage on LNG carriers and tankers require marine-certified units. Korean shipyards Daewoo and Hyundai specify these for newbuild contracts.
Oil and gas holds contract value concentration. Marine is expanding most quickly as LNG fleet orders accelerate.
End User:
Procurement authority splits between integrated automation vendors and direct facility purchasing, with shipyards representing the most price-sensitive segment.
- Process Control Facilities:Engineering firms designing distributed control systems specify thermostats within bundled safety packages. Honeywell and Emerson channel partners dominate this procurement path.
- Energy Producers:Utility and independent power producers purchase directly for balance-of-plant heating. Duke Energy and NextEra standardize on programmable architectures for fleet consistency.
- Mineral Extraction Firms:Mining houses with captive engineering departments specify ruggedized electromechanical units. Anglo American and BHP prioritize field-serviceability over remote diagnostics.
- Shipyards:Newbuild construction yards source marine-certified thermostats through classification society-approved vendor lists. Korean and Chinese yards compress margins through competitive tendering.
- Petrochemical Plants:Integrated chemical complexes with in-house reliability teams specify predictive-maintenance-enabled devices. Dow's Freeport, Texas complex mandates HART communication for all new temperature control assets.
Process control facilities anchor specification authority. Shipyards are gaining procurement volume as LNG carrier construction accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in hazardous location thermostats tilt toward net importing in emerging industrial zones while established manufacturing hubs maintain trade surpluses in certified assemblies. Germany and the United States anchor outbound shipment volumes. Gulf Coast petrochemical demand pulls disproportionate import share.
United States
Offshore platform modernization and refinery turnaround cycles drive thermostat replacement intensity along the Texas-Louisiana corridor. OSHA 29 CFR 1910.307 enforcement compels documented explosion-proof integrity through digital audit trails. The Port Arthur-Beaumont-Orange petrochemical triangle concentrates specification authority for SIL-rated programmable units.
Germany
Power-to-gas pilot facilities and hydrogen compressor cooling loops create specification pull for resistance temperature detector architectures. ATEX Directive 2014/34/EU mandates flameproof enclosure upgrades across chemical processing installations. The BASF-Ludwigshafen complex and Ruhr industrial belt standardize programmable thermostat procurement for Zone 1 compliance.
China
LNG terminal vaporization skid automation and coal mining climate control generate bifurcated demand for semiconductor sensors and capillary tube systems. GB standards alignment with IEC 60079 series accelerates domestic certification capacity. Yangtze River Delta shipyards and Sichuan-Chongqing mining equipment fabricators concentrate procurement volume.
South Korea
LNG carrier newbuild construction and tanker hazardous material storage drive marine-certified thermostat demand through Daewoo and Hyundai shipyards. Korean Register classification society approvals filter vendor eligibility. Busan-Ulsan shipbuilding clusters specify integrated thermal management within automation packages.
Netherlands
Rotterdam-Antwerp-Ghent corridor petrochemical plants specify thermistor-based freeze protection for outdoor tank heating. Emerging hydrogen economy infrastructure codes recast ignition energy thresholds for power-to-gas applications. Shell Pernis and Dow Terneuzen facilities mandate HART communication protocols for predictive maintenance enablement.
Global Hazardous Location Thermostats Market Competitive Landscape
Concentration sits with diversified industrial conglomerates possessing captive distribution through safety instrumented system integration. The vendor base stratifies across three tiers: integrated automation platforms, specialized hazardous location enclosure fabricators, and component suppliers serving price-sensitive replacement markets. Dominant competitive moves include backward integration into sensor manufacturing and firmware licensing arrangements that capture recurring revenue streams.
Among diversified industrial conglomerates, Honeywell International Inc. and Emerson Electric Co. exemplify platform-level positioning through bundled thermal management and control system integration. R. Stahl Inc. occupies a specialist tier focused on European ATEX-certified architectures. These three anchors represent distinct strategic postures: conglomerate-scale system integration, process-loop thermal management extension, and regional certification specialization.
| Leading Market Players |
|---|
| Pentair Ltd |
| Johnson Controls Inc. |
| R. Stahl Inc. |
| Honeywell International Inc. |
| Emerson Electric Co. |
| Schneider Electric SE |
| Watlow Electric Manufacturing Company |
| Thermon Group Holdings Inc. |
| OMEGA Engineering Inc. |
| Others |
Supply & Pricing Matrix
IECEx and ATEX certification regimes gate both supplier qualification and price differentiation simultaneously, concentrating margin capture among manufacturers with captive testing capabilities while compressing returns for non-certified assemblers.
Pricing Analysis
Industrial OEM buyers anchor pricing stratification across premium, standard, and economy tiers. Certification grade and firmware licensing bundling drive price differentiation, with SIL-rated programmable units commanding substantial premiums over electromechanical substitutes. Cost compression in standard-tier electromechanical units is intensifying because Korean and Chinese shipyards enforce competitive tendering. Mining operations in South Africa represent the most price-sensitive segment, while German chemical processors show lowest sensitivity due to Zone 1 compliance mandates.
Supply Chain Analysis
Strategic stockpiling of flameproof enclosures and certified electronics characterizes buyer inventory strategy, mitigating IECEx laboratory backlog risks. Manufacturing concentrates in Germany, the United States, and China, with enclosure fabrication drawing from copper, aluminum, and specialized sealing compound inputs. Single-source vulnerability around IEC 60079 testing capacity represents the dominant structural risk. Distribution runs through engineering procurement contractors and safety instrumented system integrators rather than direct manufacturer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital thermostat architectures are disrupting competitive positioning, with HART protocol integration and predictive maintenance enablement recasting procurement criteria across process industries.
For Market Incumbents: Compound firmware licensing revenue by embedding diagnostic capabilities deeper into safety instrumented system loops. Backward integration into thermistor sensor manufacturing defends margin position against component cost volatility. Prioritize ATEX Zone 0 certification investment to preempt emerging hydrogen economy specifications.
For New Entrants and Emerging Players: Predictive maintenance service gaps in marine vessel automation present underexploited white-space opportunity. LNG carrier thermal management systems remain penetrable due to incumbent concentration on land-based process industries. Pursue Korean Register and DNV classification society pre-approval as go-to-market accelerator.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across programmable thermostat architectures due to firmware development and certification testing burdens. Specialist enclosure fabricators with captive ATEX expertise represent attractive acquisition targets within a five-to-ten year industrial automation consolidation window. Monitor IECEx laboratory capacity expansion as inflection indicator for new product launch velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Captive thermistor supply secures margin control against copper price volatility for Honeywell and Emerson. |
| Firmware Licensing Arrangement | Recurring revenue streams from HART protocol diagnostics unbundle hardware from service contracts. |
| ATEX Zone 0 Certification Investment | Early hydrogen economy positioning captures power-to-gas infrastructure specifications in Germany and Netherlands. |
| Marine Classification Society Pre-Approval | Korean Register and DNV listings unlock Daewoo and Hyundai shipyard procurement channels. |
| Predictive Maintenance Platform Launch | Wireless mesh integration enables outcome-based service contracts for Gulf Coast petrochemical operators. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with plant engineers, maintenance directors at petrochemical facilities, OEM procurement teams, safety instrumented system integrators, and aftermarket service heads. Secondary validation drew from IECEx certification registries, ATEX notified body documentation, OSHA enforcement records, SEC 10-K filings of listed industrial conglomerates, and customs trade data. Bottom-up unit shipment estimates triangulated against top-down petrochemical capital expenditure patterns.
Across the analysis window, projections incorporated product architecture transitions, certification upgrade cycles, and regional petrochemical investment trajectories. Segmentation dimensions spanned sensing technology, enclosure protection class, application vertical, and end-user procurement authority. CAGRs were derived from logistic diffusion modeling of digital architecture substitution rates and replacement cycle compression in mature installed bases. Hydrogen economy code evolution and marine vessel automation intensity served as scenario-weighting inputs.
Forecasts assume regulatory continuity in IECEx, ATEX Directive 2014/34/EU, and OSHA 29 CFR 1910.307 regimes; material policy shifts would require re-modeling. Commodity price volatility in copper and aluminum, IECEx laboratory capacity constraints, and hydrogen-specific ignition threshold recalibrations represent primary revision triggers. Revision becomes warranted when marine vessel order backlogs or power-to-gas project commitments cross threshold visibility levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
ECG Sensor Market
Sensors and Controls
Anti-Collision Sensor Market
Sensors and Controls
Europe Pressure Transmitter Market
Sensors and Controls
Motion Sensor Market
Sensors and Controls
3D Profile Sensors Market
Sensors and Controls
Torque Transducer Market
Sensors and Controls
Smart Pressure Gauge Market
Sensors and Controls
Collision Sensors Market
Sensors and Controls
Global Ultrasonic Gas Leak Detector Market
Sensors and Controls
Global Sensors and Actuators Market
Sensors and Controls
Global Sonar Systems and Technology Market
Sensors and Controls
Inline Viscosity Sensor Market
Sensors and Controls
RFID Reader Market
Sensors and Controls
Antenna Transducer and Radome Market
Sensors and Controls
Industrial Transmitters Market
Sensors and Controls
Electric Pipette Controllers Market