
 Canned Mushroom Market | 2026-2036
Canned Mushroom Market Size, Share, and Industry Trends Forecast 2026-2036
Canned Mushroom Market Analysis
Food service buyers is reorganizing procurement priorities toward shelf-stable ingredients that withstand supply volatility. Bonduelle Group leverages its European canning infrastructure to serve contract food manufacturers across multiple countries. Giorgio Fresh Co. anchors North American supply through vertically integrated mushroom farming and processing operations. Monterey Mushrooms Inc. competes on scale, operating one of the largest controlled-environment mushroom production networks in the United States.
Canned mushrooms are Agaricus bisporus or specialty species preserved through blanching, thermal processing in brine or water, and hermetic sealing in metal containers with shelf stability exceeding two years at ambient temperatures; the primary commercial purpose is to deliver consistent, year-round mushroom supply for food manufacturing and food service kitchens without cold-chain dependency. Whole mushrooms command premium positioning in retail channels where visual integrity drives selection, while sliced and diced formats dominate industrial procurement for pizza toppings, soups, and sauces where labor reduction matters. Pouch packaging is gaining traction in European markets seeking lighter freight costs and reduced metal usage, though traditional cans still occupy the bulk of volume in North American wholesale.
The FDA enforces low-acid canned food regulations with strict thermal process filing requirements that shape manufacturing investment and plant certification timelines for domestic producers. The EU's Food Contact Materials Regulation and REACH compliance for can coatings constrain formulation choices and supplier qualification in European markets. Stakeholders must monitor evolving extended producer responsibility rules for packaging waste in multiple jurisdictions, as these will force decisions on material substitution and recycling infrastructure partnerships before the forecast horizon closes.
Market Dynamics
Restaurant chains and ready-meal manufacturers are reorganizing procurement priorities toward shelf-stable ingredients that withstand supply volatility, concentrating purchasing power among large-volume contract buyers who demand multi-year supply agreements.
Growth Catalysts
- EU Food Contact Materials Regulation:Tighter traceability requirements for shelf-stable produce are accelerating investment in automated canning lines with integrated tracking systems across European processing facilities.
- Pizza topping industrial procurement:Sliced and diced formats dominate food manufacturing where labor reduction matters, pulling volume from fresh mushroom suppliers unable to match year-round consistency.
- Po Valley canning clusters:Dense supplier networks near Italian mushroom farms reduce inbound logistics costs and enable just-in-time raw material flows for regional processors.
Market Restraints
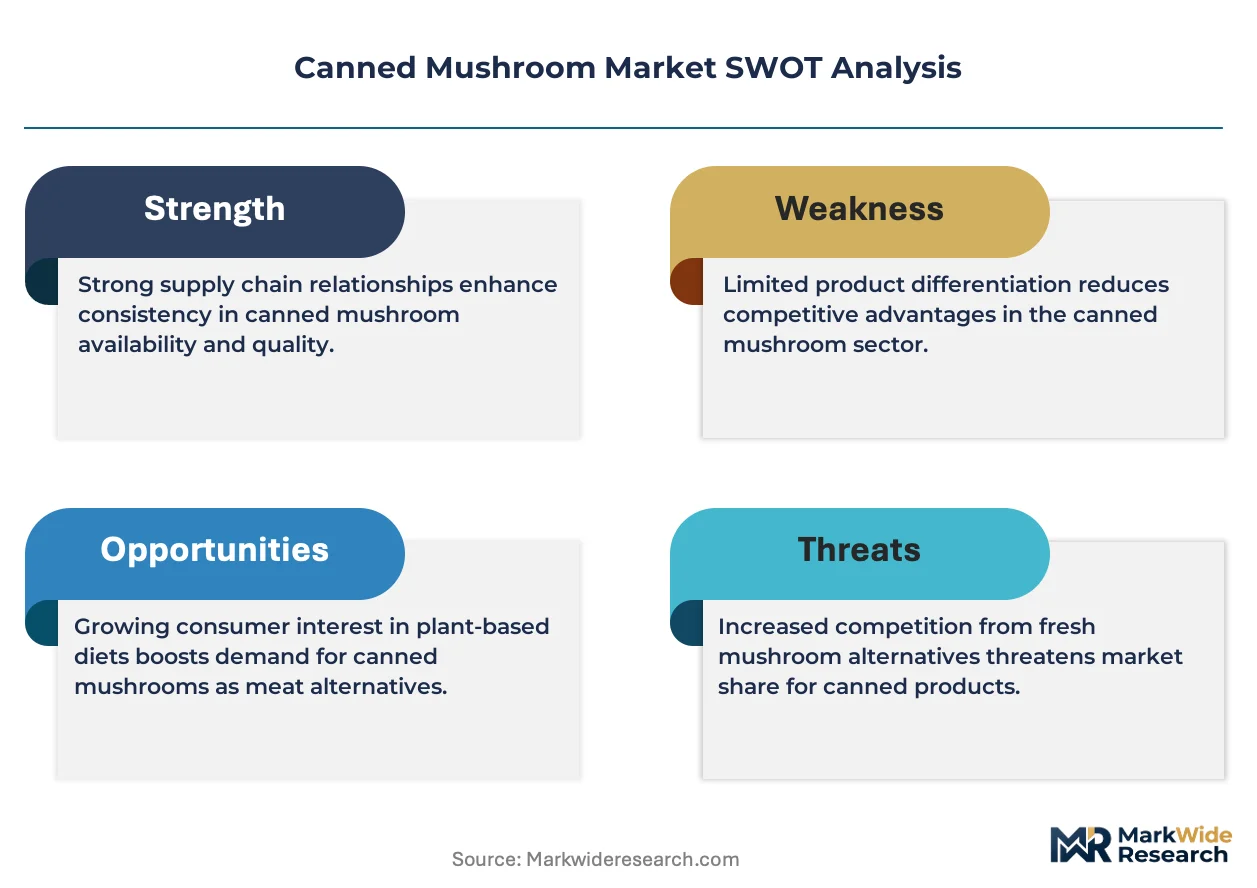
- Steel and tinplate input volatility:Metal container costs fluctuate with commodity markets, compressing margins for canners locked into annual retail price contracts.
- FDA thermal process filing requirements:Strict low-acid canned food regulations extend plant certification timelines and deter new domestic entrants from commercializing novel formats.
- Fresh mushroom substitution:Cold-chain improvements and year-round greenhouse production erode the convenience advantage of canned products in premium food service segments.
Strategic Opportunities
- Flexible pouch packaging:Lighter freight costs and reduced metal usage attract European retail buyers seeking sustainability credentials without shelf-life sacrifice.
- Extended producer responsibility rules:Packaging waste mandates in multiple jurisdictions will force material substitution decisions, rewarding early movers with recycling infrastructure partnerships.
- Specialty species cultivation:Shiitake and oyster mushroom canning commands price premiums in Asian and Mediterranean cuisine segments underserved by standard Agaricus bisporus supply.
Industry Challenges
- Thermal process validation expertise:FDA filing requirements demand specialized food engineering talent scarce outside established canning regions, constraining facility expansion.
- Legacy equipment integration:Automated pouch-filling lines must interface with existing blanching and sorting systems, creating downtime risks during format transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canned Mushroom Market |
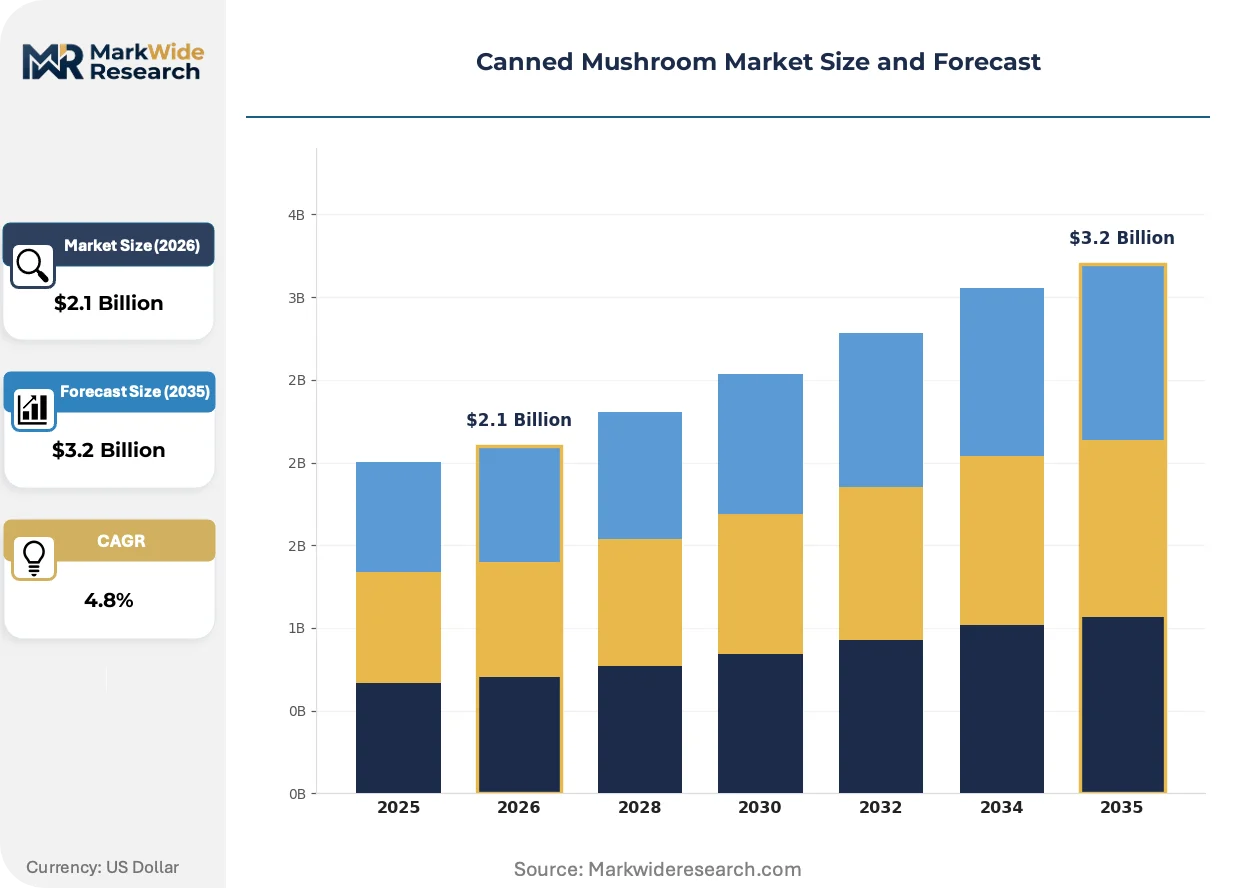
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.2 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole, Sliced, Diced, Stems & Pieces Packaging Type: Cans, Jars, Pouches, Tetra Packs Distribution Channel: Supermarkets, Online Retailers, Convenience Stores, Wholesale End User: Households, Food Service, Industrial, Restaurants |
| Companies Covered | Monterey Mushrooms Inc., Giorgio Fresh Co., Bonduelle Group, Greenyard NV, Okechamp S.A., B&G Foods Inc., Costa Group Holdings Ltd., Prochamp B.V., The Mushroom Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canned Mushroom Market Emerging Trajectories
Processing technology and packaging formats are converging to reduce cold-chain dependency while meeting tightening sustainability mandates from European regulators and North American retail buyers.
Retort pouch packaging is supplanting traditional metal cans in European wholesale channels. Lighter weight reduces freight emissions and handling costs for distributors serving supermarket chains. Bonduelle Group and regional Italian processors are retrofitting filling lines to accommodate this transition, compressing capital recovery timelines for legacy canning equipment.
REACH compliance for can coatings is constraining formulation choices across EU manufacturing. Alternative epoxy-phenolic and polyester coatings require requalification with national food safety authorities. Small and mid-sized canners in Spain and Poland face disproportionate testing burdens, pushing some toward pouch formats to bypass coating complexity entirely.
Food service procurement is consolidating through multi-year supply agreements with volume commitments. Restaurant chains now specify origin traceability and thermal process documentation as standard contract terms. This concentration is most visible in Italy and Germany, where contract manufacturers bundle canned mushrooms with other preserved vegetables to secure preferred supplier status with institutional buyers.
Canned Mushroom Market Segmentation
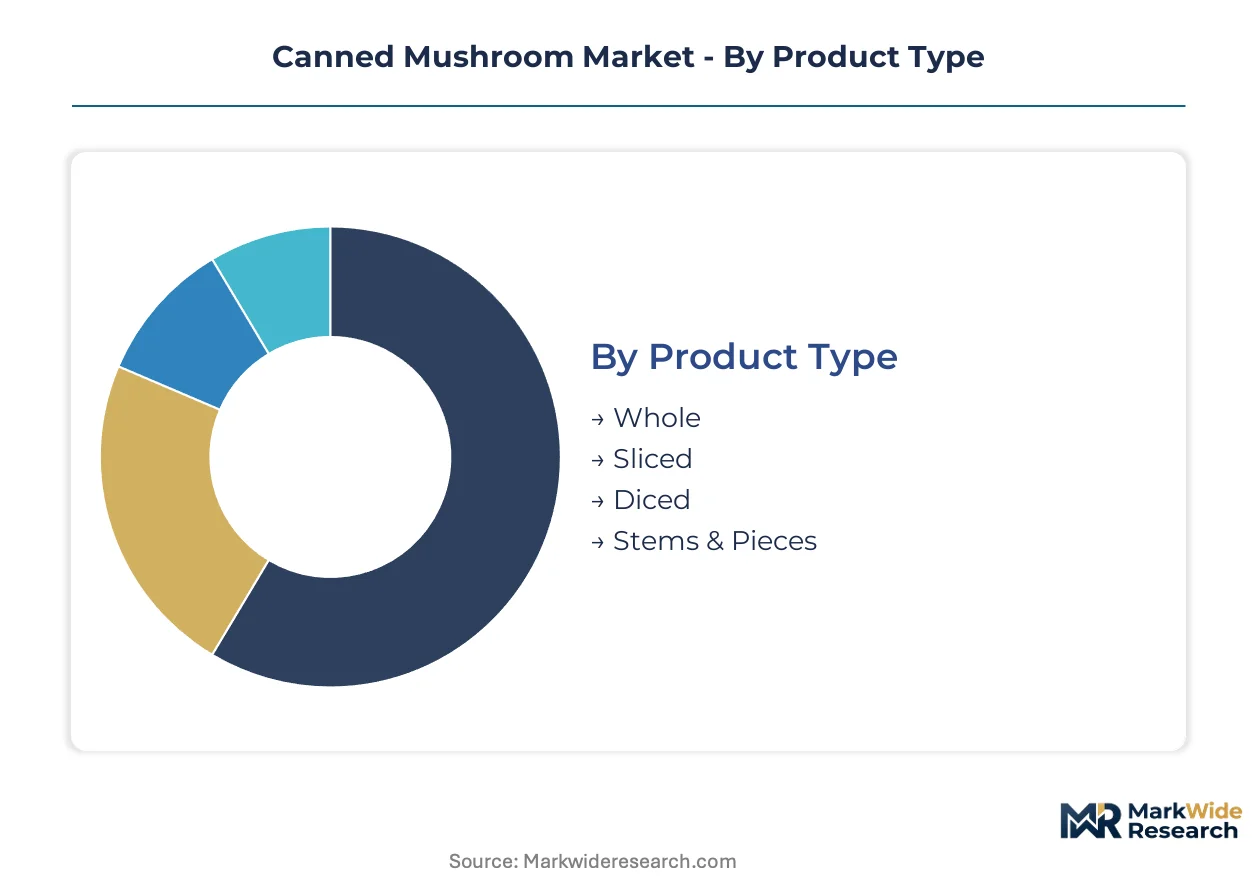
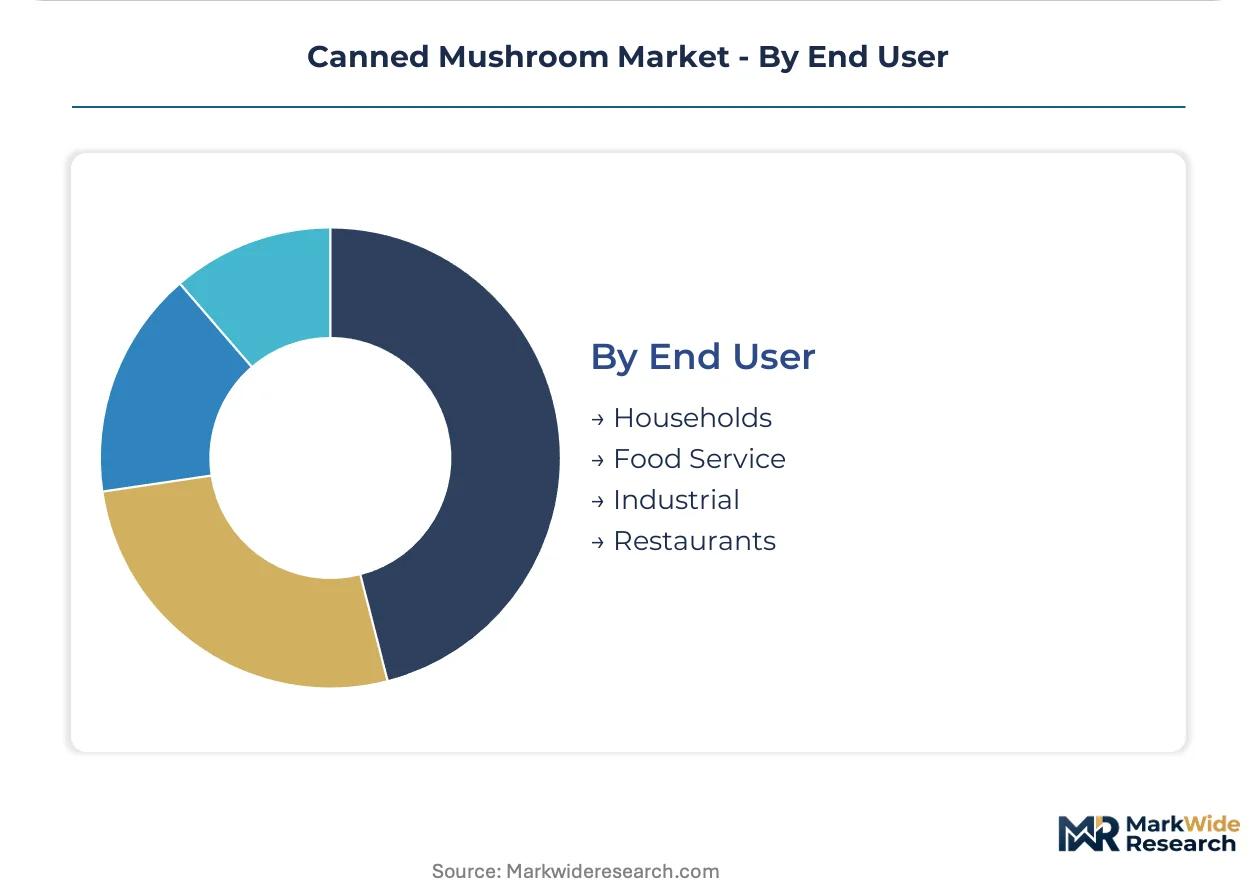
Canned mushroom procurement splits sharply between retail consumers prioritizing visual integrity and industrial buyers optimizing for labor efficiency. Format and packaging choices determine cold-chain independence, shelf stability, and freight economics across divergent use cases.
Product Type:
Fresh mushroom substitution pressure intensifies for formats where greenhouse production now delivers year-round consistency, while processed cuts retain structural advantage in food manufacturing.
- Whole:Intact caps and stems preserved through minimal handling maintain premium positioning in Italian and German retail channels where visual selection drives purchase. Bonduelle Group and Po Valley processors command shelf space in European supermarkets by emphasizing uniform size grading and blemish-free appearance.
- Sliced:Uniform 3-5mm cross-sections eliminate kitchen prep labor for pizza chains and soup manufacturers. Procurement concentrates among North American contract food manufacturers who specify thermal process documentation and origin traceability as standard terms.
- Diced:Small 6-10mm cubes suit sauce applications where rapid hydration and even distribution matter. Ready-meal manufacturers in Germany and France specify diced formats for frozen pasta and risotto products.
- Stems & Pieces:Irregular trimmings from whole mushroom processing deliver cost-efficient volume for institutional catering and ingredient blending. Demand clusters in US food service distributors serving K-12 and healthcare segments.
Whole mushrooms retain volume leadership; sliced formats hold the steepest expansion curve.
Packaging Type:
Material selection pivots on freight cost sensitivity and extended producer responsibility mandates tightening across European jurisdictions.
- Cans:Tinplate and aluminum containers with hermetic double-seamed lids dominate North American wholesale where existing filling infrastructure and retailer familiarity resist format change. FDA low-acid canned food regulations lock in thermal process specifications that deter packaging experimentation.
- Jars:Glass containers with lug or twist-off closures serve premium retail positioning in Mediterranean markets where product visibility supports quality signaling. Italian processors near Parma and Modena maintain jar-filling lines for specialty retail and gift segments.
- Pouches:Multilayer retortable films reduce freight weight and metal usage, attracting sustainability-focused European retail buyers. REACH compliance complexity for can coatings accelerates pouch adoption among Spanish and Polish mid-sized canners seeking to bypass requalification burdens.
- Tetra Packs:Aseptic carton formats remain niche for mushroom products, constrained by retort temperature requirements and limited supplier infrastructure for low-acid shelf-stable foods.
Cans dominate absolute volume; pouches are climbing the fastest.
Distribution Channel:
Channel selection reflects buyer scale and specification complexity, with large-volume procurement consolidating through direct manufacturer relationships.
- Supermarkets:Multi-banner retail chains in Italy, Germany, and France specify origin labeling and organic certification tiers. Private label penetration concentrates purchasing power among Bonduelle Group and regional co-packers.
- Online Retailers:E-commerce platforms capture pantry-stocking and subscription demand, particularly for specialty species and organic variants underserved by conventional retail assortment. Fulfillment economics favor pouch formats for last-mile delivery.
- Convenience Stores:Small-format urban retail in Japan and South Korea stocks single-serve and recipe-ready mushroom products, though ambient shelf-stable formats face competition from refrigerated banchan and deli items.
- Wholesale:Broadline distributors and contract manufacturers bundle canned mushrooms with preserved vegetables to secure preferred supplier status with restaurant chains and institutional buyers.
Supermarkets retain volume leadership; online retailers hold the steepest expansion curve.
End User:
User segmentation tracks cold-chain access and labor cost structure, with industrial procurement most insulated from fresh substitution.
- Households:Retail purchasers in Italy and Spain favor whole and sliced formats for home cooking applications where convenience competes with fresh market proximity. Price sensitivity intensifies during commodity inflation cycles.
- Food Service:Restaurant chains and contract caterers specify sliced and diced formats with multi-year supply agreements. Thermal process documentation and HACCP alignment are non-negotiable contract terms.
- Industrial:Ready-meal manufacturers and sauce processors demand diced and stems-and-pieces for formulation flexibility. Year-round supply consistency outweighs fresh quality premiums in frozen and ambient product lines.
- Restaurants:Independent operators and small chains represent fragmented demand with limited bargaining power, sourcing through broadline distributors rather than direct manufacturer contracts.
Industrial users retain volume leadership; food service holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian processors dominate export flows into Germany and France, while North American supply chains source heavily from Pennsylvania and California growing regions. Cold-chain infrastructure gaps in emerging markets preserve shelf-stable demand, though greenhouse expansion in temperate zones erodes this advantage.
United States
Food service distributors and pizza chains drive procurement of sliced and diced formats with multi-year volume commitments. FDA low-acid canned food regulations enforce strict thermal process filing requirements that extend plant certification timelines. Monterey Mushrooms Inc. operates controlled-environment production networks across Pennsylvania and California, supplying both fresh and processed channels.
Italy
Retail consumers in Lombardy and Emilia-Romagna favor whole mushroom formats where visual integrity supports quality signaling. EU Food Contact Materials Regulation and REACH compliance for can coatings constrain formulation choices across Po Valley processing clusters. Bonduelle Group maintains dense canning infrastructure near Parma and Modena, serving contract manufacturers across Germany and France.
Germany
Ready-meal manufacturers specify diced formats for frozen pasta and risotto products requiring rapid hydration. Extended producer responsibility rules for packaging waste accelerate material substitution decisions among importers. Distributors in North Rhine-Westphalia bundle canned mushrooms with preserved vegetables to secure preferred supplier status with institutional buyers.
Spain
Mid-sized canners face disproportionate testing burdens for REACH-compliant can coating requalification. Alternative epoxy-phenolic and polyester coatings require national food safety authority approval. Processors near Valencia and Catalonia retrofit filling lines toward pouch formats to bypass coating complexity entirely.
Poland
Private label penetration concentrates purchasing power among regional co-packers serving German and UK supermarket chains. EU Green Deal sustainability mandates push processors toward lighter packaging formats with reduced metal usage. Facilities near Warsaw and Łódź invest in automated pouch-filling lines to capture sustainability-focused retail buyers.
Canned Mushroom Market Vendor Landscape
Player mix skews toward vertically integrated agricultural operators with captive raw material supply. Structure concentrates among three to five dominant processors controlling canning infrastructure near major growing regions. Strategic archetypes split between scale-driven commodity suppliers, specialty species cultivators, and private-label co-packers with flexible format capabilities. Competitive moves center on backward integration into mushroom farming and geographic expansion through distributor partnerships.
Within the integrated-processor tier, Bonduelle Group S.A. and Giorgio Fresh Co. exemplify archetypes of European canning infrastructure leverage and North American vertical farming control respectively. Monterey Mushrooms Inc. anchors the scale-driven commodity segment with multi-state production networks. These three occupy positions that reflect divergent responses to regulatory pressure and format transition costs.
| Leading Market Players |
|---|
| Monterey Mushrooms Inc. |
| Giorgio Fresh Co. |
| Bonduelle Group |
| Greenyard NV |
| Okechamp S.A. |
| B&G Foods Inc. |
| Costa Group Holdings Ltd. |
| Prochamp B.V. |
| The Mushroom Company |
| Others |
Supply Flow & Price Mechanics
Ninety-day raw material inventory cycles at Po Valley canning clusters concentrate procurement leverage among Bonduelle Group and regional processors, translating inbound logistics efficiency into pricing power over fragmented Italian mushroom growers. This inventory-to-pricing linkage tightens when steel and tinplate input volatility compresses margins for canners locked into annual retail contracts.
Pricing Analysis
Legacy canning technology versus automated pouch-filling lines versus next-generation aseptic formats creates a three-tier pricing structure across premium, standard, and economy levels. Contract-based long-term offtake dominates industrial procurement, with price differentiation driven by volume scale and FDA thermal process certification tier. Cost compression in standard canned formats is intensifying because REACH compliance complexity for can coatings forces reformulation investments. Food service buyers exhibit highest price sensitivity due to multi-year volume commitments, while retail private label channels absorb premiums for organic certification and origin traceability.
Supply Chain Analysis
Po Valley logistics corridors connecting Parma and Modena processing clusters to German distribution hubs represent a chokepoint that concentrates EU supply flows. Italy, the United States, and Poland anchor global production, with raw material dependencies spanning tinplate from European steel mills, retort pouch films from Asian converters, and Agaricus bisporus spawn from specialized Dutch suppliers. Single-source vulnerability in can coating formulations exposes mid-sized Spanish and Polish canners to REACH requalification delays. Distribution runs through broadline food service distributors and contract manufacturers bundling preserved vegetables for institutional buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Retort pouch packaging technology and EU extended producer responsibility mandates are disrupting competitive positioning in shelf-stable produce, compressing capital recovery timelines for legacy canning infrastructure. This regulatory-technological inflection creates asymmetric opportunities across incumbent defense, entrant attack patterns, and capital allocation frameworks.
For Market Incumbents: Fortify backward integration into captive mushroom farming to secure raw material margin control against fresh greenhouse substitution pressure. Expand automated pouch-filling capacity in Poland and Spain to preempt REACH compliance burdens on can coatings, while locking multi-year supply agreements with German ready-meal manufacturers to defend volume base. For New Entrants and Emerging Players: Lead with specialty species cultivation—shiitake and oyster mushroom canning for Asian and Mediterranean cuisine segments—where Agaricus bisporus supply gaps command price premiums. Target online retail channels in European markets where pouch format sustainability credentials resonate with subscription pantry buyers, deploying direct-to-food-manufacturer sampling programs to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across pouch-format processing as equipment modularity reduces scale thresholds for viable entry. Five-to-ten year viability favors acquisition of mid-sized Polish and Spanish canners with flexible format capabilities and established private label relationships. Monitor EU Green Deal packaging waste mandate implementation timelines as the signal for material substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mushroom Farming | Giorgio Fresh Co. and Monterey Mushrooms Inc. demonstrate how captive raw material supply insulates margin pressure from fresh substitution. |
| Retort Pouch Line Retrofit | Bonduelle Group investments in flexible packaging bypass REACH coating complexity while capturing sustainability-focused European retail buyers. |
| Specialty Species Cultivation Expansion | Shiitake and oyster canning commands price premiums in underserved Asian and Mediterranean cuisine segments. |
| Multi-Year Supply Agreement Consolidation | German ready-meal manufacturers now specify thermal process documentation as standard contract terms, concentrating purchasing power. |
| Recycling Infrastructure Partnership | Early movers in extended producer responsibility compliance secure preferred supplier status with supermarket chains facing packaging waste mandates. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with mushroom farm operators, canning plant managers, food service procurement directors, and ready-meal manufacturer supply chain leads; and secondary validation through FDA low-acid canned food filing databases, EU Food Contact Materials Regulation compliance registries, customs trade data on tinplate and aluminum container imports, and SEC filings from publicly traded processors. Bottom-up volume modeling triangulated against top-down expenditure estimates from food manufacturing and food service sectors.
Across the projection horizon, the analytical framework modeled segmentation dimensions including product format, packaging type, distribution channel, and end-user industry, with CAGRs derived from trend extrapolation of procurement pattern shifts and regulatory implementation timelines. Forecast inputs incorporated steel and tinplate commodity price volatility assumptions, greenhouse fresh mushroom production expansion curves, and EU packaging waste mandate enforcement schedules.
Forecasts assume regulatory continuity in FDA low-acid canned food enforcement and EU REACH compliance regimes; material policy shifts would require re-modeling of plant certification timelines and coating formulation costs. Specific risk factors include accelerated fresh mushroom substitution from controlled-environment agriculture, abrupt steel tariff adjustments, and extended producer responsibility rule acceleration beyond baseline assumptions. Practitioners should keep alternative scenarios live as cold-chain infrastructure gaps in emerging markets and sustainability credential preferences in European retail evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Canned Beans Market
Packaged Foods
Dehydrated and Dried Beans Market
Packaged Foods
Ready to Use Fillings Market
Packaged Foods
South America Canned Fruits Market
Packaged Foods
Europe Free from Food Market
Packaged Foods
High-End Instant Noodles Market
Packaged Foods
Peanut Butter Market
Packaged Foods
Asia-Pacific Breakfast Cereals Market
Packaged Foods
Packaged Vegan Foods Market
Packaged Foods
Tortilla Market
Packaged Foods
North America Breakfast Cereals Market
Packaged Foods
Global Packed Food Market
Packaged Foods
Mexico Packaged Food Products Market
Packaged Foods
Protein Packed Foods Market
Packaged Foods
Cookie Pucks Market
Packaged Foods
Microwavable Foods Market