
 Calorimeters Market | 2026-2036
Calorimeters Market Size, Share, and Industry Trends Forecast 2026-2036
Calorimeters Market Outlook
Pharmaceutical buyer concentration is rebalancing as large drug developers consolidate thermal analysis procurement while mid-tier biotechs fragment demand across specialized vendors. TA Instruments leverages its North American service infrastructure to anchor long-term contracts with top-20 pharma accounts. METTLER TOLEDO competes through precision weighing integration that streamlines sample preparation workflows. Shimadzu Corporation dominates Asian academic and industrial research channels with localized application support.
Calorimeters are precision thermal analysis instruments that measure heat flow, heat capacity, and enthalpic changes in materials under controlled temperature programs, typically operating across ranges from -180°C to 700°C or higher depending on furnace configuration; their primary purpose spans reaction kinetics characterization, phase transition mapping, and safety screening for energetic materials. Differential scanning calorimeters lead product type revenue due to universal applicability across polymer and pharmaceutical matrices, while isothermal titration calorimeters capture expanding margin pools from biophysical drug discovery workflows. Conventional calorimetry technology remains the volume backbone, though micro calorimetry is displacing legacy methods in protein-ligand binding studies where sample scarcity demands nanowatt sensitivity.
US FDA guidance on thermal analytical methods for biologics, EPA combustion efficiency standards for solid waste characterization, and REACH substance registration requirements in Europe collectively elevate instrument calibration traceability and documentation burdens. Germany's KBA and France's ANSM enforce complementary material testing protocols that shape regional product specifications and market access conditions. Stakeholders must monitor evolving pharmacopeial harmonization between FDA and EMA thermal analysis chapters to anticipate validation protocol shifts that will determine competitive instrument replacement cycles.
Market Dynamics
Pharmaceutical procurement consolidation is compressing vendor margins while micro calorimetry's nanowatt sensitivity requirements are fragmenting R&D instrumentation budgets across specialized suppliers.
Growth Catalysts
- Biologics certification mandates:FDA guidance on thermal analytical methods for biologics is forcing drug developers to expand calorimeter validation protocols, accelerating instrument replacement cycles in quality control laboratories.
- Protein-ligand binding research:Micro calorimetry is capturing expanding workflows in biophysical drug discovery where sample scarcity demands extreme thermal sensitivity, pulling capital from legacy DSC installations.
- German precision manufacturing:Stuttgart and Karlsruhe host dense clusters of instrument suppliers serving pharmaceutical and materials science end-users, creating localized ecosystem effects that reduce procurement friction.
Market Restraints
- Platinum sensor cost volatility:DSC furnace assemblies depend on platinum-rhodium thermocouples, exposing manufacturers to precious metal price swings that compress gross margins on mid-range systems.
- Calibration traceability burdens:REACH substance registration requirements in Europe and EPA combustion efficiency standards collectively lengthen validation timelines, delaying revenue recognition on new installations.
- Optical calorimetry substitution:Photothermal spectroscopy methods are displacing conventional heat-flux measurements in certain polymer characterization workflows, eroding addressable market for entry-level DSC units.
Strategic Opportunities
- Cell and gene therapy workflows:Cryopreservation stability testing for viral vectors and lipid nanoparticles represents an underpenetrated application requiring specialized low-temperature calorimetry configurations.
- India's PLI scheme for precision instruments:Domestic manufacturing incentives are creating new channel structures for cost-optimized calorimeter assembly, opening price-accessible segments for academic and SME buyers.
- Cloud-native data architecture:Convergence of IoT-enabled calorimeters with laboratory information management systems is enabling predictive maintenance revenue streams and consumables subscription models.
Industry Challenges
- Metrology technician scarcity:Qualified personnel for thermal analysis instrument calibration and repair are concentrated in legacy manufacturing regions, constraining service expansion into emerging markets.
- Legacy software integration:Pharmaceutical buyers require seamless data exchange with 21 CFR Part 11 compliant systems, forcing vendors to maintain expensive parallel development tracks for modern and obsolete protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calorimeters Market |
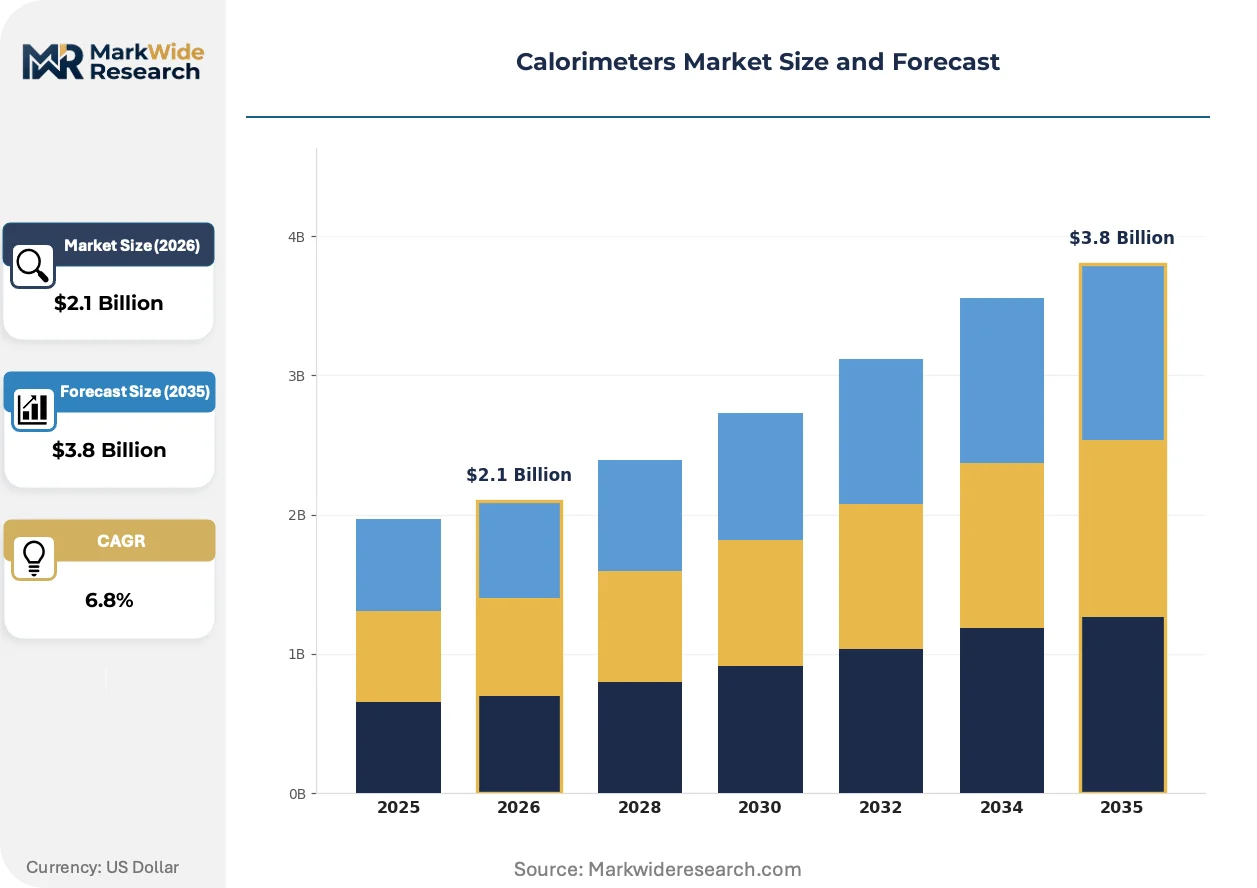
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Differential Scanning Calorimeters, Isothermal Titration Calorimeters, Bomb Calorimeters, Thermal Conductivity Calorimeters End User: Research Laboratories, Pharmaceutical Companies, Food & Beverage Industry, Academic Institutions Technology: Conventional Calorimetry, Online Calorimetry, Micro Calorimetry, Optical Calorimetry Application: Material Testing, Energy Measurement, Drug Development, Quality Control |
| Companies Covered | TA Instruments, METTLER TOLEDO, Shimadzu Corporation, NETZSCH Instruments, Parr Instrument Company, Hanna Instruments, Yokogawa Electric Corporation, IKA, Malvern Panalytical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calorimeters Market Strategic Shifts
Modular hardware architectures and AI-assisted thermal curve interpretation are compressing the expertise barrier for calorimeter operation, enabling broader deployment beyond specialist research laboratories.
Micro differential scanning calorimetry is decentralizing protein stability screening from centralized core facilities into individual drug discovery teams. Biotech start-ups are adopting benchtop µDSC units for rapid formulation triage. This technology is decentralizing capital allocation decisions and shortening feedback loops between synthesis and thermal characterization.
EMA's evolving pharmacopeial harmonization with FDA thermal analysis chapters is tightening cross-border instrument qualification requirements. Manufacturers must now maintain dual validation documentation for systems sold across Atlantic markets. European CMOs serving US-exporting pharma clients are upgrading to highest-tier calibration packages to preempt audit findings.
Service unbundling is fragmenting long-term instrument contracts into discrete calibration, repair, and application support purchases. Academic buyers in Asia-Pacific markets are favoring a la carte service models over comprehensive maintenance agreements. This pattern is most visible in Japan, where METI-funded research institutes face constrained operational budgets and prioritize capital preservation over fixed service commitments.
Calorimeters Market Segmentation
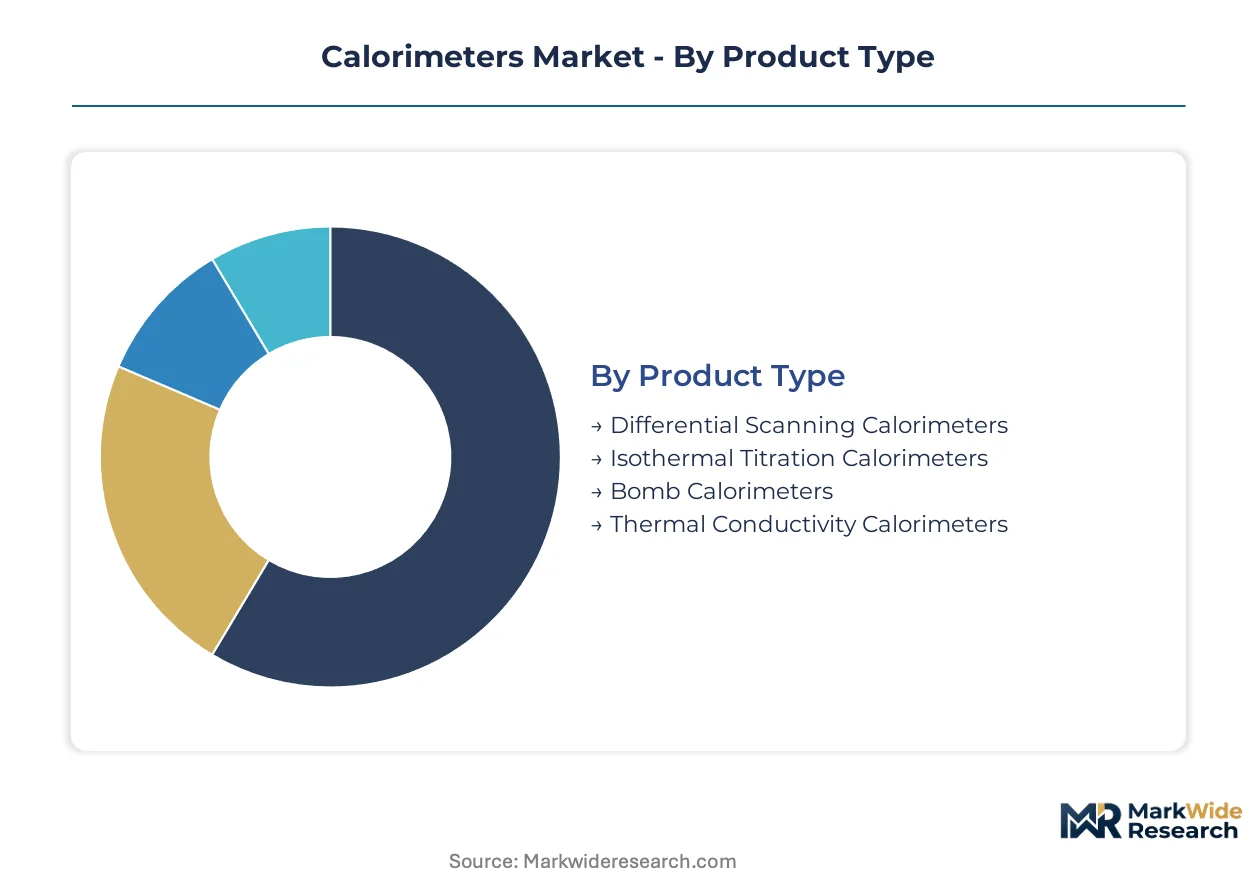
Calorimeter procurement patterns diverge sharply across product architectures and end-use workflows. Upgrade cycles accelerate where regulatory validation requirements tighten, while budget constraints in academic channels extend replacement timelines for legacy systems.
Product Type:
Replacement demand concentrates in systems where platinum sensor degradation and software obsolescence compound validation risks.
- Differential Scanning Calorimeters:Heat-flux and power-compensation configurations measure enthalpy changes across polymer and pharmaceutical matrices. Pharmaceutical quality control laboratories in Germany drive replacement cycles as EMA pharmacopeial harmonization tightens instrument qualification protocols.
- Isothermal Titration Calorimeters:These systems quantify binding thermodynamics for protein-ligand interactions with nanowatt sensitivity. Biotech drug discovery teams in Cambridge, Massachusetts and Basel, Switzerland are displacing legacy DSC capital with µITC installations for fragment-based screening workflows.
- Bomb Calorimeters:Adiabatic and isoperibol designs determine combustion enthalpies for solid fuels and waste materials.
- Thermal Conductivity Calorimeters:These units monitor heat flow in battery cells and energetic materials under thermal abuse conditions.
Volume placements concentrate in Differential Scanning Calorimeters; the faster expansion belongs to Isothermal Titration Calorimeters.
End User:
Procurement authority is consolidating where contract manufacturing organizations absorb thermal analysis capacity from fragmented biotech sponsors.
- Pharmaceutical Companies:Large drug developers centralize thermal analysis procurement under quality assurance departments. FDA guidance on biologics certification is forcing top-20 pharma accounts to upgrade validation protocols, compressing replacement cycles from seven to five years.
- Research Laboratories:Core facilities at US National Laboratories and Max Planck Institutes maintain diverse calorimeter fleets. Budget pressures at DOE-funded sites are extending service contracts rather than acquiring new optical calorimetry platforms.
- Academic Institutions:University core facilities face constrained capital budgets and prioritize multi-user accessibility.
- Food & Beverage Industry:Processors deploy calorimeters for fat content verification and shelf-life prediction.
Revenue concentration sits with Pharmaceutical Companies; Academic Institutions are gaining share fastest as research funding recovers.
Technology:
Capital allocation is fragmenting as nanowatt sensitivity requirements pull budgets toward specialized microcalorimetry platforms.
- Micro Calorimetry:Nanowatt-resolution systems enable protein stability screening with microgram sample quantities. Biophysical drug discovery workflows at Scripps Research and the Francis Crick Institute are displacing conventional DSC methods for lead optimization studies.
- Conventional Calorimetry:Heat-flux and power-compensation DSC remain the volume backbone across polymer and materials science applications. Industrial R&D departments in Japan's chemical sector favor these systems for routine phase transition mapping.
- Online Calorimetry:Process analytical technology configurations enable real-time reaction monitoring.
- Optical Calorimetry:Photothermal methods are eroding addressable market for entry-level DSC in certain polymer characterization workflows.
Installed base dominance remains with Conventional Calorimetry; Micro Calorimetry is climbing the fastest as sample scarcity reshapes biophysical workflows.
Application:
Validation protocol complexity is elevating instrument specification tiers where regulatory submission risks concentrate.
- Drug Development:Formulation scientists deploy calorimeters for excipient compatibility, polymorph screening, and lyophilization cycle optimization. FDA's updated thermal analysis guidance for biologics is forcing CMOs serving US-exporting clients to upgrade to highest-tier calibration packages.
- Quality Control:Release testing laboratories require 21 CFR Part 11 compliant data systems with complete audit trails. European CMOs are unbundling service contracts into discrete calibration purchases to manage operational expenditure.
- Material Testing:Aerospace and automotive suppliers characterize composite cure kinetics and thermal stability.
- Energy Measurement:Waste-to-energy facilities and solid fuel processors depend on bomb calorimetry for combustion efficiency compliance.
Instrument placements concentrate in Quality Control; Drug Development is expanding most quickly as biologics pipelines mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical quality control procurement concentrates in Germany and the United States, where regulatory validation requirements compress instrument replacement cycles. Academic research demand fragments across Japan and India, shaped by funding availability and domestic manufacturing incentives.
Germany
Bomb calorimeter demand from drug stability testing laboratories accelerates procurement volumes. KBA enforces material testing protocols that elevate instrument calibration documentation burdens. Stuttgart and Karlsruhe host dense precision-instrument manufacturing clusters where NETZSCH Instruments and IKA anchor supplier ecosystems serving pharmaceutical end-users.
United States
Large drug developers consolidate thermal analysis procurement under quality assurance departments, tightening vendor selection criteria. FDA guidance on thermal analytical methods for biologics forces expanded validation protocols across quality control laboratories. Greater Boston and Research Triangle Park concentrate biotech drug discovery teams adopting micro calorimetry for protein-ligand binding studies.
Japan
Academic core facilities favor a la carte service models over comprehensive maintenance agreements as operational budgets tighten. METI-funded research institutes face capital constraints that extend replacement timelines for legacy systems. Tokyo and Osaka metropolitan areas concentrate university core facilities maintaining diverse calorimeter fleets for materials science research.
India
Domestic manufacturing incentives under the PLI scheme for precision instruments create new channel structures for cost-optimized calorimeter assembly. CDSCO alignment with international pharmacopeial standards elevates instrument qualification requirements for contract manufacturers. Maharashtra and Gujarat host emerging assembly operations targeting price-accessible segments for academic and SME buyers.
France
Contract manufacturing organizations serving US-exporting pharma clients upgrade to highest-tier calibration packages to preempt audit findings. ANSM enforces complementary material testing protocols that shape regional product specifications. Paris-Saclay research cluster concentrates biophysical drug discovery workflows driving isothermal titration calorimeter demand.
Calorimeters Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue cloud-native data architectures and modular hardware configurations. The vendor base stratifies across precision instrument conglomerates, specialized thermal analysis houses, and diversified laboratory equipment suppliers. Three archetypes dominate: integrated precision weighing specialists, precision thermal analysis pure-plays, and diversified analytical instrumentation conglomerates. Competitive moves concentrate on service infrastructure expansion and predictive maintenance revenue model development.
Within the precision thermal analysis tier, TA Instruments and NETZSCH Instruments exemplify archetypes differentiated by regional service density. METTLER TOLEDO represents the integrated precision weighing specialist model. Among Asian-based analytical instrumentation houses, Shimadzu Corporation occupies a position bridging academic and industrial research channels. These three anchors illustrate how geographic origin and corporate structure shape competitive positioning without determining specific strategic outcomes.
| Leading Market Players |
|---|
| TA Instruments |
| METTLER TOLEDO |
| Shimadzu Corporation |
| NETZSCH Instruments |
| Parr Instrument Company |
| Hanna Instruments |
| Yokogawa Electric Corporation |
| IKA |
| Malvern Panalytical |
| Others |
Value Chain & Pricing Dynamics
Metrology technician scarcity in Stuttgart and Karlsruhe amplifies labor-cost differentials between German precision clusters and emerging assembly hubs, widening pricing-tier spreads across premium validation-grade systems and cost-optimized academic configurations.
Pricing Analysis
Volume placements cluster in conventional heat-flux DSC systems where price differentiation rests on calibration certification tiers and platinum sensor quality grades. Pricing pressure stems from optical calorimetry substitution eroding entry-level DSC margins, while biotech drug discovery teams show least price sensitivity for nanowatt-sensitivity microcalorimetry platforms.
Supply Chain Analysis
India's PLI scheme for precision instruments is reshaping sourcing patterns for cost-optimized calorimeter assembly, drawing component flows from Germany, Japan, and the United States. Platinum-rhodium thermocouple supply rests on South African and Russian mining output, exposing furnace manufacturers to commodity price volatility. Distribution runs through authorized service networks that bundle installation with validation documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified calibration technician scarcity props pricing power for incumbent service networks, constraining capacity expansion into emerging markets.
For Market Incumbents: Hedge against optical calorimetry substitution by deepening application support for biologics validation workflows. Anchor long-term contracts with top-20 pharmaceutical accounts through predictive maintenance subscriptions. Expand certification investment in 21 CFR Part 11 compliant data architectures to preempt software obsolescence risks. For New Entrants and Emerging Players: Begin with cloud-native data platforms targeting academic core facilities in Asia-Pacific markets where a la carte service models are displacing comprehensive maintenance agreements. India's PLI scheme creates channel access for cost-optimized assembly targeting SME buyers. Lead with modular hardware configurations that compress expertise barriers for non-specialist operators. For Investors and Strategic Acquirers: Re-rating potential sits with precision thermal analysis pure-plays given EMA-FDA pharmacopeial harmonization tightening cross-border instrument qualification requirements. Five-to-ten year viability favors vendors with captive service infrastructure in German manufacturing clusters. Monitor platinum price trajectories as inflection indicator for gross margin compression on mid-range systems.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Subscription Launch | Recurring revenue streams lock in pharmaceutical quality control laboratories facing FDA validation pressures. |
| Cloud-Native LIMS Integration | IoT-enabled calorimeters enable consumables subscription models and remote diagnostic capabilities. |
| Modular Hardware Architecture Development | Swappable furnace configurations reduce downtime for biotech teams running diverse thermal protocols. |
| Dual Validation Documentation Investment | Parallel FDA-EMA qualification packages preempt audit findings for European CMOs serving US-exporting clients. |
| Regional Service Hub Expansion | Localized calibration capabilities address metrology technician scarcity constraining emerging market penetration. |
Study Parameters
Independent corroboration across thermal analysis instrument manufacturers, pharmaceutical quality control directors, and academic core facility managers underwrites the qualitative findings. Primary fieldwork engaged regulatory affairs specialists at EMA-notified bodies and EPA compliance officers alongside procurement leads at contract manufacturing organizations. Secondary validation drew from FDA guidance documents, REACH substance registration databases, and pharmacopeial harmonization working papers. Bottom-up installation data triangulated against top-down capital expenditure disclosures from precision instrument conglomerates.
Rate-of-change decomposition across product type, end user, technology, and application dimensions structured the analytical framework over the projection horizon. CAGRs derived from replacement cycle compression in pharmaceutical quality control laboratories and capital allocation shifts toward microcalorimetry in biophysical drug discovery. Modeled inputs incorporated platinum price trajectories, pharmacopeial chapter revision timelines, and domestic manufacturing incentive uptake under India's PLI scheme.
EMA-FDA harmonization delays, platinum supply disruptions, and optical calorimetry technology maturation are the dominant revision risks to instrument placement forecasts. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Analog Multimeters Market
Test and Measurement
Sound Meter Market
Test and Measurement
Hardware-Assisted Verification Market
Test and Measurement
Compression Testing Machines Market
Test and Measurement
Global Conductivity Meters Market
Test and Measurement
Ethernet Test Equipment Market
Test and Measurement
Digital Inspection Tools Market
Test and Measurement
Tensile Testers Market
Test and Measurement
Digital Moisture Meters Market
Test and Measurement
Electric Vehicle Edrive Test System Market
Test and Measurement
In-Situ Layer-by-Layer AM Defect Monitoring Test Equipment Market
Test and Measurement
Digital Depth Gauges Market
Test and Measurement
RF Test Equipment Market
Test and Measurement
Asia-Pacific Laser Interferometer Market
Test and Measurement
Non-Destructive Testing (NDT) Service Market
Test and Measurement
Industrial Direct Radiography Market