
 Insulated Icebox Market | 2026-2036
Insulated Icebox Market Size, Share, and Industry Trends Forecast 2026-2036
Insulated Icebox Market Analysis
Market Context
Rotomolded polyethylene construction is tilting insulated icebox manufacturing toward thicker-wall, multi-day ice retention designs. YETI leverages its premium brand positioning to command shelf space in specialty outdoor retailers. Igloo sustains mass-market volume through broad distribution at big-box chains. RTIC Outdoors competes on price-point proximity while matching performance claims of higher-tier rivals.
Technical Definition and Segment Structure
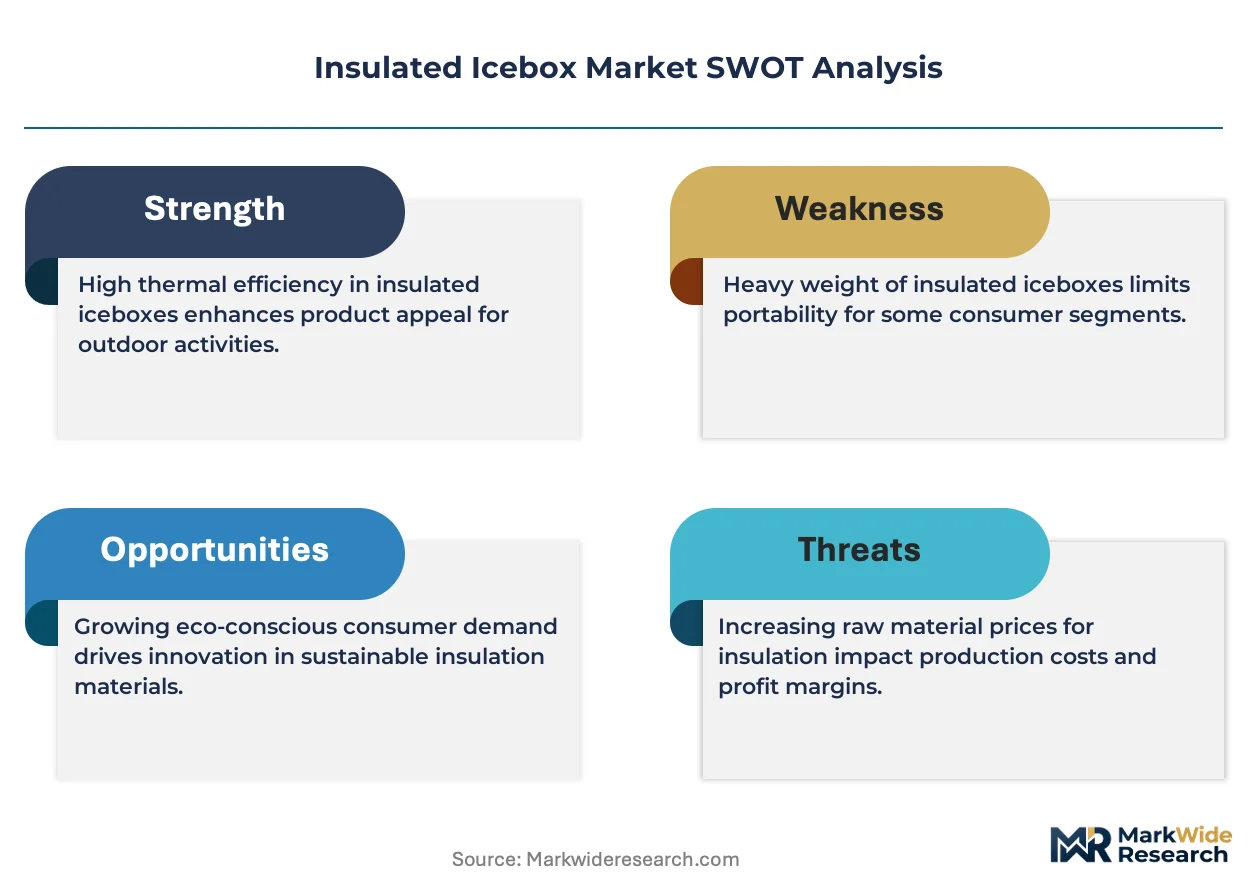
An insulated icebox is a thermally insulated container, typically employing polyurethane foam between plastic or metal walls with gasket-sealed lids, designed to maintain sub-ambient temperatures for perishable goods without active refrigeration. Hard-shell coolers anchor commercial revenue due to durability expectations in marine and expedition applications, while electric coolers represent the fastest-expanding category as vehicle-accessory power integration improves. Soft-sided coolers concentrate margin pools in the hospitality sector where portability and brand aesthetics drive replacement cycles.
Regulatory Environment and Outlook
The US EPA regulates foam-blowing agents under the AIM Act, pushing manufacturers toward hydrofluoroolefin alternatives with lower global warming potential. California's SB 1013 restricts high-GWP substances in consumer products, directly affecting insulated icebox supply chains serving West Coast distribution. The Consumer Product Safety Commission monitors lead content in metal components and phthalates in flexible vinyl liners. Stakeholders must monitor state-level chemical restriction trajectories to preempt reformulation costs and maintain multi-channel market access.
Market Dynamics
The US EPA's phasedown of hydrofluorocarbon refrigerants under the AIM Act is forcing manufacturers to reformulate foam insulation systems, compressing margins for legacy polyurethane-dependent producers while advantaging vacuum-insulated panel adopters.
Growth Catalysts
- AIM Act refrigerant mandates:The US EPA's hydrofluorocarbon restrictions are accelerating substitution toward hydrofluoroolefin-blown foams and phase-change materials in domestic manufacturing.
- Pharmaceutical cold-chain expansion:Vaccine distribution networks are procuring electric hard-shell units with vehicle-power integration for last-mile temperature integrity.
- Coastal recreational fishing corridors:Concentrated demand from Florida, California, and Texas charter operators sustains replacement cycles for multi-day ice retention designs.
Market Restraints
- Petrochemical feedstock volatility:Rotomolded polyethylene resin costs fluctuate with crude oil indices, compressing margin predictability for thick-wall cooler manufacturers.
- Asian vacuum-insulated panel concentration:Core VIP manufacturing clusters in China and Japan create supply vulnerability for North American cooler assemblers seeking thermal efficiency gains.
- California SB 1013 chemical restrictions:The state's high-global-warming-potential substance limits add compliance layers for foam-blowing agent selection in West Coast distribution channels.
Strategic Opportunities
- India pharmaceutical logistics:The country's CDSCO cold-chain requirements for biologics distribution present white space for vacuum-insulated container imports as domestic manufacturing scales.
- EU F-Gas Regulation alignment:Manufacturers certifying to the regulation's lower-GWP benchmarks gain preferential access to continental outdoor recreation retail networks.
- Direct-to-consumer channel expansion:Subscription-based cooler replacement programs bypass traditional big-box retail slotting fees, capturing lifetime value from expedition tourism segments.
Industry Challenges
- Thermal engineering talent scarcity:Phase-change material formulation expertise concentrates among polymer science specialists, constraining R&D velocity for mid-tier manufacturers.
- Multi-jurisdiction certification timelines:Simultaneous EPA, CPSC, and state-level chemical reviews extend product launch windows by twelve to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insulated Icebox Market |
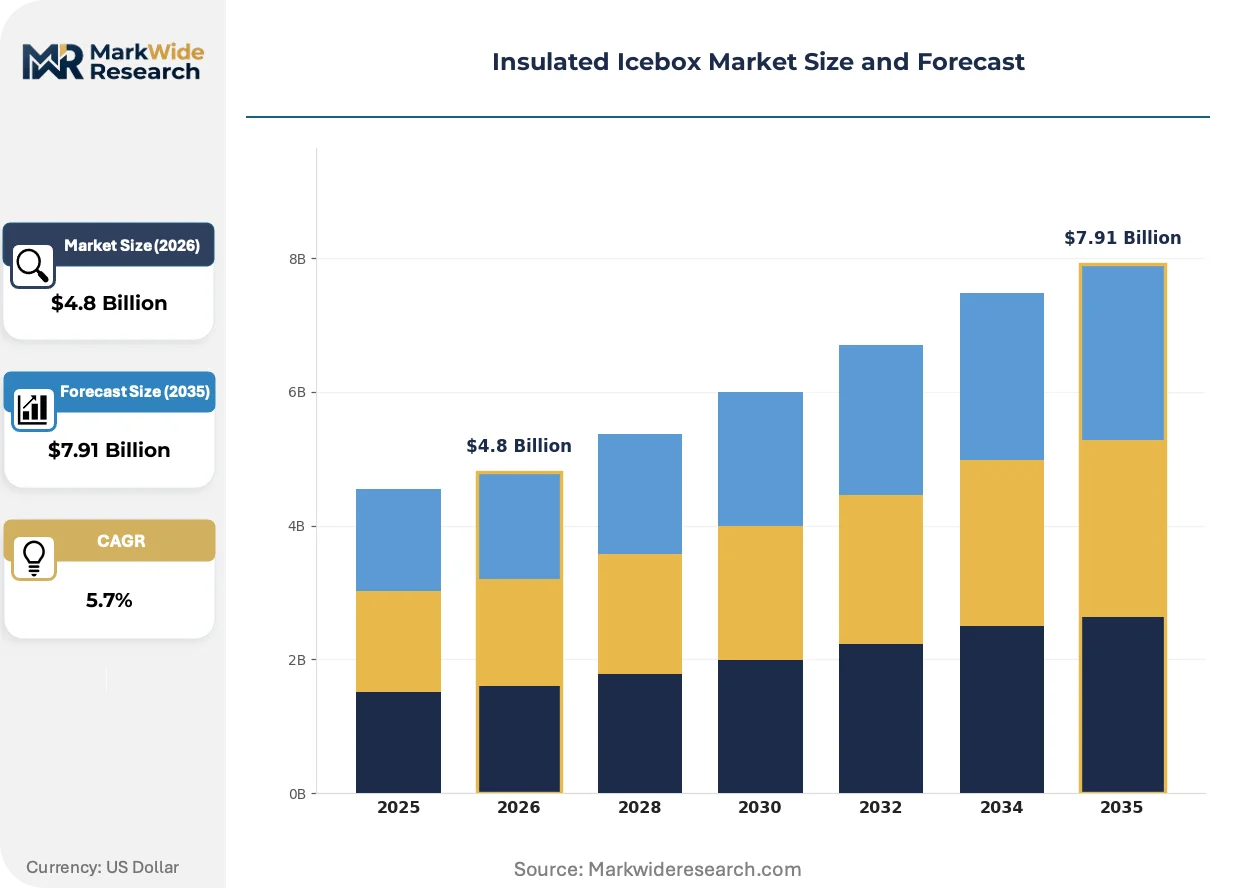
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard-Shell Coolers, Soft-Sided Coolers, Electric Coolers, Marine Iceboxes Application: Camping, Fishing, Outdoor Events, Tailgating Material: Plastic, Stainless Steel, Aluminum, Composite Materials Customer Type: Retail Customers, Industrial Suppliers, Hospitality Sector, Event Planners |
| Companies Covered | Pelican, Stanley, Igloo, ORCA, Grizzly, YETI, Rubbermaid, RTIC Outdoors, Coleman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insulated Icebox Market Emerging Trajectories
Material science advances are compressing thermal conductivity benchmarks while digital integration redefines cooler functionality beyond passive insulation. These shifts are fragmenting the vendor base into specialized technology tiers.
Vacuum-insulated panel technology is virtualizing the traditional thick-wall foam paradigm. Marine expedition operators are specifying VIP-core units for weight-sensitive vessel applications. This substitution is compressing demand for conventional polyurethane-injected rotomolded designs in premium price tiers.
California's SB 1013 and the US EPA's AIM Act implementation are mandating hydrofluoroolefin transition in foam-blowing agents. Domestic manufacturers face reformulation capital outlays or supplier switching costs. Hard-shell cooler production serving West Coast distribution bears the steepest compliance burden, accelerating nearshoring of VIP assembly to Mexico.
Vehicle-accessory power integration is reshaping buyer specifications for electric cooler categories. Overland adventure tourism operators are specifying dual-zone compressor units with solar-charging compatibility. This specification shift concentrates in the Arizona-Utah-Colorado corridor where dispersed camping infrastructure remains limited.
Insulated Icebox Market Segmentation
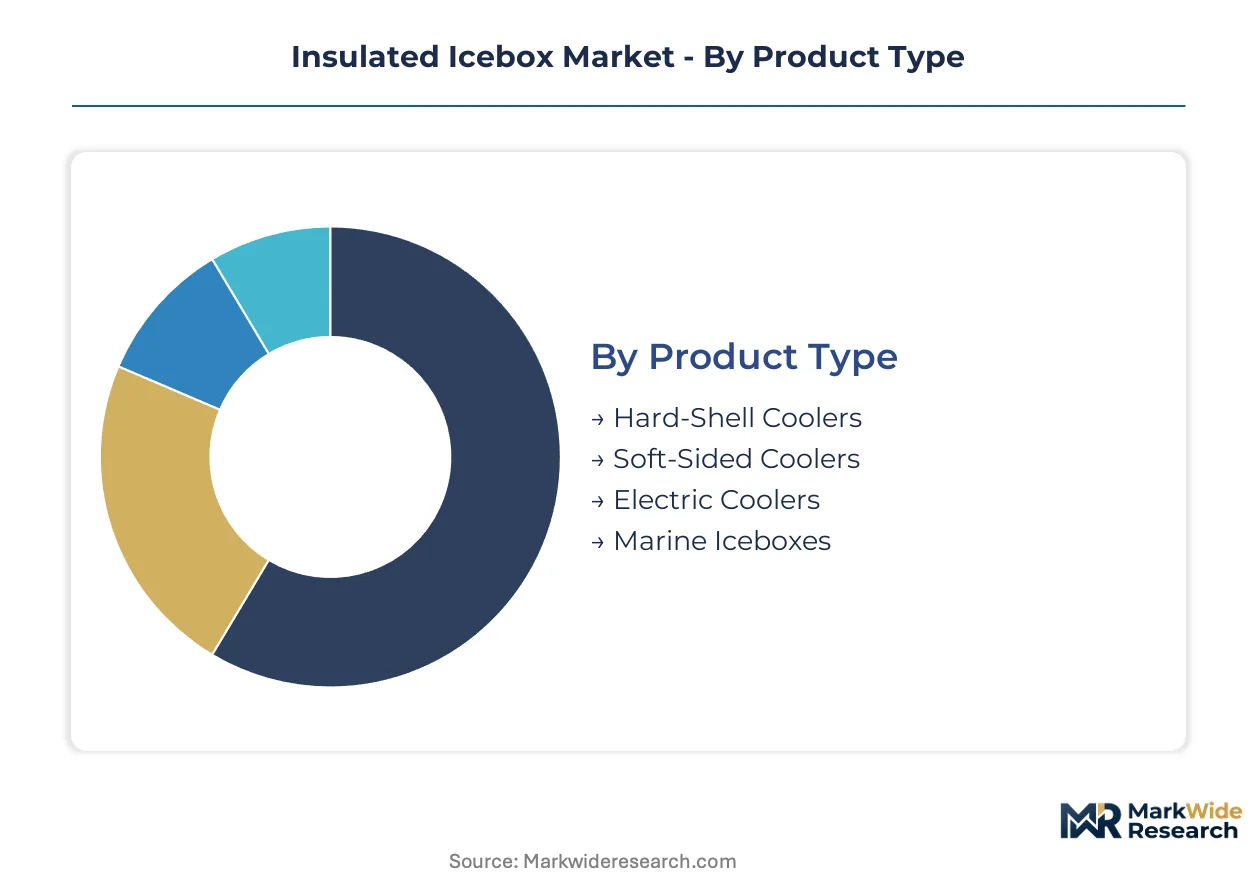
Segmentation in the insulated icebox market reveals divergent durability expectations and procurement rhythms across user categories. Marine operators replace units on multi-year cycles while hospitality buyers turn over soft-sided inventory seasonally. Understanding these replacement cadences shapes inventory planning and channel strategy for manufacturers.
Product Type:
Replacement cycles stretch from seasonal hospitality refreshes to decade-long marine deployments, creating divergent revenue recognition patterns across the category.
- Hard-Shell Coolers:Rotomolded polyethylene walls with polyurethane foam cores deliver multi-day ice retention for expedition fishing. Demand concentrates in Florida charter fleets where durability expectations extend replacement intervals to seven to ten years.
- Electric Coolers:Compressor or thermoelectric units with vehicle-power integration enable active temperature control without ice dependency. Pharmaceutical last-mile distributors in Texas and Arizona are specifying these for vaccine transport where temperature integrity cannot fail.
- Soft-Sided Coolers:Flexible vinyl or fabric exteriors with insulated liners prioritize portability over duration. Hospitality procurement in California coastal resorts drives annual replacement cycles tied to brand refresh schedules.
- Marine Iceboxes:Fiberglass or stainless steel built-in units with gasket-sealed lids integrate directly into vessel structures. Custom boatbuilders in the Gulf Coast specify these during new construction phases.
Hard-shell designs dominate installed base across recreational segments. Electric coolers are where expansion concentrates as vehicle electrification enables new power-accessory categories.
Application:
Activity-based segmentation maps directly to seasonal demand concentration and premium-price tolerance thresholds.
- Camping:Backpacking and basecamp configurations span ultralight soft-sided to wheeled hard-shell capacities. Overland tourism operators in the Arizona-Utah corridor are procuring dual-zone electric units with solar compatibility.
- Fishing:Offshore and inshore applications demand corrosion-resistant hardware and multi-day ice retention. Florida and Texas charter operators sustain the premium hard-shell tier through replacement of legacy foam-injected designs.
- Outdoor Events:Temporary cooling for festivals and sporting gatherings favors collapsible soft-sided formats with logo customization. Event rental companies in California rotate inventory on eighteen-month cycles.
- Tailgating:Vehicle-integrated electric and hard-shell hybrids serve pre-game food service. College-town retail clusters in Texas drive concentrated seasonal procurement patterns.
Fishing applications anchor commercial-grade volume commitments. Camping is climbing the fastest as dispersed recreation participation expands post-infrastructure investment.
Material:
Material selection trades thermal performance against weight penalties and regulatory compliance burdens across manufacturing geographies.
- Plastic:Rotomolded polyethylene dominates mass-market production with cost-efficient thermal conductivity profiles. EPA AIM Act foam-blowing agent restrictions are forcing reformulation of polyurethane cores in domestic manufacturing.
- Stainless Steel:Marine-grade alloys with welded seams resist salt corrosion in offshore environments. Premium boatbuilders specify these for integrated galley installations where aesthetics match durability requirements.
- Aluminum:Lightweight stamped or extruded shells serve aviation and weight-sensitive expedition applications. Specialty outfitters in Colorado backcountry guiding operations specify these for pack-in logistics.
- Composite Materials:Vacuum-insulated panels with fiberglass or carbon fiber exteriors deliver maximum thermal efficiency per unit mass. VIP manufacturing concentration in Japan and China creates supply vulnerability for North American assemblers seeking performance tier positioning.
Plastic constructions dominate unit volume across consumer tiers. Composite materials are gaining share fastest as vacuum-insulated panel costs compress toward mass-market accessibility.
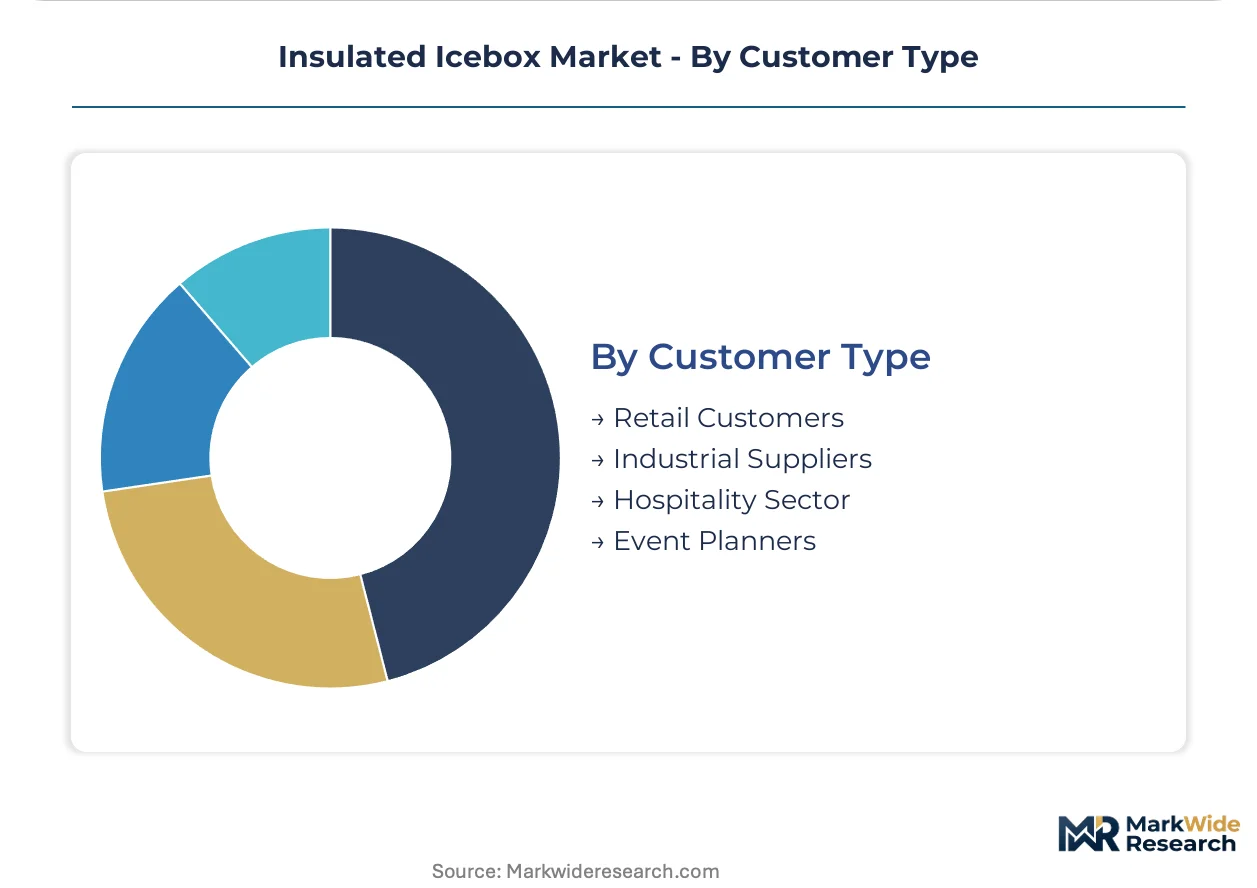
Customer Type:
Procurement authority and specification complexity fragment across direct consumer, institutional, and industrial buyer categories.
- Retail Customers:Individual purchasers selecting through big-box, specialty outdoor, or direct-to-consumer channels. Brand aesthetics and warranty terms drive replacement decisions in this price-sensitive tier.
- Industrial Suppliers:Cold-chain logistics operators procuring electric hard-shell units for pharmaceutical and biologics distribution. CDSCO compliance requirements in India are opening import demand for vacuum-insulated container specifications.
- Hospitality Sector:Hotels, resorts, and food service operations rotating soft-sided inventory on brand-refresh cycles. California coastal properties sustain margin pools through premium private-label procurement.
- Event Planners:Rental and staging companies managing temporary cooling infrastructure for corporate and entertainment gatherings. Seasonal demand spikes in Texas and Florida concentrate procurement timing.
Retail customers dominate transaction frequency. Industrial suppliers are where specification complexity and contract value are expanding most quickly as pharmaceutical cold-chain requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexican vacuum-insulated panel assembly facilities export to West Coast distributors navigating California's SB 1013 chemical restrictions. This trade corridor channels thermally efficient hard-shell units toward pharmaceutical cold-chain operators in Arizona and Texas.
United States
Florida charter fishing fleets sustain seven-to-ten-year replacement cycles for rotomolded polyethylene units. The EPA's AIM Act phasedown of hydrofluorocarbon refrigerants forces domestic manufacturers toward hydrofluoroolefin foam-blowing agent reformulations. Coastal recreational demand concentrates in the California-Texas-Florida corridor where multi-day ice retention specifications dominate procurement.
Germany
Outdoor recreation retailers in Bavaria and Baden-Württemberg stock premium hard-shell inventory for Alpine expedition tourism. The EU F-Gas Regulation mandates lower-global-warming-potential benchmarks for foam insulation systems. Manufacturing clusters in North Rhine-Westphalia assemble electric cooler units with vehicle-power integration for continental distribution.
China
Domestic cold-chain logistics operators in the Yangtze River Delta procure vacuum-insulated containers for biologics distribution. The country's dual carbon goals pressure manufacturers toward phase-change material alternatives in cooler assembly. VIP core manufacturing concentrates in Guangdong and Jiangsu provinces, supplying North American assemblers seeking thermal efficiency gains.
India
Pharmaceutical distributors in Maharashtra and Gujarat import vacuum-insulated specifications to meet CDSCO cold-chain requirements for vaccine transport. The PLI scheme incentivizes domestic manufacturing scale-up for insulated container production. Mumbai-Pune logistics corridors anchor demand for electric hard-shell units with active temperature control.
Japan
Marine boatbuilders in Nagoya and Osaka specify fiberglass-integrated iceboxes for offshore fishing vessel construction. METI efficiency standards drive adoption of vacuum-insulated panel technology in premium cooler segments. Specialty outfitters in Hokkaido backcountry guiding operations procure lightweight aluminum-shell designs for pack-in logistics.
Insulated Icebox Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered price-positioning bands. Mass-market volume flows through big-box retail slotting arrangements while premium positioning depends on specialty outdoor retailer relationships. Three archetypes dominate: heritage camping brands with broad distribution, rotomolding specialists with thick-wall durability claims, and direct-to-consumer challengers with price-point proximity strategies. Competitive moves center on foam-blowing agent reformulation compliance and vacuum-insulated panel supply chain securing.
Within the heritage-brand tier, Igloo and Coleman exemplify mass-market scale through decades-long retail channel presence. YETI anchors the premium-positioning vector with specialty retailer shelf-space control. RTIC Outdoors occupies a direct-to-consumer challenger position, representing price-point competition against established premium claims. These three companies illustrate how channel strategy and brand positioning fragment competitive dynamics across consumer, industrial, and hospitality procurement segments.
| Leading Market Players |
|---|
| Pelican |
| Stanley |
| Igloo |
| ORCA |
| Grizzly |
| YETI |
| Rubbermaid |
| RTIC Outdoors |
| Coleman |
| Others |
Supply Flow & Price Mechanics
Guangdong vacuum-insulated panel manufacturing clusters anchor global thermal core supply, concentrating pricing leverage among Japanese and Chinese material suppliers while compressing margin pools for North American cooler assemblers dependent on imported VIP technology.
Pricing Analysis
Cost-plus contracts with polyethylene resin indexation dominate rotomolded cooler procurement between domestic manufacturers and Gulf Coast petrochemical suppliers. Pricing stratifies across premium, standard, and economy tiers based on wall thickness specifications and ice-retention certification grades. Cost compression in mass-market plastic constructions is intensifying because EPA AIM Act foam-blowing agent reformulations add reformulation pass-through charges. Charter fishing operators in Florida demonstrate lowest price sensitivity, while hospitality bulk buyers in California coastal resorts negotiate hardest on per-unit landed costs.
Supply Chain Analysis
Export-control scrutiny on vacuum-insulated panel core technology limits technology transfer to unlicensed Mexican assembly facilities, constraining nearshoring velocity for North American brands seeking West Coast distribution compliance. VIP core manufacturing concentrates in Japan, China, and South Korea, while rotomolded polyethylene resin feeds from Texas and Louisiana petrochemical complexes. Single-source vulnerability runs through Guangdong VIP laminate suppliers. Distribution runs through big-box retail slotting arrangements for mass-market volume and specialty outdoor dealer networks for premium positioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Insulated icebox incumbents face substitution pressure from vehicle-integrated electric compressor units as overland tourism electrifies, requiring defensive repositioning around thermal performance claims that passive insulation cannot match.
For Market Incumbents: Insulate core rotomolding capacity through backward integration into polyurethane foam-blowing agent formulation, preempting EPA AIM Act supplier switching costs. Secure multi-year VIP core supply agreements with Japanese laminate specialists before export-control tightening restricts technology flows. Channel control through specialty outdoor retailer exclusivity remains the priority defensive lever against direct-to-consumer challengers. For New Entrants and Emerging Players: Maharashtra pharmaceutical logistics corridors present underpenetrated white space for vacuum-insulated container imports meeting CDSCO cold-chain requirements. Target India biologics distributors with rental-model electric hard-shell units, bypassing capital-intensive retail channel buildouts. Direct procurement relationships with Mumbai-Pune cold-chain operators offer the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors rotomolding specialists with demonstrated EPA compliance pathways over undifferentiated plastic injection molders. Long-term viability hinges on thermal engineering R&D depth rather than brand equity alone. Watch FDA pharmaceutical distribution qualification timelines as the inflection signal for electric cooler category acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foam Chemistry | Captures EPA AIM Act compliance margin by controlling hydrofluoroolefin formulation in-house. |
| VIP Supply Agreement with Japanese Specialists | Secures thermal core access before export controls restrict laminate technology transfer. |
| Direct-to-Consumer Channel Launch | Bypasses big-box slotting fees while capturing lifetime value from expedition tourism segments. |
| India Pharmaceutical Logistics Entry | Addresses CDSCO cold-chain white space with vacuum-insulated specifications for biologics transport. |
| Electric Cooler Solar Integration Development | Matches Arizona-Utah overland operator specifications for dispersed camping power independence. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with rotomolding plant managers, cold-chain logistics procurement leads at pharmaceutical distributors, specialty outdoor retailer category buyers, and thermal engineering R&D directors. Secondary validation drew from EPA AIM Act regulatory filings, CDSCO cold-chain guidelines, customs trade data on VIP core imports, and SEC 10-K disclosures from listed outdoor recreation manufacturers. Bottom-up unit shipment estimates triangulated against top-down category value reconstructions.
Calibration against historical volume trajectories and installed base replacement cycles shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application activity, material construction, and customer procurement authority, with pharmaceutical cold-chain compliance tier as an industry-specific overlay. CAGRs derived from regression analysis of replacement cycle compression and vehicle electrification penetration curves, incorporating resin cost volatility indices and regulatory phase-in schedules as scenario inputs.
Macroeconomic conditions sit as an overlay; deviation in crude oil price indices and freight rate volatility would shift the trajectory of rotomolded polyethylene cost pass-through. Forecasts reflect documented assumptions on EPA enforcement timing and CDSCO inspection regime stringency. Material shifts in export-control classification for vacuum-insulated panel core technology would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Containers
Assembly Trays Market
Packaging Containers
Global Food Re Close Pack Market
Packaging Containers
Slide Tray Box Market
Packaging Containers
Hinged Food Containers Market
Packaging Containers
Foldable Mailer Box Market
Packaging Containers
Candle Box Market
Packaging Containers
Shipping Mailers Market
Packaging Containers
Chalk Boxes Market
Packaging Containers
Membrane Boxes Market
Packaging Containers
Clamshell Packaging Market
Packaging Containers
Custom Boxes Market
Packaging Containers
Roll-On Bottles Market
Packaging Containers
Global Acrylic Airless Bottle Market
Packaging Containers
Snap Single Dose Dispensers Market
Packaging Containers
Sanitizer Bottles Market
Packaging Containers
Single Serve Packaging Market