
 Dropper Caps Market | 2026-2036
Dropper Caps Market Size, Share, and Industry Trends Forecast 2026-2036
Dropper Caps Market Foresight
Pharmaceutical-grade compliance tiers is reorganizing the Dropper Caps Market as buyers prioritize USP Class VI and child-resistant certifications over commodity alternatives. AptarGroup leverages its multi-material platform to serve both pharma and cosmetics channels with differentiated closure systems. Berry Global anchors North American supply through high-volume injection molding capacity for plastic droppers. Gerresheimer sustains glass dropper leadership via precision borosilicate forming for sensitive formulations.
Dropper caps are precision-dispensing closures incorporating a threaded or snap-fit collar, a compressible bulb, and a calibrated orifice tube, typically molded from polypropylene, LDPE, or borosilicate glass to deliver controlled liquid volumes ranging from 0.05 mL to 2.0 mL per drop. Their primary purpose is to ensure dosing accuracy, product integrity, and user safety across liquid medications, essential oils, and laboratory reagents. Plastic closures dominate unit volumes due to cost scalability and design flexibility, while glass variants command premium positioning in essential oils and laboratory applications where chemical inertness is non-negotiable. Child-resistant mechanisms represent the fastest-growing closure subsegment as regulatory mandates expand beyond pharmaceuticals into cannabis and household chemical packaging.
FDA 21 CFR Part 210-211, USP Class VI biocompatibility standards, and ISO 15378 pharmaceutical packaging directives collectively dictate material selection, extractables testing, and lot traceability requirements for dropper cap suppliers. The Consumer Product Safety Commission enforces Poison Prevention Packaging Act compliance, forcing redesigns of legacy snap-on formats into screw-cap child-resistant systems. Stakeholders must monitor evolving state-level cannabis packaging regulations and EU MDR traceability expansions to preempt compliance-driven sourcing shifts.
Market Dynamics
Child-resistant closure mandates from the Consumer Product Safety Commission are forcing wholesale redesign of legacy dropper formats, compressing supplier margins while accelerating certification-driven consolidation among specialized molders and glass formers.
Growth Catalysts
- Poison Prevention Packaging Act enforcement:The Consumer Product Safety Commission's tightening child-resistant standards are mandating screw-cap conversions across pharmaceutical and cannabis packaging, eliminating snap-fit alternatives from regulated channels.
- Essential oil premiumization:Aromatherapy and clean beauty brands are specifying borosilicate glass droppers with calibrated orifice tubes to signal formulation integrity and support precise dosing claims.
- USP Class VI certification pull:Injectable and ophthalmic drug manufacturers are filtering supplier pools to biocompatible-grade closures, disqualifying commodity polypropylene sources from high-value contracts.
Market Restraints
- Raw material concentration:Borosilicate glass feedstock depends on concentrated European furnace capacity, exposing pharmaceutical customers to energy-cost volatility and supply interruption risks.
- Tooling cost escalation:Multi-cavity injection molds for child-resistant mechanisms require hardened steel and precision machining, extending breakeven timelines for mid-volume pharmaceutical programs.
- Silicone bulb substitution:Thermoplastic elastomer bulbs are displacing natural rubber in laboratory applications, eroding traditional supplier competencies and forcing material qualification rework.
Strategic Opportunities
- Cannabis packaging compliance:State-level mandates for child-resistant and tamper-evident closures in recreational and medical cannabis are opening regulated channels previously closed to conventional pharmaceutical suppliers.
- Prefilled dropper assembly:Contract manufacturers are integrating sterile filling and closure application into single-source offerings, capturing value from brands seeking to outsource packaging line investment.
- EU MDR traceability expansion:The Medical Device Regulation's unique device identifier requirements are creating demand for laser-marked, lot-traceable glass droppers in diagnostic and therapeutic applications.
Industry Challenges
- Extractables validation timelines:USP Class VI and ISO 10993 biocompatibility testing protocols extend qualification cycles to 18-24 months, freezing supplier switching decisions and delaying new product introductions.
- Multi-material assembly integration:Child-resistant mechanisms combining polypropylene collars, LDPE bulbs, and glass tubes require precision tolerancing across incompatible thermal expansion coefficients, elevating defect rates and rework costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dropper Caps Market |
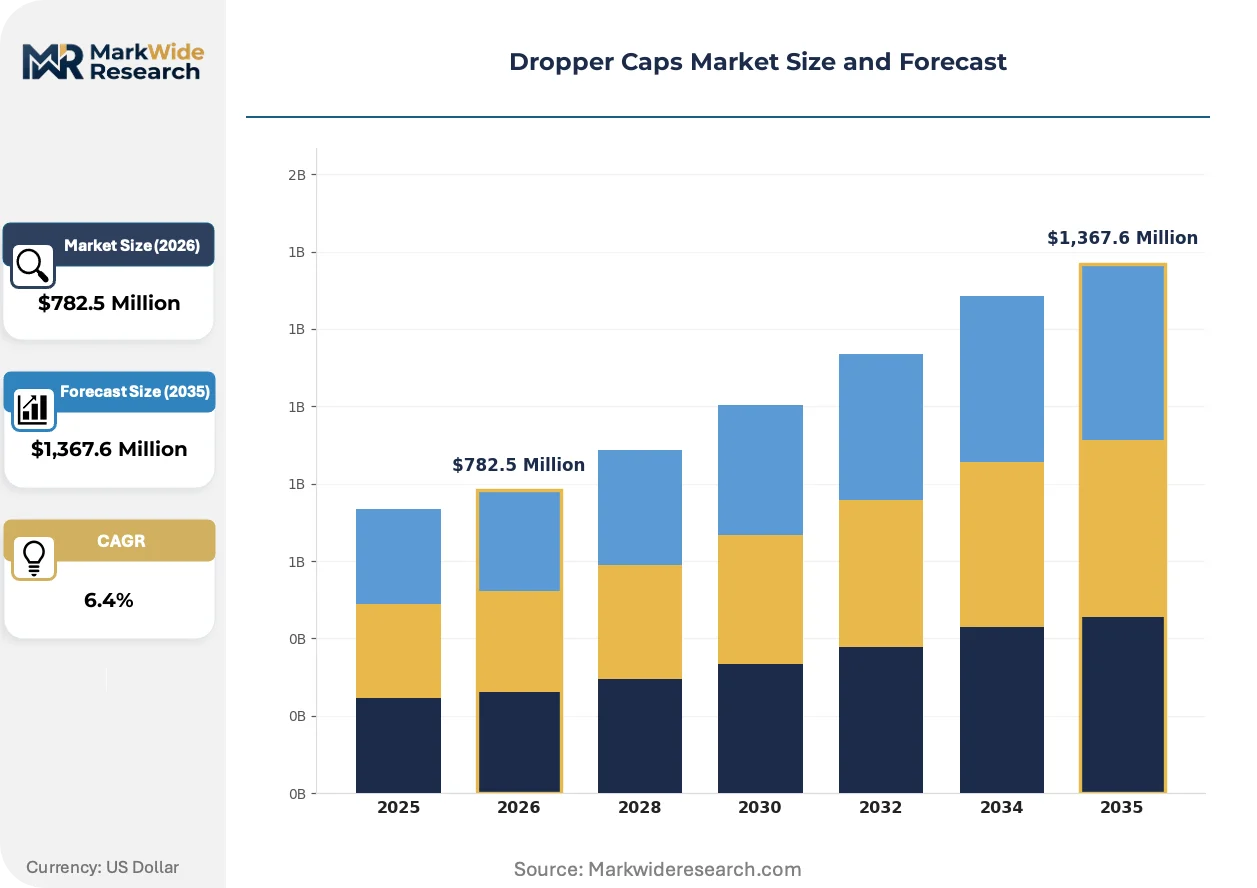
| Market Size in 2026 | $782.5 Million |
| Market Size in 2035 | $1,367.6 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Glass, Child-Resistant, Tamper-Evident Closure Type: Screw Cap, Snap-On, Dropper Tip, Plug End User: Pharmaceuticals, Cosmetics, Food & Beverage, Chemicals Application: Liquid Medications, Essential Oils, Beverages, Laboratory Use |
| Companies Covered | AptarGroup, Berry Global, Gerresheimer, Bormioli Pharma, Comar, Nolato, DWK Life Sciences, Silgan Plastics, Phoenix Closures, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dropper Caps Market Shifts & Advancements
Dropper cap engineering is splitting along performance-grade lines, with pharmaceutical compliance tiers diverging sharply from commodity cosmetic specifications and forcing parallel development tracks within supplier portfolios.
Precision orifice tube manufacturing is bifurcating the market. Laser-drilled borosilicate tubes deliver sub-microliter dosing accuracy for ophthalmic and biologic applications. Specialty glass formers in Germany and Italy are capturing these high-specification contracts. Commodity molded-plastic droppers are retreating to volume cosmetics and household chemical segments where dosing tolerance is less critical.
REACH Annex XVII restrictions on phthalate plasticizers are accelerating migration to bio-based polypropylene and post-industrial recycled content in European cosmetic packaging. Compounders in the Netherlands and Belgium are certifying halogen-free, food-contact-grade resins for dropper collar production. Beauty brands with EU retail exposure are reformulating closure specifications to preempt regulatory non-compliance.
Direct-to-consumer essential oil brands are consolidating supplier relationships to secure custom color-matched bulb and collar combinations. Subscription-box fulfillment requirements are driving demand for leak-tested, drop-ship-qualified assemblies with torque-verified child-resistant closures. North American contract packagers are investing in automated capping and induction-sealing lines to serve these emerging channel specifications.
Dropper Caps Market Segmentation
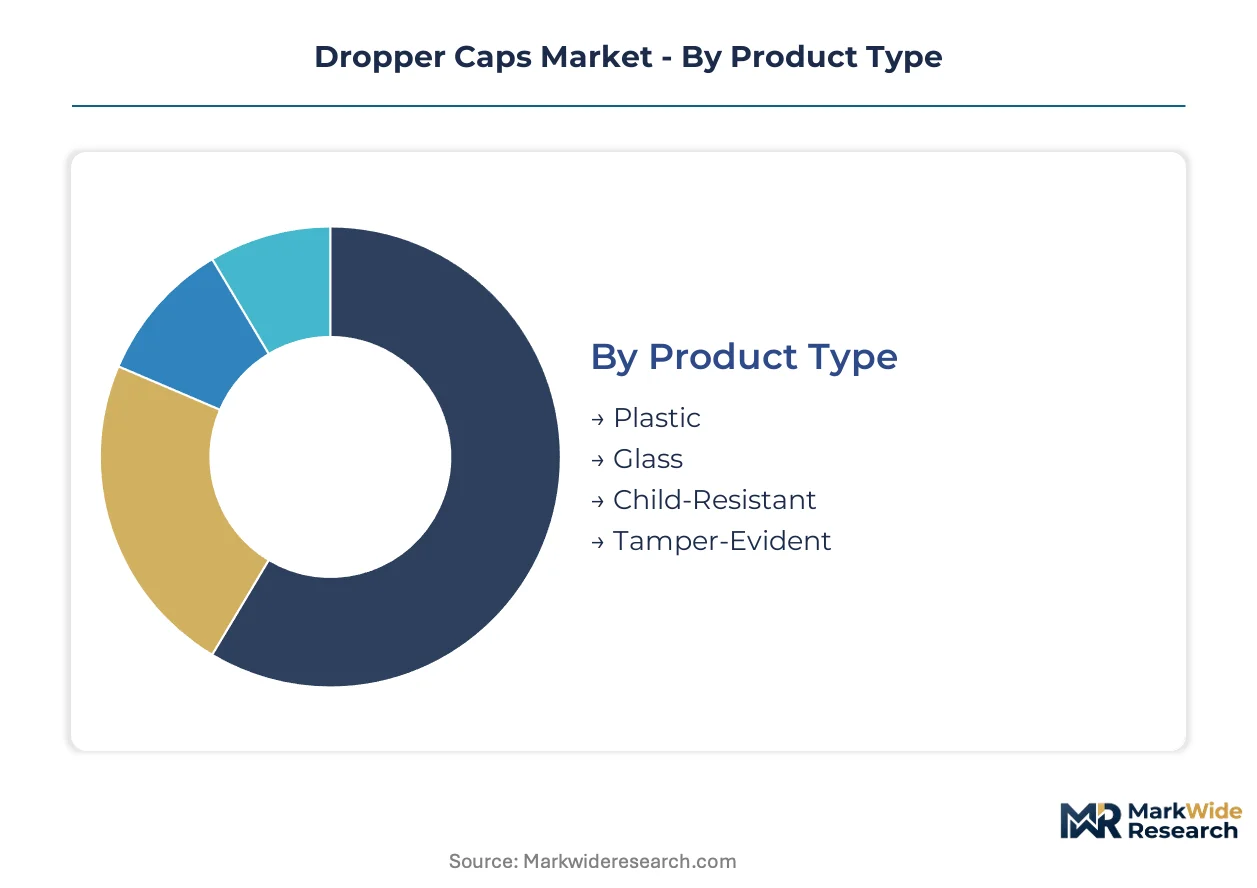
Dropper cap procurement patterns diverge sharply across material grades and regulatory tiers, with pharmaceutical buyers filtering on USP Class VI compliance while cosmetic brands optimize for color-matching and shelf appeal. Understanding these segment boundaries clarifies where substitution threats and margin compression concentrate.
Product Type:
Glass variants face the strongest substitution pressure as bio-based polypropylene and advanced thermoplastic elastomers close the performance gap in non-pharmaceutical applications.
- Plastic:Polypropylene and LDPE formulations dominate unit economics through injection molding scalability. Demand concentrates in North American contract packagers serving subscription-box essential oil brands with torque-verified, drop-ship-qualified assemblies.
- Glass:Borosilicate tubes deliver chemical inertness for ophthalmic and biologic formulations. German and Italian specialty formers anchor European pharmaceutical supply amid energy-cost volatility affecting furnace capacity.
- Child-Resistant:Screw-cap mechanisms with press-and-turn functionality satisfy Consumer Product Safety Commission mandates. State-level cannabis packaging regulations are opening regulated channels previously closed to conventional pharmaceutical suppliers.
- Tamper-Evident:Ring-break or shrink-band configurations protect product integrity in essential oils and laboratory reagents. Clean beauty brands specify these for formulation integrity signaling.
Plastic anchors the volume base while child-resistant mechanisms gain share at the steepest rate.
Closure Type:
Cost tier differentiation separates precision-machined screw systems from commodity snap formats, with mid-volume pharmaceutical programs bearing the steepest tooling amortization burdens.
- Screw Cap:Threaded polypropylene collars enable repeatable torque application and child-resistant compliance. FDA 21 CFR Part 210-211 mandates are forcing wholesale conversions from legacy alternatives.
- Snap-On:Press-fit designs retain cost advantage in non-regulated cosmetics and household chemicals. REACH Annex XVII phthalate restrictions are accelerating material requalification cycles.
- Dropper Tip:Calibrated orifice tubes deliver 0.05 mL to 2.0 mL dosing precision. Laser-drilled borosilicate variants capture ophthalmic specifications from specialty glass formers.
- Plug:Simple friction-fit closures serve laboratory and industrial reagent applications. Silicone bulb substitution by thermoplastic elastomers is eroding traditional supplier competencies.
Screw cap configurations command the premium tier while dropper tip specifications climb the fastest on biologic dosing accuracy requirements.
End User:
Customer type determines certification burden, with pharmaceutical and cannabis channels requiring 18-24 month extractables validation timelines that freeze supplier switching decisions.
- Pharmaceuticals:Injectable and ophthalmic drug manufacturers filter supplier pools to USP Class VI and ISO 15378 compliant sources. ISO 10993 biocompatibility testing extends qualification cycles significantly.
- Cosmetics:Aromatherapy and clean beauty brands prioritize borosilicate glass with custom color-matched bulbs for shelf differentiation. EU MDR traceability expansions are creating demand for laser-marked, lot-traceable droppers.
- Food & Beverage:Flavor extracts and concentrated additives require food-contact-grade resins. Netherlands and Belgium compounders are certifying halogen-free alternatives for European retail exposure.
- Chemicals:Laboratory reagents and industrial formulations demand chemical resistance and precise dosing. Thermoplastic elastomer bulbs are displacing natural rubber in this segment.
Pharmaceuticals anchor the compliance-driven revenue base while cosmetics expand most quickly on direct-to-consumer essential oil premiumization.
Application:
Volume concentration in liquid medications contrasts with margin expansion in precision-dosing specialty applications where sub-microliter accuracy commands price premiums.
- Liquid Medications:Pediatric and geriatric formulations drive child-resistant mechanism adoption. Poison Prevention Packaging Act enforcement is eliminating snap-fit alternatives from regulated channels.
- Essential Oils:Aromatherapy brands specify calibrated glass droppers to support precise dosing claims. Subscription-box fulfillment requirements are driving automated capping and induction-sealing line investments.
- Beverages:Concentrated flavor extracts and functional drink additives use food-grade plastic closures. North American contract packagers are integrating sterile filling and closure application into single-source offerings.
- Laboratory Use:Diagnostic and therapeutic applications require EU MDR unique device identifier compliance. Precision borosilicate forming from German suppliers sustains leadership in sensitive formulations.
Liquid medications anchor the volume base while laboratory use gains share at the steepest rate on diagnostic traceability mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies, with European pharmaceutical buyers absorbing premium pricing for certified glass droppers while Asian cosmetics manufacturers prioritize polypropylene cost scalability.
United States
Pediatric medication and cannabis packaging channels drive child-resistant mechanism adoption. The Consumer Product Safety Commission enforces Poison Prevention Packaging Act compliance, eliminating legacy snap-fit formats from regulated distribution. New Jersey and Pennsylvania host contract packaging clusters serving subscription-box essential oil brands with automated capping lines.
Germany
Injectable and ophthalmic drug manufacturers filter suppliers to USP Class VI certified sources. The EU Medical Device Regulation mandates unique device identifiers for diagnostic droppers, extending traceability requirements. Münsterland and Bavaria concentrate precision borosilicate forming capacity for sensitive biologic formulations.
China
Domestic aromatherapy brands scale polypropylene dropper production for cost-competitive export positioning. The National Medical Products Administration aligns pharmaceutical packaging standards with international biocompatibility protocols. Zhejiang and Jiangsu provinces anchor injection molding clusters serving clean beauty contract manufacturers.
India
Generic pharmaceutical exporters build child-resistant closure capabilities to access regulated Western markets. The Central Drugs Standard Control Organization enforces packaging material safety notifications for ophthalmic products. Gujarat and Maharashtra house specialized molders qualifying ISO 15378 pharmaceutical directives.
France
Clean beauty brands specify REACH-compliant bio-based polypropylene for EU retail exposure. ANSM pharmaceutical packaging guidelines emphasize extractables testing for liquid medication containers. The Auvergne-Rhône-Alpes region clusters cosmetic packaging innovation around Lyon-based compounders certifying halogen-free resins.
Dropper Caps Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. Precision glass formers capture pharmaceutical premium tiers through certification barriers, while high-volume plastic molders dominate cosmetics through scale economies. Three archetypes define the field: multi-material platform specialists, regional injection molding scale players, and European precision glass formers. Consolidation pressures concentrate among mid-tier molders facing child-resistant tooling cost escalation, while strategic partnerships link compounders with brand owners seeking sustainable material qualifications.
Among the multi-material platform specialists, AptarGroup and Berry Global occupy positions spanning pharmaceutical compliance and cosmetics flexibility. European precision glass forming is anchored by Gerresheimer and Bormioli Pharma, representing the certified-tier archetype for sensitive formulations.
| Leading Market Players |
|---|
| AptarGroup |
| Berry Global |
| Gerresheimer |
| Bormioli Pharma |
| Comar |
| Nolato |
| DWK Life Sciences |
| Silgan Plastics |
| Phoenix Closures |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between pharmaceutical brands and German glass formers lock in borosilicate supply access while anchoring price visibility against energy-cost volatility. These arrangements concentrate pricing power with certified-tier suppliers, forcing cosmetic buyers into spot-market exposure for polypropylene alternatives.
Pricing Analysis
FDA 21 CFR Part 210-211 dictates the pricing tier structure across pharmaceutical-grade dropper caps, separating USP Class VI certified closures from commodity alternatives. Three-tier pricing structure across premium certified, standard compliant, and economy cosmetic levels reflects extractables validation burden and material grade. Cost compression in standard-tier plastic droppers is intensifying because REACH Annex XVII compliance is forcing compounders into bio-based resin requalification. Contract packagers serving subscription-box essential oil brands exhibit the highest price sensitivity, while injectable drug manufacturers absorb premium glass pricing without volume elasticity.
Supply Chain Analysis
European furnace capacity for borosilicate glass feedstock anchors the critical chokepoint for pharmaceutical-grade dropper supply. Manufacturing concentrates in Germany, Italy, and China, with precision forming clustered in Münsterland and Bavaria while injection molding scales through Zhejiang and Jiangsu provinces. Raw material flows draw from concentrated petrochemical feedstocks for polypropylene collars, LDPE bulbs, and specialty glass sands. Single-source vulnerability runs through German glass formers dependent on natural gas furnace operations. Distribution runs through North American contract packaging clusters in New Jersey and Pennsylvania serving direct-to-consumer fulfillment requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dropper cap procurement is shifting toward integrated service models where sterile filling, torque verification, and drop-ship qualification capture recurring revenue layers expanding faster than hardware margins alone.
For Market Incumbents: Consolidate child-resistant mechanism capabilities through precision mold-making investments in Pennsylvania and New Jersey clusters, defending against mid-tier molder displacement from tooling cost escalation. Deepen backward integration into bio-based polypropylene compounder relationships to preempt REACH-driven material switching costs among European cosmetic accounts. For New Entrants and Emerging Players: Differentiate on cannabis packaging compliance services, targeting state-level mandates for child-resistant and tamper-evident closures in recreational and medical channels previously closed to conventional pharmaceutical suppliers. Penetrate through prefilled dropper assembly partnerships with contract manufacturers seeking to outsource packaging line capital. For Investors and Strategic Acquirers: Capital is best deployed toward multi-material platform specialists spanning pharmaceutical certification and cosmetics flexibility, with long-term viability tied to USP Class VI validation moats widening over a multi-year horizon. Watch extractables testing timeline compression as the inflection signal—accelerated FDA review pathways would unlock supplier switching velocity and consolidation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| USP Class VI Certification Investment | Biocompatibility validation opens injectable and ophthalmic drug contracts with FDA-regulated manufacturers. |
| Child-Resistant Mechanism Scale-Up | Multi-cavity hardened steel tooling captures Poison Prevention Packaging Act mandated conversions from legacy formats. |
| Prefilled Assembly Integration | Single-source sterile filling and closure application captures value from brands avoiding packaging line capital. |
| Bio-Based Polypropylene Transition | REACH Annex XVII compliance secures EU retail access for clean beauty and aromatherapy brand accounts. |
| Laser-Marking Traceability Deployment | EU MDR unique device identifier capability penetrates diagnostic and therapeutic glass dropper specifications. |
Research Methodology
Desk research of FDA 21 CFR filings, EMA packaging directives, and customs trade data preceded structured interviews with pharmaceutical procurement managers, cosmetic brand supply chain directors, and contract packaging operations heads. Primary fieldwork with German glass formers and Chinese injection molders combined with secondary validation from ISO 15378 certification databases and USP biocompatibility registries. Bottom-up volume modeling across material grades and closure types triangulated against top-down pharmaceutical packaging expenditure estimates.
Variance decomposition across product type, closure configuration, end-user certification tier, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories weighted by pricing tier concentration, with inputs including child-resistant mandate adoption curves, borosilicate furnace capacity utilization, and bio-based resin compounder certification timelines.
The analysis sits within stated boundaries; outcomes outside sustained FDA enforcement of Poison Prevention Packaging Act standards or accelerated EU MDR traceability rollouts would require recalibration. Practitioners should keep alternative scenarios live as state-level cannabis packaging regulations and REACH restriction expansions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Vented Caps Market
Caps and Closures
China Plastic Caps and Closures Market
Caps and Closures
Cone Lined Caps Market
Caps and Closures
Continuous Thread Metal Cap Market
Caps and Closures
Nigeria Plastic Caps and Closures Market
Caps and Closures
Linerless Closures Market
Caps and Closures
Benelux Plastic Caps and Closures Market
Caps and Closures
Cap Seals Market
Caps and Closures
Spray Caps Market
Caps and Closures
Bar Top Corks Market
Caps and Closures
Child Resistant Pipette Closures Market
Caps and Closures
Crimp-On Spouts Market
Caps and Closures
Brush Caps Market
Caps and Closures
Spout Closures Market
Caps and Closures
Middle East and Africa Plastic Caps and Closures Market
Caps and Closures
Bag Closures Market