
 North America Frozen Snacks Market | 2026-2036
North America Frozen Snacks Market Size, Share, and Industry Trends Forecast 2026-2036
North America Frozen Snacks Market Analytics
Canadian cold-storage infrastructure is hardening around major urban distribution nodes, tightening regional supply availability. General Mills leverages its captive flour-milling network to stabilize input costs for frozen pizza crust production. Tyson Foods anchors its position through integrated poultry processing that feeds directly into frozen appetizer lines. Nestlé S.A. competes across the premium ice-cream segment with dedicated manufacturing assets in the U.S. Midwest.
Frozen snacks encompass ready-to-heat or ready-to-eat food items preserved at sub-zero temperatures through blast freezing or individual quick freezing, typically formulated with moisture contents between 50-75 percent to maintain texture upon reheating. These products serve commercial foodservice operators and retail consumers seeking extended shelf life without preservative dependence. Frozen pizza commands the largest revenue pool within product-type segmentation, sustained by continuous topping and crust innovation that commands price premiums in supermarkets and wholesale channels. Online retail represents the fastest-expanding distribution channel, though convenience stores retain the highest purchase-frequency metrics for single-serve frozen snack formats. Households dominate end-user volume, while restaurants and catering services generate superior per-unit margins through bulk procurement contracts.
The U.S. FDA governs frozen food labeling, safety standards, and nutritional disclosure requirements under the Federal Food, Drug, and Cosmetic Act, directly shaping product reformulation cycles and packaging redesign investments. USDA oversight of meat and poultry components in frozen snacks imposes additional pathogen-control mandates that elevate processing costs for manufacturers. Canada's CFIA enforces parallel safety protocols through the Safe Food for Canadians Regulations, creating compliance harmonization pressure for cross-border suppliers. Stakeholders must monitor evolving sodium-reduction targets and front-of-package labeling proposals across both jurisdictions, as these regulatory trajectories will determine which product formulations retain shelf space and which face delisting risk.
Market Dynamics
Quick-service restaurant chains across the United States and Canada are accelerating frozen appetizer procurement as labor costs climb and kitchen staffing shortages persist, fundamentally restructuring upstream supplier relationships and cold-chain investment priorities.
Growth Catalysts
- USDA pathogen-control mandates:Meat and poultry safety protocols are forcing processing upgrades that simultaneously reduce spoilage rates and extend distribution reach for frozen protein-based snacks.
- Blast freezing equipment advances:Cryogenic tunnel systems now achieve -40°F core temperatures within minutes, preserving cellular structure in vegetable-based appetizers previously excluded from frozen formats.
- Northeast corridor cold-chain density:Refrigerated warehouse concentration between Boston and Washington D.C. enables daily replenishment cycles that convenience retailers require for high-velocity single-serve SKUs.
Market Restraints
- Wheat flour price volatility:Pizza crust input costs fluctuate with commodity grain markets, compressing margins for manufacturers lacking captive milling capacity.
- Cross-border regulatory harmonization friction:Divergent sodium-reduction timelines between the FDA and Health Canada force dual formulation runs or conservative recipes that underperform in taste tests.
- Fresh-prepared meal substitution:Grocery deli sections and ghost kitchen delivery are capturing occasion-based snack purchases through perceived quality advantages.
Strategic Opportunities
- Canadian urban distribution nodes:Toronto, Montreal, and Vancouver cold-storage infrastructure expansions create regional supply bottlenecks that first-mover suppliers can preempt.
- Front-of-package labeling proposals:Anticipated FDA and Health Canada warning symbol requirements favor clean-label reformulations with shorter ingredient decks commanding shelf space premiums.
- Online retail channel convergence:Direct-to-consumer frozen delivery platforms are absorbing last-mile logistics costs previously borne by retailers, opening urban household penetration.
Industry Challenges
- Refrigerated logistics talent scarcity:Commercial driver shortages and warehouse automation engineering gaps constrain capacity expansion timelines for frozen distribution networks.
- Legacy ERP integration complexity:Temperature-monitoring IoT sensors and blockchain traceability systems require costly middleware to interface with decades-old manufacturing execution platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Frozen Snacks Market |
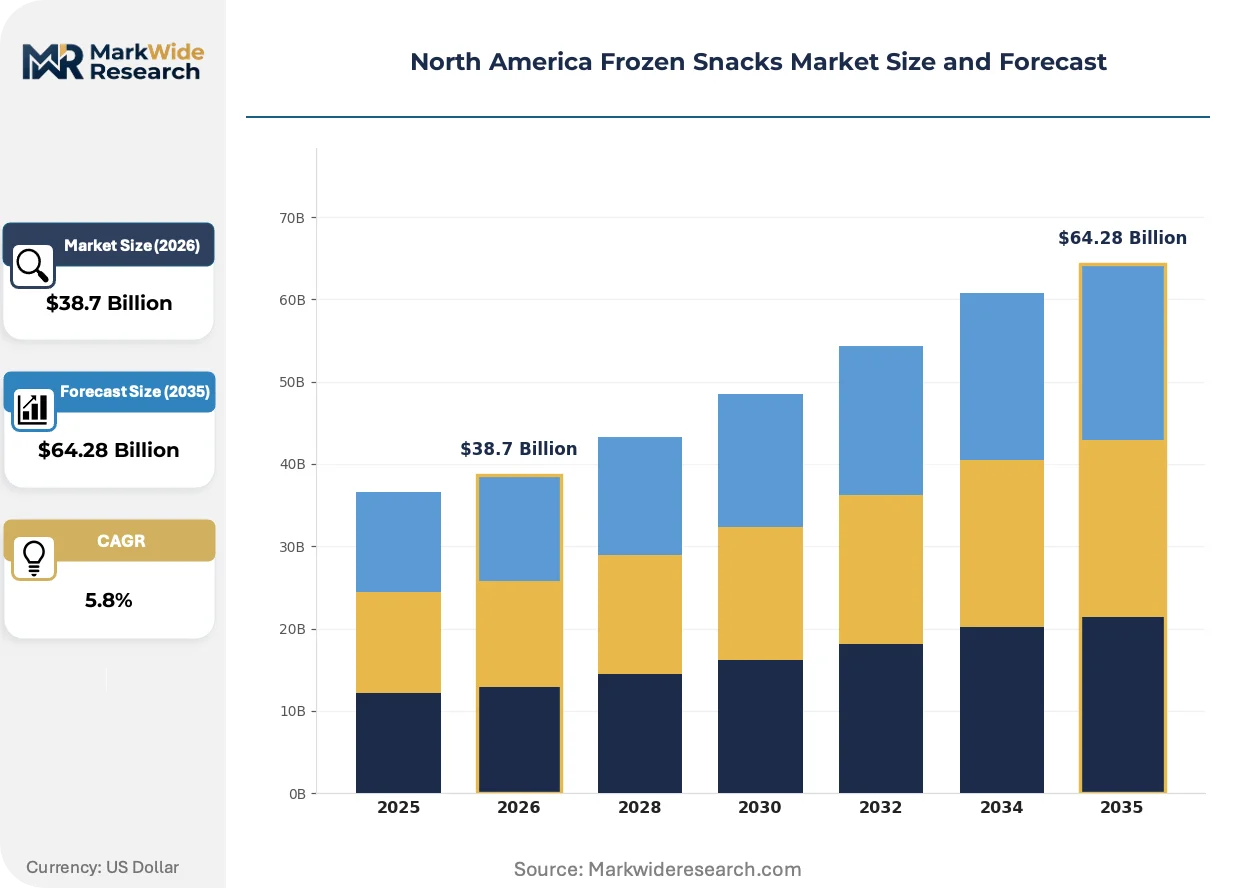
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
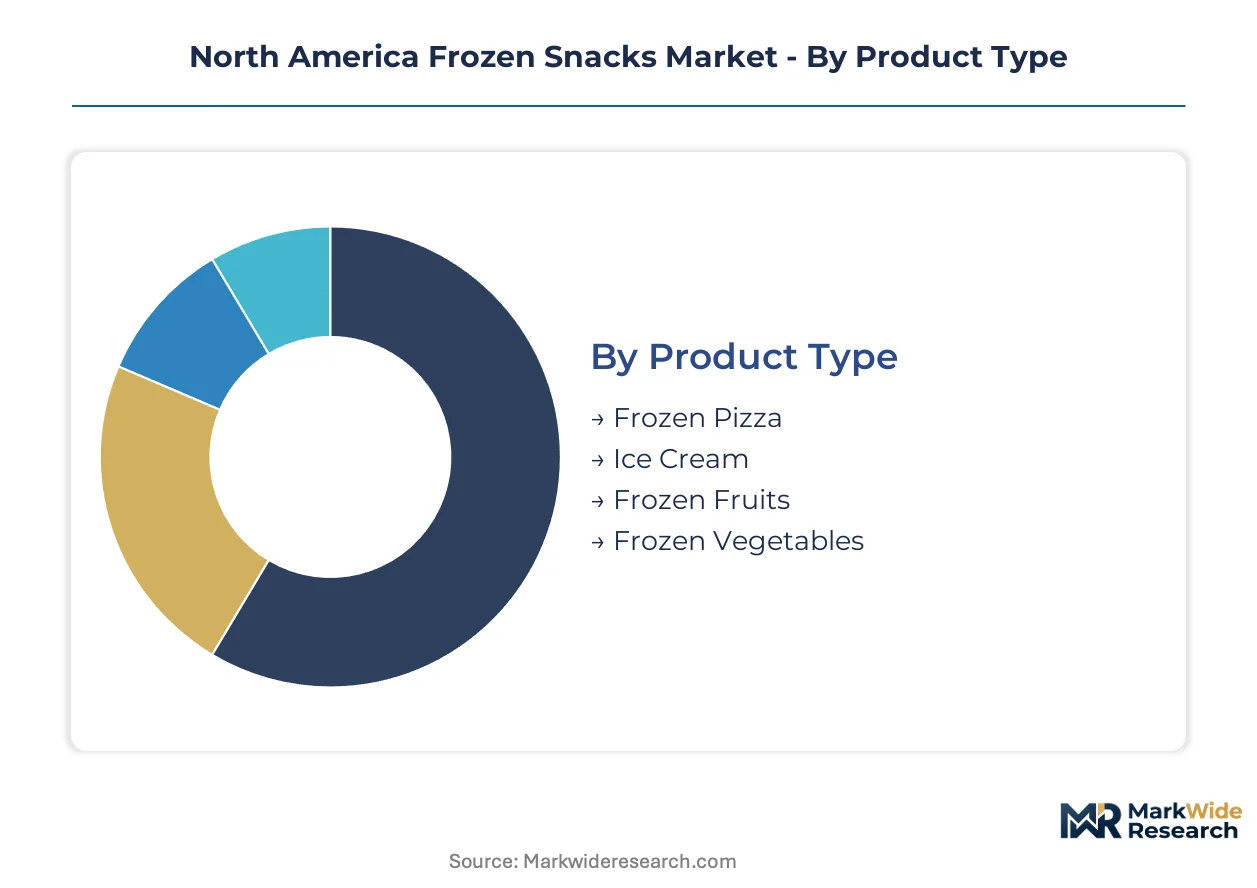
| Segmentation | Product Type: Frozen Pizza, Ice Cream, Frozen Fruits, Frozen Vegetables End User: Households, Restaurants, Food Trucks, Catering Services Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Wholesale Packaging Type: Bags, Boxes, Pouches, Containers |
| Companies Covered | General Mills, Tyson Foods, Nestlé S.A., Hormel Foods Corporation, Schwan's Company, Conagra Brands, Kraft Heinz Company, Unilever PLC, McCain Foods, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Frozen Snacks Market Evolving Landscape
Reformulation chemistry and packaging engineering are converging to solve the texture degradation problem that has historically limited frozen snack category expansion beyond pizza and breaded proteins.
Individual quick freezing technology paired with cryoprotectant carbohydrate blends is absorbing moisture migration challenges in fruit-based and dairy-based snack formats. Premium ice-cream manufacturers and frozen dessert startups are adopting these systems to launch clean-label products without stabilizer gums. The structural barrier between frozen confectionery and frozen snacks is dissolving as texture standards equalize.
The FDA's updated Nutrition Facts labeling requirements are forcing packaging redesign investments that simultaneously accommodate dual-language English-French mandates for Canadian export compliance. Reformulation cycles now integrate sodium-reduction targets and added-sugar disclosure positioning from the initial concept phase rather than post-launch adjustment. Frozen pizza and appetizer lines targeting cross-border distribution are standardizing on conservative recipes that satisfy both jurisdictions' emerging front-of-package warning criteria.
Household buyers are consolidating frozen snack purchases into fewer, larger-format transactions through club channel and online subscription models. Convenience stores are responding by compressing single-serve SKU assortments and expanding grab-and-go heated case offerings that compete directly with frozen for immediate consumption occasions. This channel tension is most visible in the US Northeast corridor, where urban convenience density and rapid delivery fulfillment overlap.
North America Frozen Snacks Market Segmentation
Frozen snack manufacturers configure production lines around distinct demand profiles. Product formulation, packaging engineering, and channel economics diverge sharply across household, foodservice, and institutional buyers.
Product Type:
Customization intensity spans from commodity frozen vegetables to highly engineered pizza platforms requiring proprietary crust chemistry and topping adhesion systems.
- Frozen Pizza:Manufacturers engineer moisture-retentive crusts through modified starch blends and par-baking protocols. U.S. Northeast corridor supermarkets command premium positioning through regional topping combinations and artisan crust claims. FDA sodium-reduction timelines are forcing reformulation of cheese blends and cured meat inclusions.
- Ice Cream:Premium formulations leverage cryoprotectant carbohydrate systems to eliminate stabilizer gums. Nestlé S.A. and dedicated Midwest manufacturing assets anchor clean-label production for cross-border distribution. Health Canada's front-of-package labeling proposals favor shorter ingredient decks in this segment.
- Frozen Fruits:Individual quick freezing preserves cellular structure for smoothie and baking applications.
- Frozen Vegetables:Blast-frozen formats serve institutional procurement with extended shelf-life requirements.
Most installed capacity flows through Frozen Pizza. Expansion is steepest in Ice Cream.
End User:
Volume concentration versus margin extraction defines the strategic calculus across buyer categories with divergent procurement patterns and quality specifications.
- Households:Club channel and online subscription models are consolidating purchase frequency into fewer, larger-format transactions. Urban households in the U.S. Northeast corridor absorb rapid delivery fulfillment through direct-to-consumer platforms absorbing last-mile logistics costs.
- Restaurants:Quick-service chains accelerate frozen appetizer procurement as labor costs climb and kitchen staffing shortages persist. Tyson Foods leverages integrated poultry processing to supply bulk contracts with superior per-unit margins.
- Food Trucks:Mobile operators prioritize single-serve formats with minimal equipment requirements.
- Catering Services:Event-based demand concentrates in metropolitan nodes with cold-chain density supporting rapid replenishment.
Households absorb the greatest volume tonnage. Restaurants generate the highest per-unit profitability.
Distribution Channel:
Cold-chain infrastructure investment and replenishment velocity determine competitive positioning across physical and digital retail formats.
- Supermarkets:Frozen pizza commands shelf space through continuous topping and crust innovation. General Mills leverages captive flour-milling networks to stabilize input costs for crust production across U.S. and Canadian banners.
- Online Retail:Direct-to-consumer frozen delivery platforms are absorbing last-mile logistics costs previously borne by retailers. Canadian urban distribution nodes in Toronto, Montreal, and Vancouver create regional supply bottlenecks that first-mover suppliers can preempt.
- Convenience Stores:Single-serve SKUs retain the highest purchase-frequency metrics for immediate consumption occasions.
- Wholesale:Bulk procurement contracts serve institutional buyers with standardized specifications.
Supermarkets maintain the broadest SKU breadth. Online retail is gaining share fastest.
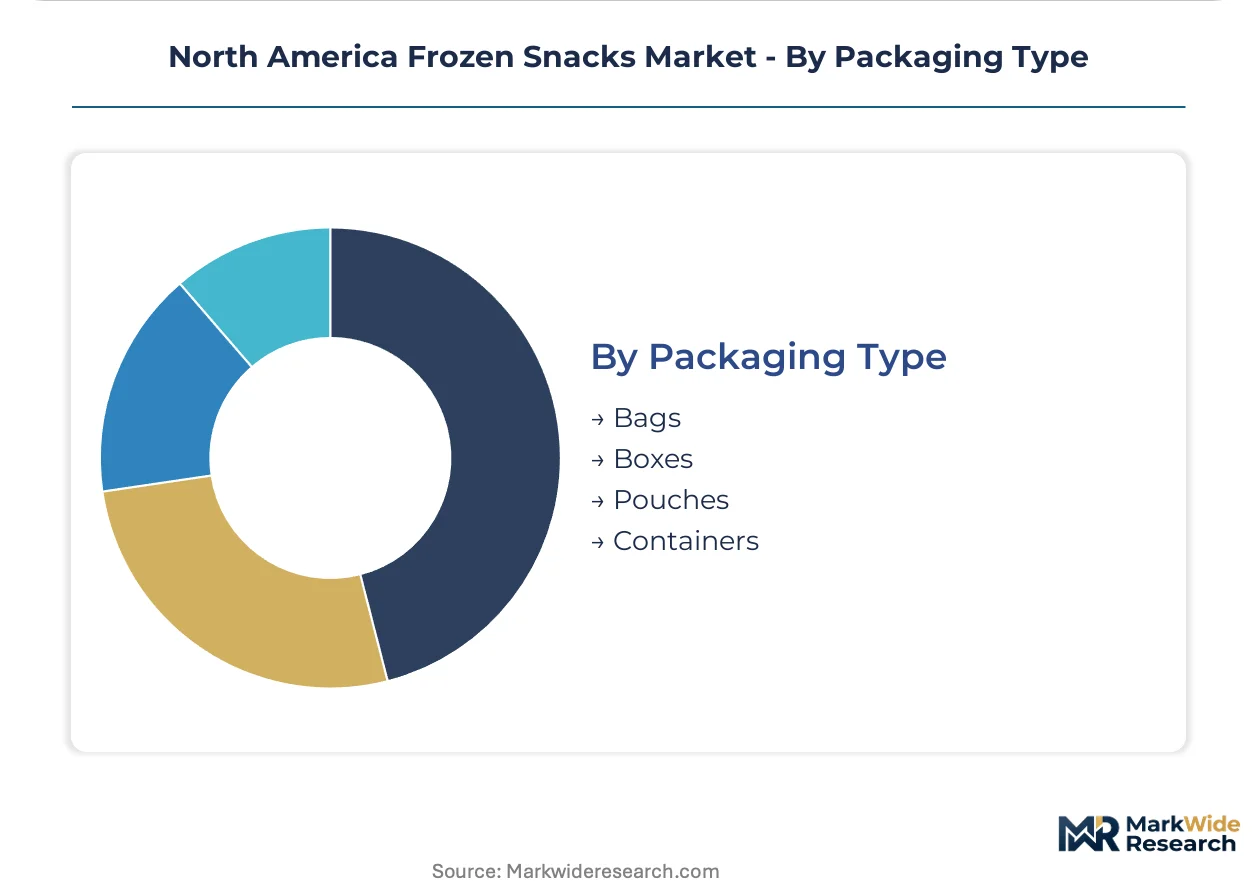
Packaging Type:
Temperature integrity and reheating convenience drive material selection across formats with varying barrier properties and consumer interaction design.
- Boxes:Structural rigidity protects pizza crust integrity through distribution handling. Dual-language English-French packaging redesigns for Canadian export compliance integrate FDA Nutrition Facts updates and Health Canada front-of-package warning proposals.
- Bags:Flexible formats reduce cube utilization for frozen vegetables and fruits in wholesale distribution.
- Pouches:Single-serve configurations dominate convenience store velocity for handheld snack formats.
- Containers:Rigid formats with resealable features support ice cream premium positioning and multi-use household consumption.
Boxes carry the greatest frozen pizza volume. Pouch configurations are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage pressures are reshaping frozen snack production geography across North America, as manufacturers weigh FDA sodium-reduction timelines against Health Canada's front-of-package labeling proposals when siting new capacity.
United States
Quick-service restaurant chains are accelerating frozen appetizer procurement as labor costs climb and kitchen staffing shortages persist. The FDA's updated Nutrition Facts labeling requirements are forcing reformulation cycles that favor cleaner ingredient decks. The U.S. Northeast corridor between Boston and Washington D.C. anchors cold-chain density, enabling daily replenishment cycles that convenience retailers require for high-velocity single-serve SKUs.
Canada
Urban distribution nodes in Toronto, Montreal, and Vancouver are hardening cold-storage infrastructure, tightening regional supply availability for cross-border suppliers. Health Canada's CFIA enforces Safe Food for Canadians Regulations with parallel safety protocols to USDA mandates, creating compliance harmonization pressure. Canadian quick-service operators are expanding frozen procurement as labor costs mirror U.S. escalation patterns.
Mexico
Manufacturers are evaluating northern border states for export-oriented frozen snack production serving U.S. retail and foodservice channels. Mexico's national food safety regulator maintains protocols for frozen meat and poultry components that align with USDA pathogen-control frameworks. Industrial clusters in Nuevo León and the Bajío Region are absorbing cold-chain investment targeting North American integration.
North America Frozen Snacks Market Competitive Landscape
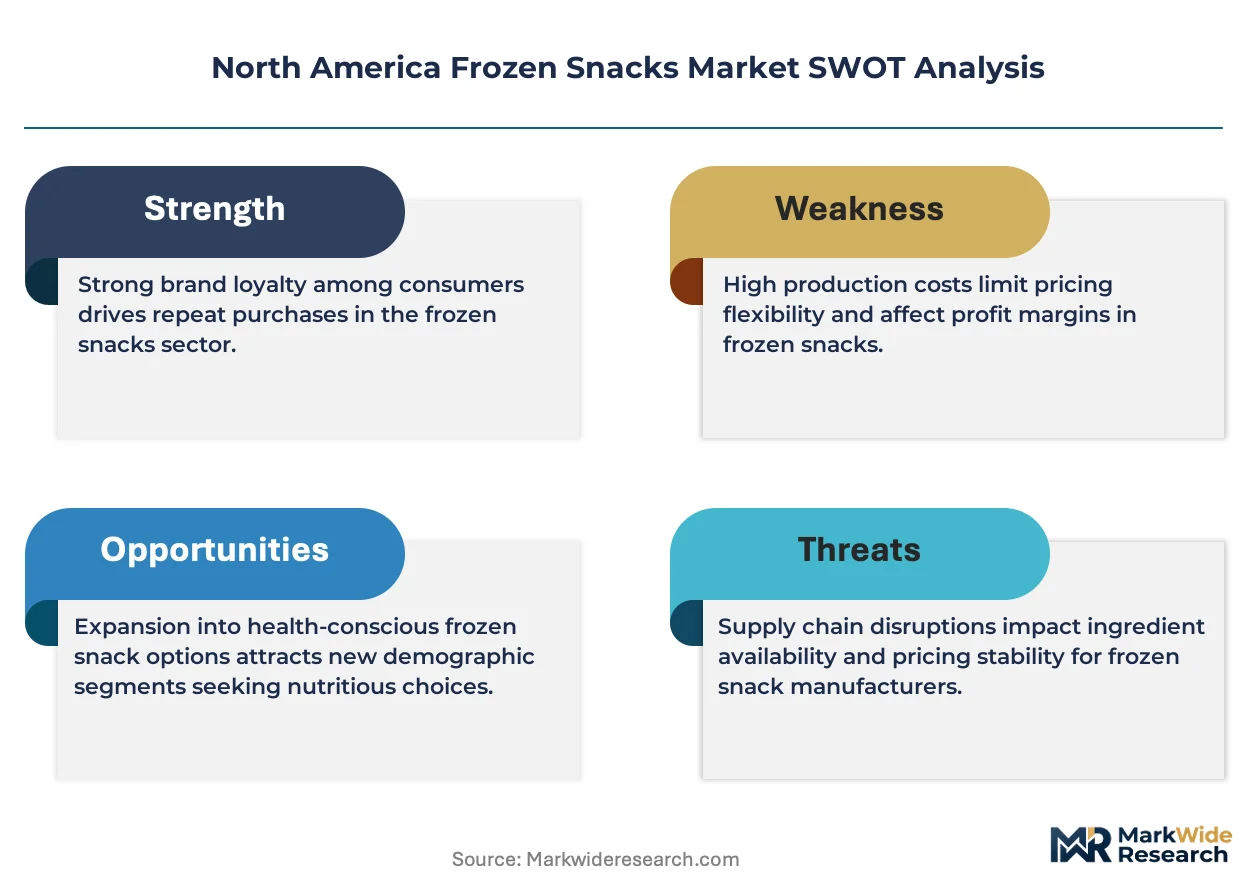
U.S. producers anchor one tier of frozen snack supply; Canadian specialists hold regional distribution advantages through integrated cold-chain assets. The market structure concentrates around diversified food conglomerates with captive ingredient networks and dedicated frozen manufacturing footprints. Three archetypes dominate: integrated protein processors with backward control over poultry supply, diversified consumer goods groups with flour-milling assets, and premium dessert specialists with cryogenic freezing capabilities. Competitive moves center on reformulation investments for clean-label compliance and cold-chain capacity expansion at urban distribution nodes.
Within the integrated processor tier, Tyson Foods exemplifies upstream control through poultry operations feeding directly into frozen appetizer lines. General Mills anchors crust production economics through captive flour-milling networks stabilizing input costs across U.S. and Canadian banners. Nestlé S.A. occupies a position in premium frozen dessert manufacturing through dedicated Midwest assets serving cross-border distribution.
| Leading Market Players |
|---|
| General Mills |
| Tyson Foods |
| Nestlé S.A. |
| Hormel Foods Corporation |
| Schwan's Company |
| Conagra Brands |
| Kraft Heinz Company |
| Unilever PLC |
| McCain Foods |
| Others |
Value Network & Pricing Analysis
Wheat flour input costs cascade through frozen pizza crust production into three-tier pricing structure across premium, standard, and economy levels, with captive milling networks insulating integrated manufacturers from commodity volatility that compresses margins for dependent competitors.
Pricing Analysis
Distributor margin layers absorb cold-chain logistics premiums before retailer markup finalizes shelf positioning. Pricing stratifies across premium, standard, and economy tiers driven by crust formulation complexity and topping ingredient provenance. Cost compression in the economy tier is intensifying because wheat flour price volatility feeds directly into base product economics. Quick-service restaurant chains exhibit lowest price sensitivity through bulk procurement contracts, while convenience store single-serve buyers demonstrate highest elasticity.
Supply Chain Analysis
USDA and CFIA certification gating for meat and poultry components creates qualification barriers that filter supplier participation. Production concentrates in the United States, Canada, and northern Mexico border states serving North American integration. Raw material flows draw from wheat belts, poultry processing clusters, and dairy production regions. Single-source vulnerability emerges from concentrated blast freezing equipment manufacturing. Distribution runs through refrigerated warehouse networks anchored at urban cold-storage nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in frozen snacks rests on clean-label reformulation premiums offsetting input cost volatility, with premium ice-cream and appetizer tiers capturing value from health-conscious household buyers.
For Market Incumbents: Deploy captive ingredient networks to stabilize crust and protein input economics against commodity swings. Accelerate sodium-reduction reformulation ahead of FDA and Health Canada front-of-package warning mandates to preempt delisting risk. Consolidate regional cold-storage capacity at Toronto, Montreal, and Vancouver nodes before supply bottlenecks harden. For New Entrants and Emerging Players: Ghost kitchen delivery platforms represent the most penetrable channel white-space, bypassing traditional retail slotting barriers. Target online subscription models for urban Northeast corridor households absorbing last-mile logistics costs. Pursue co-manufacturing partnerships with underutilized cryogenic freezing assets to minimize capital intensity. For Investors and Strategic Acquirers: Consolidation pressure builds where cold-chain infrastructure scarcity meets fragmented regional supplier bases. Mid-term viability favors integrated processors with backward poultry control or captive flour milling. Watch for FDA sodium-reduction timeline acceleration as inflection signal triggering reformulation investment surges.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation | FDA and Health Canada front-of-package proposals favor shorter ingredient decks commanding shelf premiums. |
| Cold-Chain Capacity Expansion | Toronto, Montreal, and Vancouver urban nodes create regional supply bottlenecks for first-mover capture. |
| Online Retail Channel Convergence | Direct-to-consumer platforms absorb last-mile logistics costs previously borne by retailers. |
| Captive Ingredient Integration | Integrated poultry processing and flour milling stabilize input costs against commodity volatility. |
| Cryogenic Freezing Technology Adoption | Blast freezing advances enable vegetable-based and dairy-based formats previously excluded from frozen categories. |
Research Methodology
Direct dialogue with frozen food manufacturing executives, quick-service restaurant procurement directors, cold-chain logistics operators, and retail category buyers grounded qualitative insights in operational reality. Secondary validation drew from FDA enforcement reports, USDA pathogen-control guidance, CFIA Safe Food for Canadians Regulations, and Nielsen retail audit data. Bottom-up production capacity modeling and top-down demand segmentation triangulated market sizing across the analysis window.
Segment-level outputs reflect product type, end-user procurement pattern, distribution channel velocity, and packaging format economics modeled across the projection horizon. CAGRs derived from historical volume trajectories, regulatory timeline impacts, and channel shift elasticity parameters. Forecast inputs incorporated blast freezing technology adoption curves and sodium-reduction reformulation cycle timing.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA-Health Canada regulatory divergence and wheat commodity price volatility. Forecasts reflect documented assumptions about labor cost escalation patterns and cold-chain infrastructure investment timelines. A model refresh is warranted upon material change in front-of-package labeling mandate implementation schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
India Snack Bar Market
Snacks
Cheese Snacks Market
Snacks
North America Baked Savory Snacks Market
Snacks
Flexible Plastic Snack Food Packaging Market
Snacks
Premium Snacks Market
Snacks
Saudi Arabia Snacks Industry Market
Snacks
Low Calorie Cookies Market
Snacks
France Energy Bar Market
Snacks
Snack Food Packaging Market
Snacks
Middle East Snack Bar Market
Snacks
No Fat Snacks Market
Snacks
Low Fat Sweet Snacks Market
Snacks
United Kingdom Energy Bar Market
Snacks
Instant Meat Marinated Snacks Market
Snacks
Fat Free Snacks Market
Snacks
Europe Frozen Snacks Market