
 Low Temperature Battery Market | 2026-2036
Low Temperature Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Low Temperature Battery Market Insights
Project finance tied to cold-climate infrastructure is fragmenting competitive access across the low temperature battery sector. CATL leverages its integrated cathode material operations to sustain cost advantages in sub-zero cell production. Samsung SDI anchors premium positioning through solid-state electrolyte development for aerospace applications. Grepow specializes in compact formats that dominate portable device contracts for polar research expeditions.
A low temperature battery is an electrochemical energy storage device engineered to maintain discharge efficiency and ionic conductivity at temperatures below minus 20 degrees Celsius, typically achieved through modified electrolyte formulations, low-resistance electrode architectures, and integrated thermal management subsystems. Its primary purpose is to deliver reliable power in environments where standard lithium-ion cells suffer capacity fade, mechanical failure, or lithium plating hazards. Lithium Ion chemistry occupies the dominant revenue share due to established manufacturing scale and energy density requirements in automotive cold climate vehicle platforms. Solid State technology represents the fastest-expanding segment as electrochemical stability and reduced thermal runaway risk attract military equipment and aerospace procurement budgets. Nickel Metal Hydride retains niche positions in remote monitoring installations where cost sensitivity outweighs performance optimization.
The EPA and FAA in the United States impose distinct testing protocols for battery systems deployed in aviation and ground transport, while China's MIIT enforces GB standards that govern low-temperature cycle life and safety thresholds for domestic and export-bound manufacturers. REACH compliance in Europe restricts certain electrolyte additives, compelling reformulation investments that reshape supplier qualification timelines. Stakeholders must monitor how divergent thermal management system certification requirements across regulators affect platform standardization strategies and cross-border equipment compatibility.
Market Dynamics
Electrolyte formulation patents held by a concentrated supplier base are reshaping competitive access in sub-zero battery production, as cathode material integration becomes the decisive cost lever for automotive cold-climate platforms.
Growth Catalysts
- Arctic logistics electrification:Commercial fleet operators in Norway, Finland, and Canada's northern territories are mandating low-temperature battery specifications for last-mile delivery vehicles operating below minus 25 degrees Celsius.
- China's GB/T 31467.3 standards:The MIIT's tightened low-temperature cycle life thresholds are forcing export-bound manufacturers to reformulate electrolyte additives, accelerating qualification timelines for cross-border suppliers.
- Solid-state electrolyte maturation:Sulfide-based ceramic conductors are achieving ionic conductivity benchmarks previously unattainable in liquid systems, opening procurement budgets in aerospace thermal management applications.
Market Restraints
- Lithium carbonate volatility:Cathode precursor costs swing with spot market fluctuations, compressing margins for cell producers locked into fixed-price automotive supply agreements.
- Separator membrane concentration:Wet-process polyolefin supply chains cluster in East Asian manufacturing corridors, exposing non-integrated assemblers to single-source disruption risk.
- Fluorinated electrolyte restrictions:REACH Annex XVII limitations on perfluorinated compounds are forcing solvent reformulation investments that extend European qualification cycles by 8-14 months.
Strategic Opportunities
- Maritime cold-chain electrification:Norway's northern port clusters serving offshore wind installation vessels represent underpenetrated demand for modular sub-zero energy storage systems.
- Dual-use military procurement:Convergence of solid-state architectures with conformal battery geometries is unlocking defense equipment specifications for polar expeditionary forces.
- India's PLI scheme extension:Advanced chemistry cell manufacturing incentives now explicitly cover low-temperature performance tiers, attracting cathode material joint ventures into Gujarat and Tamil Nadu.
Industry Challenges
- Electrolyte formulator talent scarcity:Industrial-scale experience with sulfide ceramic processing resides with a narrow cohort of materials scientists concentrated in Japanese and South Korean research institutes.
- Multi-jurisdiction certification stacking:Simultaneous EPA automotive, FAA aviation, and MIIT export testing protocols create redundant validation costs for unified product platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Temperature Battery Market |
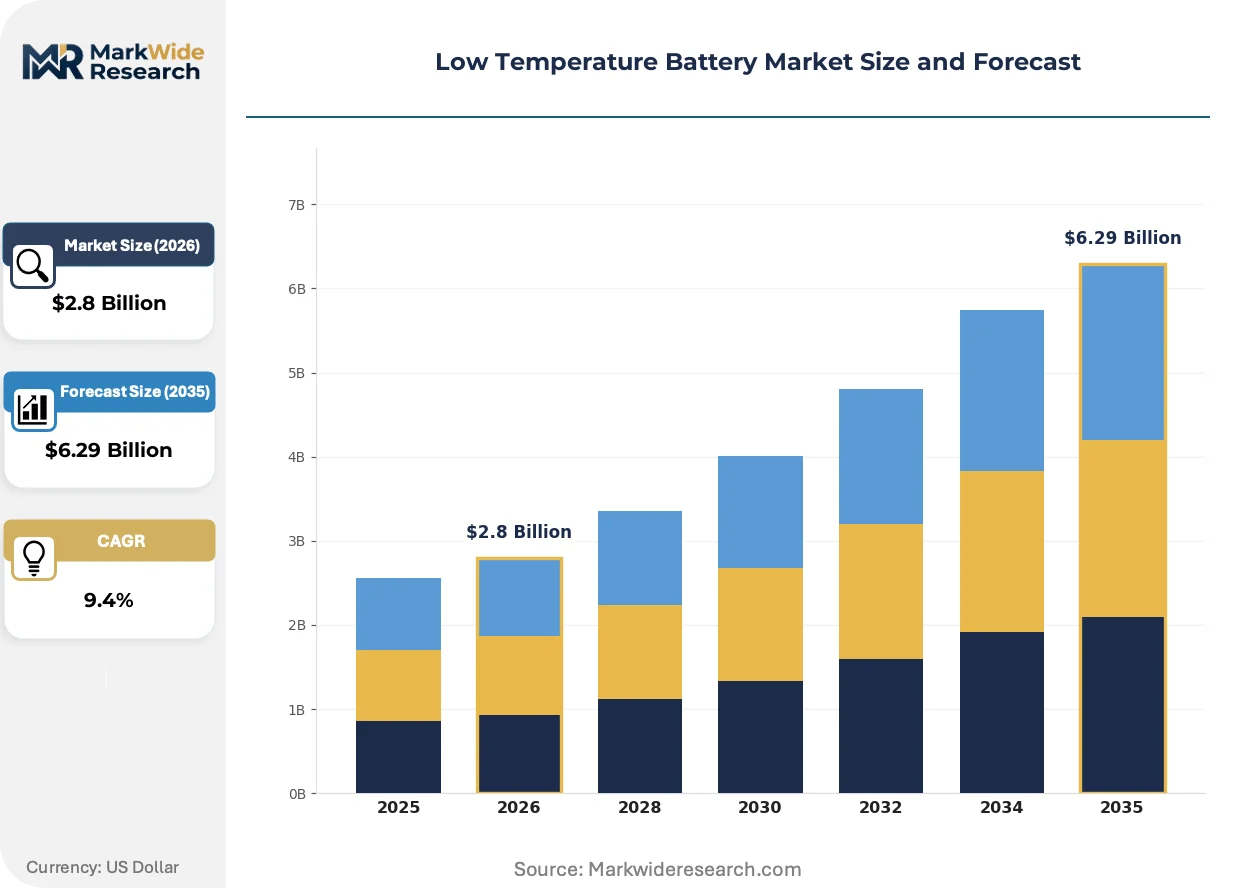
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium Ion, Nickel Metal Hydride, Lead Acid, Solid State End User: Automotive, Aerospace, Consumer Electronics, Energy Storage Application: Cold Climate Vehicle, Remote Monitoring, Portable Devices, Military Equipment Technology: Charge Control, Electrochemical, Thermal Management, Battery Management System |
| Companies Covered | CATL, JEVE, BYD, Samsung SDI, Grepow, Nichicon, LISHEN, UltraXel Limited, Large Power, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Temperature Battery Market Trends and Innovations
Sulfide-based solid-state architectures are collapsing the performance gap between laboratory demonstrations and production-scale cell manufacturing, while regulatory divergence across major economies is fragmenting standardization pathways.
Sulfide ceramic electrolytes are replacing carbonate liquid solvents in pilot production lines for aerospace battery systems. Defense procurement agencies in the United States and Nordic countries are accelerating qualification timelines for conformal solid-state packs. This chemistry is collapsing the traditional trade-off between energy density and cold-start reliability that has constrained polar vehicle electrification.
REACH compliance deadlines for fluorinated electrolyte additives are forcing European suppliers to accelerate solvent substitution programs. ECHA's restriction proposals on per- and polyfluoroalkyl substances are compressing reformulation investment windows to 18-24 months. Automotive OEMs with pan-European assembly footprints are responding by dual-sourcing electrolyte formulations from compliant and legacy suppliers during transition periods.
Battery-as-a-service contracting is displacing capital purchase models in Arctic commercial fleet operations. Logistics operators in Norway and Finland are unbundling cell ownership from vehicle acquisition, transferring degradation risk to energy service providers. This restructuring is most visible in offshore supply vessel electrification programs where utilization-based pricing aligns operator incentives with cycle life optimization.
Low Temperature Battery Market Segmentation
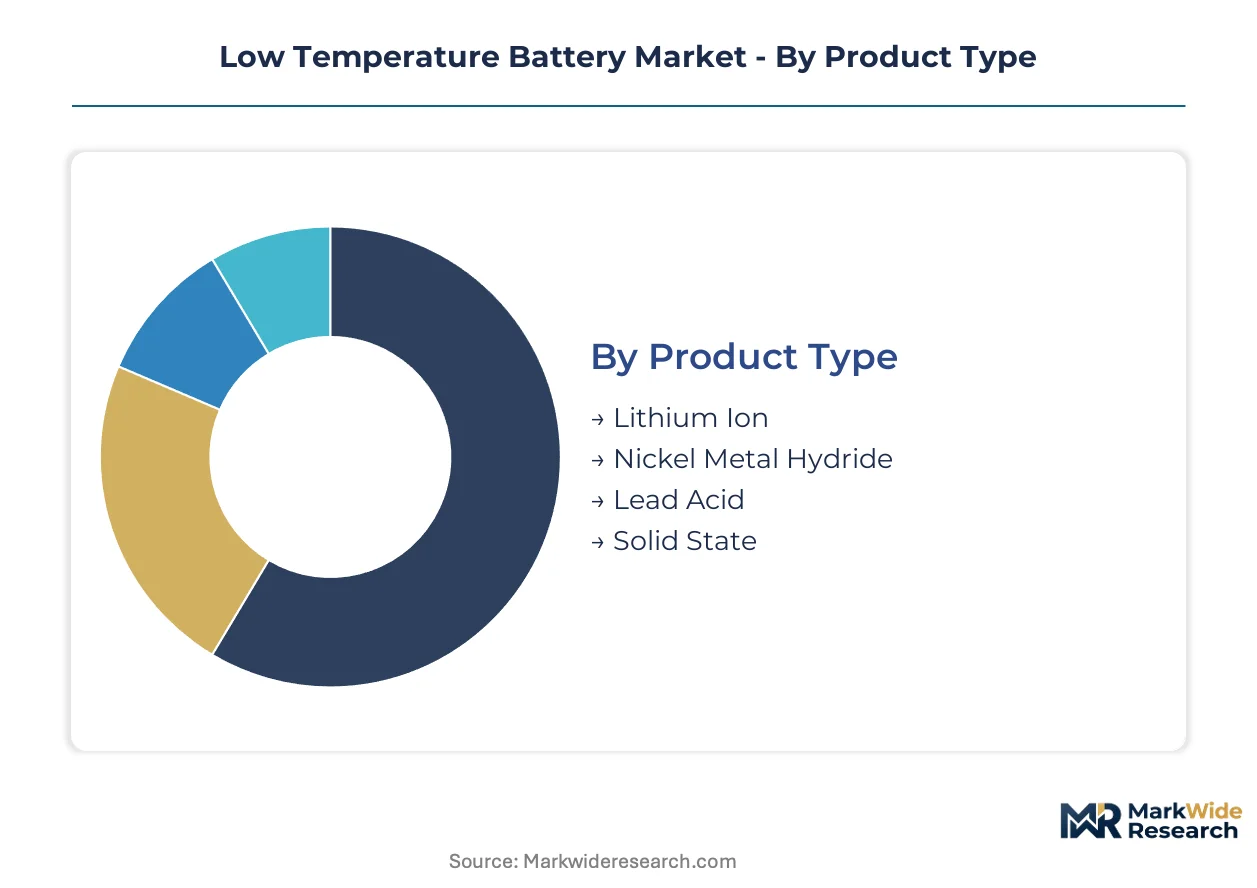
Low temperature battery procurement patterns diverge sharply across chemistry platforms and thermal management architectures. Each segment tier carries distinct qualification burdens and supply chain concentration risks that reshape vendor access.
Product Type:
Chemistry selection determines the thermal floor, energy density trade-off, and manufacturing capital intensity for sub-zero deployment.
- Lithium Ion:Graphite-anode cells with carbonate electrolyte modifications achieve discharge efficiency at minus 25 degrees Celsius through low-viscosity solvent blends. Norwegian automotive OEMs and Arctic logistics fleets anchor procurement volume for cold climate vehicle platforms.
- Solid State:Sulfide ceramic electrolytes eliminate liquid freezing constraints while suppressing lithium dendrite formation at extreme temperatures. Aerospace qualification programs in the United States and Nordic defense procurement are accelerating pilot production scale-up.
- Nickel Metal Hydride:Aqueous potassium hydroxide electrolyte resists freezing but sacrifices gravimetric density; remote Alaskan and Canadian monitoring installations tolerate the weight penalty for cost containment.
- Lead Acid:Flooded and absorbed glass mat variants serve legacy backup power in Siberian infrastructure where replacement cycles extend beyond performance optimization horizons.
Lithium Ion commands the established base. The steepest expansion runs through Solid State.
End User:
Customer archetypes impose divergent certification stacks and performance degradation tolerances on cell suppliers.
- Automotive:OEM cold climate vehicle specifications mandate cycle life retention above 80 percent after 1,000 sub-zero cycles. Finland and Norway have mandated low-temperature performance thresholds for commercial fleet procurement.
- Aerospace:FAA testing protocols for thermal runaway containment dominate qualification timelines. Solid-state architectures are displacing legacy lithium-polymer in high-altitude drone and satellite applications.
- Consumer Electronics:Polar research expeditions and alpine sports equipment drive compact format demand. Grepow and similar specialists capture portable device contracts through conformal geometries.
- Energy Storage:Grid-scale installations in sub-Arctic regions prioritize cell longevity over power density. Russia and Canada are deploying containerized systems for remote community electrification.
Automotive absorbs the dominant procurement volume. Aerospace is climbing the fastest as defense budgets reallocate toward polar expeditionary capabilities.
Application:
Deployment context dictates thermal management subsystem complexity and packaging form factor requirements.
- Cold Climate Vehicle:Battery packs integrate active heating loops and phase-change materials to sustain discharge rates during startup events. Norway's northern port clusters are electrifying offshore supply vessels with modular sub-zero storage.
- Military Equipment:Conformal solid-state packs must survive mechanical shock and thermal cycling without auxiliary heating. United States and Nordic defense agencies are converging specifications for polar expeditionary forces.
- Remote Monitoring:Unattended installations in Siberia and northern Canada favor Nickel Metal Hydride for maintenance intervals exceeding five years.
- Portable Devices:Compact cylindrical and pouch formats dominate scientific instrumentation for Antarctic and Greenland research stations.
Cold Climate Vehicle anchors current revenue concentration. Military Equipment is gaining share fastest through dual-use procurement convergence.
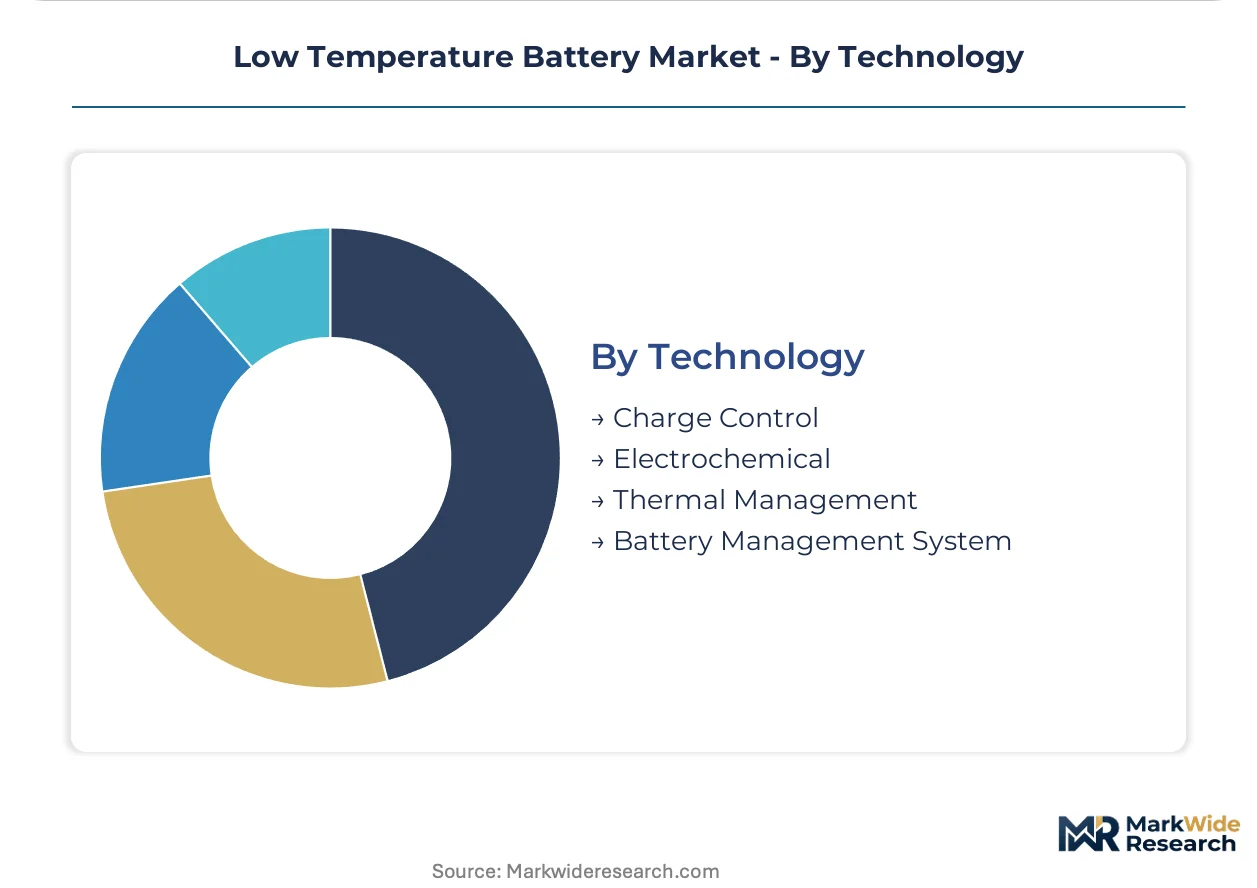
Technology:
Subsystem architecture determines thermal equilibrium maintenance and safety monitoring capabilities across operating envelopes.
- Thermal Management:Active heating films and phase-change material integration add 15-25 percent pack mass but enable minus 40 degrees Celsius operation. Arctic logistics operators are mandating these subsystems for commercial fleet electrification.
- Battery Management System:Firmware-controlled charge rate throttling prevents lithium plating during cold startup. China's GB standards are tightening BMS certification thresholds for export-bound suppliers.
- Electrochemical:Electrolyte additive selection and electrode porosity engineering modify ionic conductivity without external heating. Japanese and South Korean research institutes hold concentrated formulation expertise.
- Charge Control:Algorithms adapt current profiles based on cell temperature telemetry, extending cycle life in variable cold environments.
Thermal Management commands the installed base. Battery Management System is expanding most quickly as software-defined safety becomes a procurement differentiator.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-bound manufacturers face divergent certification burdens across destination markets, with China's tightening GB standards reshaping cross-border supplier qualification timelines and European REACH compliance forcing electrolyte reformulation investments.
China
MIIT's GB/T 31467.3 standards mandate stricter low-temperature cycle life thresholds for automotive battery exports. The Yangtze River Delta hosts concentrated cathode material production serving both domestic OEMs and cross-border supply chains. Shenzhen and Ningbo port clusters are expanding cold-chain logistics electrification for maritime applications.
Norway
Arctic logistics fleet operators mandate sub-zero battery specifications for commercial vehicles operating below minus 25 degrees Celsius. The country's national maritime regulator enforces thermal management system certification for offshore supply vessel electrification. Tromsø and Hammerfest port clusters anchor procurement for modular energy storage systems serving wind installation vessels.
United States
FAA testing protocols for thermal runaway containment dominate aerospace battery qualification timelines. EPA automotive standards and defense procurement specifications create overlapping certification requirements for dual-use solid-state architectures. Alaska's remote monitoring installations drive niche demand for maintenance-tolerant electrochemical systems.
Germany
ECHA's REACH Annex XVII restrictions on perfluorinated electrolyte compounds compress European reformulation investment windows. The KBA enforces cold-climate vehicle battery safety thresholds for automotive OEM supply agreements. Bavaria's industrial corridor hosts thermal management subsystem engineering for Arctic commercial fleet platforms.
Finland
Commercial fleet procurement mandates now require documented low-temperature performance for last-mile delivery electrification. The country's transport safety authority aligns with Nordic defense specifications for polar expeditionary equipment. Oulu and Rovaniemi logistics hubs are transitioning offshore supply operations to battery-as-a-service contracting models.
Low Temperature Battery Market Competitive Landscape
On the supply side, the industry is consolidating around integrated cathode material operations and specialized electrolyte formulation expertise. Tiered competitive positioning separates scale-driven automotive suppliers from premium-tier solid-state specialists and compact-format portable device fabricators. Dominant competitive moves include backward integration into cathode precursor production and strategic partnerships with defense procurement agencies for polar expeditionary specifications.
Within the integrated materials tier, CATL anchors scale advantages through captive cathode production, while Samsung SDI occupies a position exemplifying premium solid-state development for aerospace applications. Grepow represents the compact-format specialization archetype serving polar research instrumentation contracts.
| Leading Market Players |
|---|
| CATL |
| JEVE |
| BYD |
| Samsung SDI |
| Grepow |
| Nichicon |
| LISHEN |
| UltraXel Limited |
| Large Power |
| Others |
Pricing and Supply Chain Analysis
The Yangtze River Delta's cathode material concentration gives integrated Chinese producers leverage over export pricing, while European reformulation costs from REACH compliance compress margin structures for non-integrated assemblers serving automotive cold-climate platforms.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on GB/T 31467.3 certification grade and cathode precursor integration depth. Cost compression in standard-tier cells is intensifying because lithium carbonate spot volatility feeds through fixed-price automotive contracts. Fleet operators in Arctic logistics show highest price sensitivity, while aerospace procurement tolerates premium positioning for solid-state thermal management performance.
Supply Chain Analysis
Lithium carbonate feedstock draws from Chilean and Australian extraction corridors, with Chinese refining dominance concentrating precursor supply. Cathode active materials, ceramic sulfide electrolytes, and wet-process polyolefin separators constitute critical input dependencies. Single-source vulnerability runs through East Asian separator membrane production. Distribution runs through direct long-term offtake agreements with automotive OEMs and defense procurement agencies, bypassing spot market exposure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state electrolyte maturation represents a technological inflection disrupting incumbent liquid-cell economics, while China's tightening GB standards and Europe's REACH deadlines compress qualification windows for cross-border suppliers.
For Market Incumbents: Pre-empt margin erosion by capturing cathode precursor supply through backward integration into Yangtze River Delta material corridors. Accelerate sulfide ceramic processing R&D to defend aerospace positioning against emerging solid-state specialists. Lock in multi-year offtake agreements with Norwegian and Finnish Arctic fleet operators before battery-as-a-service models commoditize cell ownership.
For New Entrants and Emerging Players: Build out conformal solid-state pack capabilities targeting dual-use military procurement convergence between United States and Nordic defense agencies. Maritime cold-chain electrification in Norway's northern port clusters offers the most penetrable white-space, with modular sub-zero storage systems for offshore wind vessels underserved by incumbent automotive-focused suppliers. Lead with thermal management subsystem integration as your go-to-market wedge.
For Investors and Strategic Acquirers: Long-term, this sits as a defense-aerospace compounder play because polar expeditionary force modernization budgets are structurally decoupled from civilian automotive cyclicality. Target acquisition candidates with captive sulfide ceramic electrolyte formulation expertise and existing FAA qualification timelines. Watch for India's PLI scheme extension attracting cathode joint ventures into Gujarat as the signal that manufacturing gravity is shifting toward cost-competitive low-temperature tier production.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Precursor Production | CATL's captive Yangtze River Delta material operations sustain cost advantages in sub-zero cell output. |
| Solid-State Electrolyte Pilot Scale-Up | Samsung SDI's sulfide ceramic development unlocks FAA qualification for aerospace thermal management applications. |
| Battery-as-a-Service Contracting Model | Norwegian offshore vessel operators transfer degradation risk to energy service providers through utilization-based pricing. |
| Dual-Use Defense Procurement Partnership | Conformal solid-state pack specifications for polar expeditionary forces converge across United States and Nordic military agencies. |
| REACH-Compliant Electrolyte Reformulation | European suppliers face 18-24 month investment windows to substitute perfluorinated compounds under ECHA restriction proposals. |
Research Methodology
Initial hypotheses were tested against primary input from cathode material procurement directors, thermal management subsystem engineers, defense equipment specification officers, and Arctic logistics fleet operators, and refined through secondary validation against MIIT GB standard filings, ECHA REACH restriction proposals, FAA certification databases, and customs trade records for lithium carbonate and precursor materials. Bottom-up cell production estimates were triangulated against top-down automotive and aerospace procurement budget allocations.
Demand-supply balance modeling across the analysis window segmented by chemistry platform, thermal management architecture, end-use qualification tier, and regional regulatory cluster. CAGRs were derived from production capacity buildout timelines, fleet electrification mandates in Norway and Finland, and defense procurement budget trajectories for polar expeditionary equipment. Forecast inputs incorporated solid-state pilot production scale-up rates and electrolyte additive substitution investment cycles.
Stress conditions across lithium carbonate price volatility bands, REACH compliance deadline delays, and GB/T 31467.3 threshold revisions were modeled; outcomes outside those bands fall beyond the analytical envelope. Cross-checking against IEA critical mineral supply projections and national defense procurement disclosure filings is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Atomic Battery Market
Batteries
Potassium-Ion Battery Market
Batteries
Battery Separators Market
Batteries
Vietnam Battery Market
Batteries
Global Primary Cells Market
Batteries
GCC Rechargeable Battery Market
Batteries
East Asia Battery Market
Batteries
Battery Simulator Market
Batteries
N-Type Battery Market
Batteries
Battery Plate Market
Batteries
North America Consumer Battery Market
Batteries
Micro Mobility Battery PACK Market
Batteries
Battery Voltage Recorder Market
Batteries
Tubular GEL Battery Market
Batteries
PVT Battery Panel Market
Batteries
Zinc-Ion Battery Cells Market