
 South Africa Freight and Logistics Market | 2026-2036
South Africa Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Freight and Logistics Market Outlook
CEA licensing reforms for freight operators is pivoting the cost-of-entry calculus for new road haulage entrants. Transnet Freight Rail leverages its monopoly over the Cape and Richards Bay bulk corridors to sustain coal and iron ore throughput. DHL Group competes on express parcel networks, while Imperial Logistics dominates contract logistics for automotive and healthcare clients.
Freight and logistics encompasses the planning, execution, and management of goods movement across multimodal networks, with cargo consolidation requiring container standardization at twenty-foot equivalent units and temperature-controlled specifications for perishables. Its primary purpose is reducing inventory carrying costs while synchronizing supply with industrial production schedules. Road freight anchors volume throughput due to last-mile flexibility and underinvestment in rail infrastructure. Rail freight retains margin concentration in bulk minerals and long-haul corridors where Transnet controls dedicated lines. E-commerce providers represent the fastest-growing end user category as same-day delivery expectations reshape urban distribution topology.
BIS vehicle safety standards and CEA operator licensing govern road freight compliance costs, while the National Transport Master Plan directs public infrastructure spending toward corridor densification. SARS customs modernization initiatives are reshaping cross-border clearance velocity at Beitbridge and Lebombo. Stakeholders must monitor Transnet's capital allocation decisions and port concession renewals to anticipate capacity bottlenecks and tariff trajectories.
Market Dynamics
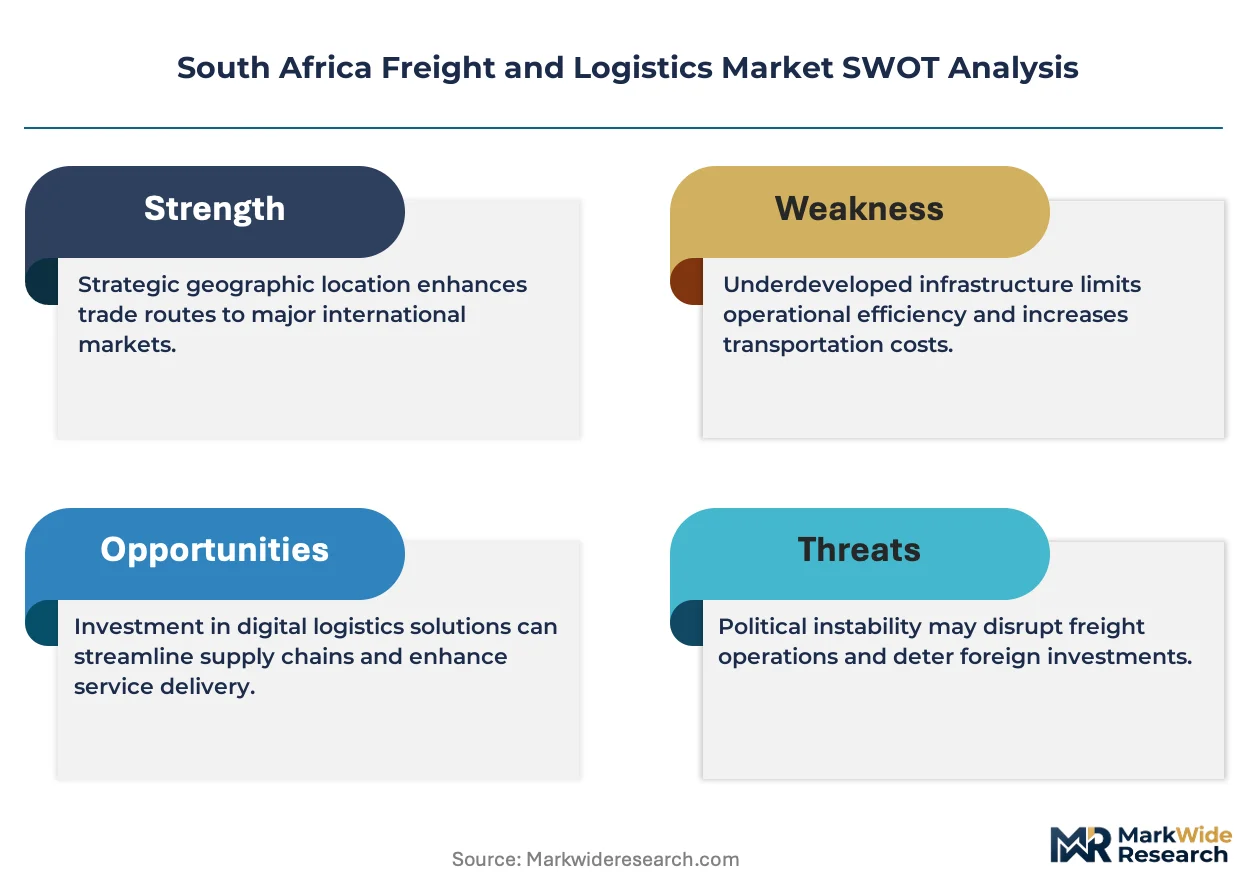
Transnet's monopoly over the Cape and Richards Bay bulk corridors is squeezing road freight margins while the National Transport Master Plan redirects public capital toward corridor densification, forcing logistics operators to recalibrate modal mix strategies.
Growth Catalysts
- Mining Outsourcing Surge:Extractive firms are divesting captive fleets to third-party logistics providers, expanding contract logistics addressable market.
- National Transport Master Plan:Corridor investment prioritization is unlocking dedicated freight lanes along the Durban-Gauteng axis.
- CEA Licensing Reforms:Streamlined operator certification is lowering entry barriers for specialized haulage categories.
Market Restraints
- Rail Infrastructure Underinvestment:Transnet's capital constraints limit modal shift acceleration from road to rail bulk.
- Fuel Price Volatility:Diesel cost swings compress road freight operator margins unpredictably.
- Port Capacity Bottlenecks:Durban and Cape Town terminal congestion extends vessel turnaround times.
Strategic Opportunities
- E-Commerce Distribution Topology:Same-day delivery expectations are reshaping last-mile node placement in Johannesburg and Cape Town.
- Temperature-Controlled Logistics:Pharmaceutical cold chain requirements are expanding specialized warehousing demand.
- Beitbridge Modernization:SARS customs automation initiatives are compressing cross-border clearance velocity for regional freight.
Industry Challenges
- Driver Certification Backlogs:Professional Driving Permit processing delays constrain fleet expansion timelines.
- Telematics Integration Complexity:Legacy fleet management systems resist seamless API connectivity with modern cargo tracking platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Freight and Logistics Market |
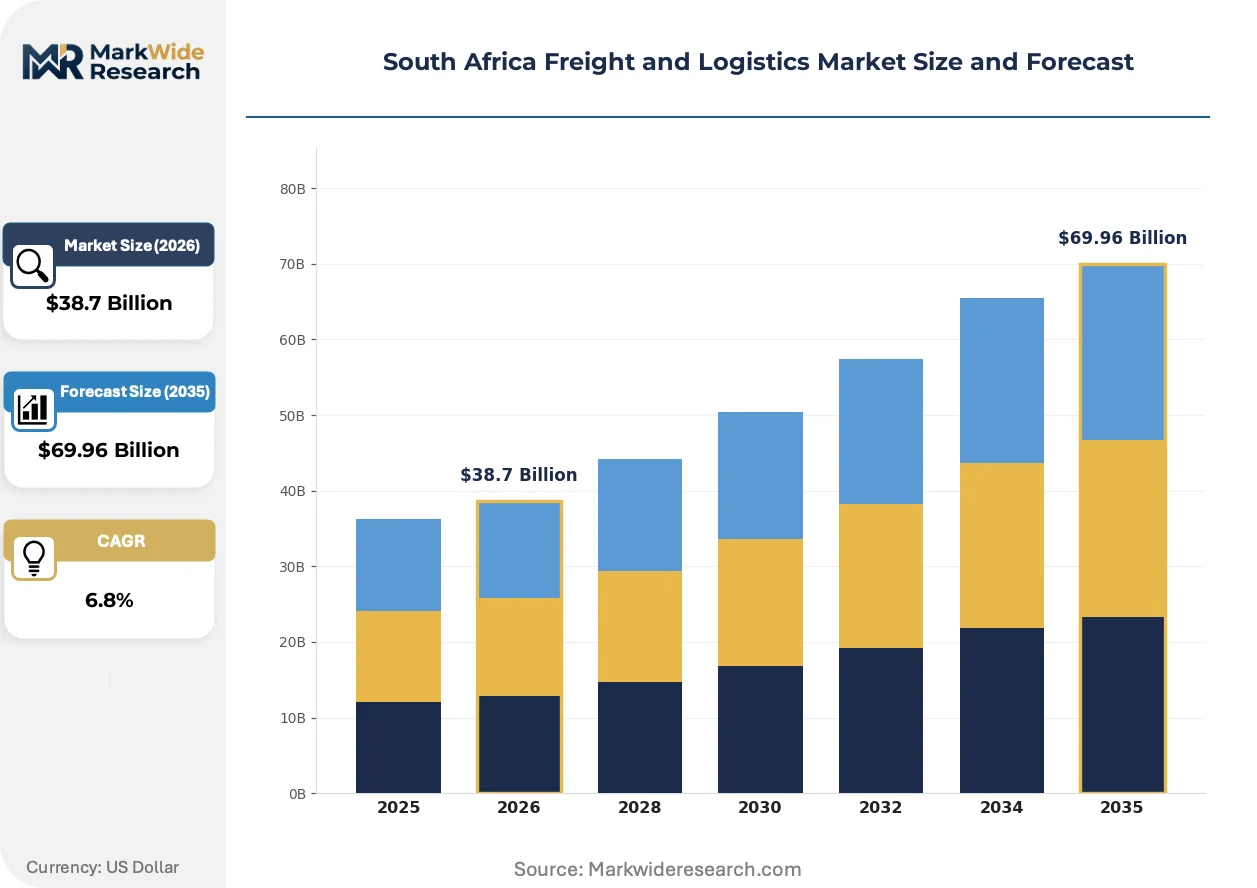
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Road Freight, Rail Freight, Air Freight, Sea Freight Delivery Mode: Direct Delivery, Scheduled Delivery, Same-Day Delivery, Deferred Delivery Industry Vertical: Retail, Manufacturing, Agriculture, Mining End User: Small Enterprises, Large Corporations, Government Agencies, E-commerce Providers |
| Companies Covered | DHL Group, Transnet Freight Rail, DP World, Bidvest Logistics, Bridgewater Logistics, Imperial Logistics, Kuehne+Nagel, Turners Shipping, DSV, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Freight and Logistics Market Strategic Shifts
Digital freight matching platforms and autonomous yard management systems are compressing dispatch-to-delivery cycles, while regulatory pressure on carbon intensity is forcing modal reconfiguration across the Gauteng-Johannesburg logistics cluster.
Telematics-enabled predictive maintenance is integrating real-time engine diagnostics with route optimization algorithms. Fleet operators serving the automotive sector are deploying these systems fastest, reducing unplanned downtime by synchronizing maintenance windows with delivery schedules. The technology is integrating asset utilization data directly into contract pricing structures.
The National Transport Master Plan mandates corridor densification investments that privilege rail-friendly cargo categories. Industrial shippers of coal and iron ore are recalibrating procurement specifications to lock in Transnet capacity allocations. Bulk mineral exporters face the steepest compliance cost adjustments as the plan redirects public infrastructure spending.
Consolidation among e-commerce fulfillment providers is compressing delivery service-level agreements from next-day to same-day standards. Urban distribution nodes in Pretoria and Durban are displacing centralized warehousing with micro-fulfillment centers positioned within 15-kilometer radii of dense consumer clusters. Healthcare and pharmaceutical verticals exhibit the most acute pressure for temperature-assured rapid delivery.
South Africa Freight and Logistics Market Segmentation
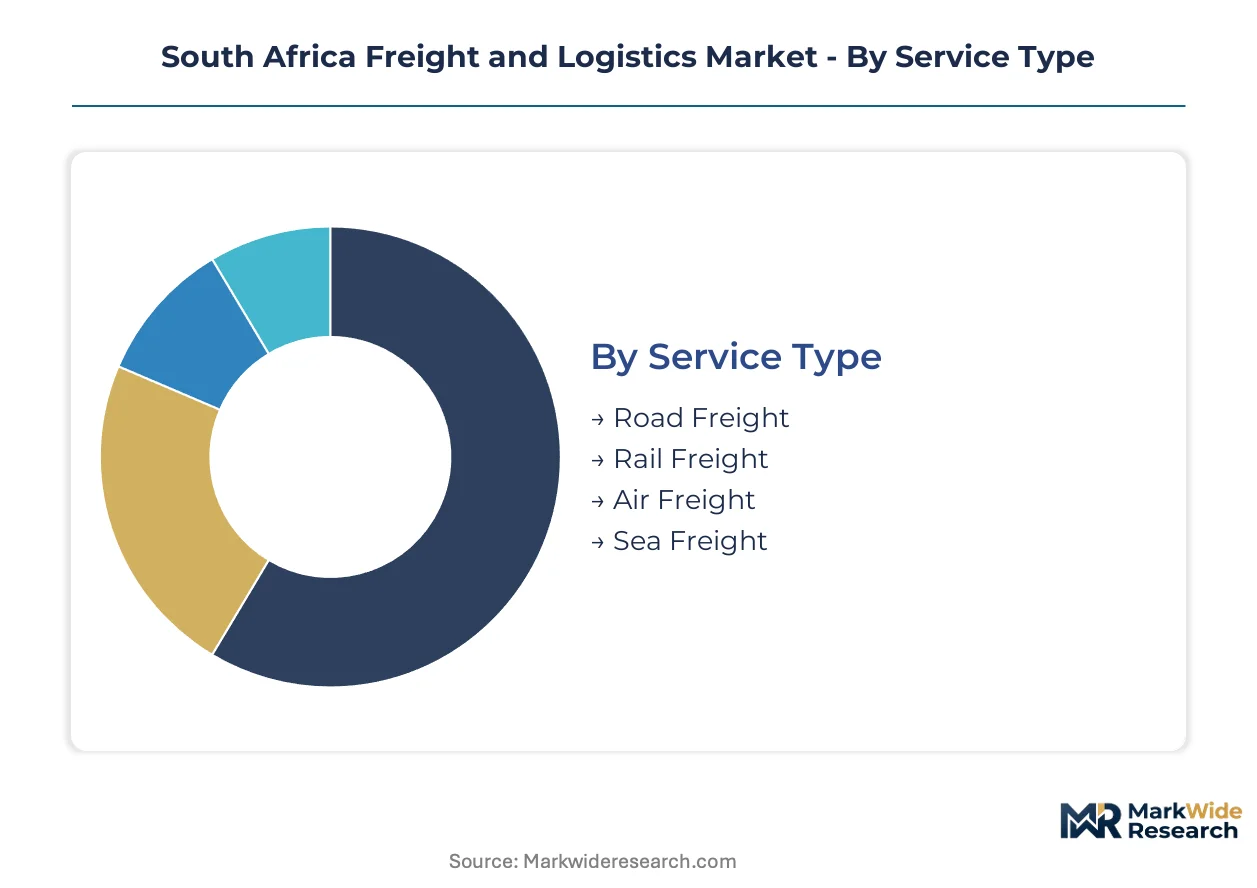
Modal choice in South Africa reflects infrastructure asymmetry: road dominates flexibility while rail captures bulk economies. Delivery speed expectations diverge sharply between mining supply chains and urban e-commerce fulfillment. Understanding segment boundaries reveals where Transnet's monopoly pricing power intersects with deregulated road competition.
Service Type:
Cost sensitivity and cargo density separate buyers across transport modes, with mineral exporters prioritizing unit cost per ton-kilometer against time-definite shippers valuing velocity premiums.
- Road Freight:Containerized and break-bulk cargo moves via articulated truck fleets on the N1 and N3 corridors. Last-mile flexibility anchors volume in the Gauteng-Johannesburg logistics cluster, though diesel price volatility compresses operator margins unpredictably.
- Rail Freight:Dedicated bulk corridors handle coal and iron ore movements from Mpumalanga and Northern Cape mines to Richards Bay and Cape Town terminals. Transnet's monopoly over these lines limits modal shift acceleration despite National Transport Master Plan corridor densification mandates.
- Air Freight:High-value electronics and pharmaceutical time-critical shipments utilize OR Tambo International cargo terminals. Premium pricing reflects constrained belly-hold capacity on domestic routes.
- Sea Freight:Containerized imports and bulk mineral exports flow through Durban, Cape Town, and Ngqura terminals. Port congestion at Durban extends vessel turnaround times, forcing shippers toward Cape Town alternatives.
Volume sits with Road Freight; growth tilts toward Sea Freight as port modernization unlocks throughput expansion.
Delivery Mode:
Inventory carrying cost tolerance distinguishes procurement specifications, with just-in-time manufacturers accepting premium pricing against bulk commodity traders optimizing for lowest landed cost.
- Direct Delivery:Point-to-point dedicated truck movements serve mining equipment and automotive component supply chains. Transnet Freight Rail's unreliable scheduling pushes sensitive cargo toward road-based direct options.
- Scheduled Delivery:Recurring lane assignments on fixed timetables support retail distribution center replenishment. Imperial Logistics and DHL Group compete on route density and departure frequency reliability.
- Same-Day Delivery:Urban micro-fulfillment networks position inventory within 15-kilometer radii of Johannesburg and Cape Town consumer clusters. E-commerce providers drive steepest expansion trajectory as service-level agreements compress from next-day standards.
- Deferred Delivery:Non-urgent consolidated shipments optimize load factors on backhaul lanes. Agricultural exporters utilize deferred ocean freight for seasonal harvest movements to European markets.
Revenue concentrates in Scheduled Delivery; margin expansion favors Same-Day Delivery as urban topology reshapes node placement economics.
Industry Vertical:
Supply chain complexity and regulatory exposure differentiate vertical requirements, with temperature-assured and hazardous cargo specifications filtering provider capabilities.
- Retail:Omnichannel fulfillment demands synchronize store replenishment with direct-to-consumer parcel flows. Fashion and electronics verticals exhibit highest same-day delivery penetration in Sandton and Cape Town CBD corridors.
- Manufacturing:Automotive assemblers in Rosslyn and Gqeberha mandate sequenced component deliveries synchronized to production takt times. Contract logistics providers integrate directly into supplier park operations.
- Agriculture:Perishable exports require cold chain integrity from farm gate to Cape Town refrigerated terminals. Citrus and table grape seasons create concentrated demand spikes testing capacity availability.
- Mining:Extractive firms divest captive fleets to third-party logistics providers, expanding contract logistics addressable market for heavy equipment and consumables movements to remote Northern Cape and Limpopo sites.
Contract value aggregates in Mining; volume velocity peaks in Retail as e-commerce penetration deepens.
End User:
Procurement sophistication and shipment scale stratify buyer power, with centralized logistics functions negotiating rate cards against fragmented SME spot market purchasing.
- Small Enterprises:Fragmented spot market purchasing concentrates on road freight brokers and digital freight matching platforms. CEA licensing reforms lower entry barriers for specialized haulage serving this segment.
- Large Corporations:Integrated supply chain functions negotiate multi-year contracts with tiered service-level agreements. Mining and automotive OEMs drive outsourcing surge to Imperial Logistics and DHL Group.
- Government Agencies:Public procurement regulations mandate BEE compliance and preferential supplier designation. Transnet's capital allocation decisions on rail infrastructure directly shape modal options for state freight.
- E-commerce Providers:Same-day delivery expectations reshape last-mile node placement, with Takealot and Amazon South Africa driving warehouse densification in Pretoria and Durban peripheries.
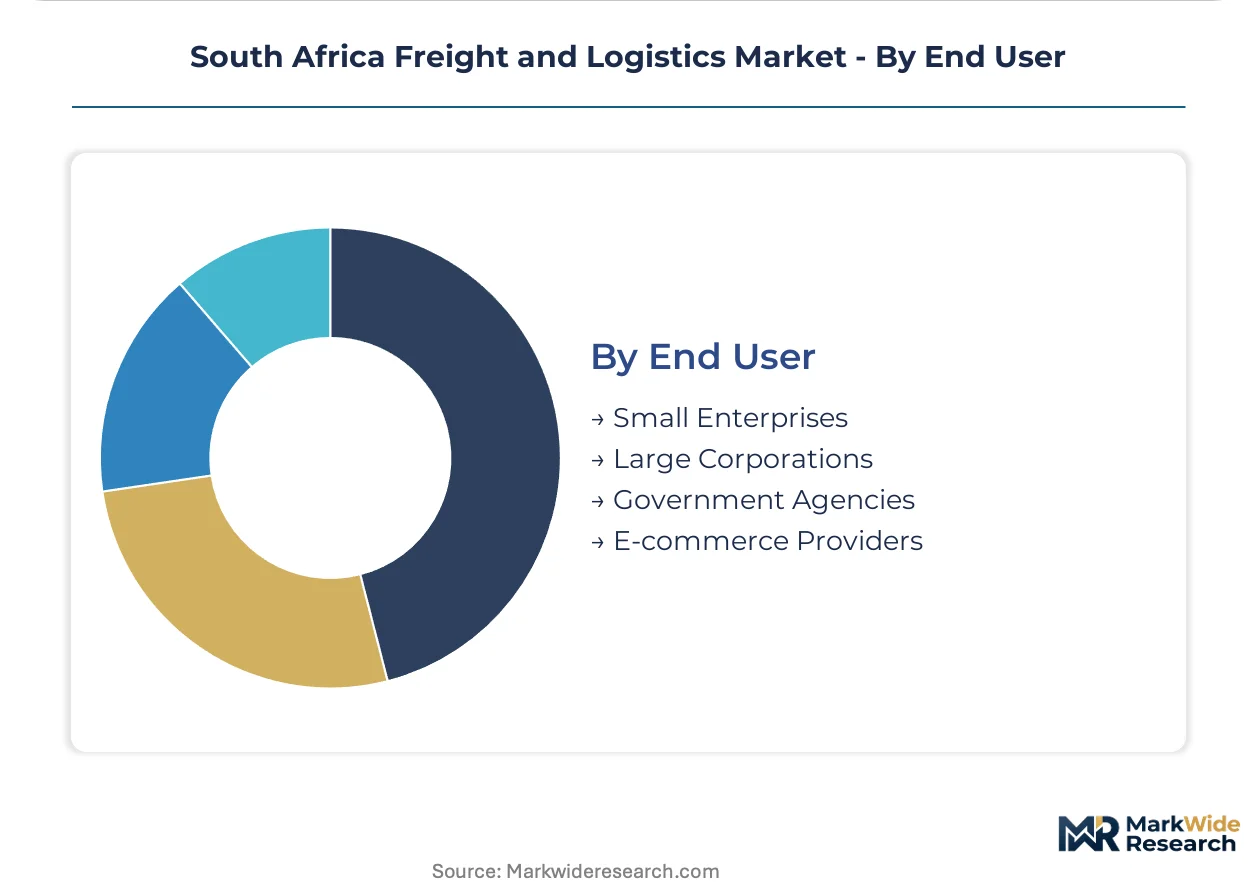
Shipment volume concentrates with Large Corporations; technology adoption spreads fastest among E-commerce Providers as fulfillment automation investments accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Coega Special Economic Zone near Port Elizabeth concentrates automotive and manufacturing logistics investment, while the Richards Bay Industrial Development Zone anchors bulk mineral export corridors. Provincial freight demand patterns diverge sharply between mineral-heavy Northern Cape and consumer-driven Gauteng logistics clusters.
Gauteng
Johannesburg and Pretoria logistics nodes handle the densest parcel volumes driven by e-commerce fulfillment expansion. The National Transport Master Plan prioritizes dedicated freight lanes along the N3 corridor toward Durban. The OR Tambo International cargo precinct processes high-value electronics and pharmaceutical time-critical shipments under pressure from same-day delivery standards.
KwaZulu-Natal
Durban container terminal congestion extends vessel turnaround times, forcing agricultural exporters toward Cape Town alternatives. Transnet's capital allocation decisions on port deepening directly shape regional throughput capacity. The Dube TradePort special economic zone integrates air cargo with temperature-controlled pharmaceutical warehousing.
Western Cape
Cape Town refrigerated terminals handle concentrated citrus and table grape export seasons testing cold chain capacity. SARS customs modernization at Cape Town port compresses clearance velocity for perishable cargo. The Atlantis Industrial zone hosts automotive component suppliers synchronizing sequenced deliveries to export assembly lines.
Northern Cape
Iron ore and manganese movements from Sishen and Hotazel mines to Saldanha Bay depend entirely on Transnet's dedicated bulk rail lines. Mining companies divest captive fleets to third-party logistics providers, expanding contract logistics addressable market. The Kathu logistics cluster serves as the primary equipment and consumables staging point for remote extraction sites.
Mpumalanga
Coal corridor throughput to Richards Bay dominates regional freight economics under Transnet Freight Rail monopoly pricing. The N4 toll road carries overflow mining equipment movements when rail scheduling proves unreliable. The Nelspruit logistics node positions agricultural processing exports toward Maputo port alternatives.
South Africa Freight and Logistics Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across modal boundaries, creating a tiered market structure where rail monopoly power intersects with deregulated road competition. Transnet Freight Rail controls dedicated bulk corridors while road freight fragments across hundreds of licensed operators. Three archetypes dominate: integrated multimodal providers, specialized contract logistics operators, and digital freight matching platforms. Consolidation through acquisition and strategic partnerships with mining houses represent the dominant competitive vectors as outsourcing accelerates.
Among integrated logistics groups, DHL Group and Imperial Logistics exemplify scale-driven multimodal positioning across express parcel and contract logistics segments. Transnet Freight Rail occupies the rail monopoly tier, controlling coal and iron ore corridor economics. Kuehne+Nagel and DSV represent global forwarding specialists competing on international connectivity and customs brokerage integration. Bidvest Logistics and Turners Shipping anchor mid-market contract logistics and shipping agency services respectively.
| Leading Market Players |
|---|
| DHL Group |
| Transnet Freight Rail |
| DP World |
| Bidvest Logistics |
| Bridgewater Logistics |
| Imperial Logistics |
| Kuehne+Nagel |
| Turners Shipping |
| DSV |
| Others |
Value Chain & Pricing Dynamics
Telematics-enabled predictive maintenance systems are compressing fleet operating costs while simultaneously concentrating procurement leverage among integrated logistics groups with capital to deploy these platforms. The National Transport Master Plan's corridor densification mandates are redistributing infrastructure cost burdens across modal choices, with rail-dependent bulk shippers absorbing tariff premiums while road operators face diesel volatility exposure.
Pricing Analysis
Short lead-time premiums command substantial markups in the automotive and pharmaceutical verticals, where Transnet Freight Rail's scheduling unreliability pushes time-sensitive cargo toward road-based alternatives at 15-25% cost elevation. Contract logistics pricing stratifies across premium dedicated-fleet, standard shared-capacity, and economy deferred-consolidation tiers. Cost compression in the road freight tier is intensifying because fuel price volatility erodes operator margins unpredictably. Small enterprises exhibit acute price sensitivity, negotiating spot rates through digital freight matching platforms, while mining houses prioritize service reliability over unit cost optimization.
Supply Chain Analysis
Direct-to-mine-site channels handle extractive industry demand through third-party logistics providers divesting from captive fleet ownership. Equipment and consumables sourcing draws from China, Germany, and the United States for specialized mining machinery, while fuel supply rests on South African refinery capacity and regional import dependence. Single-source vulnerability concentrates in Transnet's monopoly over the Cape and Richards Bay bulk rail corridors, where capital allocation decisions directly constrain throughput expansion. Distribution runs through the Gauteng-Johannesburg logistics cluster for final-mile fulfillment, with port-centric warehousing at Durban and Cape Town anchoring import-export flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Transnet's capital constraints on rail infrastructure expansion are sustaining pricing power for incumbent road freight operators serving time-definite cargo segments. The Richards Bay and Durban port capacity bottlenecks prop up contract logistics premiums as shippers absorb congestion-driven cost elevation.
For Market Incumbents: Acquire specialized cold-chain warehousing assets in the Western Cape citrus belt and Gauteng pharmaceutical corridors to defend against temperature-controlled logistics specialists encroaching on healthcare verticals. Deepen backward integration into fuel storage and fleet maintenance facilities to buffer margin compression from diesel volatility. Lock in multi-year mining outsourcing contracts before CEA licensing reforms expand competitor entry. For New Entrants and Emerging Players: SME spot-market buyers remain underserved by integrated logistics groups focused on corporate contract value, creating white-space opportunity for digital freight matching platforms with instant quoting and flexible capacity aggregation. The Northern Cape mining equipment logistics cluster offers penetrable geography where divesting extractive firms seek third-party alternatives to captive fleet maintenance. Position through pay-per-use telematics bundling that lowers upfront technology adoption barriers for fragmented haulage operators. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to global forwarding groups seeking African market anchoring, with DSV and Kuehne+Nagel archetypes representing likely acquirers of mid-scale contract logistics specialists. Long-term viability favors operators with multimodal capability spanning Transnet rail allocation access and road fleet flexibility. Monitor Transnet capital allocation announcements as the critical inflection signal for modal shift acceleration and corridor capacity expansion timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Multimodal Capability Integration | Combines Transnet rail access with road fleet flexibility to serve mining outsourcing demand. |
| Temperature-Controlled Warehouse Expansion | Captures pharmaceutical cold chain growth at OR Tambo and Dube TradePort cargo precincts. |
| Digital Freight Platform Development | Aggregates fragmented SME spot demand through API-connected carrier matching algorithms. |
| Last-Mile Micro-Fulfillment Network | Positions inventory within 15-kilometer radii of Johannesburg and Cape Town consumer density. |
| Cross-Border Customs Automation Partnership | Leverages SARS modernization at Beitbridge to compress clearance velocity for regional freight. |
Study Parameters
Trade flow databases, National Transport Master Plan documentation, and Transnet annual performance reports formed the secondary backbone, cross-referenced against SARS customs modernization filings and CEA regulatory updates. Primary interviews with fleet operations directors, mining supply chain managers, pharmaceutical logistics coordinators, and port terminal operators validated capacity utilization assumptions and outsourcing trend trajectories. Bottom-up carrier fleet counts and top-down GDP-correlated freight demand modeling enabled triangulation across independent estimation approaches.
Historical trendline analysis of modal share evolution and corridor throughput patterns anchored the projection framework across the analysis window. Segmentation dimensions modeled include transport mode, delivery speed tier, industry vertical, and end-user procurement sophistication, with CAGRs derived from elasticity-adjusted demand curves and infrastructure capacity constraints. Forecast inputs incorporated diesel price scenario sensitivity and Transnet capital expenditure pipeline disclosure.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Transnet rail modernization execution and port concession renewal timelines. Forecasts reflect documented assumptions regarding mining outsourcing velocity and e-commerce penetration trajectories. Periodic stress-testing of base assumptions is recommended against fuel price volatility shocks and regulatory enforcement shifts on CEA operator licensing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Australia Last Mile Delivery Market
Logistics and Shipping
Indonesia Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
US Fourth-Party Logistics (4PL) Market
Logistics and Shipping
Sri Lanka Freight and Logistics Market
Logistics and Shipping
Germany Automotive 3PL Market
Logistics and Shipping
Nigeria Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Bangladesh Contract Logistics Market
Logistics and Shipping
Hong Kong Container Transshipment Market
Logistics and Shipping
Airfreight Forwarding Market
Logistics and Shipping
Asia-Pacific Pharmaceutical Logistics Market
Logistics and Shipping
Hazardous Goods Logistics Market
Logistics and Shipping
US Retail Logistics Market
Logistics and Shipping
North America Last Mile Delivery Market
Logistics and Shipping
Russia Freight and Logistics Market
Logistics and Shipping
Egypt Freight and Logistics Market
Logistics and Shipping
Singapore Freight and Logistics Market