
 Nigeria Packaging Market | 2026-2036
Nigeria Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Nigeria Packaging Market Foresight
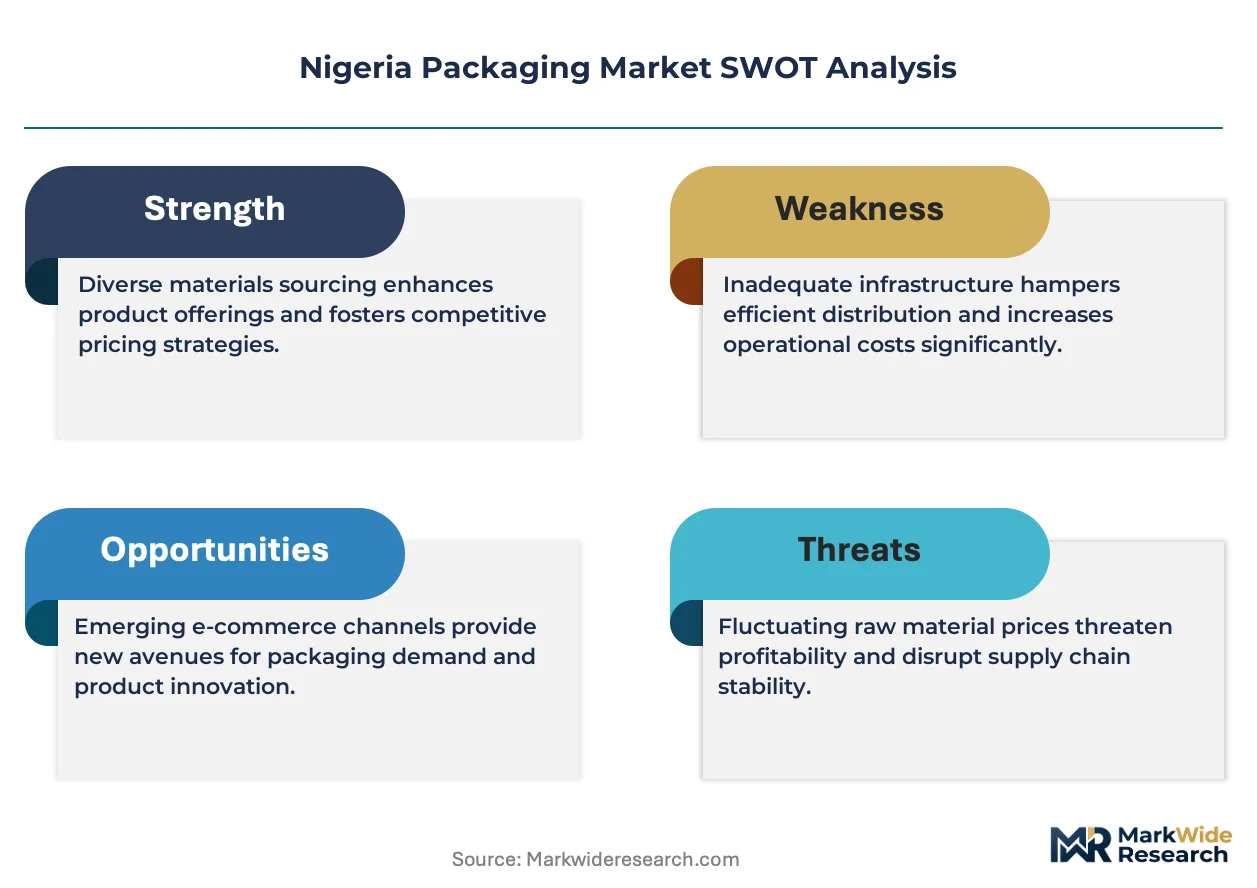
NAFDAC's revised packaging material safety guidelines is consolidating compliance costs for new entrants while favoring incumbents with in-house testing laboratories. Shongai Packaging leverages its integrated bottle-to-resin operations across Ogun State to sustain cost advantages over import-dependent rivals. Nigerian Bottling Company anchors demand through captive glass and PET sourcing for its beverage filling lines. Beta Glass dominates returnable bottle refurbishment, a segment where capital intensity blocks smaller competitors.
Nigeria packaging encompasses the design, fabrication, and finishing of containers—typically 0.5 to 25 liter capacity in rigid formats—using blow molding, thermoforming, or carton folding to protect goods through distribution and retail display. Plastic bottles and pouches lead volume given their dominance in bottled water, edible oils, and sachet cosmetics, though margin pools concentrate in pharmaceutical blister packs where NAFDAC certification creates scarcity rents. Glass bottles retain structural importance in premium beverages and pharmaceuticals, while paper-based boxes expand in e-commerce fulfillment despite pulp import dependency.
NAFDAC, the Standards Organisation of Nigeria (SON), and the National Environmental Standards and Regulations Enforcement Agency (NESREA) collectively govern material migration limits, dimensional tolerances, and post-consumer waste obligations, pushing converters toward documented supply chains and recyclate content. SON's mandatory product certification scheme blocks uncertified imports at Lagos and Apapa ports, reshaping procurement patterns for local assemblers. Stakeholders must monitor how extended producer responsibility rules under NESREA's plastic waste regulations reshape cost structures and create first-mover advantages for recyclers with formal collection partnerships.
Market Dynamics
NAFDAC's material safety mandates are compressing supplier qualification timelines while concentrating procurement power among converters with captive laboratory infrastructure. This regulatory pressure is redrawing competitive boundaries faster than capacity expansion can respond.
Growth Catalysts
- Urban consumption clusters:Lagos-Ibadan corridor demand for bottled water and edible oils pulls rigid plastic volume through dedicated blow molding lines. Population density above 5,000 per square kilometer sustains minimum efficient scale for regional converters.
- NAFDAC certification scarcity:Pharmaceutical blister pack approvals create protected margin pools for qualified domestic suppliers. Import substitution incentives channel government procurement toward certified local producers.
- South-West logistics concentration:Apapa and Tin Can Island port infrastructure anchors resin import flows, reducing inland freight costs for Ogun State converting clusters versus northern competitors.
Market Restraints
- Resin import dependency:Naira volatility against dollar-denominated polyethylene and polypropylene contracts transmits directly to converter margins. No domestic polymer cracking capacity exists to hedge currency exposure.
- Glass furnace concentration:Beta Glass and Nigerian Bottling Company control returnable bottle refurbishment through capital-intensive furnace assets. New entrants face 36-48 month payback periods on equivalent equipment.
- Pulp import bottleneck:E-commerce corrugated demand runs into containerboard supply constraints at Lagos ports. SON certification delays for imported linerboard extend lead times beyond customer tolerance thresholds.
Strategic Opportunities
- NESREA extended producer responsibility:Formal recyclate collection partnerships unlock preferential procurement status from multinational FMCG buyers. First-mover recyclers secure offtake agreements before mandate enforcement tightens.
- North-East penetration gap:Kano and Kaduna beverage bottling operates with higher packaging logistics costs than southern competitors. Regional converting capacity investment captures price premiums currently absorbed by transport.
- Pharmaceutical serialization:NAFDAC track-and-trace requirements for secondary packaging create demand for integrated carton-printing and coding equipment. Converters with serialization capability bundle compliance services.
Industry Challenges
- Polymer chemist scarcity:Migration testing and material qualification require specialized expertise concentrated in Lagos and Abuja. Northern converters face 6-9 month hiring cycles for laboratory staff.
- Multi-standard certification burden:SON product certification, NAFDAC material approval, and NESREA waste handling permits operate on non-aligned renewal calendars. Administrative overhead consumes senior management bandwidth disproportionately.
- Legacy equipment integration:Pre-2015 blow molding lines lack the precision tolerances required for lightweighting initiatives. Retrofit costs approach 40% of replacement value without matching output gains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nigeria Packaging Market |
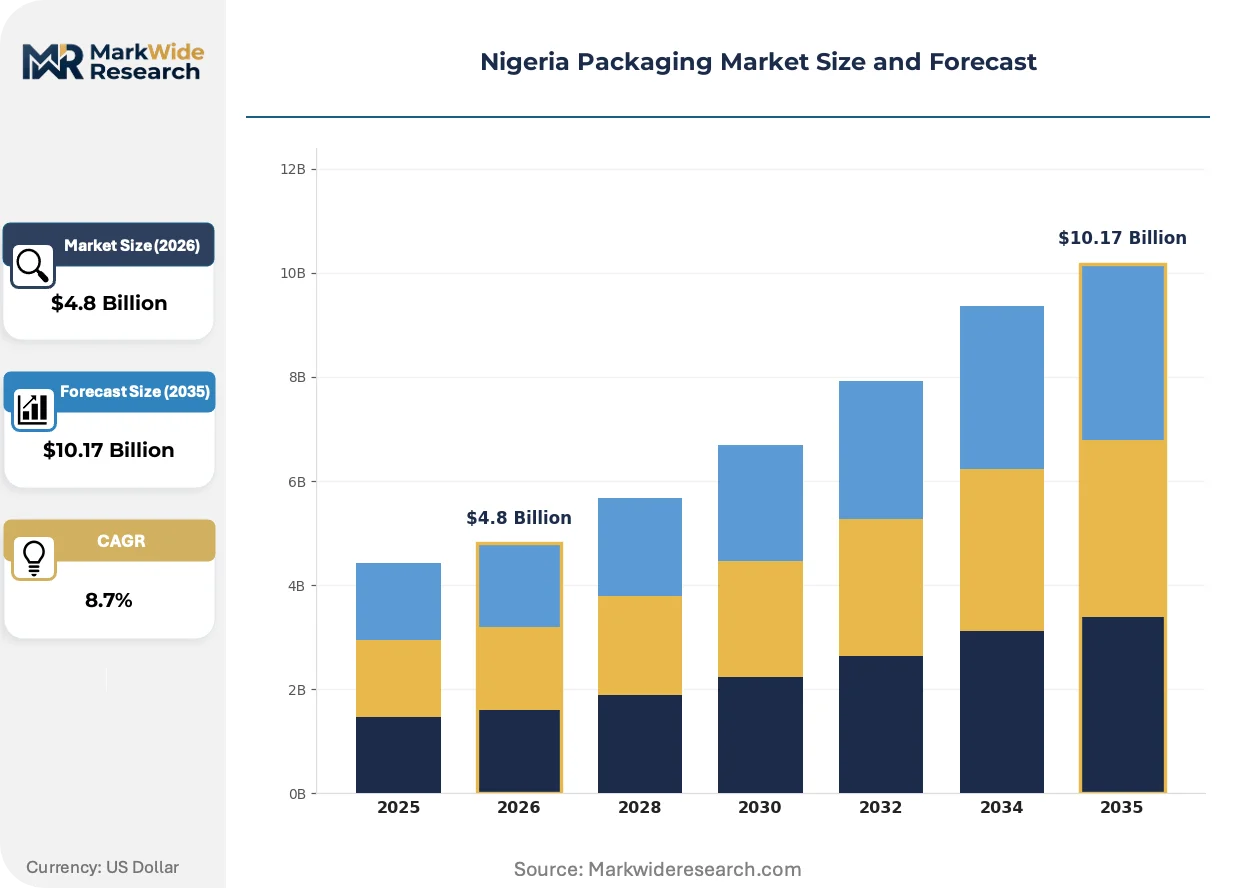
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Cans, Boxes, Pouches Material: Plastic, Glass, Paper, Metal End User: Food & Beverage, Pharmaceuticals, Cosmetics, Electronics Packaging Type: Flexible, Rigid, Stand-up, Blister |
| Companies Covered | Shongai Packaging, Nigerian Bottling Company, The Paper Packaging Company, Beta Glass, Dangote Group, PrimePak Industries Nigeria Ltd, Polysmart Packaging, Guinness Nigeria, Shongai Technologies Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nigeria Packaging Market Shifts & Advancements
Digital printing and material lightweighting are compressing traditional converting economics while regulatory serialization mandates reconfigure equipment investment priorities across the sector.
Bio-based polyethylene from cassava-derived ethanol is converging with conventional fossil resin in blow molding applications. Nigerian Bottling Company and regional water bottlers are piloting 30% bio-content bottles for premium positioning. This convergence is enabling price premiums in urban retail channels without requiring dedicated processing lines.
NAFDAC's 2024 labeling guideline revisions mandate QR-code integration for pharmaceutical secondary packaging. Converters must retrofit flexographic presses with inline digital coding stations or lose tender eligibility. Blister pack and folding carton segments are absorbing 15-20% equipment reinvestment cycles to maintain certification status.
Direct converter-to-retailer procurement contracts are displacing traditional distributor intermediaries in Lagos and Ibadan. Large format retailers and pharmacy chains now negotiate volume commitments directly with Shongai Packaging and Beta Glass for private-label lines. This channel compression is most visible in the South-West where retail consolidation has proceeded furthest.
Nigeria Packaging Market Segmentation
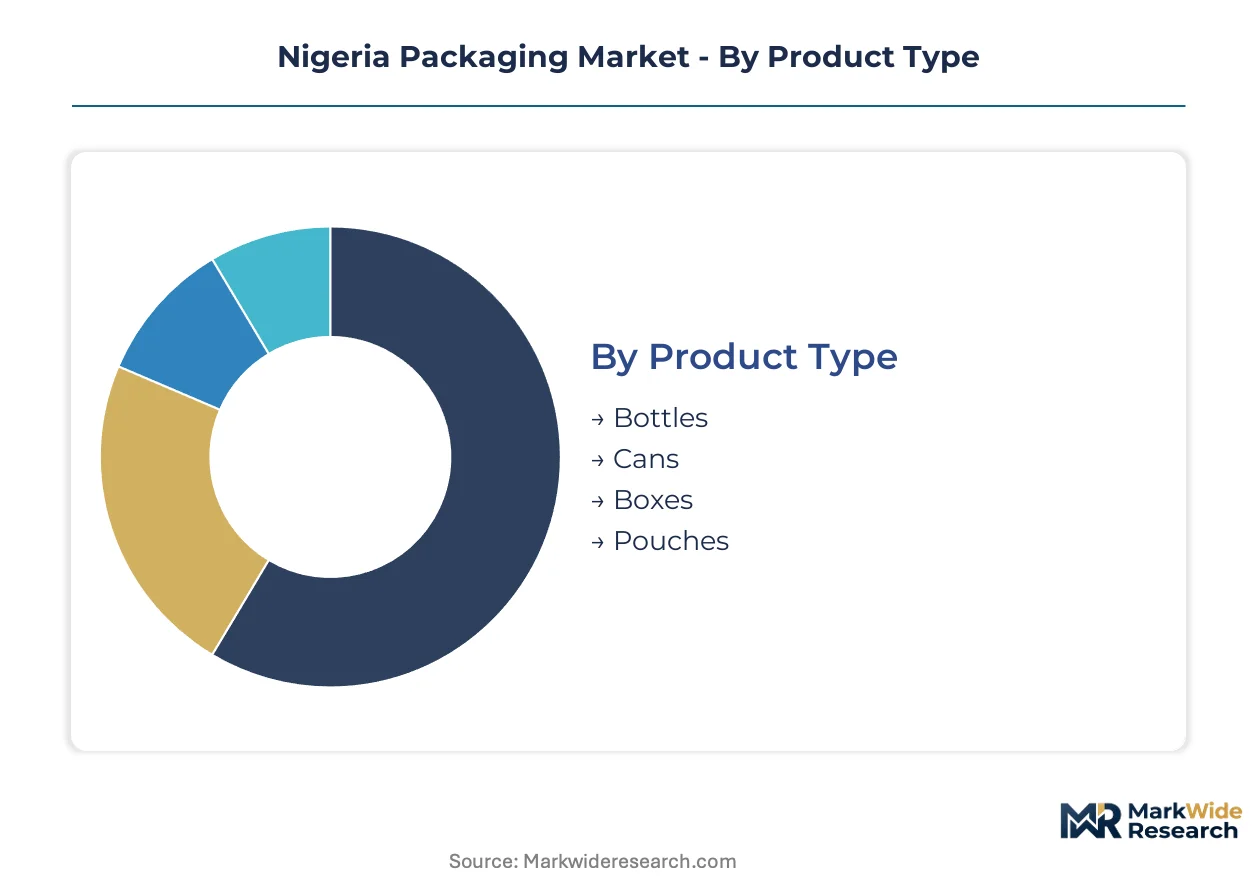
Packaging procurement in Nigeria fragments across four structural axes that determine converter capabilities and regulatory exposure. Each segmentation layer carries distinct margin profiles, certification burdens, and logistics requirements that reshape competitive positioning.
Product Type:
Container geometry and closure systems define manufacturing equipment requirements and NAFDAC qualification pathways.
- Bottles:Blow-molded PET and HDPE containers dominate bottled water and edible oil distribution. Lagos-Ibadan corridor demand sustains dedicated 24-cavity production lines at Shongai Packaging and Nigerian Bottling Company facilities.
- Cans:Aluminum beverage cans rely entirely on imported substrate given zero domestic smelting capacity. Apapa port clearance delays and naira-dollar volatility compress margins for energy drink and beer brand owners.
- Boxes:Corrugated fiberboard and folding carton formats expand with e-commerce fulfillment and pharmaceutical serialization mandates. Pulp import dependency at Lagos ports constrains supply security.
- Pouches:Flexible laminated structures serve sachet water, condiments, and cosmetics. Low capital entry thresholds fragment supply across Ogun State converting clusters.
Bottles lead on scale; pouches lead on momentum.
Material:
Substrate selection determines migration testing protocols, recyclate content obligations under NESREA, and currency exposure profiles.
- Plastic:Polyethylene and polypropylene resins account for the majority of rigid packaging volume. No domestic polymer production exists; converters hedge naira volatility through 90-day forward contracts with Saudi and Korean suppliers.
- Glass:Soda-lime silica containers retain structural importance in premium beverages and parenteral pharmaceuticals. Beta Glass and Nigerian Bottling Company control furnace capacity through capital-intensive refurbishment operations in Lagos and Benin City.
- Paper:Containerboard and folding carton substrates depend on imported kraft linerboard. SON certification delays at Apapa extend lead times beyond customer tolerance for corrugated shipper demand.
- Metal:Tinplate and aluminum substrates serve processed food cans and aerosol applications. Three-piece can manufacturing concentrates in a single Lagos facility with captive coating lines.
Plastic dominates volume throughput; glass commands premium positioning.
End User:
Downstream industry requirements dictate certification depth, serialization infrastructure, and batch traceability standards.
- Food & Beverage:Bottled water, edible oils, and carbonated soft drinks pull the majority of rigid plastic and glass volume. Urban consumption clusters above 5,000 per square kilometer sustain minimum efficient scale for regional blow molding.
- Pharmaceuticals:Blister packs, vials, and secondary cartons face NAFDAC material approval and track-and-trace serialization mandates. Certification scarcity creates protected margin pools for qualified domestic suppliers.
- Cosmetics:Sachet and jar formats serve mass-market personal care. Flexible pouch converters compete on speed-to-market for seasonal product launches.
- Electronics:Corrugated shipper and anti-static bag demand tracks consumer durable import flows through Lagos ports. Volume remains concentrated in mobile phone and appliance distribution.
Food & Beverage anchors procurement scale; Pharmaceuticals drives specification intensity.
Packaging Type:
Structural mechanics determine barrier properties, shelf presence, and equipment reinvestment cycles.
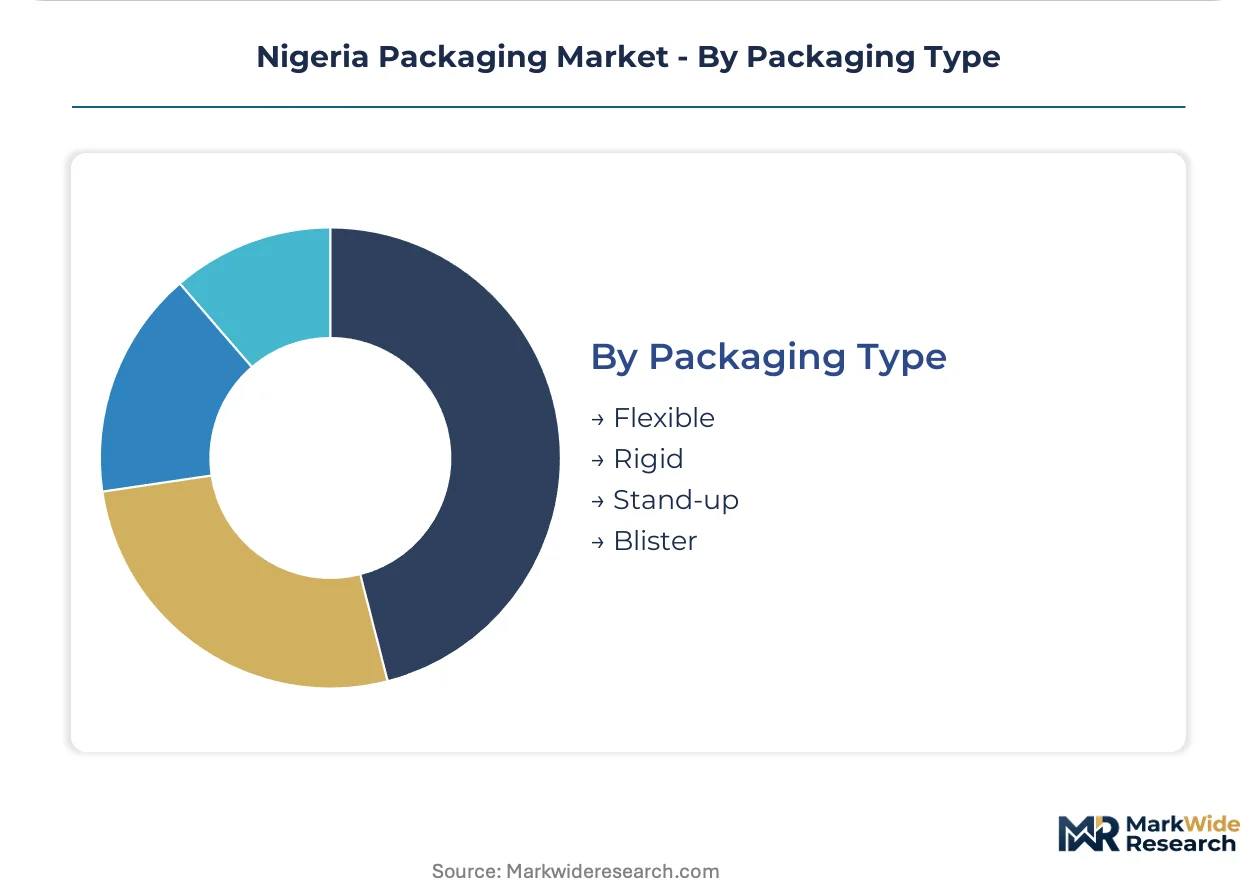
- Flexible:Laminated films and pouches enable lightweight distribution and retail-ready display. Horizontal form-fill-seal lines dominate Ogun State converting parks.
- Rigid:Blow-molded and thermoformed containers protect product integrity through ambient supply chains. Nigerian Bottling Company and Shongai Packaging anchor capacity.
- Stand-up:Doyen-style pouches with spout fitments gain traction in condiments and liquid detergents. Premium positioning justifies higher per-unit converter margins.
- Blister:Thermoformed cavities with lidding foil serve pharmaceutical unit-dose compliance. NAFDAC material migration limits require specialized PVC-PVDC expertise concentrated in Lagos.
Flexible formats dominate volume throughput; blister packs concentrate value capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer chemists and laboratory technicians concentrate disproportionately in Lagos and Abuja, creating a talent moat that southern converters exploit over northern competitors. This workforce distribution shapes where NAFDAC certification capacity can expand.
Lagos State
Bottled water and edible oil demand from 21 million residents pulls rigid plastic volume through dedicated blow molding corridors. NAFDAC maintains its headquarters and primary testing laboratories here, compressing approval timelines for local converters. Apapa and Tin Can Island ports anchor resin import flows, reducing inland freight costs for Ogun State converting clusters.
Ogun State
Shongai Packaging's integrated bottle-to-resin operations exploit proximity to Lagos demand while escaping metropolitan land costs. The state's industrial free zones offer tax holidays for packaging equipment imports. Agbara and Sagamu corridors concentrate converting parks where captive laboratory infrastructure satisfies NAFDAC material safety mandates.
Kano State
Beverage bottling and edible oil packaging operate with 15-20% higher logistics costs than southern competitors due to resin haulage distances. The state's pharmaceutical manufacturers import pre-qualified blister packs from Lagos rather than maintain northern certification capacity. Dangote's cement packaging lines represent the primary rigid format demand anchor locally.
Rivers State
Port Harcourt's petrochemical adjacency offers theoretical feedstock advantages that remain unrealized without domestic polymer cracking. Food and beverage distribution to the Niger Delta relies on flexible pouch formats that tolerate poor road infrastructure. Guinness Nigeria's brewery anchors glass bottle demand for returnable premium beer packaging.
Federal Capital Territory
Abuja's administrative concentration hosts NAFDAC's secondary laboratory complex and SON certification offices. Government procurement rules channel pharmaceutical packaging tenders toward certified domestic suppliers. The city's sparse manufacturing base forces converters to maintain Lagos supply relationships despite 800-kilometer distances.
Nigeria Packaging Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across material-specific segments. The market exhibits tiered concentration: glass furnace assets and integrated resin operations consolidate among capital-intensive players, while flexible pouch converting fragments across low-entry-threshold Ogun State parks. Three archetypes dominate—captive beverage bottlers with in-house packaging lines, integrated resin-to-bottle converters, and independent corrugated specialists serving e-commerce fulfillment. Capacity expansion and NAFDAC certification acquisition constitute the primary competitive moves.
Among integrated converters, Shongai Packaging and Shongai Technologies Ltd exemplify backward integration archetypes that control resin sourcing through captive operations. Beta Glass occupies a position within the capital-intensive furnace tier where refurbishment economics block smaller competitors. Nigerian Bottling Company represents the captive bottler model that internalizes glass and PET demand across its beverage filling network.
| Leading Market Players |
|---|
| Shongai Packaging |
| Nigerian Bottling Company |
| The Paper Packaging Company |
| Beta Glass |
| Dangote Group |
| PrimePak Industries Nigeria Ltd |
| Polysmart Packaging |
| Guinness Nigeria |
| Shongai Technologies Ltd |
| Others |
Supply & Pricing Matrix
Backward integration into captive resin operations anchors pricing power for southern Nigerian converters while locking northern competitors into volatile import-denominated cost structures. NAFDAC certification bundling with material testing services creates unbundled procurement alternatives that fragment price discovery across laboratory-capable and laboratory-dependent supplier tiers.
Pricing Analysis
Bundled certification-and-material contracts dominate pharmaceutical blister pack procurement, while unbundled resin spot purchases prevail in flexible pouch converting. Three-tier pricing structure across premium certified, standard compliant, and economy non-certified levels reflects NAFDAC approval depth and laboratory infrastructure investment. Pricing pressure stems from naira volatility transmitting directly to dollar-denominated polyethylene contracts. Food and beverage bottlers show least price sensitivity given captive demand scale; sachet water converters absorb maximum margin compression.
Supply Chain Analysis
Polymer chemist and laboratory technician scarcity in Kano and Kaduna versus Lagos-Ogun concentration shapes where NAFDAC certification capacity can expand. Resin supply draws from Saudi Arabian and Korean petrochemical exporters through Apapa port clearance. Single-source vulnerability concentrates in containerboard linerboard imports facing SON certification delays. Distribution runs through converter-to-retailer direct contracts displacing traditional distributor intermediaries in the South-West corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Nigeria's packaging sector functions as a regulatory compounder where NAFDAC's 2024 QR-code serialization mandate for pharmaceutical secondary packaging forces equipment reinvestment cycles that consolidate procurement power among certified incumbents.
For Market Incumbents: Deploy captive laboratory infrastructure as a defensive moat against resin-price volatility and emerging flexible pouch competitors. Expand backward integration into recyclate collection partnerships before NESREA mandate enforcement tightens. Consolidate regional converting capacity in Ogun State industrial free zones to capture tax-advantaged equipment imports. For New Entrants and Emerging Players: Direct-to-retailer digital procurement channels in Lagos and Ibadan offer white-space penetration beneath incumbent distributor relationships. Target Kano and Kaduna beverage bottling with regional blow molding capacity that captures 15-20% logistics premiums currently absorbed by southern haulage. Lead with serialization-capable carton-printing equipment to bundle NAFDAC compliance services. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap flexible pouch specialists because Ogun State converting park fragmentation creates multiple sub-scale targets with shared NAFDAC certification pathways. Five-to-ten year viability hinges on recyclate content mandates hardening under NESREA enforcement. Monitor formal waste collection partnership announcements as inflection signals for first-mover recyclers securing multinational FMCG offtake agreements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Operations | Shongai Packaging's captive supply hedges naira volatility against Korean and Saudi contract exposure. |
| NAFDAC Certification Acquisition | Laboratory infrastructure investment blocks uncertified imports at Lagos and Apapa port clearance points. |
| Regional Capacity Expansion | Kano and Kaduna converting investment captures logistics premiums from northern beverage bottling demand. |
| Recyclate Collection Partnerships | NESREA extended producer responsibility rules create preferential procurement status with multinational FMCG buyers. |
| Serialization Equipment Retrofit | Inline digital coding stations maintain pharmaceutical tender eligibility under NAFDAC track-and-trace mandates. |
Research Methodology
Bottom-up food and beverage procurement modeling reconciled against top-down resin import tracking forms the analytical core of this study. Primary interviews with NAFDAC compliance officers, converter plant managers, pharmaceutical packaging procurement leads, and logistics coordinators at Apapa port operators combined with secondary validation from SON certification databases, NESREA waste handling permit registries, and customs trade records. Triangulation across stakeholder inputs and documentary sources anchored volume estimates.
Historical trendline analysis of blow molding capacity utilization and pharmaceutical blister pack approval timelines informed projection mechanics. Segmentation dimensions modeled include material substrate, end-use industry vertical, packaging format rigidity, and regional regulatory cluster density. CAGRs derived from weighted average of demand elasticity coefficients and supply-side capacity expansion schedules. Forecast inputs incorporated urban consumption cluster density thresholds and NAFDAC laboratory approval queue lengths.
The model assumes a particular technology adoption path; alternative pathways for cassava-derived bio-polyethylene blending would alter the outlook if feedstock scaling exceeds pilot volumes. Forecasts reflect documented assumptions about naira stability and resin import clearance efficiency. Practitioners should monitor NESREA enforcement announcements and SON certification processing times at Apapa for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Polycoated Cup Stock Market
Packaging Materials
PET Packaging Market
Packaging Materials
VCI Films Market
Packaging Materials
Germany Packaging Market
Packaging Materials
Paint Packaging Market
Packaging Materials
Printable Self-Adhesive Vinyl Films Market
Packaging Materials
Bulb Packaging Market
Packaging Materials
Construction Films Market
Packaging Materials
VCI Packaging Market
Packaging Materials
Gift Wrapping Product Market
Packaging Materials
Hygiene Packaging Market
Packaging Materials
Water Soluble Pods Packaging Market
Packaging Materials
Anti-Scratch Film Market
Packaging Materials
Asia-Pacific Airless Packaging Market
Packaging Materials
PVC Packing Straps Market
Packaging Materials
Fanfold Market